
 Pet Food Microalgae Market | 2026-2036
Pet Food Microalgae Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Microalgae Market Analytics
Asset-light contract fermentation is narrowing the capital barrier for new entrants in microalgae-derived pet nutrition. DSM Nutritional Products leverages its long-standing biotechnology infrastructure to sustain high-purity omega-3 output for companion animal formulations. Cyanotech anchors its position through controlled cultivation of Haematococcus pluvialis at its Kona facility, competing on astaxanthin concentration for premium dog and cat diets. Roquette differentiates through pea-microalgae protein blends, extending its plant-extraction expertise into novel pet food ingredient systems.
Pet food microalgae denotes phototrophic or heterotrophic cultivation of single-celled organisms such as Schizychytrium, Chlorella, or Spirulina, typically harvested at cell densities exceeding 5 grams per liter and processed into lipid-rich biomass or protein concentrates for companion animal diets. The primary commercial purpose centers on delivering docosahexaenoic acid (DHA) and eicosapentaenoic acid (EPA) without marine fishery dependence, alongside complete protein profiles containing all essential amino acids. Omega-3 fatty acids dominate current revenue pools due to established veterinary validation for skin, coat, and cognitive health in aging dogs. Powder formulations lead volume throughput owing to stability during extrusion and dry kibble coating, while paste and liquid forms are gaining fastest in refrigerated fresh pet food segments where moisture content and palatability drive formulation choices.
The European Food Safety Authority (EFSA) evaluates novel food applications for microalgae species, while the FDA Center for Veterinary Medicine governs ingredient safety and labeling claims for algae-derived additives in US pet food products. REACH compliance and EU Green Deal sustainability disclosures are reshaping how suppliers document carbon intensity and cultivation water use across the value chain. Pet food manufacturers and ingredient suppliers must monitor evolving novel food authorizations and carbon border adjustment mechanisms to secure uninterrupted market access and premium positioning.
Market Dynamics
EU Green Deal sustainability mandates are forcing pet food manufacturers to document carbon intensity across algae cultivation supply chains, reshaping how omega-3 sourcing contracts are structured and audited.
Growth Catalysts
- EU Green Deal disclosure requirements:Mandatory carbon accounting for imported feed ingredients is accelerating algae-derived omega-3 substitution for fish oil across German and French pet food formulations.
- Heterotrophic fermentation technology:Controlled tank cultivation of Schizochytrium species delivers consistent DHA titers independent of seasonal sunlight variability, securing year-round supply contracts.
- German pet owner willingness-to-pay:Premium functional nutrition acceptance in Europe's largest companion animal market is concentrating demand for astaxanthin-enriched senior dog diets.
Market Restraints
- Capital intensity of photobioreactor infrastructure:Stainless steel closed-system cultivation requires substantial upfront investment, limiting viable production to well-capitalized fermentation specialists.
- EFSA novel food authorization timelines:Multi-year safety evaluation protocols for emerging microalgae species create regulatory lag between strain development and commercial deployment.
- Fish oil price volatility:Peruvian anchovy catch fluctuations continue to distort omega-3 feedstock economics, compressing algae-derived alternatives' cost-competitive window.
Strategic Opportunities
- Fresh refrigerated pet food channels:Liquid and paste algae formulations are penetrating cold-chain pet nutrition segments where moisture content drives palatability premiums.
- Carbon border adjustment mechanisms:Upcoming EU import levies on high-carbon feedstuffs will structurally advantage domestically cultivated microalgae against Southeast Asian fish meal.
- Protein concentrate diversification:Chlorella and Spirulina biomass integration into hypoallergenic dog diets addresses rising veterinary diagnoses of poultry and beef sensitivities.
Industry Challenges
- Phycologist talent scarcity:Specialized algae strain optimization expertise concentrates in academic and national laboratory settings, constraining commercial R&D scaling.
- Downstream processing standardization:Cell wall disruption and lipid extraction protocols vary significantly across equipment suppliers, complicating multi-source procurement strategies.
- REACH compliance documentation:Complex substance registration requirements for novel algae-derived compounds extend time-to-market for innovative ingredient launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Microalgae Market |
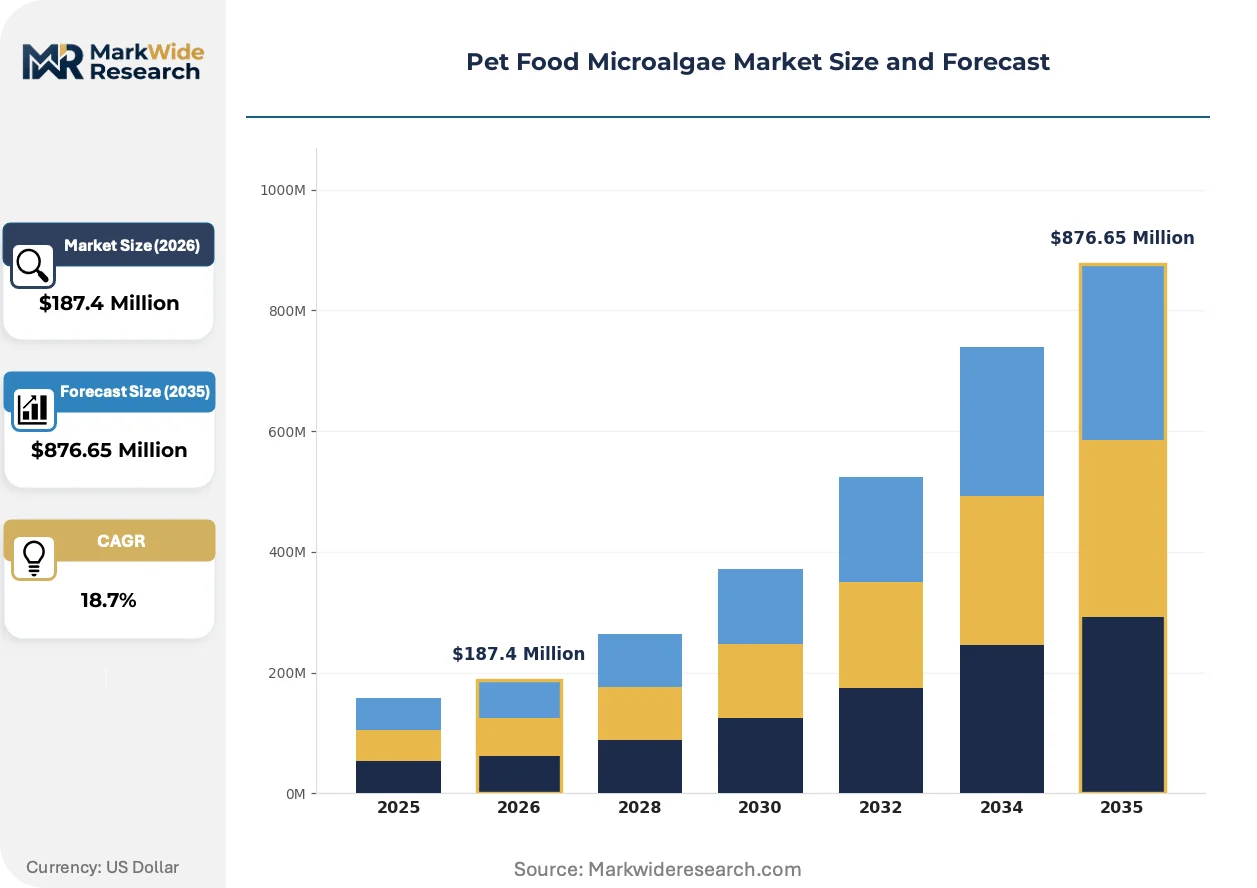
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Omega-3 Fatty Acids, Antioxidants, Protein Sources End User: Dogs, Cats, Small Mammals, Fish Form: Powder, Paste, Liquid, Granules Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Veterinarian Clinics |
| Companies Covered | Alltech, Heliae, Cyanotech, Pond Technologies, Roquette, DIC Corporation, DSM Nutritional Products, Qualitas Health, Earthrise Nutritionals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Microalgae Market Evolving Landscape
Biotechnology convergence with precision fermentation is collapsing traditional cultivation economics while regulatory carbon accounting is rewriting supplier qualification criteria across the value chain.
Single-cell protein refineries using precision fermentation of methanol-fed methylotrophs are rendering obsolete open-pond algae cultivation for high-volume commodity omega-3 production. Contract manufacturers in the Netherlands and Singapore are commissioning 100,000-liter stainless steel bioreactors dedicated to pet food DHA output. This capital deployment is compressing unit economics toward fish oil parity within five years.
REACH substance registration and EU Green Deal sustainability disclosure mandates are compelling algae suppliers to commission third-party lifecycle assessments documenting cultivation water use and energy intensity. Pet food manufacturers in Germany and France now require batch-level carbon footprints as standard procurement terms. Suppliers without verified environmental product declarations are losing qualified vendor status at major formulation houses.
Veterinary clinics are emerging as a direct distribution channel for algae-supplemented therapeutic diets, bypassing traditional retail and e-commerce intermediaries. Specialty practitioners in urban centers prescribe DHA-enriched formulations for cognitive decline in aging dogs, capturing margin that previously accrued to mass-market brands. This channel shift is most pronounced in German-speaking markets where pet insurance reimbursement covers prescription nutrition.
Pet Food Microalgae Market Segmentation
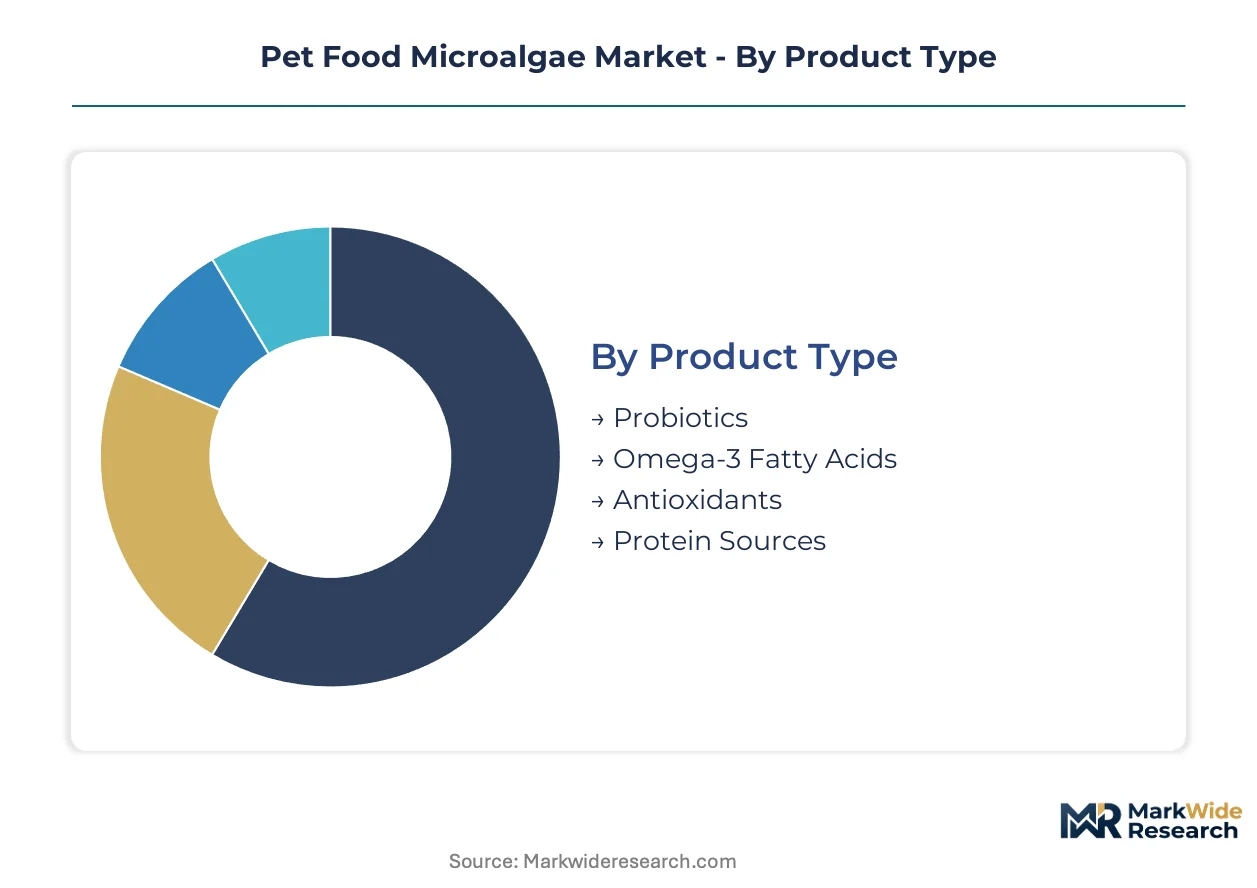
Microalgae ingredient suppliers configure production lines around distinct nutritional outputs and animal physiological requirements. Segmentation reveals where formulation R&D concentrates and which delivery formats command premium positioning.
Product Type:
Use-case spectrum spans therapeutic intervention to complete diet replacement, with each category demanding different cultivation and extraction infrastructure.
- Omega-3 Fatty Acids:DHA and EPA concentrates from Schizochytrium fermentation dominate current revenue pools. German and French premium kibble manufacturers specify minimum 35% DHA content for senior cognitive health claims.
- Protein Sources:Chlorella and Spirulina biomass delivers complete amino acid profiles for hypoallergenic formulations. Rising veterinary diagnoses of poultry sensitivities in urban companion animals are accelerating incorporation into limited-ingredient diets.
- Antioxidants:Astaxanthin from Haematococcus pluvialis targets oxidative stress in aging dogs. Controlled cultivation at high-light Hawaiian facilities ensures concentration consistency.
- Probiotics:Live microalgae cultures support gastrointestinal microbiome balance. Regulatory complexity around viable cell counts limits deployment to refrigerated fresh food channels.
The dominant share belongs to Omega-3 Fatty Acids, while Protein Sources is closing the gap fastest.
End User:
Volume concentration maps directly onto pet population demographics and owner willingness-to-pay for functional nutrition.
- Dogs:Cognitive decline formulations for senior animals represent the highest-value application. Veterinary prescription channels in Germany capture margin through DHA-enriched therapeutic diets.
- Cats:Obligate carnivore physiology demands higher protein concentration in algae biomass. Palatability challenges with marine-derived flavors constrain powder formulation acceptance.
- Small Mammals:Rabbit and guinea pig segments favor protein concentrates over lipid extracts. Niche volume limits dedicated production line investment.
- Fish:Ornamental aquarium and aquaculture feed applications utilize Spirulina for color enhancement. Price sensitivity relative to companion animals compresses margin.
Dogs command the largest addressable base, though Cats exhibit the steepest expansion trajectory as palatability engineering improves.
Form:
Processing economics and stability requirements during distribution create sharp differentiation across delivery systems.
- Powder:Spray-dried biomass integrates seamlessly into extrusion and dry kibble coating. Thermal stability during high-temperature processing secures dominant volume throughput.
- Liquid:Oil suspensions of DHA concentrates penetrate refrigerated fresh food segments. Cold-chain infrastructure requirements limit geographic reach to developed markets.
- Paste:Semi-moist formats balance palatability with shelf stability. Wet food manufacturers specify paste for uniform mixing without dusting losses.
- Granules:Agglomerated particles reduce segregation in multi-component premixes. Specialty store treat applications favor granule aesthetics.
Powder maintains volume leadership, while Liquid formats are gaining share fastest in premium refrigerated channels.
Distribution Channel:
Channel selection determines margin capture and regulatory burden for health-related claims.
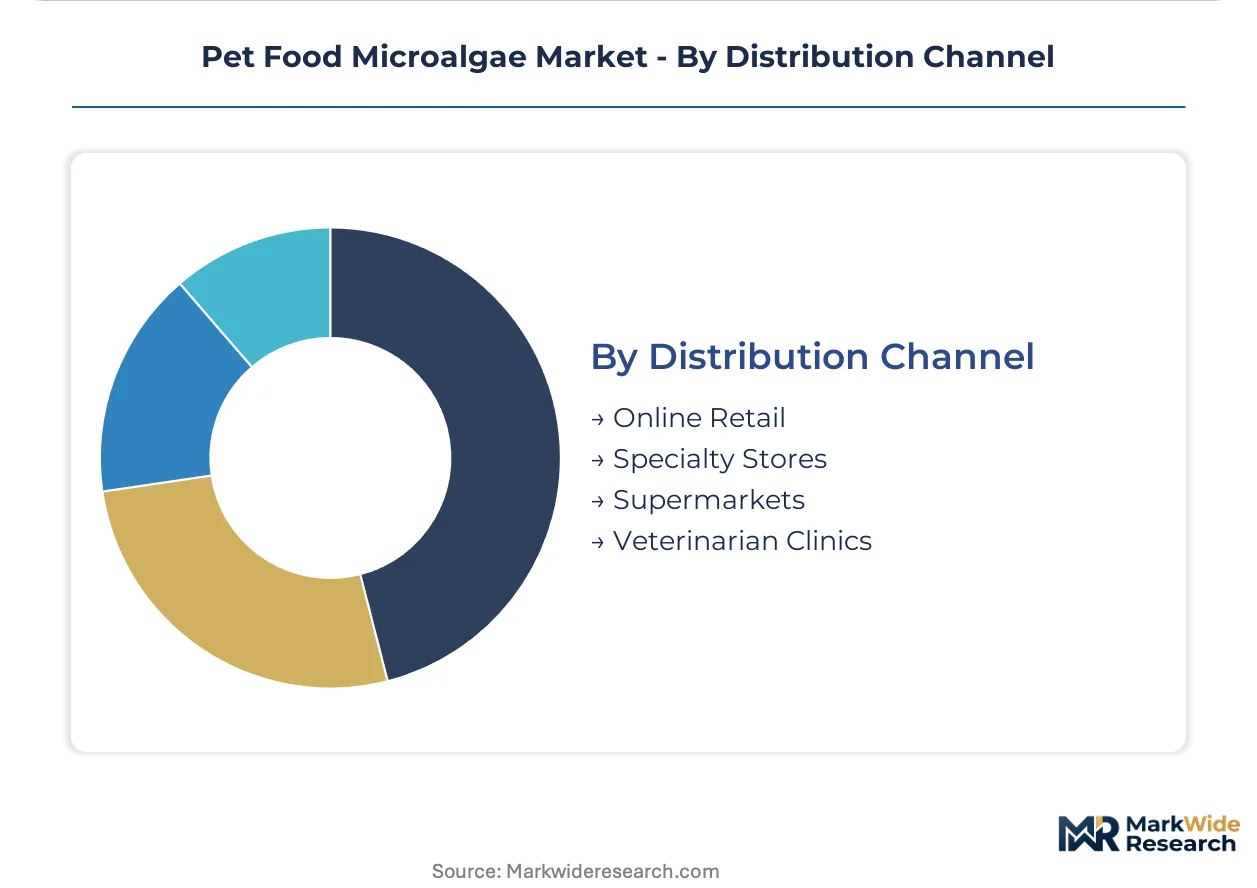
- Veterinarian Clinics:Prescription nutrition bypasses retail intermediaries. German pet insurance reimbursement structures enable direct margin capture for therapeutic formulations.
- Online Retail:Subscription models for premium functional nutrition concentrate in urban markets. Direct-to-consumer channels support batch-level traceability storytelling.
- Specialty Stores:Independent pet retailers emphasize sustainability credentials and novel ingredient education. Staff training requirements limit chain scalability.
- Supermarkets:Mass-market penetration demands cost parity with fish oil alternatives. Private label pressure compresses supplier margins.
Veterinarian Clinics extract the highest per-unit value, while Online Retail is climbing the fastest as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pet owners command price premiums exceeding French and Italian markets by double-digit margins, while US coastal metros concentrate formulation R&D investment against Midwestern production cost advantages.
Germany
Veterinary prescription channels and pet insurance reimbursement structures drive functional nutrition uptake. The EU Green Deal mandates carbon intensity disclosures for imported feed ingredients. Bavaria's biotechnology corridor hosts precision fermentation facilities supplying DHA concentrates to premium kibble manufacturers.
United States
Refrigerated fresh pet food segments in coastal metros absorb liquid algae formulations at volume. FDA Center for Veterinary Medicine governs ingredient safety claims for algae-derived additives. California's controlled-environment agriculture cluster integrates photobioreactor infrastructure with existing vertical farming operations.
Netherlands
Contract fermentation specialists serve as European toll manufacturers for global pet food brands. REACH compliance documentation requirements extend time-to-market for novel compounds. The Randstad region concentrates stainless steel bioreactor capacity dedicated to heterotrophic Schizochytrium cultivation.
France
Mass-market private label penetration demands cost parity with fish oil alternatives. EFSA novel food authorization timelines create regulatory lag for emerging microalgae species. The Brittany agricultural belt hosts pilot facilities testing algae protein integration into conventional feed milling operations.
Japan
Aging pet demographics and veterinary cognitive health diagnoses accelerate DHA-enriched senior dog diets. METI industrial biotechnology programs subsidize domestic algae cultivation scale-up. The Chubu region around Nagoya anchors pharmaceutical-grade fermentation expertise transferable to companion animal nutrition.
Pet Food Microalgae Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biomass concentrates and extracted lipids to formulation houses. The vendor base stratifies across multinational nutrition conglomerates with captive fermentation capacity, dedicated algae cultivation specialists, and toll manufacturers offering asset-light contract production. Two archetypes dominate: vertically integrated life sciences platforms controlling strain-to-shelf supply chains, and focused biomass producers competing on cultivation efficiency and extraction yields. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with fermentation specialists securing long-term offtake agreements and ingredient houses acquiring toll manufacturing access.
Within the integrated nutrition platform tier, DSM Nutritional Products and Roquette exemplify divergent sourcing strategies—one leveraging long-standing biotechnology infrastructure, the other extending plant-extraction expertise into novel ingredient systems. Cyanotech occupies a distinct position among dedicated cultivation specialists, with its Kona facility representing controlled-environment production archetypes competing on astaxanthin concentration consistency.
| Leading Market Players |
|---|
| Alltech |
| Heliae |
| Cyanotech |
| Pond Technologies |
| Roquette |
| DIC Corporation |
| DSM Nutritional Products |
| Qualitas Health |
| Earthrise Nutritionals |
| Others |
Value Network & Pricing Analysis
Undercapacity in European precision fermentation facilities is compressing supplier margins while amplifying pricing power for toll manufacturers with available stainless steel bioreactor capacity. This utilization squeeze forces ingredient buyers into longer-term offtake commitments to secure DHA concentrate supply, reshaping contract structures across German and Dutch formulation houses.
Pricing Analysis
The customization-premium spread between standard Schizochytrium biomass and configured-to-order astaxanthin concentrates exceeds three-to-one across German veterinary prescription channels. Contract-based long-term offtake agreements dominate volume transactions, with price differentiation hinging on EFSA novel food certification status and batch-level carbon footprint documentation. Cost compression in mass-market powder formulations is intensifying because French private label manufacturers demand fish oil parity. Supermarket buyers exhibit acute price sensitivity, while German specialty retailers absorb premiums for verified sustainability credentials.
Supply Chain Analysis
Extended payment terms from Dutch contract fermentation specialists to German pet food manufacturers are stabilizing working capital across the value chain. Supply concentrates in the Netherlands, Germany, and Hawaii, with heterotrophic cultivation infrastructure drawing from methanol feedstock, stainless steel bioreactor components, and phycologist technical labor pools. Single-source vulnerability around Haematococcus pluvialis astaxanthin from Cyanotech's Kona facility creates concentration risk. Distribution runs through veterinarian clinics and specialty stores for premium tiers, with online retail subscription models gaining fastest in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through a capacity-buildout phase as precision fermentation economics approach fish oil parity, with the recovery trajectory tethered to EU Green Deal carbon accounting enforcement tightening import substitution incentives.
For Market Incumbents: Pre-empt margin erosion in commodity omega-3 segments by securing captive supply of heterotrophic fermentation capacity in the Netherlands or Bavaria. DSM Nutritional Products and Roquette must defend against asset-light contract manufacturers by deepening EFSA certification moats and locking multi-year offtake agreements with German veterinary clinic networks before carbon border adjustments structurally advantage domestic cultivation. For New Entrants and Emerging Players: Mid-market refrigerated fresh pet food channels in France and the United States represent the most penetrable entry point, as palatability engineering for liquid DHA formulations remains undersupplied relative to powder saturation. Target veterinary prescription networks in German-speaking markets through direct sales forces capable of batch-level traceability documentation. A sustainability storytelling go-to-market angle, anchored to verified lifecycle assessments, unlocks qualified vendor status at formulation houses faster than price competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among toll fermentation specialists with dedicated pet food bioreactor lines and long-term offtake contracts. Over a five-to-ten-year viability window, acquisition targets should demonstrate backward integration into methanol supply or strain optimization IP rather than pure cultivation assets. The signal to watch as an inflection indicator is EFSA novel food authorization acceleration for emerging microalgae species, which would expand addressable formulation portfolios beyond Schizochytrium dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | 100,000-liter stainless steel bioreactor deployment in the Netherlands compresses unit economics toward fish oil parity. |
| Backward Integration | Captive methanol supply agreements insulate heterotrophic fermentation from feedstock volatility. |
| Green Certification Program | Third-party lifecycle assessments satisfying EU Green Deal disclosure mandates secure qualified vendor status. |
| Long-term Supply Agreement | Multi-year offtake contracts with German veterinary clinic networks lock in premium channel margin. |
| Regulatory Approval Pathway | EFSA novel food authorization for emerging microalgae species expands formulation portfolios beyond DHA concentrates. |
Research Methodology
Initial hypotheses were tested against primary input from precision fermentation plant managers, pet food formulation R&D directors, veterinary clinic procurement leads, and EU regulatory affairs specialists, then refined against secondary validation from EFSA novel food application databases, EU Green Deal implementation guidance, REACH substance registration filings, and customs trade data for algae-derived feed ingredients. Bottom-up capacity modeling across Dutch and German bioreactor installations was triangulated with top-down demand estimation from pet population demographics and functional nutrition penetration rates.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation across product type, end user species, formulation format, and distribution channel, with CAGRs derived from installed capacity ramp schedules and price elasticity estimates for premium versus mass-market tiers. Industry-specific forecast inputs included heterotrophic fermentation yield curves, EFSA authorization timeline distributions, and carbon border adjustment mechanism implementation phasing.
Practitioners should monitor EFSA novel food authorization velocity, EU carbon border adjustment enforcement timing, and Peruvian anchovy catch volatility for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Food Cultures Market