
 Octopus Market | 2026-2036
Octopus Market Size, Share, and Industry Trends Forecast 2026-2036
Octopus Market Analysis
ISO 22000 certification is reorganizing supplier eligibility across the octopus supply chain, forcing smaller harvesters toward third-party audit investments. Pescanova Hellas EPE leverages integrated Mediterranean processing infrastructure to sustain volume consistency. Nueva Pescanova S.L. anchors its competitive stance through Galician fleet proximity. Thai Union Group differentiates via cold-chain logistics spanning Southeast Asian source waters.
Octopus denotes soft-bodied cephalopods of the order Octopoda, harvested wild or aquacultured, typically processed at 1-8 kg dressed weight for foodservice and retail trade. Fresh product commands premium positioning in Japanese sushi corridors and Iberian tapas channels. Frozen octopus occupies the largest volume share as blast-freezing at sea extends shelf life for intercontinental shipment. Dried segments serve niche East Asian broth markets where umami concentration justifies price elevation above standard frozen blocks.
FDA HACCP mandates govern United States import safety verification, while EFSA traceability protocols and EU IUU Regulation compel catch documentation for all Atlantic and Mediterranean landings. These frameworks elevate compliance costs for non-certified operators and redirect procurement toward documented supply sources. Stakeholders must weigh aquaculture scale-up timelines against wild-stock quota tightening as the decisive capacity variable.
Market Dynamics
EU IUU Regulation enforcement is compressing wild-catch documentation timelines, forcing processors to consolidate procurement around certified Mediterranean and Atlantic fleets or risk port rejection.
Growth Catalysts
- East Asian restaurant channel expansion:Sushi and izakaya operators in Japan and South Korea are absorbing larger frozen-block volumes as octopus displaces cuttlefish in premium raw preparations.
- EU IUU Regulation traceability mandates:Catch documentation requirements are redirecting procurement toward Spanish and Portuguese flagged vessels with established digital logbook systems.
- Blast-freezing at sea:Onboard processing technology is extending shelf life for intercontinental shipment, opening new supply corridors from Mauritanian and Moroccan waters.
Market Restraints
- Wild-stock quota tightening:Spanish and Portuguese TAC reductions are constraining raw material availability for Galician processing clusters.
- Diesel and ice input volatility:Fuel and refrigeration cost spikes are eroding margins for small-scale artisanal harvesters operating day-boat fleets.
- Octopus aquaculture timeline delays:Commercial-scale hatchery protocols remain unproven, blocking planned capacity additions from Mexican and Japanese pilot operations.
Strategic Opportunities
- Thai cold-chain logistics expansion:Bangkok-based blast-freezing terminals offer underutilized capacity for Indian Ocean catch diversion.
- ISO 22000 certification arbitrage:Smaller Moroccan and Mauritanian operators can capture EU retail contracts by bridging the audit gap through third-party certification bodies.
- East Asian dried segment premiumization:Niche broth markets in China and Korea reward umami-concentrated product with price elevation above standard frozen blocks.
Industry Challenges
- Cephalopod veterinary specialist scarcity:Hatchery biologists with Octopus vulgaris larval-rearing expertise command premium compensation, slowing aquaculture R&D staffing.
- Multi-jurisdiction catch documentation reconciliation:Vessels landing in Moroccan ports for Spanish processing must harmonize national logbook formats with EU IUU Regulation digital submission portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Octopus Market |
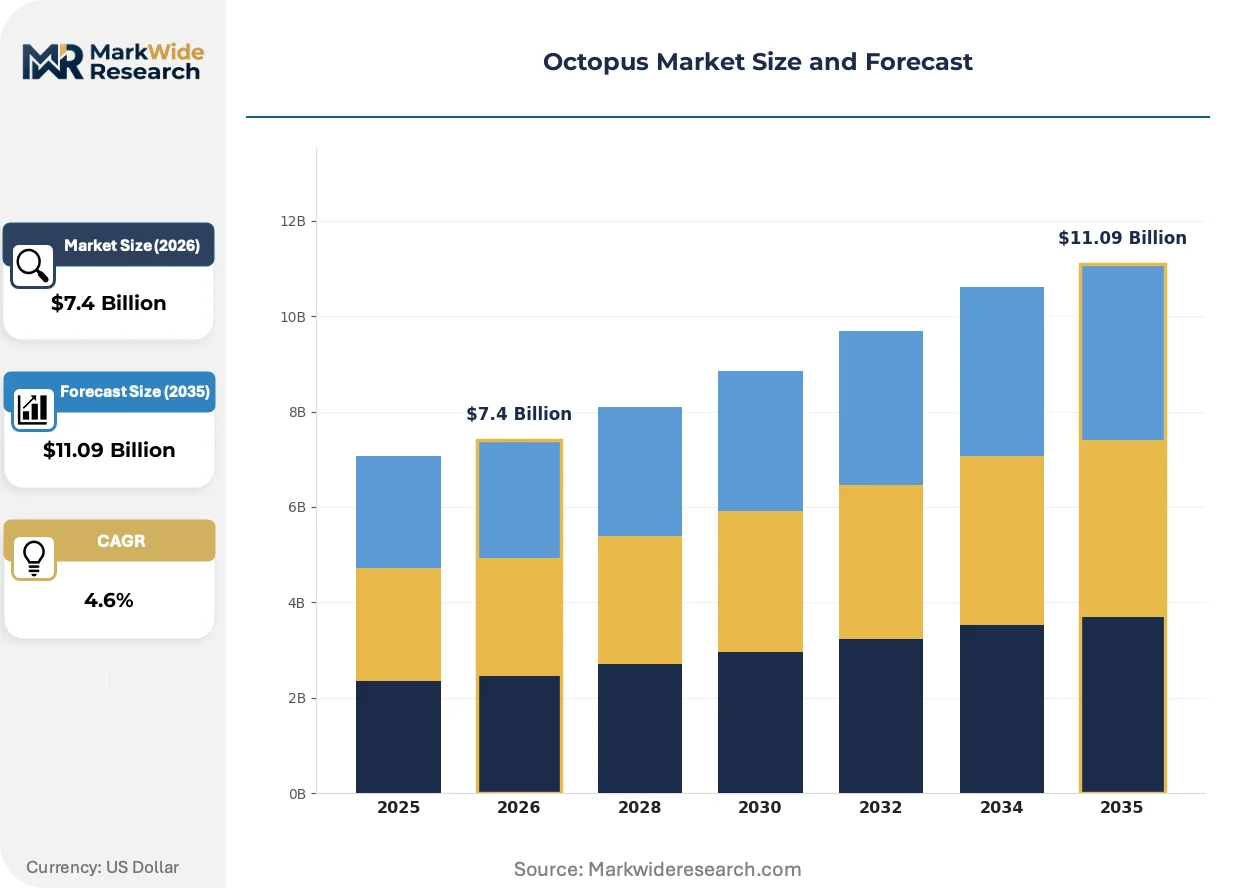
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.09 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Canned, Dried Distribution Channel: Supermarkets, Online Retail, Fish Markets, Direct Sales End User: Restaurants, Households, Food Processing, Catering Services Application: Sushi, Soups, Salads, Sauces |
| Companies Covered | Pescanova Hellas EPE, Nueva Pescanova S.L., Frigorificos de Camariñas S.L., Mackay Reef Fish Pty Ltd., Siam Canadian Foods Co. Ltd., Galveston Shrimp Company, Thai Union Group, Amigo Seafood Co., Joe Patti's Seafood Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Octopus Market Emerging Trajectories
Processing technology and regulatory digitization are compressing supply chain latency while buyer certification requirements are resegmenting supplier tiers.
Hypobaric storage systems for live octopus transport are miniaturizing from container-scale installations to truck-mounted units. Japanese high-end restaurant suppliers are piloting these systems for same-day airport-to-kitchen delivery. This is miniaturizing the geographic radius from which fresh product can be sourced without mortality loss.
EFSA traceability protocols now mandate species-level DNA verification for all frozen octopus blocks entering EU retail channels. Processing facilities in Vigo and Aveiro are retrofitting PCR testing lines to preempt port-of-entry rejection. The frozen retail segment bears the heaviest compliance burden, with Spanish supermarkets demanding batch-level genetic certificates.
Chef procurement is rotating toward supplier-held inventory models. Spanish tapas chains are shifting from weekly spot-market purchases to quarterly contracted volumes with certified Galician processors. This pattern is most visible in Madrid and Barcelona, where restaurant groups consolidate purchasing across thirty-plus locations.
Octopus Market Segmentation
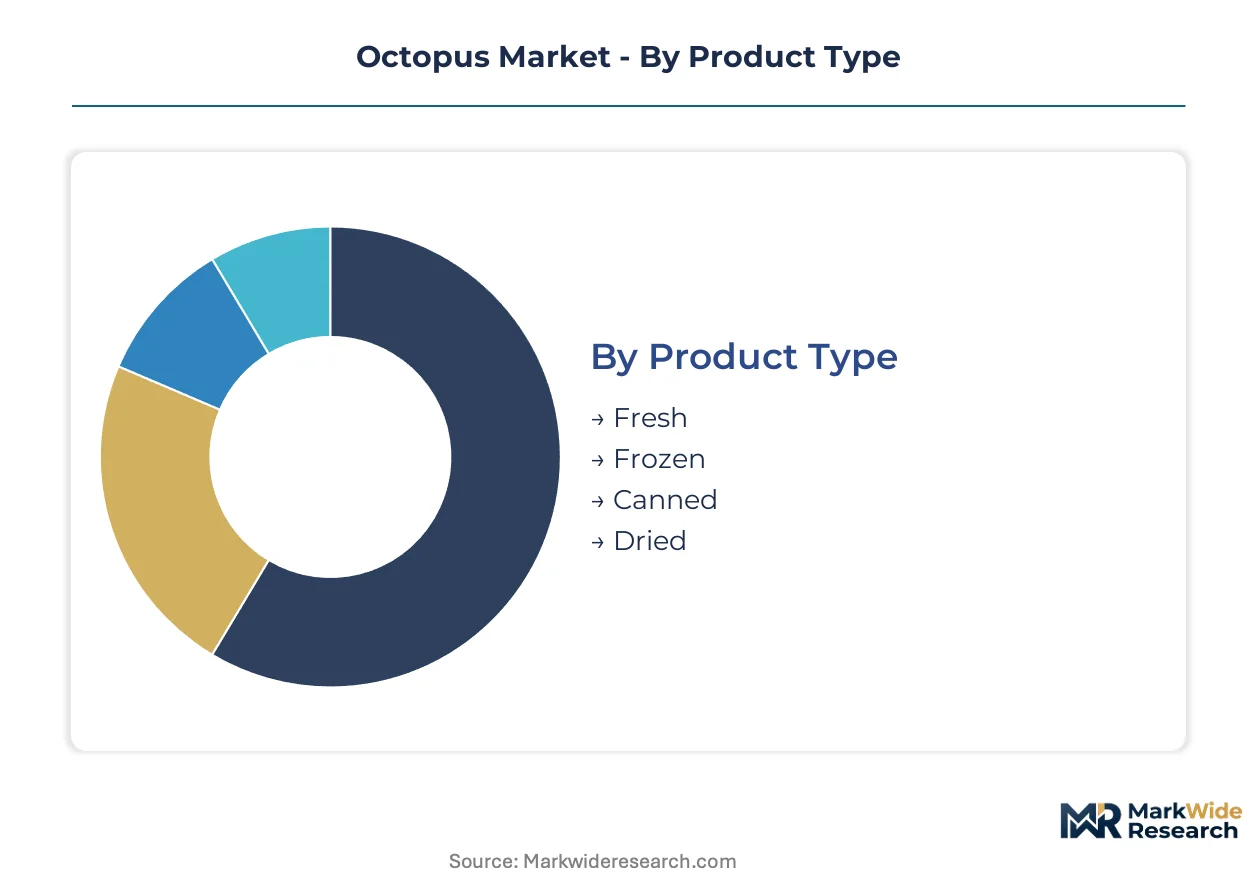
Octopus product flows split across preservation states, channel economics, and culinary preparation requirements. Each segment carries distinct cold-chain investments, certification thresholds, and substitution exposure from other cephalopods.
Product Type:
Fresh octopus faces the most acute substitution pressure from frozen blocks as blast-freezing quality improves and restaurant procurement shifts toward inventory-managed contracts.
- Frozen:Blast-frozen at sea in 10-20 kg blocks, this segment dominates intercontinental shipment corridors from Mauritanian and Moroccan waters to Iberian processing clusters. Japanese izakaya chains and Spanish tapas groups now specify frozen-over-fresh for consistency across multi-location operations.
- Fresh:Live or chilled product commands premium positioning in Tokyo sushi corridors and Madrid high-end restaurants where same-day mortality limits sourcing radius to 400-500 km from landing ports. Hypobaric transport systems are compressing this constraint.
- Dried:Traditional East Asian broth markets in China and Korea absorb this niche output where umami concentration justifies price elevation.
- Canned:Mediterranean shelf-stable product serves retail emergency-purchase occasions with limited growth trajectory.
Frozen retains volume leadership; fresh holds the steepest expansion curve as logistics technology extends its reachable market.
Distribution Channel:
Channel selection maps directly to certification burden and lot-size economics, with certified processors capturing share from fragmented wholesale layers.
- Supermarkets:EU retail chains now mandate species-level DNA verification and ISO 22000 documentation, favoring Spanish and Portuguese flagged suppliers with integrated cold-chain control.
- Fish Markets:Traditional wet markets in Japan, Korea, and southern Europe still absorb significant fresh volume but face regulatory documentation pressure under EU IUU Regulation traceability mandates.
- Online Retail:Direct-to-consumer frozen blocks are gaining traction in urban China and South Korea where cold-chain last-mile infrastructure matures.
- Direct Sales:Restaurant group procurement offices in Barcelona and Madrid are contracting quarterly volumes directly with Galician processors, bypassing wholesale layers.
Supermarkets concentrate compliance investment; online retail is climbing fastest as logistics infrastructure spreads.
End User:
End-user segmentation reveals diverging price sensitivity and volume predictability, with foodservice operators driving standardization requirements upstream.
- Restaurants:Sushi and izakaya operators in Japan plus tapas chains across Spain absorb the largest frozen-block volumes as octopus displaces cuttlefish in premium raw preparations.
- Food Processing:Prepared-meal manufacturers and sauce blenders in Portugal and Spain require consistent sizing and documented origin for retail co-packing contracts.
- Households:Retail purchase concentrates in coastal Iberian and Japanese urban centers with established octopus consumption traditions.
- Catering Services:Event and institutional foodservice demands volume flexibility with lower certification stringency than retail-facing channels.
Restaurants anchor procurement volume; food processing shows the sharpest specification tightening as retail co-packing expands.
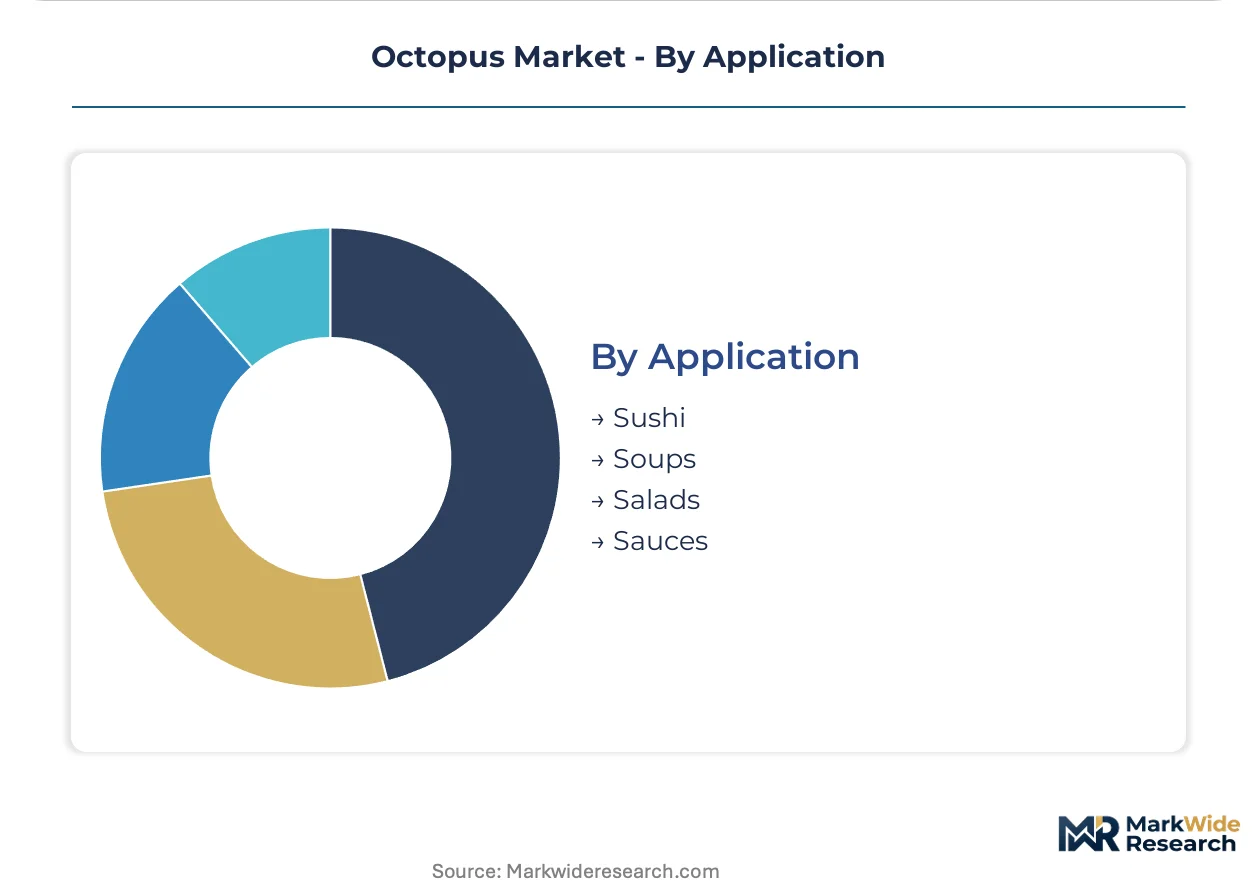
Application:
Application segmentation tracks culinary preparation method and corresponding product form requirements, with raw consumption imposing the strictest handling protocols.
- Sushi:Raw consumption in Japanese and Korean restaurants demands parasite-free certification, rapid chill chains, and specified tenderness grades.
- Soups:East Asian broth applications favor dried or frozen tentacle portions where extended simmering extracts maximum umami.
- Salads:Mediterranean and global casual-dining preparations require pre-cooked frozen product with consistent texture after thawing.
- Sauces:Processed food manufacturing incorporates minced or pureed octopus for flavor bases with less stringent whole-muscle specification.
Sushi commands the premium price tier; soup applications are gaining share fastest in East Asian market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese izakaya chains and Spanish tapas groups concentrate procurement volume, driving standardization requirements upstream toward processing clusters in Galicia and Vigo. Restaurant procurement offices in Tokyo and Madrid now contract quarterly volumes directly with certified processors.
Spain
Tapas chains across Madrid and Barcelona absorb the largest frozen-block volumes as octopus displaces cuttlefish in premium raw preparations. The EU IUU Regulation compels catch documentation for all Atlantic and Mediterranean landings, elevating compliance costs for non-certified operators. Galician processing clusters in Vigo and Aveiro retrofit PCR testing lines to preempt port-of-entry rejection under EFSA traceability protocols.
Japan
Sushi and izakaya operators in Tokyo and Osaka are absorbing larger frozen-block volumes as octopus gains share in premium raw preparations. The country's national food safety regulator mandates parasite-free certification and rapid chill chains for raw consumption. Kanto region suppliers pilot hypobaric storage systems for same-day airport-to-kitchen delivery of live product.
Portugal
Traditional processing hubs in Aveiro and Matosinhos maintain concentration as EU IUU Regulation traceability mandates redirect procurement toward flagged vessels with established digital logbook systems. Prepared-meal manufacturers and sauce blenders require consistent sizing and documented origin for retail co-packing contracts. Lisbon restaurant groups consolidate purchasing across thirty-plus locations through quarterly contracted volumes.
Morocco
Artisanal harvesters operating day-boat fleets from Agadir and Casablanca face diesel and ice input volatility eroding margins. National logbook formats must harmonize with EU IUU Regulation digital submission portals for vessels landing in Moroccan ports for Spanish processing. Smaller operators capture EU retail contracts by bridging the ISO 22000 audit gap through third-party certification bodies.
South Korea
Seoul-based restaurant chains drive frozen-block absorption as octopus gains share in premium raw preparations alongside Japan. The country's national food safety regulator enforces species-level verification for imported seafood blocks. Busan blast-freezing terminals offer underutilized capacity for Indian Ocean catch diversion into East Asian supply corridors.
Octopus Market Vendor Landscape
Player mix skews toward integrated Mediterranean processors with fleet proximity and Southeast Asian logistics specialists with cold-chain infrastructure. The vendor base separates into three tiers: Galician-flagged vessels with established digital documentation, Bangkok-based blast-freezing terminal operators, and smaller Moroccan artisanal harvesters bridging certification gaps. Consolidation pressure intensifies as EU IUU Regulation enforcement compresses wild-catch documentation timelines. Dominant competitive moves include ISO 22000 certification arbitrage and quarterly contracted volume arrangements with restaurant procurement offices.
Among Iberian integrated processors, Pescanova Hellas EPE and Nueva Pescanova S.L. occupy positions representing fleet-proximity archetypes with Galician infrastructure. Thai Union Group exemplifies the cold-chain logistics specialist tier, anchoring Southeast Asian supply corridor expansion. These three entities represent distinct competitive vectors: Mediterranean processing integration, Atlantic fleet documentation compliance, and intercontinental blast-freezing terminal utilization.
| Leading Market Players |
|---|
| Pescanova Hellas EPE |
| Nueva Pescanova S.L. |
| Frigorificos de Camariñas S.L. |
| Mackay Reef Fish Pty Ltd. |
| Siam Canadian Foods Co. Ltd. |
| Galveston Shrimp Company |
| Thai Union Group |
| Amigo Seafood Co. |
| Joe Patti's Seafood Company |
| Others |
Supply Flow & Price Mechanics
Blast-freezing technology substitution for traditional ice-packed fresh shipment is compressing landed cost differentials between Mauritanian catch and Mediterranean day-boat landings, simultaneously expanding supply geography toward West African waters while eroding the historical premium commanded by Galician-flagged fresh product.
Pricing Analysis
Cost-plus contracts with diesel indexation dominate procurement between Spanish processors and Moroccan artisanal fleets. Three-tier pricing structure across premium sushi-grade, standard foodservice blocks, and economy-grade catering portions reflects ISO 22000 certification status and volume scale. Pricing pressure stems from TAC-driven raw material scarcity in Iberian waters. Restaurant procurement offices show lowest price sensitivity; small-scale wet market distributors face acute margin compression.
Supply Chain Analysis
Strait of Gibraltar transit underwrites intercontinental shipment economics for frozen blocks moving from Agadir to Vigo processing clusters. Supply concentrates in Morocco, Mauritania, and Spain, with raw material dependencies on diesel, onboard ice capacity, and blast-freezing equipment. Single-source vulnerability runs through Moroccan port infrastructure for EU-bound landings. Distribution runs through certified Galician processors consolidating fragmented artisanal catch into retail-facing blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The octopus market rewards specialized capability holders—particularly hatchery biologists with Octopus vulgaris larval-rearing expertise and processors with integrated cold-chain documentation—while punishing fragmented operators lacking certification infrastructure or fleet proximity.
For Market Incumbents: Fortify backward integration into Moroccan and Mauritanian landing port operations to secure catch documentation compliance under EU IUU Regulation mandates. Expand quarterly contracted volume arrangements with Madrid and Barcelona restaurant procurement offices to lock in throughput against TAC-driven supply volatility.
For New Entrants and Emerging Players: Differentiate on ISO 22000 certification arbitrage by bridging third-party audit gaps for smaller West African operators seeking EU retail access. Target the East Asian dried segment where umami concentration commands price elevation above commodity frozen blocks, leveraging Bangkok blast-freezing terminals for Indian Ocean catch diversion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Iberian processors holding Galician fleet proximity but lacking Southeast Asian logistics footprint. Long-term viability hinges on aquaculture timeline resolution and regulatory documentation automation. Watch hatchery protocol breakthroughs as the decisive capacity inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22000 Certification Investment | Third-party audit completion unlocks EU supermarket contracts previously blocked to uncertified Moroccan operators. |
| Blast-Freezing Terminal Expansion | Bangkok and Busan cold-chain infrastructure diversion captures Indian Ocean catch outside traditional Iberian processing corridors. |
| Quarterly Contracted Volume Arrangements | Madrid restaurant group procurement offices bypass wholesale layers through direct processor relationships. |
| Hatchery Biologist Talent Acquisition | Octopus vulgaris larval-rearing expertise commands premium compensation and accelerates commercial aquaculture timelines. |
| Hypobaric Transport System Deployment | Truck-mounted live octopus units extend same-day delivery radius from 400 km toward 800 km for Tokyo sushi corridors. |
Methodological Framework
The analysis maps frozen block logistics, fresh product distribution, dried segment trade flows, and aquaculture development pipelines, each validated through primary interviews with Galician processing plant managers, Moroccan artisanal fleet operators, Japanese izakaya procurement directors, EU regulatory compliance officers, and Bangkok cold-chain terminal operators. Secondary validation draws from EU IUU Regulation submission databases, EFSA traceability protocol guidance, FAO capture statistics, and customs trade records. Bottom-up volume estimates triangulate against top-down demand modeling across preservation states and end-use channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include preservation state, distribution channel certification tier, end-user price sensitivity, and regional regulatory cluster. CAGRs derive from trend extrapolation moderated by supply-side constraint analysis, with aquaculture commercialization timelines and TAC adjustment schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable EU IUU Regulation enforcement and diesel price assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as Moroccan port infrastructure investments and Japanese hatchery breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Fish Meal Market
Seafood
Canned Mackerel Market
Seafood
Tuna Market
Seafood
European Frozen Seafood Market
Seafood
Canned Tuna Market
Seafood
Mussel Extract Market
Seafood
Europe Shrimp Market
Seafood
Toothfish Market
Seafood
Mackerel Market
Seafood
Canned Salmon Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
South America Canned Seafood Market
Seafood
Sea Biscuits Market
Seafood
Smoked Whiting Market
Seafood
Groundfish Market
Seafood
Surimi Market