
 Haddock Market | 2026-2036
Haddock Market Size, Share, and Industry Trends Forecast 2026-2036
Haddock Market Outlook
North Atlantic whitefish processing is broadening as Icelandic and Norwegian producers expand cold-storage and filleting capacity. Leroy Seafood leverages its integrated aquaculture and wild-catch operations across Nordic waters. Young's Seafood anchors British retail and food service channels with branded frozen lines. High Liner Foods competes through its North American distribution scale and value-added portion-cut programs.
Haddock is a gadoid marine fish with lean white flesh, typically 0.5–2 kg landed weight, processed through heading, gutting, filleting, blast freezing, or cold smoking for human consumption. Fresh and frozen product types dominate volume, though smoked haddock carries premium positioning in UK breakfast and recipe-dish segments. Food service and retail distribution channels split demand unevenly, with restaurants and caterers driving portion-cut and marinated formats while supermarkets favor whole and filleted presentations for home preparation.
Norway's national fisheries regulator enforces strict catch documentation and quota compliance that shapes export eligibility for haddock processors. The UK's Food Standards Agency and Marine Management Organisation apply landing limits and food safety protocols that filter market access for domestic and imported supply. Stakeholders must monitor quota negotiations, cold-chain infrastructure investments, and shifting retail private-label specifications to secure position in this regulated whitefish trade.
Market Dynamics
The haddock trade is tightening around quota-constrained supply from Iceland and Norway, forcing processors to compete for limited raw material through long-term vessel contracts and cold-storage investments.
Growth Catalysts
- EU Green Deal sustainable sourcing mandates:Retailers across Germany and France now require Marine Stewardship Council certification, pulling certified Icelandic landings into premium private-label programs.
- Prepared-meal manufacturing automation:British food manufacturers are scaling robotic portion-cutting lines that reduce labor cost per kilogram of frozen haddock fillets.
- Traceability blockchain integration:Norwegian exporters are deploying vessel-to-retail digital tracking that satisfies UK Food Standards Agency documentation requirements.
Market Restraints
- Fuel cost volatility:North Atlantic trawler operations face diesel price swings that compress vessel operating margins and limit fleet expansion.
- Supply concentration in Nordic waters:Over two-thirds of export-grade haddock originates from Icelandic and Norwegian quotas, creating single-source vulnerability.
- Substitute whitefish competition:Alaskan pollock and Atlantic cod fillets compete directly in frozen retail cases, pressuring haddock price premiums.
Strategic Opportunities
- Underpenetrated German food service:Independent restaurants in Bavaria and North Rhine-Westphalia remain underserved by portion-cut haddock distributors.
- Regulatory tailwind from UK carbon labeling:The British Retail Consortium's voluntary emissions disclosure scheme rewards low-carbon Icelandic supply chains with shelf placement.
- Direct-to-foodservice platform expansion:Digital procurement portals are bypassing traditional wholesale auctions, connecting Icelandic processors directly with UK caterers.
Industry Challenges
- Skilled filleting labor scarcity:Processing plants in Grimsby and Peterhead struggle to recruit experienced whitefish butchers.
- Cold-chain capex intensity:Blast freezing and controlled-atmosphere storage upgrades require capital outlays that strain mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Haddock Market |
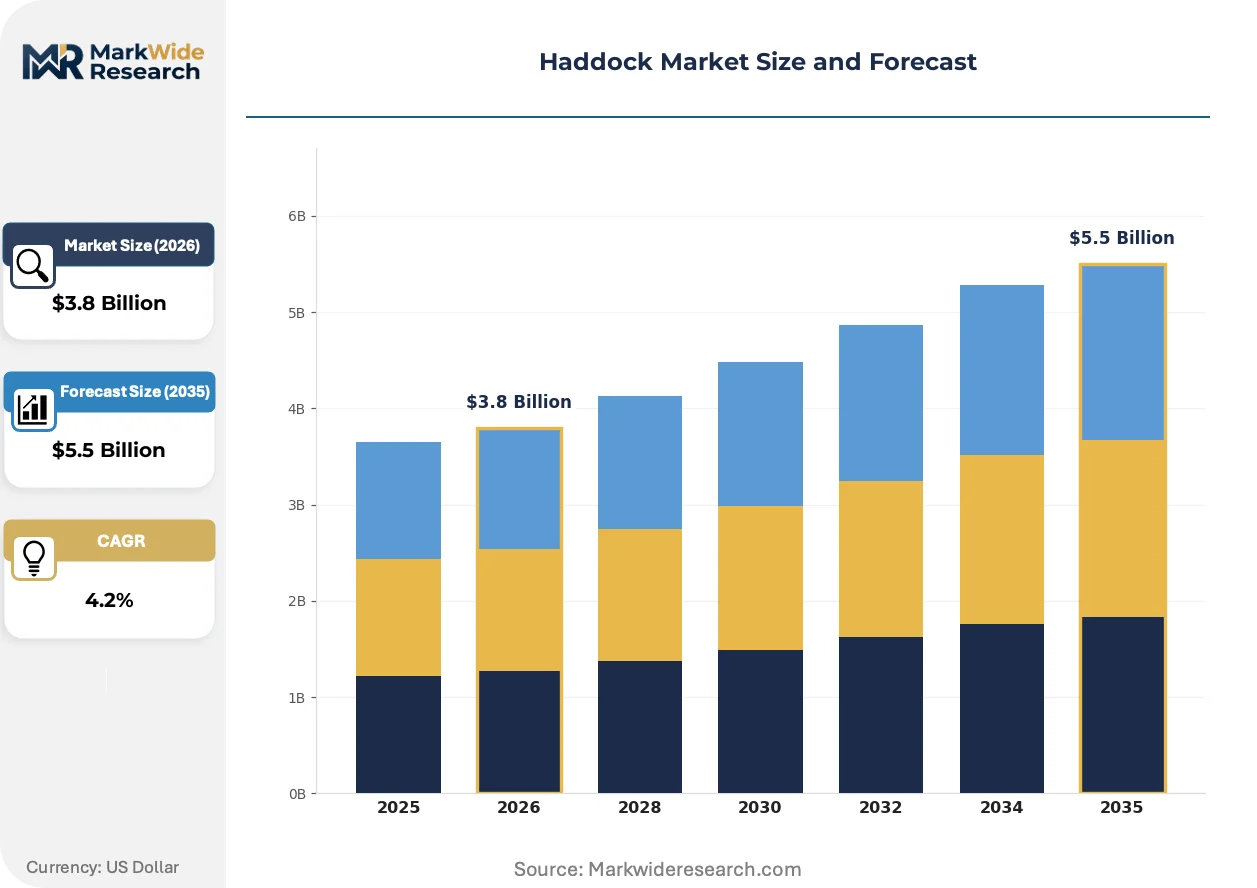
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Frozen, Smoked, Dried Distribution Channel: Retail, Wholesale, Online, Food Service End User: Restaurants, Supermarkets, Households, Caterers Processing Method: Filleted, Whole, Portion Cut, Marinated |
| Companies Covered | Leroy Seafood, Young's Seafood, High Liner Foods, Channel Fish Processing, Channel Seafoods International, CTLE Seafood, Holmes Seafood, Marine Harvest, Icelandic Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haddock Market Strategic Shifts
Processing technology and regulatory transparency are converging to reshape how haddock moves from vessel to retail shelf, with digital traceability and automation compressing traditional supply structures.
Hyperspectral imaging systems for real-time flesh-quality assessment are expanding into Nordic processing lines. Icelandic filleting plants are adopting this technology to sort raw material by fat content and texture before cutting. The systems are expanding into quality-control workflows that previously required manual inspection, reducing rejection rates at export gates.
Norway's national fisheries regulator now mandates electronic catch documentation for all haddock landings destined for EU markets. This policy creates compliance friction for smaller vessel operators lacking digital infrastructure. British importers are responding by consolidating purchases around large-scale Norwegian exporters with pre-certified documentation systems.
Food manufacturers are unbundling long-term supply contracts into shorter, volume-flexible agreements that track quarterly quota allocations. This pattern disrupts traditional annual procurement cycles between Icelandic producers and UK processors. The shift is most visible in Yorkshire prepared-meal factories, where buyers now index contract prices to live quota auction results.
Haddock Market Segmentation
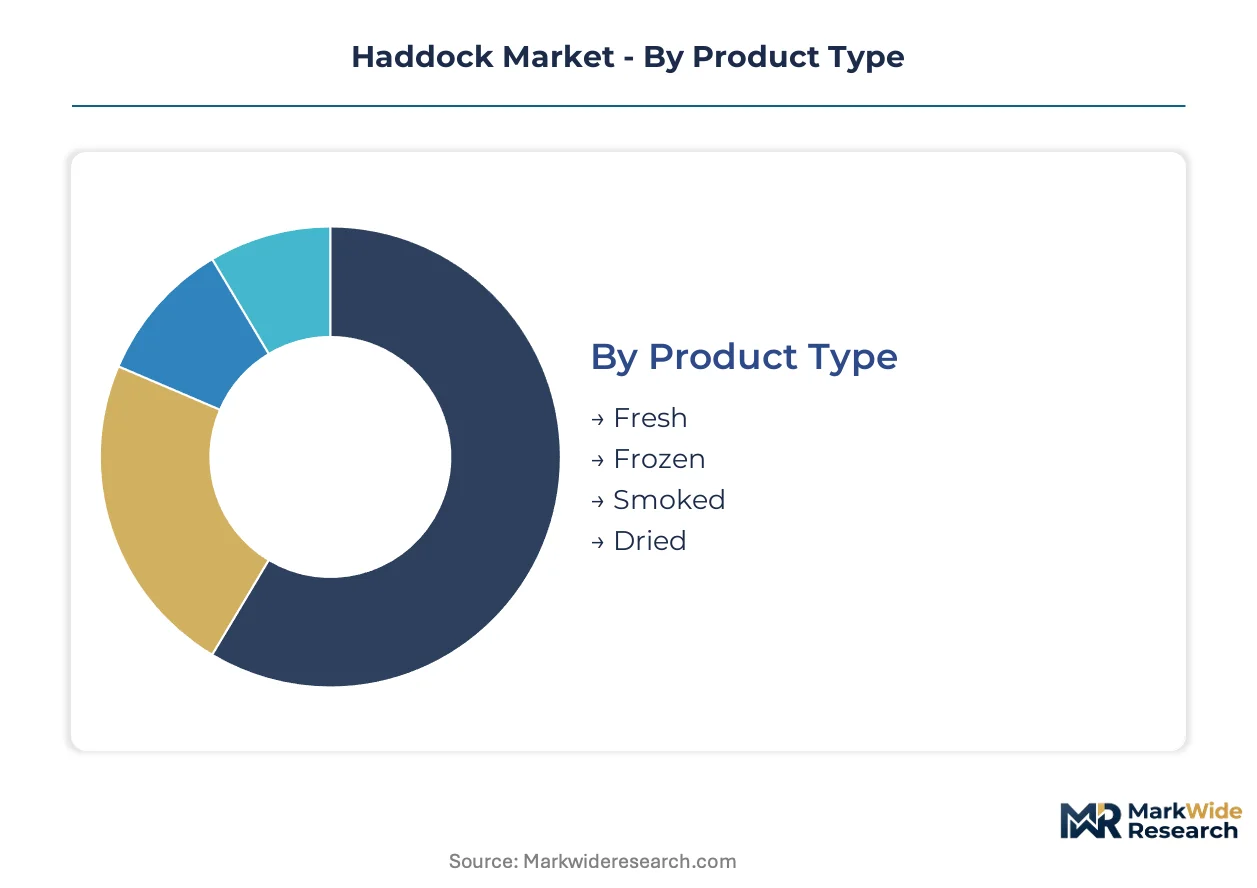
Haddock segmentation reveals how product form, channel access, and end-use application dictate margin capture across the value chain. Processing intensity and cold-chain requirements create distinct competitive arenas that separate commodity handlers from premium-positioned operators.
Product Type:
Frozen formats dominate volume throughput while fresh and smoked variants command price premiums in specialized channels.
- Fresh:Landed haddock maintains cellular structure and moisture content through rapid chilled distribution. UK fishmongers and high-end restaurants in London and Edinburgh drive procurement of same-day-catch fillets where texture differentiation justifies shorter shelf life.
- Frozen:Blast-frozen fillets at sea or in shore plants lock in quality for extended supply chains. European food service buyers and British prepared-meal manufacturers anchor demand for individually quick-frozen portions that tolerate inventory buffering.
- Smoked:Cold-smoked haddock carries traditional processing heritage with premium positioning in UK breakfast segments.
- Dried:Salt-dried preservation serves niche ethnic food markets and long-haul export corridors with limited refrigeration.
Mature deployment sits with Frozen. Newer deployment is concentrated in Smoked as craft processing techniques gain retail traction.
Distribution Channel:
Channel selection determines margin structure through cold-chain investment requirements and customer concentration risk.
- Retail:Supermarket chains and independent fishmongers stock fresh counter displays and frozen private-label cases. German and French retailers now require MSC certification as a condition of shelf placement, filtering supplier eligibility.
- Wholesale:Central market halls and specialized fish merchants aggregate landings for redistribution to smaller retail and food service accounts.
- Online:Direct-to-consumer platforms and B2B procurement portals are compressing traditional wholesale markups.
- Food Service:Contract caterers, restaurant groups, and institutional buyers purchase portion-cut and marinated formats at volume.
Established infrastructure concentrates in Wholesale. Digital procurement is expanding most quickly in Food Service as Icelandic processors bypass auction systems.
End User:
End-use differentiation separates commodity volume from value-added margin capture through preparation labor and specification tightness.
- Restaurants:White-tablecloth and casual dining operators specify center-cut fillets with consistent portion weights. London restaurant groups index procurement to Icelandic quota auction pricing through quarterly-adjusted contracts.
- Supermarkets:Multiple and discount grocery chains dominate frozen haddock volume with private-label and branded lines.
- Households:Direct consumer purchases through retail and online channels favor whole fish and skin-on fillets for home preparation.
- Caterers:Contract feeding operations and event specialists demand pre-portioned, marinated, or breadcrumbed formats that minimize kitchen labor.
Volume leadership rests with Supermarkets. Specification intensity is climbing fastest in Restaurants as chefs source named-provenance Icelandic landings.
Processing Method:
Processing depth correlates with margin expansion and capital intensity, separating commodity handlers from integrated operators.
- Filleted:Machine-guided or manual removal of pin bones and skin produces boneless, skinless fillets for retail and food service. Icelandic plants deploy hyperspectral imaging for real-time flesh quality sorting before cutting, reducing rejection rates at export gates.
- Whole:Headed-and-gutted presentation preserves product integrity for customers with in-house processing capability. Traditional fishmongers in UK coastal towns and ethnic wholesale markets in continental Europe maintain demand for round fish.
- Portion Cut:Standardized weight blocks and loins suit automated cooking equipment in prepared-meal factories.
- Marinated:Value-added coating, curing, or saucing commands premium positioning in retail ready-meal cases.
Operational scale centers on Filleted. Automation investment is accelerating most steeply in Portion Cut as Yorkshire prepared-meal factories scale robotic lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Icelandic and Norwegian waters anchor the raw-material base for North Atlantic haddock supply, with processing clusters concentrated in Nordic coastal towns and British port cities. Quota allocations in these jurisdictions determine annual export availability. Downstream demand concentrates in British prepared-meal manufacturing and German retail distribution.
United Kingdom
British prepared-meal manufacturers in Yorkshire and Grimsby drive demand for individually quick-frozen haddock portions. The Marine Management Organisation enforces landing limits and quota compliance that filter domestic and imported supply eligibility. London restaurant groups now index procurement contracts to live Icelandic quota auction pricing through quarterly-adjusted agreements.
Norway
Norwegian exporters supply premium-grade haddock fillets to German and French retailers demanding Marine Stewardship Council certification. The national fisheries regulator mandates electronic catch documentation for all EU-bound landings, creating compliance friction for smaller vessel operators. Bergen and Ålesund processing plants deploy vessel-to-retail digital tracking that satisfies British import documentation requirements.
Germany
German supermarket chains in Bavaria and North Rhine-Westphalia require MSC certification as a condition of frozen whitefish shelf placement. The EU Green Deal sustainable sourcing mandates pull certified Icelandic landings into premium private-label programs. Independent restaurants in southern Germany remain underserved by portion-cut haddock distributors, creating whitespace for direct procurement platforms.
Iceland
Icelandic catch quotas constrain total export volume, forcing processors to secure raw material through long-term vessel contracts. The national quota system allocates transferable catch rights that consolidate harvesting rights among larger integrated operators. Reykjanesbær and Grindavík filleting plants adopt hyperspectral imaging for real-time flesh quality sorting before cutting, reducing rejection rates at export gates.
France
French retailers in Paris and Lyon apply sustainability criteria that favor traceable Nordic supply chains over non-certified alternatives. EFSA food safety protocols and national labeling requirements filter market access for imported whitefish. Brittany and Normandy food service distributors aggregate haddock landings for redistribution to smaller restaurant accounts, though direct-to-caterer digital portals are compressing traditional wholesale markups.
Haddock Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue traceability-certified premium positioning through blockchain documentation and MSC accreditation. The competitive terrain separates integrated Nordic operators with captive vessel fleets from British processors dependent on auction-sourced raw material. Three archetypes dominate: quota-holding integrated harvesters, retail-branded portion-cut specialists, and food service distribution scalers. Consolidation pressure manifests through cold-storage capacity investments and long-term supply contract restructuring.
Among Nordic integrated operators, Leroy Seafood represents the quota-backed vertical archetype with operations spanning Norwegian and Icelandic waters. Young's Seafood anchors British retail and food service channels as a branded frozen line specialist. High Liner Foods occupies North American distribution scale positioning through value-added portion-cut programs. These three exemplify how geographic origin and channel focus stratify competitive position in quota-constrained supply conditions.
| Leading Market Players |
|---|
| Leroy Seafood |
| Young's Seafood |
| High Liner Foods |
| Channel Fish Processing |
| Channel Seafoods International |
| CTLE Seafood |
| Holmes Seafood |
| Marine Harvest |
| Icelandic Group |
| Others |
Value Chain & Pricing Dynamics
MSC certification tiers separate premium Icelandic landings from standard Norwegian supply in both contract pricing and vessel-sourcing requirements. Buyers bundling traceability documentation with long-term offtake agreements command favorable terms, while commodity handlers face margin compression from unbundled spot purchases at auction.
Pricing Analysis
Traceability warranty bundling distinguishes premium contracts from stripped-down spot transactions at Grimsby auction houses. Three-tier pricing structure across MSC-certified premium, standard IQF fillets, and economy-grade whole fish reflects vessel-provenance and documentation completeness. Pricing pressure stems from Alaskan pollock substitution in frozen retail cases, compressing haddock premiums. Prepared-meal manufacturers exhibit highest price sensitivity due to automated portion-cutting investments, while London restaurant groups absorb premiums for named-provenance Icelandic landings.
Supply Chain Analysis
UK landing limits and Norwegian electronic catch documentation mandates reshape sourcing toward large-scale integrated operators with pre-certified vessel fleets. Raw material draws from Icelandic transferable quota holders, Norwegian coastal trawlers, and limited Faroese landings. Single-source vulnerability concentrates in Reykjanesbær and Grindavík processing clusters dependent on quota-constrained domestic catch. Distribution runs through Bergen cold-storage hubs to British prepared-meal factories and German retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
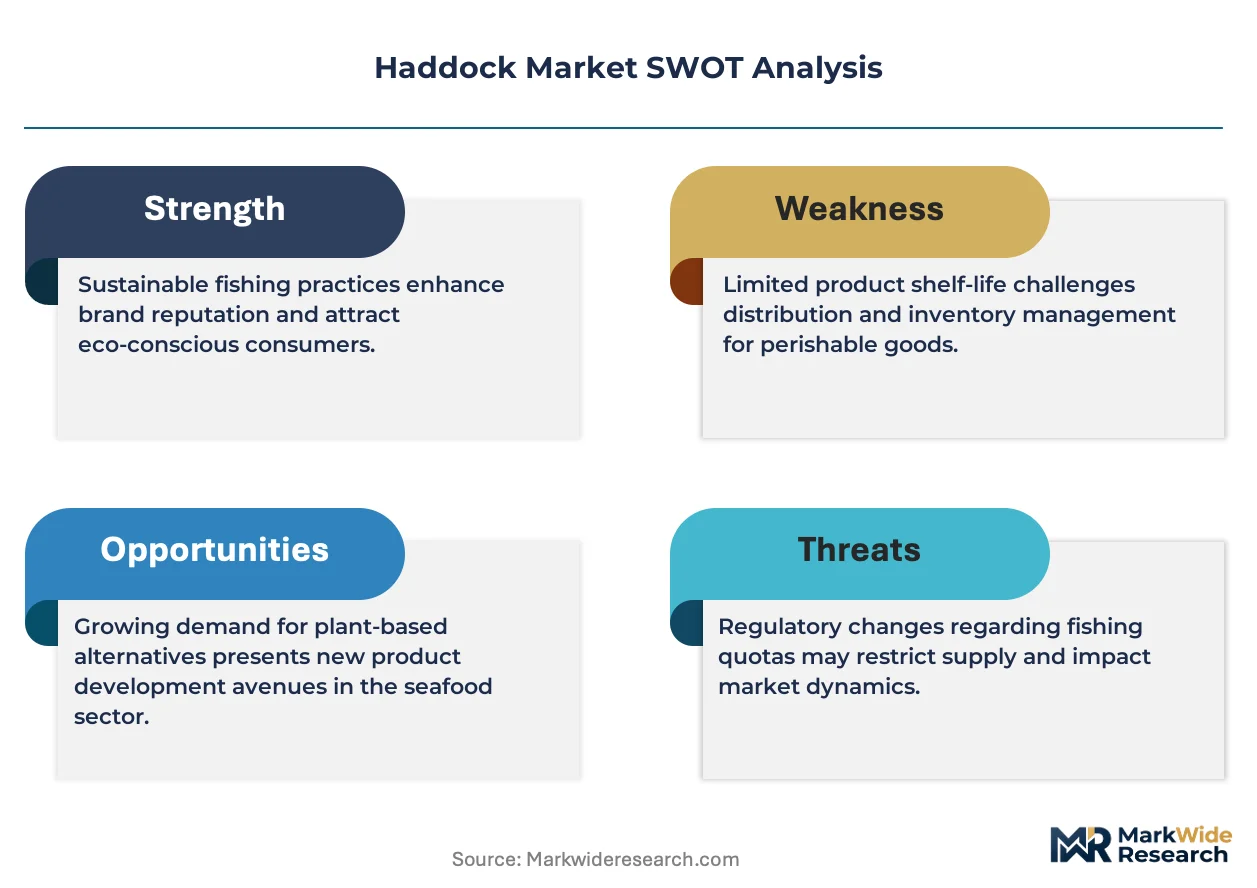
The haddock trade operates as a cost-of-compliance market where Norway's electronic catch documentation mandate and Iceland's transferable quota system erect regulatory moats favoring capitalized incumbents with vessel-to-retail digital infrastructure.
For Market Incumbents: Anticipate quota consolidation pressure by securing long-term vessel contracts before transferable rights concentrate among rival integrated operators. Reinforce cold-storage capacity at Grimsby and Peterhead to buffer auction price volatility. MSC certification investment defends shelf placement against substitute whitefish encroachment in German retail channels. For New Entrants and Emerging Players: Launch via direct-to-foodservice digital procurement portals targeting underserved independent restaurants in Bavaria and North Rhine-Westphalia. Bypass traditional wholesale markups by connecting Icelandic processors with UK contract caterers through B2B platforms. Smoked haddock craft processing offers whitespace traction in premium UK breakfast segments. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated quota holders given EU Green Deal sustainable sourcing mandates accelerating retailer consolidation around certified supply chains. Long-term viability favors operators with captive vessel fleets and shore-based processing assets across the analysis window. Monitor Icelandic quota auction clearing prices as inflection signal for raw material cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Quota-Backed Vessel Fleet Expansion | Captive raw material supply insulates processors from auction price volatility in Icelandic waters. |
| Blockchain Traceability Integration | Vessel-to-retail digital tracking satisfies UK Food Standards Agency documentation requirements for EU export eligibility. |
| Robotic Portion-Cut Automation | Yorkshire prepared-meal factories reduce labor cost per kilogram through scaled robotic filleting lines. |
| MSC Certification Program | German and French retailers require certification as condition of frozen whitefish shelf placement. |
| Cold-Storage Capacity Buildout | Blast freezing and controlled-atmosphere upgrades at Grimsby buffer inventory against quota auction volatility. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Icelandic quota holders, Norwegian processing plant managers, UK prepared-meal procurement directors, and German retail category buyers validated supply chain configurations. Marine Management Organisation landing statistics, Icelandic Directorate of Fisheries quota auction results, and EU customs trade databases provided volume triangulation against bottom-up processor capacity assessments.
Granularity-level modeling operated at product type, distribution channel, and end-user segmentation dimensions across the projection horizon. CAGRs derived from quota allocation trajectories, cold-storage capacity expansion schedules, and prepared-meal manufacturing automation adoption curves. Icelandic catch quota transfers, Norwegian electronic documentation compliance rates, and UK carbon labeling scheme participation informed scenario-weighted outputs.
The model assumes a particular technology adoption path; alternative pathways for hyperspectral imaging quality sorting would alter the outlook for fillet rejection rates and export gate economics. Forecasts reflect documented assumptions regarding quota stability, fuel cost normalization, and substitute whitefish price convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Powders Market
Seafood
Edible Seaweed Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Sea Biscuits Market
Seafood
Europe Seafood Market
Seafood
Mackerel Market
Seafood
North America Salmon Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Frozen Seafood Market
Seafood
Sea Bass Market
Seafood
Global Shrimp Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Seafood Flavors Market
Seafood
Canned Salmon Market
Seafood
Surimi Market