
 Robotic Process Automation (RPA) in Financial Services Market | 2026-2036
Robotic Process Automation (RPA) in Financial Services Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Process Automation (RPA) in Financial Services Market Analytics
North American software engineering capacity is pivoting toward financial-grade automation platforms with embedded governance layers. UiPath sustains broad horizontal coverage across banking workflows, while Automation Anywhere specializes in cloud-native bot orchestration for distributed compliance teams. SS&C Blue Prism anchors high-security deployments inside investment firms with strict data residency requirements.
Robotic Process Automation in financial services deploys software bots that mimic human interactions with core banking systems, ERP modules, and customer-facing applications through structured UI manipulation and API orchestration at throughput rates exceeding 10,000 transactions per hour. Its primary commercial purpose is to execute high-volume, rule-based processes without human intervention while maintaining complete audit trails for regulatory examination. Cloud-based deployment is displacing on-premise installations as banks seek elastic capacity for seasonal workload spikes in mortgage processing and tax reporting. AI integration represents the fastest-expanding technology segment, though optical character recognition still occupies the largest share of legacy document digitization workflows. Banking institutions dominate end-user demand, while payment processors represent the most margin-attractive customer category due to real-time transaction volume requirements.
The SEC enforces disclosure obligations on automated decision systems used in credit underwriting and fraud scoring, compelling vendors to embed explainability modules. The EU AI Act classifies certain financial RPA applications as high-risk, mandating conformity assessments before deployment across European banking networks. GDPR and state-level privacy statutes in California and New York constrain cross-border data flows that unattended bots frequently trigger during overnight batch processing. Stakeholders must weigh regulatory fragmentation against the operational efficiency gains of centralized bot management platforms.
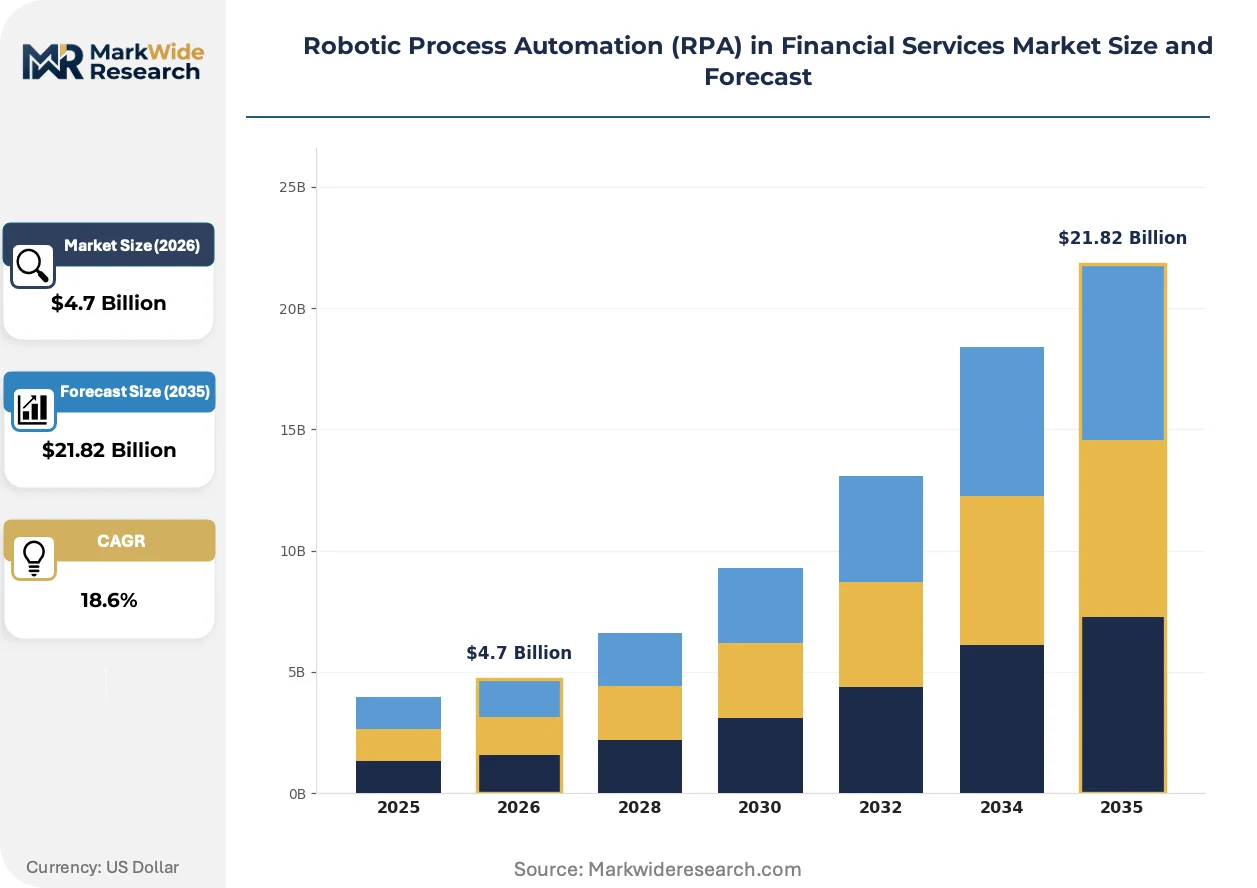
Market Dynamics
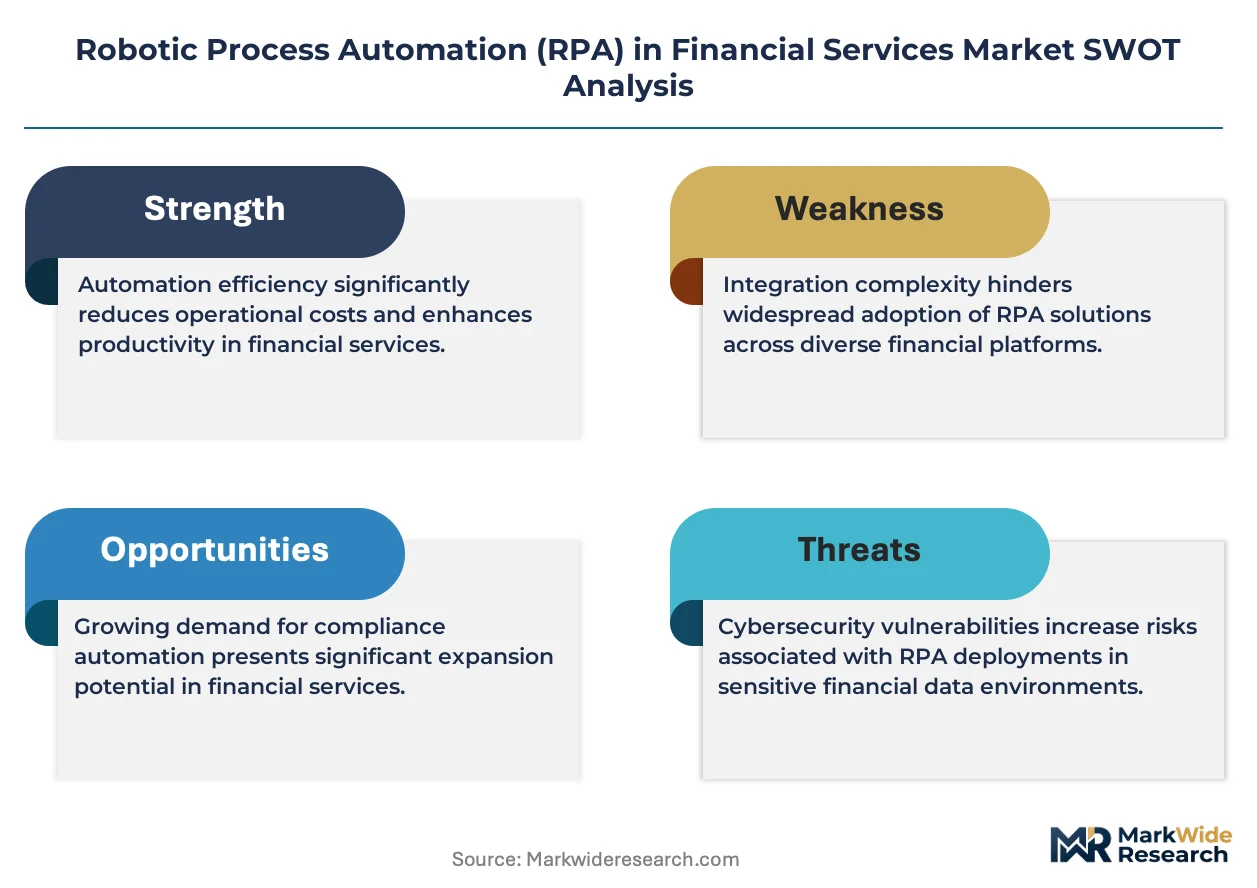
The EU AI Act's high-risk classification of credit underwriting automation is forcing banks to retrofit explainability modules into legacy bot deployments, compressing vendor development cycles and elevating audit infrastructure from optional feature to mandatory architecture.
Growth Catalysts
- Cloud-native orchestration:Distributed compliance teams at payment processors demand elastic bot capacity for real-time transaction monitoring, displacing rigid on-premise installations.
- GDPR Article 17 compliance automation:European banks deploy attended bots to execute data erasure requests across fragmented core banking systems, reducing manual processing backlogs.
- Anti-money laundering workflow digitization:Suspicious activity report filing automation at US Tier 1 institutions now processes threshold alerts at throughput rates exceeding human capacity by orders of magnitude.
Market Restraints
- Cross-border data friction:GDPR and California Consumer Privacy Act constraints trigger compliance costs when unattended bots execute overnight batch processes across jurisdictions.
- Legacy system integration complexity:Mainframe-based core banking architectures at established institutions resist API-based bot connectivity, requiring expensive middleware layers.
- Specialized talent scarcity:Shortages of engineers fluent in both financial compliance logic and RPA platform configuration inflate implementation timelines.
Strategic Opportunities
- SEC disclosure rule alignment:Vendors embedding native audit trails and decision-explanation engines capture preference share among US institutions preparing for examination.
- AI-RPA convergence:Intelligent document processing combining optical character recognition with natural language understanding opens mortgage underwriting automation at regional banks.
- India's banking modernization:Public sector bank digitization mandates under RBI supervision create demand for attended automation in rural branch networks.
Industry Challenges
- Bot credential management:Security teams struggle to maintain least-privilege access controls across thousands of unattended bot identities with rotating authentication requirements.
- Change management resistance:Operations staff at acquired institutions frequently circumvent mandated automation protocols, preserving shadow manual processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Process Automation (RPA) in Financial Services Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Compliance Monitoring, Invoice Processing, Customer Onboarding End User: Banking Institutions, Insurance Companies, Investment Firms, Payment Processors Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Technology: AI Integration, Machine Learning, Natural Language Processing, Optical Character Recognition |
| Companies Covered | Pega, Microsoft Power Automate, UiPath, EdgeVerve, WorkFusion, Automation Anywhere, IBM Robotic Process Automation, Appian, SS&C Blue Prism, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Process Automation (RPA) in Financial Services Market Evolving Landscape
Financial automation architecture is pivoting from monolithic bot deployments toward composable, governance-embedded platforms that satisfy simultaneous demands from risk committees and engineering teams.
Intelligent automation platforms are modularizing core banking connectivity into standardized, reusable components that reduce deployment time for new workflows. Mid-market banks in Germany and the Netherlands are adopting these pre-built connectors at accelerated procurement cycles. The structural consequence is compressing vendor implementation revenue from multi-year professional services engagements toward recurring subscription models anchored by connector libraries.
EU AI Act conformity assessments now precede deployment authorization for high-risk credit decisioning automations across European banking networks. This regulatory architecture elevates documentation and testing costs but simultaneously creates procurement preference for vendors with pre-certified module libraries. French and Italian institutions are consolidating vendor relationships toward those offering bundled conformity services.
Buying patterns among US regional banks are rotating from perpetual license models toward consumption-based pricing tied to transaction throughput. Channel partners and system integrators are restructuring compensation to align with this shift, capturing margin through managed service overlays rather than upfront implementation fees. This behavioral change is most pronounced among institutions with assets between $10 billion and $100 billion navigating compressed technology budgets.
Robotic Process Automation (RPA) in Financial Services Market Segmentation
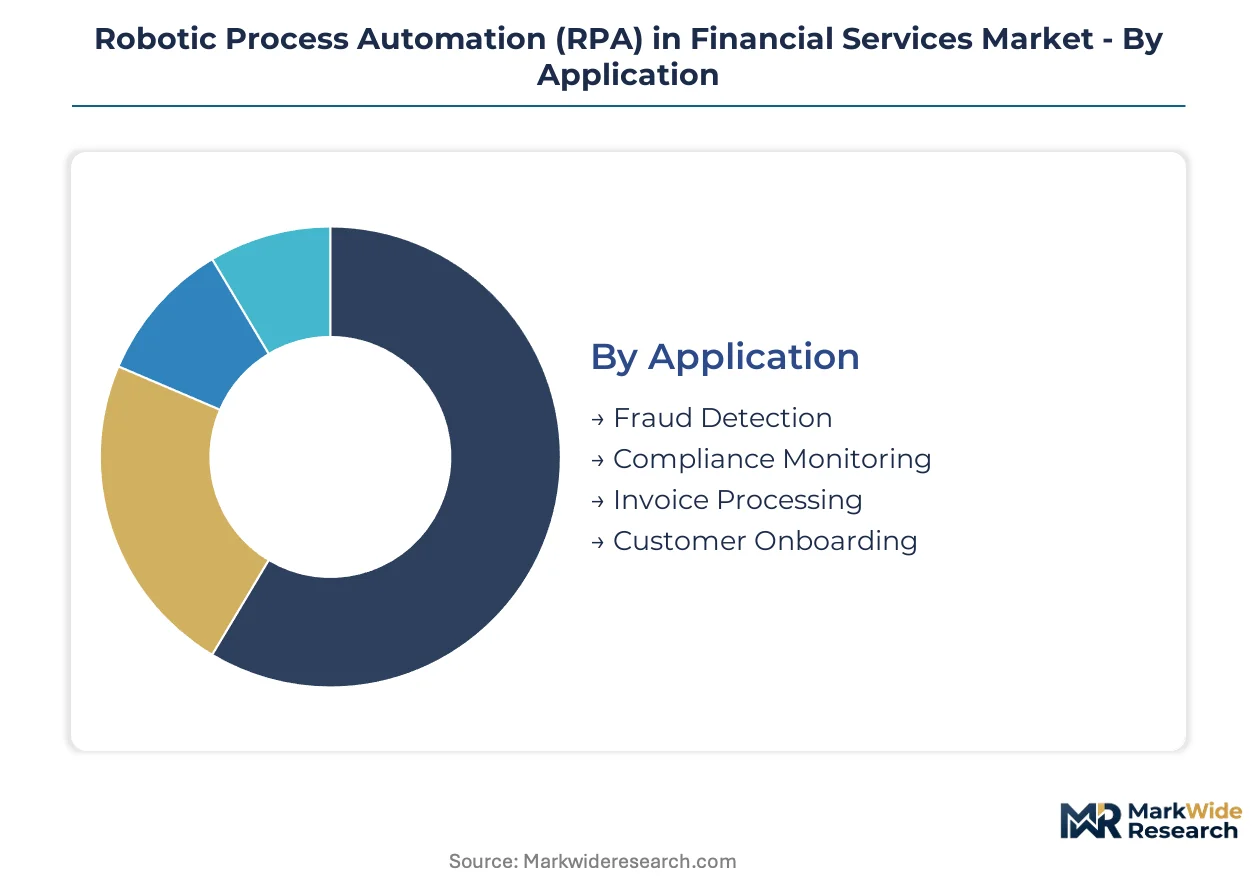
Financial services RPA procurement hinges on matching deployment architecture to regulatory jurisdiction and workload predictability. Segmentation reveals how technology choices cascade into compliance posture and operational economics across banking networks.
Application:
Functional use cases determine bot complexity tiers and audit trail requirements.
- Fraud Detection:Real-time transaction pattern analysis demands sub-second bot response latencies and continuous model retraining pipelines. US Tier 1 banks concentrate investment here driven by SEC disclosure obligations on automated scoring systems.
- Compliance Monitoring:Regulatory workflow automation spans AML alert triage, GDPR Article 17 erasure execution, and EU AI Act conformity documentation. European institutions prioritize this segment under supervisory pressure from EBA and national regulators.
- Invoice Processing:Accounts payable automation extracts line-item data from unstructured vendor documents through OCR-NLP hybrid pipelines.
- Customer Onboarding:KYC document verification and identity validation workflows accelerate account opening at digital-first banks.
Mature deployment sits with Invoice Processing. Newer deployment is concentrated in Compliance Monitoring.
End User:
Customer type shapes pricing models and service-level expectations.
- Banking Institutions:Universal banks deploy the largest attended and unattended bot fleets across retail, commercial, and investment banking divisions. US institutions dominate installed base volume driven by operational scale and regulatory examination intensity.
- Payment Processors:Real-time transaction clearing requirements create the most margin-attractive customer category. Elastic cloud-native orchestration commands premium pricing for seasonal volume spikes.
- Insurance Companies:Claims processing and policy administration automation lags banking adoption due to unstructured document complexity.
- Investment Firms:Strict data residency requirements favor on-premise or private cloud deployments with SS&C Blue Prism anchoring high-security installations.
Banking Institutions anchor current revenue. Payment Processors are climbing the fastest.
Deployment:
Infrastructure location directly determines data sovereignty compliance and capacity elasticity.
- Cloud-Based:Elastic compute pools scale bot capacity for mortgage processing seasonality and tax reporting peaks. GDPR cross-border transfer constraints limit European adoption despite operational advantages.
- On-Premise:Air-gapped installations satisfy data residency mandates at investment firms and Swiss private banks. Fixed capacity creates procurement friction during volume spikes.
- Hybrid:Sensitive workflows remain on-premise while scalable tasks burst to cloud infrastructure.
- Managed Services:Third-party bot operations transfer credential management and maintenance burden to specialized providers.
On-Premise retains share at investment firms. Cloud-Based is gaining share fastest.
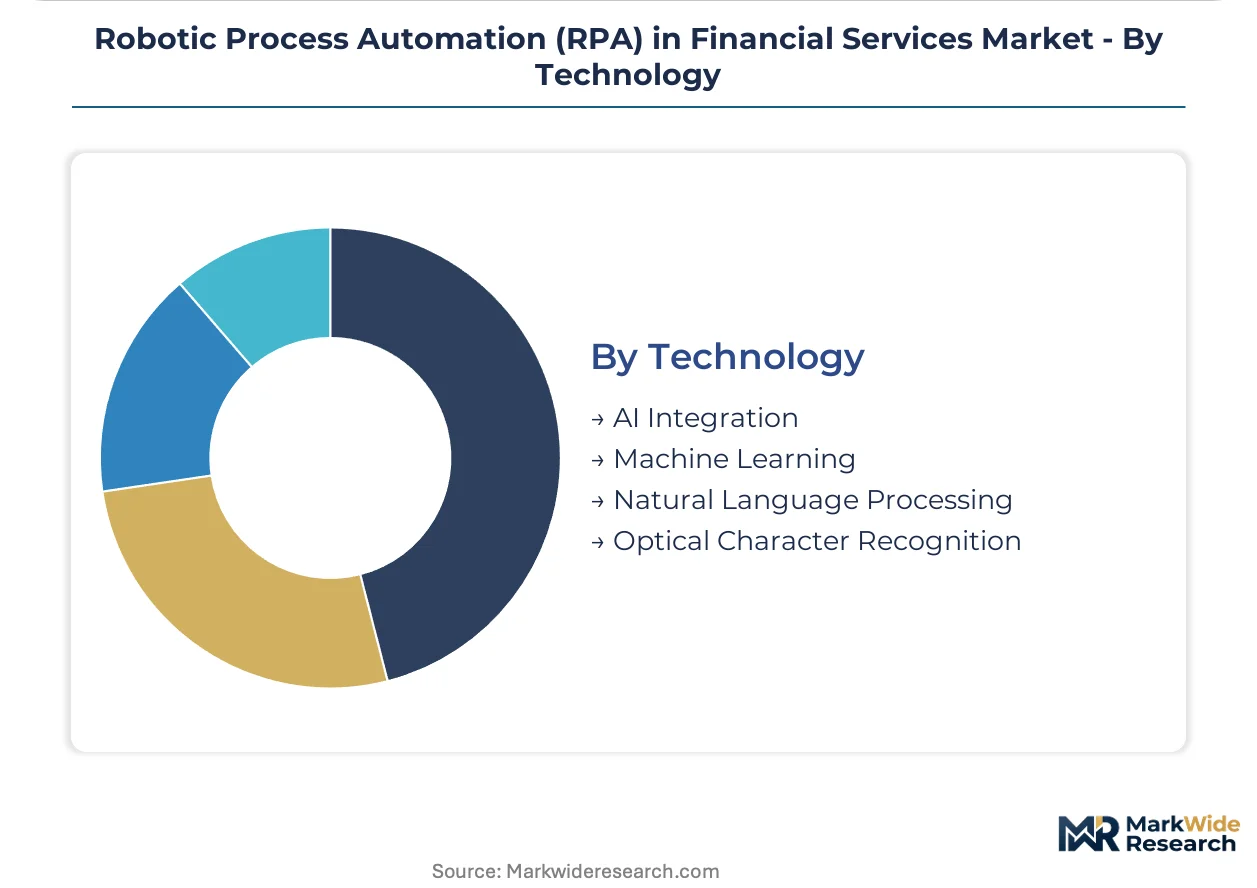
Technology:
Intelligence layering transforms rule-based automation into adaptive decision systems.
- Optical Character Recognition:Legacy document digitization occupies the largest technology share through mature extraction engines. Mortgage and trade finance workflows depend on OCR accuracy for downstream processing validity.
- AI Integration:Machine learning model embedding enables exception handling beyond rigid rule sets. This segment expands most quickly as vendors retrofit explainability modules for EU AI Act high-risk classification compliance.
- Natural Language Processing:Unstructured text comprehension powers customer communication analysis and contract review automation.
- Machine Learning:Predictive models enhance fraud scoring and credit decisioning with continuous feedback loops.
Optical Character Recognition anchors legacy workflows. AI Integration commands newest investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's software engineering density anchors North American RPA development, while Frankfurt's banking concentration drives European demand for compliance-embedded automation platforms.
United States
Tier 1 banks in New York and Chicago operate the largest installed bases of attended and unattended automations for AML workflows and SEC disclosure compliance. The SEC mandates explainability modules for automated credit underwriting systems, forcing vendors to retrofit audit infrastructure. Charlotte's banking cluster concentrates bot deployment for mortgage processing seasonality.
Germany
Frankfurt's universal banks drive demand for GDPR Article 17 erasure automation across fragmented core banking systems. The EU AI Act's high-risk classification for credit decisioning compels conformity assessments before deployment. Munich's insurance sector lags in adoption due to unstructured document complexity in claims processing.
United Kingdom
London's investment banks favor SS&C Blue Prism for strict data residency requirements in high-security deployments. The Financial Conduct Authority's operational resilience rules pressure firms to document bot decision trails. Edinburgh's fintech cluster experiments with cloud-native orchestration for distributed compliance teams.
India
Mumbai's public sector banks execute RBI-mandated digitization through attended automation in rural branch networks. The central bank's supervision framework prioritizes bot credential management for overnight batch processes. Bangalore's IT services corridor supplies engineers fluent in financial compliance logic and platform configuration.
Switzerland
Zurich's private banks maintain on-premise installations for air-gapped data sovereignty compliance. FINMA's guidance on operational risk amplifies audit trail requirements for cross-border wealth management workflows. Geneva's commodity trading houses deploy elastic capacity for seasonal tax reporting peaks.
Robotic Process Automation (RPA) in Financial Services Market Competitive Landscape
Global majors compete with regional champions across governance-embedded platform architectures, with horizontal coverage specialists facing vertical specialists in banking workflow automation. The vendor base organizes into three tiers: cloud-native orchestration platforms, high-security on-premise anchors, and AI-integration specialists. Consolidation pressure intensifies as EU AI Act conformity costs favor vendors with pre-certified module libraries. M&A activity targets connector library assets, while strategic partnerships reshape channel economics toward consumption-based pricing.
Within the horizontal automation tier, UiPath and Automation Anywhere occupy positions as scale-driven platform providers, with the former sustaining broad banking workflow coverage and the latter specializing in distributed compliance team orchestration. SS&C Blue Prism anchors the high-security deployment segment for investment firms with strict data residency requirements. These three exemplify the strategic archetype divergence between elastic cloud-native capacity and fixed on-premise governance infrastructure.
| Leading Market Players |
|---|
| Pega |
| Microsoft Power Automate |
| UiPath |
| EdgeVerve |
| WorkFusion |
| Automation Anywhere |
| IBM Robotic Process Automation |
| Appian |
| SS&C Blue Prism |
| Others |
Value Network & Pricing Analysis
Cloud-native orchestration platforms are displacing rigid on-premise installations across banking networks, simultaneously compressing implementation margins and concentrating procurement power with vendors offering elastic capacity pools. This technology transition elevates recurring subscription economics over perpetual license revenue while redistributing supply chain leverage toward hyperscaler infrastructure partners.
Pricing Analysis
Service bundling separates premium-tier vendors with embedded EU AI Act conformity assessments from unbundled competitors charging separately for audit infrastructure. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification depth and after-sales support intensity. Price differentiation hinges on explainability module sophistication and geographic data residency guarantees. Regional banks with assets between $10 billion and $100 billion exhibit highest price sensitivity due to compressed technology budgets, while payment processors accept premium pricing for real-time throughput guarantees. Cost compression in standard tiers intensifies because channel partners are restructuring compensation toward consumption-based models.
Supply Chain Analysis
Freight costs for on-premise hardware deployments to Swiss private banks and investment firms in London remain elevated due to air-gapped security requirements. Software supply draws from the United States, India, and Ireland, with development concentrated in Silicon Valley and Bangalore's IT services corridor. Component dependencies include hyperscaler compute capacity, API middleware layers, and optical character recognition engines. Single-source vulnerability sits with cloud infrastructure concentration among three dominant providers. Distribution runs through system integrators and channel partners restructuring toward managed service overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The financial RPA sector is transitioning from rule-based bot deployments toward AI-integrated intelligent automation platforms, with legacy OCR-centric workflows ceding share to natural language understanding pipelines.
For Market Incumbents: Anticipate margin compression from consumption-based pricing adoption by regional banks and defend through backward integration into connector library assets. Consolidate vendor relationships at French and Italian institutions seeking bundled EU AI Act conformity services. Threat emergence from cloud-native specialists demands certification investment in pre-certified module libraries. Channel control levers include restructuring partner compensation toward transaction-based models. For New Entrants and Emerging Players: Enter via white-space targeting of India's public sector bank digitization mandates under RBI supervision, where attended automation demand in rural branch networks remains underpenetrated. Regional banks in Germany and the Netherlands offer penetrable procurement cycles for pre-built core banking connectors. Go-to-market execution should emphasize consumption-based pricing alignment with compressed technology budgets. For Investors and Strategic Acquirers: Re-rating potential sits with vendors possessing pre-certified EU AI Act module libraries given conformity assessment cost escalation across European banking networks. Long-term viability favors platforms with embedded governance layers satisfying simultaneous risk committee and engineering demands. Acquisition target archetype: specialists in intelligent document processing combining OCR with natural language understanding. Signal to watch: consolidation velocity among mid-market banks rotating from perpetual licenses toward elastic cloud-native orchestration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | UiPath and Automation Anywhere embed explainability modules for SEC disclosure compliance. |
| Acquisition of Specialist Firm | Connector library assets compress implementation timelines at mid-market European banks. |
| Geographic Expansion | SS&C Blue Prism anchors high-security deployments in Swiss private banking networks. |
| Strategic Partnership | Hyperscaler alliances provide elastic compute pools for payment processor seasonal spikes. |
| Product Launch | Intelligent document processing opens mortgage underwriting automation at regional banks. |
Research Methodology
Document review covered SEC disclosure filings, EU AI Act regulatory texts, and EBA supervisory guidance, complemented by interviews with banking technology officers, compliance automation leads, RPA platform engineers, and channel partner executives. Secondary validation drew from vendor annual reports, hyperscaler infrastructure disclosures, and central bank digitization mandates. Bottom-up triangulation across bot deployment volumes and top-down cross-reference against banking IT expenditure surveys anchored market sizing.
Historical adoption curves for attended versus unattended automation were cross-referenced against panel input from procurement directors at Tier 1 institutions. Segmentation dimensions modeled include deployment architecture, end-user category, application function, and technology intelligence tier. CAGRs were derived through regression analysis of bot throughput scaling and regulatory compliance cost trajectories. Forecast inputs incorporated EU AI Act implementation timelines and RBI-mandated public sector bank modernization schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation acceleration or hyperscaler capacity constraints. Assumptions reflect steady cloud-native adoption velocity and sustained SEC examination intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Services Cloud Market
FinTech
AI Finance Market
FinTech
Financial App Market
FinTech
Fintech Technologies Market
FinTech
France AI in Fintech Market
FinTech
Automotive Fintech Market
FinTech
Financial Fraud Detection Software Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Canada AI in Fintech Market
FinTech
Asia-Pacific Fintech Market
FinTech
United States Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Stock Trading App Market
FinTech
Malaysia Fintech Market
FinTech
Supply Chain Finance Market