
 Crayfish Market | 2026-2036
Crayfish Market Size, Share, and Industry Trends Forecast 2026-2036
Crayfish Market Analysis
A wide capital-intensity gap between integrated processors and seasonal harvesters is bifurcating competitive dynamics across the crayfish supply chain. Fruge Seafood Company leverages vertical integration from pond to port, sustaining cold-chain dominance across Gulf Coast distribution networks. Louisiana Crawfish Company anchors its position through specialized live-tank logistics, while Riceland Crawfish differentiates via proprietary grading systems that command premium pricing from restaurant buyers.
Crayfish are freshwater crustaceans of the superfamilies Astacoidea and Parastacoidea, typically harvested at 10–15 centimeters in length and processed either live-chilled or blast-frozen within hours of catch to preserve texture and flavor for culinary applications. The frozen segment leads volume throughput due to year-round availability and extended shelf stability, while processed value-added products capture expanding margin pools from food service buyers seeking labor-saving formats. Distribution through restaurants and fish markets retains structural importance for live-product freshness, though online channels are gaining traction among direct-to-consumer households.
USDA grading standards and FDA Hazard Analysis Critical Control Point rules govern interstate commerce and export eligibility, while China's NMPA and GB standards regulate import tolerances for aquaculture residues. These frameworks elevate compliance costs for smaller harvesters but create market access advantages for certified operators with documented chain-of-custody systems. Stakeholders must weigh traceability investments against emerging biosecurity protocols that could reshape sourcing geography and processing location decisions.
Market Dynamics
Cold-chain infrastructure gaps between integrated processors and seasonal harvesters are fragmenting competitive dynamics across the crayfish supply chain, forcing capital-light operators toward contract processing arrangements or exit.
Growth Catalysts
- Food service procurement:Frozen and processed crayfish procurement is accelerating across North American and European restaurant chains seeking premium menu differentiation.
- China's NMPA traceability mandates:Export-grade cold-chain documentation requirements are favoring certified processors with chain-of-custody systems over informal harvesters.
- Louisiana processing corridor concentration:Gulf Coast packaging infrastructure proximity to domestic harvest is shortening farm-to-freezer windows and preserving product grade.
Market Restraints
- Feed input cost volatility:Soybean and fishmeal price swings compress margins for pond operators without forward-contracting capabilities.
- Seasonal supply concentration:Louisiana and Texas harvest windows create annual volume cliffs that strain freezer capacity and working capital cycles.
- Wild-catch regulatory ceilings:State-level harvest quotas on natural waterways limit upstream supply elasticity regardless of downstream demand signals.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online seafood platforms are bypassing traditional fish market intermediaries and capturing margin from freshness-guaranteed live shipments.
- EU Green Deal aquaculture incentives:Carbon-efficient pond system certification is opening preferential access lanes for compliant exporters into European food service.
- Value-added format innovation:Peeled tail meat and seasoned boil-in-bag products are displacing whole-cook commodity sales in time-constrained household segments.
Industry Challenges
- HACCP compliance timeline compression:FDA hazard analysis documentation requirements demand dedicated quality staff that seasonal operators cannot retain year-round.
- Live-tank logistics capex intensity:Oxygenation systems and temperature-controlled transport fleets require capital deployment that harvester cooperatives struggle to syndicate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crayfish Market |
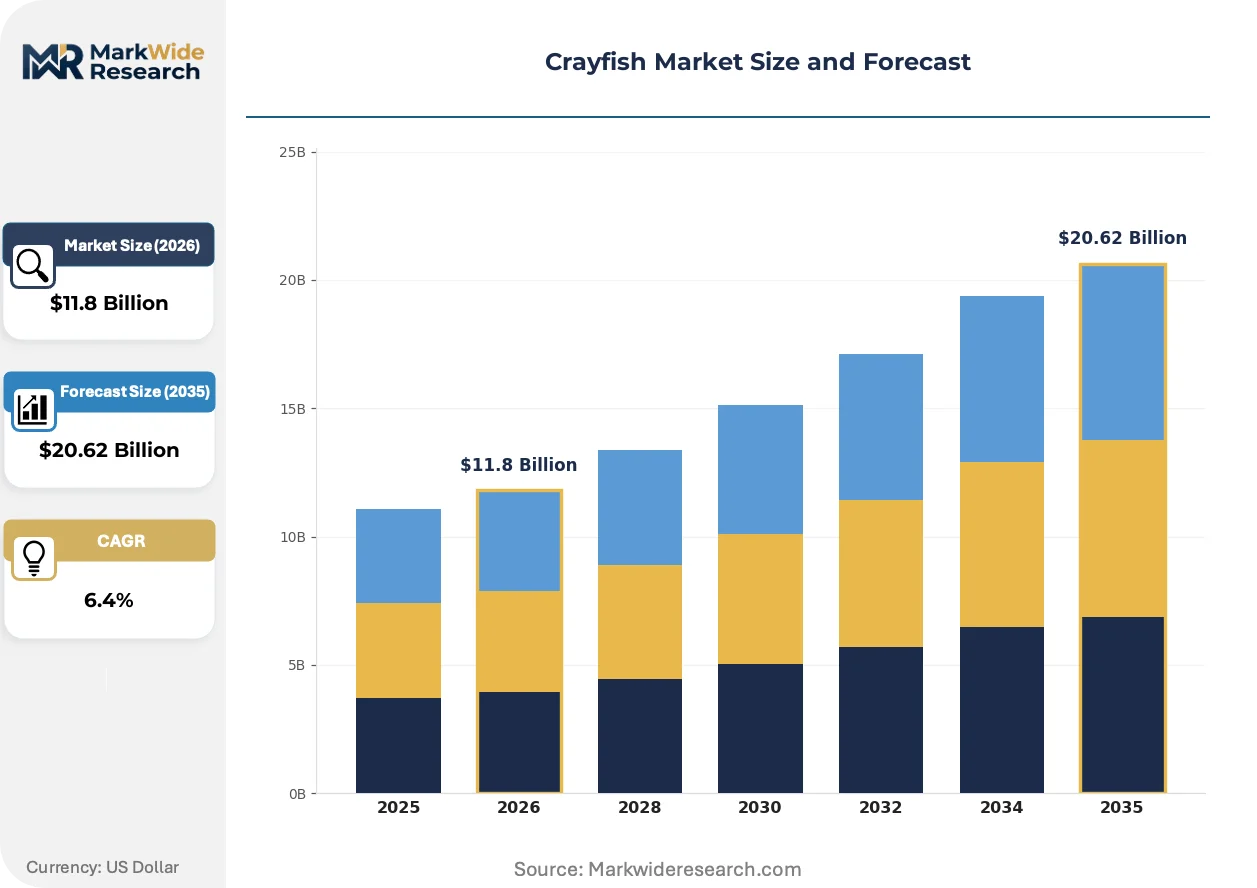
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freshwater, Frozen, Dried, Processed Distribution Channel: Online, Supermarkets, Fish Markets, Restaurants End User: Households, Chefs, Food Service, Retailers Application: Cooking, Export, Aquaculture, Research |
| Companies Covered | Fruge Seafood Company, Mah Protein Inc., Alfocan SA, Live Aquaponics, American Seafoods Group, Louisiana Crawfish Company, Seven Star Ocean Fisheries, Bocage Crawfish, Riceland Crawfish, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crayfish Market Emerging Trajectories
Automation in grading and packaging is compressing labor dependency while biosecurity protocols and channel disintermediation are rewriting how crayfish move from pond to plate.
Hyperspectral imaging systems for real-time shell quality assessment are displacing manual grading tables at Louisiana processing facilities. Mid-scale processors are adopting these units to reduce sorting labor by half and eliminate human error in size classification. The technology is displacing traditional hand-sorting workflows and compressing the premium that manual graders once commanded.
China's NMPA is tightening GB standard residue testing for imported aquaculture, mandating third-party laboratory certification for every export lot. This regulatory friction is elevating compliance costs for smaller harvesters while creating documented competitive moats for integrated operators with in-house testing capabilities. Frozen product exporters to China are responding by consolidating around certified cold-chain partners with pre-clearance relationships.
Restaurant procurement departments are consolidating supplier relationships around single-source frozen contracts with guaranteed year-round availability. This buying-pattern shift is compressing spot-market volumes and favoring processors with captive pond operations or multi-state sourcing networks. The concentration is most visible in Gulf Coast casual dining chains where menu consistency requirements override price sensitivity.
Crayfish Market Segmentation
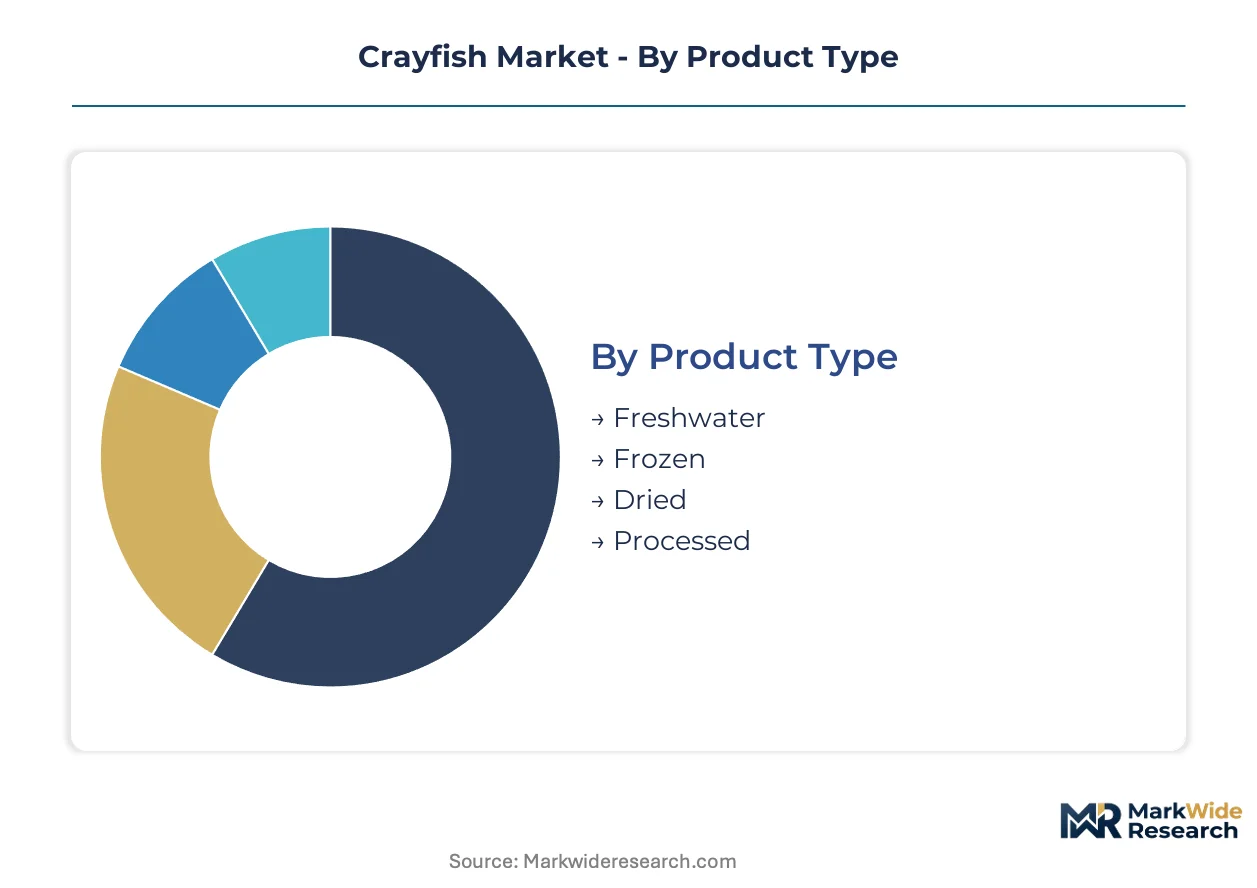
Crayfish segmentation reveals how product format and channel access determine margin capture across the value chain. Each dimension carries distinct substitution pressures from competing crustaceans and alternative protein sources.
Product Type:
Freshwater crayfish face the strongest substitution threat from imported frozen shrimp and domestic crab, forcing format differentiation to defend shelf space.
- Freshwater:Live-chilled product maintains cellular structure through controlled oxygenation and rapid cooling post-harvest. Louisiana processing corridors dominate throughput, though seasonal supply cliffs strain working capital cycles for pond operators without captive freezer capacity.
- Frozen:Blast-frozen whole-cook and tail meat formats extend shelf stability to 18-24 months while preserving texture for food service rethermalization. Year-round availability from integrated processors is displacing live-product procurement at casual dining chains seeking menu consistency.
- Dried:Dehydrated crayfish powder serves flavoring applications in snack seasonings and broth bases, concentrated in Asian import markets with established dried seafood consumption patterns.
- Processed:Peeled tail meat, seasoned boil-in-bag offerings, and value-added seasoned products reduce labor requirements for time-constrained households and commercial kitchens.
Frozen product anchors the volume base while processed formats gain share at the steepest rate.
Distribution Channel:
Channel cost tiers separate capital-intensive cold-chain operators from seasonal harvesters dependent on spot-market intermediaries.
- Online:Direct-to-consumer platforms bypass traditional fish market intermediaries through freshness-guaranteed live shipments with oxygenated packaging. Gulf Coast processors are investing in last-mile cold-chain partnerships to capture household margin pools.
- Supermarkets:Retail frozen seafood cases stock imported and domestic blast-frozen product with standardized grading labels. Chain procurement consolidation favors suppliers with year-round volume guarantees and documented HACCP compliance.
- Fish Markets:Traditional live-tank retail maintains structural importance for freshness-sensitive buyers in coastal Louisiana and Texas communities with established boil culture.
- Restaurants:Food service procurement departments are consolidating around single-source frozen contracts, compressing spot-market volumes and elevating processors with multi-state sourcing networks.
Restaurants anchor the volume base while online channels expand most quickly.
End User:
Customer type determines price tolerance and format preference across household, professional, and institutional buyer segments.
- Households:Time-constrained consumers are shifting from whole-cook commodity purchases toward labor-saving peeled tail meat and seasoned boil-in-bag formats.
- Chefs:Premium restaurant kitchens specify live-chilled product for texture-critical applications, sourcing through specialized logistics operators with documented chain-of-custody systems.
- Food Service:Casual dining chains prioritize frozen product with guaranteed year-round availability over price sensitivity, consolidating supplier relationships around single-source contracts.
- Retailers:Supermarket and fish market operators balance live-tank logistics complexity against frozen product margin stability in category planning decisions.
Food service anchors the volume base while households gain share at the steepest rate.
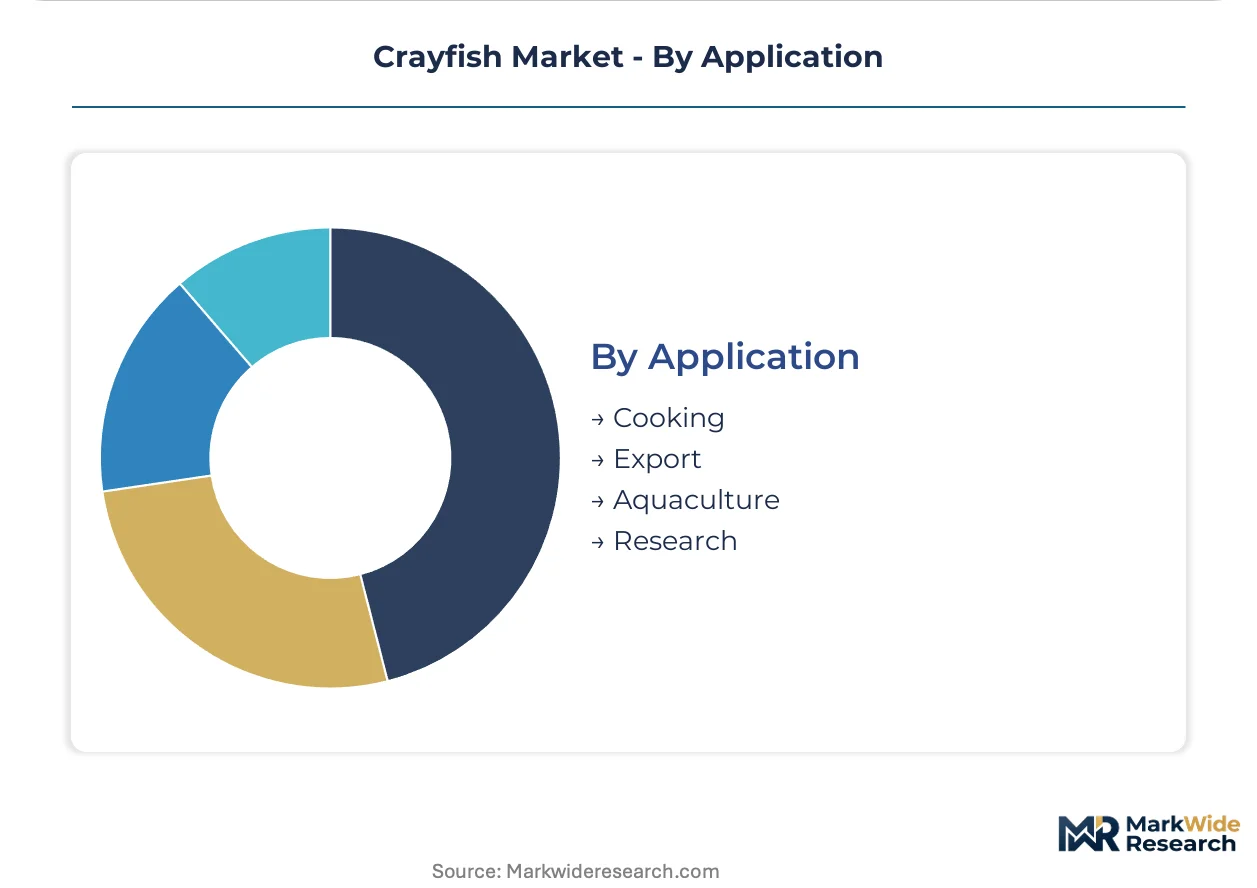
Application:
Application maturity varies from established culinary consumption to emerging research and aquaculture seedstock demand.
- Cooking:Traditional boil preparation and emerging fusion cuisine applications drive domestic consumption concentration in Gulf Coast and Midwest markets with established crayfish culture.
- Export:China's NMPA traceability mandates and GB standard residue testing are elevating compliance costs while creating documented competitive moats for certified processors with in-house laboratory capabilities.
- Aquaculture:Broodstock and seedstock supply supports pond restocking cycles, concentrated among integrated operators with captive hatchery operations.
- Research:Biomedical and ecological research applications utilize crayfish as model organisms for neurobiological and environmental toxicity studies.
Cooking anchors the volume base while export applications expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese food service buyers exhibit the lowest price elasticity for traceability-certified frozen crayfish, while European casual dining chains prioritize year-round availability over origin premiums. Louisiana processors command mid-tier pricing power through Gulf Coast harvest proximity. Spot-market volatility concentrates most acutely among seasonal harvesters without captive cold-chain assets.
United States
Louisiana's processing corridor anchors domestic volume, where pond-to-freezer infrastructure shortens harvest-to-blast-freeze windows below six hours. FDA HACCP documentation requirements and USDA interstate commerce rules govern export eligibility, elevating compliance costs for operators without dedicated quality staff. The Atchafalaya Basin and southwestern Louisiana parishes concentrate integrated processors with captive hatchery and freezer capacity.
China
Import demand from Sichuan and Hubei provincial markets drives premium pricing for residue-tested frozen product with documented cold-chain custody. NMPA GB standard aquaculture residue testing mandates third-party laboratory certification for every export lot, creating competitive moats for certified processors. Shanghai and Guangzhou cold-chain hubs consolidate pre-clearance relationships for compliant exporters.
Sweden
EU Green Deal carbon-efficient aquaculture certification opens preferential procurement lanes for pond operators with documented low-carbon production systems. EFSA import tolerances for aquaculture residues align with REACH chemical documentation requirements for processed seafood. Stockholm and Gothenburg distribution networks channel certified product into Nordic food service and retail frozen cases.
Spain
Mediterranean casual dining chains source frozen tail meat for tapas and paella applications, prioritizing standardized grading over live-product freshness. EU hygiene regulations and national food safety agency protocols govern import documentation for aquaculture products. Barcelona and Valencia port infrastructure handles re-export distribution into North African and Middle Eastern markets.
Australia
Tasmanian and South Australian pond operators serve domestic food service and limited Asian export demand for live-chilled product. TGA-aligned state fisheries regulations and biosecurity protocols govern interstate movement and export certification for aquaculture crustaceans. Melbourne and Sydney cold-chain logistics operators consolidate southern hemisphere supply for hospitality procurement.
Crayfish Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the crayfish supply chain. Integrated processors with captive pond operations and in-house cold-chain assets command premium positioning through documented traceability systems. Seasonal harvester cooperatives compete on spot-market price but lack year-round availability guarantees. The competitive terrain stratifies around three archetypes: vertically integrated Gulf Coast processors, specialized live-tank logistics operators, and regional harvester cooperatives. Dominant competitive moves include backward integration into pond operations and strategic consolidation around certified cold-chain partnerships.
Among integrated processors with geographic naming, Fruge Seafood Company and Louisiana Crawfish Company exemplify Gulf Coast pond-to-port operators with captive supply control. Riceland Crawfish occupies a position within the specialized grading and logistics tier, representing processors that differentiate through quality documentation systems. These three entities anchor the competitive structure visible in company naming patterns, sitting within distinct capability clusters that separate capital-intensive integrated operators from seasonal harvester networks.
| Leading Market Players |
|---|
| Fruge Seafood Company |
| Mah Protein Inc. |
| Alfocan SA |
| Live Aquaponics |
| American Seafoods Group |
| Louisiana Crawfish Company |
| Seven Star Ocean Fisheries |
| Bocage Crawfish |
| Riceland Crawfish |
| Others |
Supply Flow & Price Mechanics
Shrimp substitution in casual dining menus simultaneously redraws sourcing geography toward Gulf Coast pond operations and compresses price premiums for whole-cook commodity formats. Food service buyers trading down to imported frozen shrimp during supply cliffs force crayfish processors to defend margin through value-added differentiation rather than volume discounting.
Pricing Analysis
After-sales service contracts for live-tank logistics and freshness guarantees command lifetime value premiums from restaurant chains. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-certified processors with in-house laboratories from seasonal harvesters and spot-market intermediaries. Cost compression in the economy tier is intensifying because soybean and fishmeal input volatility squeezes pond operators without forward-contracting capabilities. Casual dining chains exhibit lowest price sensitivity due to menu consistency requirements, while household direct-to-consumer buyers show highest elasticity.
Supply Chain Analysis
Port congestion at Gulf Coast export terminals and container availability constraints on the Shanghai-Guangzhou trade lane elevate inbound logistics costs for frozen product exporters. Supply concentrates in the United States, China, and Australia, with raw material dependencies on fishmeal, soybean feed, and oxygenation equipment. Single-source vulnerability around Louisiana's processing corridor creates concentration risk during hurricane season disruptions. Distribution runs through integrated processors with captive cold-chain assets, bypassing traditional fish market intermediaries for food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cold-chain documentation capabilities are scarce relative to export demand, creating a structural advantage for operators with in-house testing and traceability systems. The gap between integrated processors and seasonal harvesters is widening as China's NMPA mandates tighten.
For Market Incumbents: Fortify captive pond operations through backward integration into hatchery capacity, securing broodstock control against wild-catch regulatory ceilings. Invest in hyperspectral grading automation to compress labor costs and defend margin position from mid-scale processors adopting similar technology. Prioritize pre-clearance relationships with Shanghai and Guangzhou cold-chain hubs to lock in China export access before smaller competitors achieve certification. For New Entrants and Emerging Players: Direct-to-consumer freshness-guaranteed live shipments represent the most penetrable service-layer gap, as incumbents under-serve household buyers with complex logistics. Target online seafood platforms with oxygenated packaging partnerships, bypassing traditional fish market intermediaries. Lead with boil-in-bag value-added formats for time-constrained Midwest households outside established Gulf Coast crayfish culture zones. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with documented chain-of-custody systems over capital-light harvester cooperatives. Long-term viability hinges on regulatory compliance moats widening through biosecurity protocol expansion. Target acquisition archetypes include mid-scale Louisiana processors with latent cold-chain capacity and EU Green Deal certification pathway potential. Watch NMPA GB standard enforcement consistency as the signal for export margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hatchery Operations | Captive broodstock supply insulates processors from wild-catch quota restrictions in Louisiana and Texas waterways. |
| Hyperspectral Grading System Deployment | Automation halves sorting labor at Louisiana processing facilities and eliminates human error in size classification. |
| EU Green Deal Aquaculture Certification | Carbon-efficient pond documentation opens preferential procurement lanes into Nordic food service and retail frozen cases. |
| Direct-to-Consumer Channel Expansion | Online platforms with oxygenated packaging capture household margin pools bypassing traditional fish market intermediaries. |
| Pre-clearance Partnership with China Cold-chain Hubs | Shanghai and Guangzhou logistics relationships streamline NMPA GB standard residue testing documentation for export lots. |
Methodological Framework
The analysis maps freshwater, frozen, dried, and processed crayfish sub-sectors, each validated through pond operators, processing facility managers, food service procurement directors, and cold-chain logistics specialists. Primary interviews with Louisiana and Gulf Coast industry stakeholders combined with secondary validation from FDA HACCP guidance documents, USDA interstate commerce regulations, China's NMPA GB standards, and EU EFSA aquaculture residue tolerances. Bottom-up volume modeling across product formats triangulates against top-down value estimates from trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including product type, distribution channel, end user archetype, and application use case, with geographic regulatory cluster as an additional crayfish-specific dimension. CAGRs were derived from trend extrapolation adjusted for input cost volatility and regulatory compliance timeline compression. Forecast inputs include feed price indices, freezer capacity utilization rates, and NMPA enforcement intensity proxies.
Material uncertainties — biosecurity protocol expansion, climate disruption to Louisiana harvest windows, and NMPA standard revision cycles — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and input cost normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Shellfish Extract Market
Seafood
Fish Protein Concentrate Market
Seafood
Seafood Extracts Market
Seafood
Sea Biscuits Market
Seafood
Fish Nutrition Market
Seafood
Milkfish Market
Seafood
Japan Frozen Seafood Market
Seafood
Octopus Market
Seafood
United States Lobster Market
Seafood
United States Frozen and Canned Seafood Market
Seafood
Fish Oil Market
Seafood
Surimi by-Product Market
Seafood
Tuna Fish Market
Seafood
China Crustaceans Market
Seafood
Asia-Pacific Shrimp Market
Seafood
Latin America Salmon Market