
 File Analysis Software Market | 2026-2036
File Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
File Analysis Software Market Analysis
The capability gap between cloud-native architectures and legacy on-premise stacks is unwinding competitive dynamics across the file analysis software landscape. Varonis leverages deep metadata extraction and behavioral analytics to sustain technology leadership in data governance. Dell Technologies anchors enterprise credibility through integrated hardware-software bundles that dominate large-scale deployment cycles. IBM competes via Watson-powered cognitive classification engines that extend into regulated verticals.
File analysis software encompasses platforms that scan, classify, and generate actionable intelligence from distributed unstructured data repositories using content inspection engines, metadata harvesting, and policy-driven automation workflows. These systems serve primary commercial purposes including storage cost reduction, regulatory compliance verification, and security risk exposure mitigation across petabyte-scale environments. Cloud-based deployment now leads revenue contribution as enterprises abandon capital-intensive data center footprints, while security analysis solutions command premium pricing due to escalating breach notification obligations under GDPR and state privacy laws. The compliance management feature set is maturing fastest as financial services and healthcare buyers mandate audit-ready lineage tracking.
FDA 21 CFR Part 11, HIPAA Security Rule, and GDPR Article 30 impose structured data inventory requirements that directly shape product roadmaps and procurement criteria for file analysis vendors. The SEC's cybersecurity disclosure rules are forcing publicly traded software buyers to adopt continuous monitoring capabilities that integrate with governance dashboards. Stakeholders must evaluate whether vendor consolidation or specialized point solutions offer superior adaptability as regulatory fragmentation intensifies across federal and state jurisdictions.
Market Dynamics
The migration from on-premise data centers to cloud-native architectures is restructuring procurement patterns and vendor selection criteria across the file analysis software landscape.
Growth Catalysts
- HIPAA Security Rule mandates:Healthcare organizations in the United States face audit-ready data inventory requirements that accelerate platform deployment timelines.
- GDPR Article 30 record-keeping obligations:European enterprises must maintain detailed processing records, driving automated classification engine adoption.
- Petabyte-scale unstructured data proliferation:Financial services firms generate massive document volumes that exceed manual governance capacity.
Market Restraints
- Cloud egress cost volatility:AWS, Azure, and Google Cloud data transfer fees create unpredictable total cost of ownership calculations for multi-terabyte environments.
- On-premise technical debt:Legacy NAS and SAN architectures lack API accessibility for modern metadata extraction engines.
- State privacy law fragmentation:Divergent requirements across California, Virginia, Colorado, and Connecticut complicate single-platform compliance strategies.
Strategic Opportunities
- India's digitization push:RBI data localization mandates and enterprise cloud adoption create first-mover positioning for file analysis vendors.
- AI-powered sensitive data discovery:Large language models trained on compliance patterns enable autonomous policy enforcement without rule-based configuration.
- Managed service provider channels:MSPs seek white-label file analysis capabilities to embed governance into multi-tenant security stacks.
Industry Challenges
- Data science talent scarcity:Behavioral analytics implementation requires rare expertise in both statistical modeling and regulatory interpretation.
- Integration complexity:SIEM and SOAR platform connectivity demands custom API development that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | File Analysis Software Market |
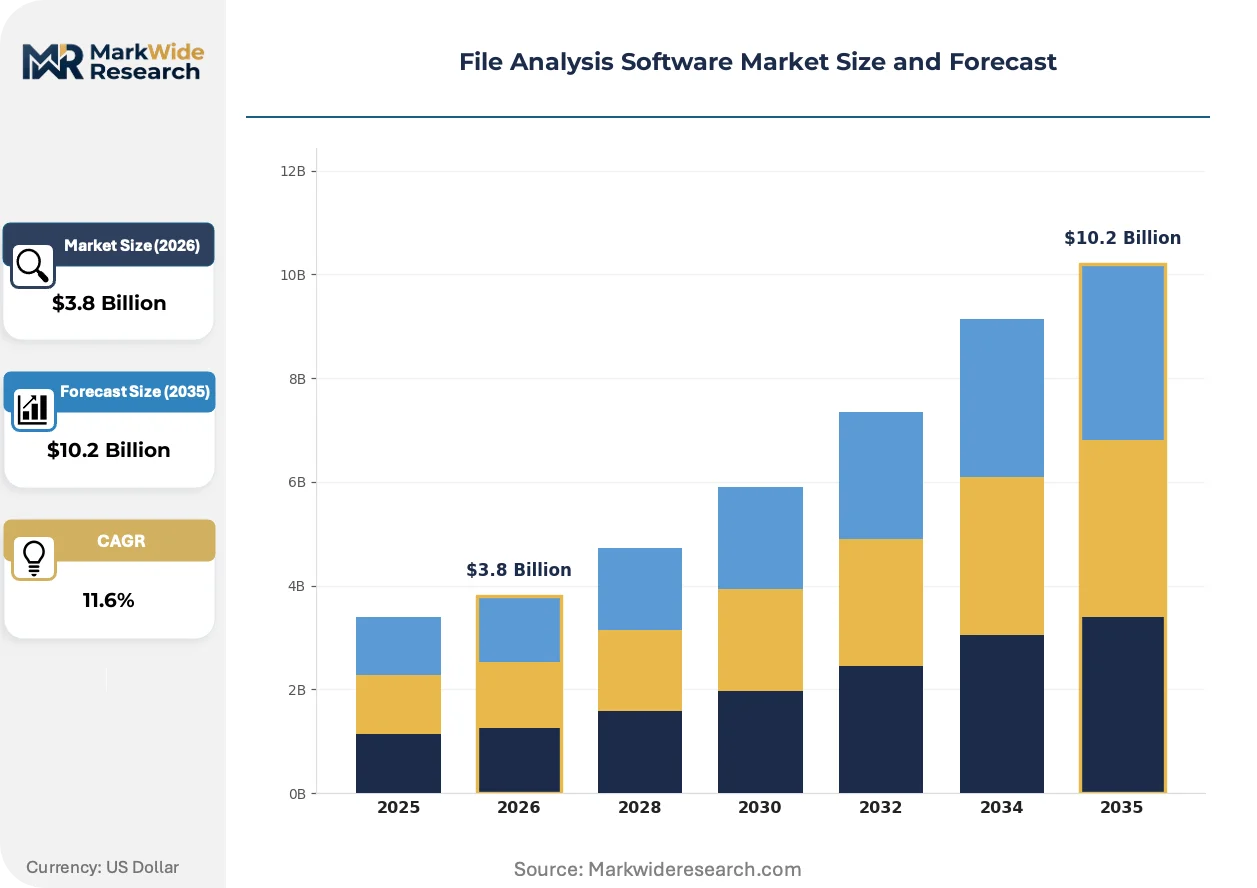
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
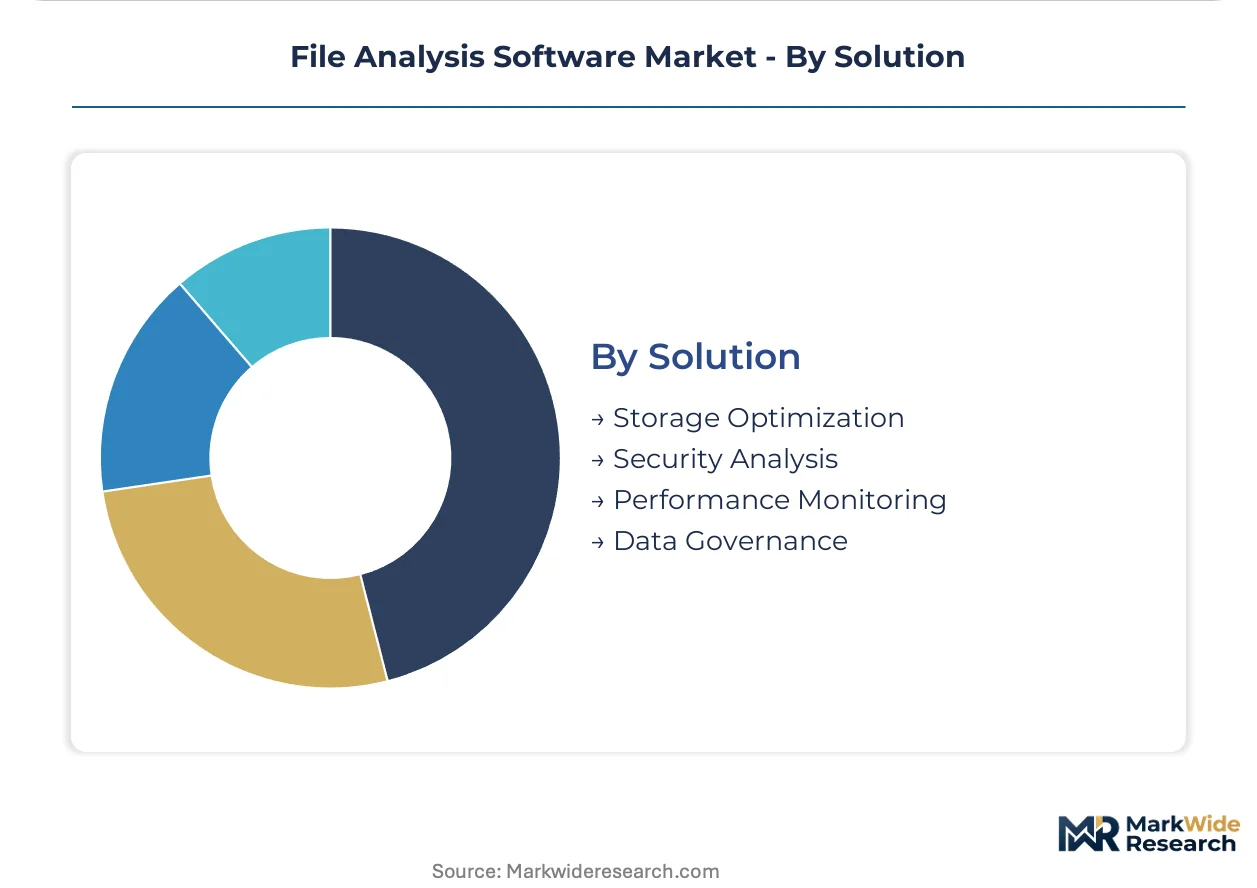
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Healthcare, Education, Retail, Financial Services Feature: Data Visualization, Reporting, Compliance Management, Automation Solution: Storage Optimization, Security Analysis, Performance Monitoring, Data Governance |
| Companies Covered | Cisco Systems, Dell Technologies, International Business Machines Corporation, Varonis, OpenText, Securiti, Ground Labs, Formpipe Software, ActiveNav, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
File Analysis Software Market Emerging Trajectories
Agentic AI architectures and real-time streaming classification are compressing the latency between data creation and policy enforcement across enterprise environments.
Neural classification engines trained on regulatory document corpora are displacing rule-based pattern matching in sensitive data discovery workflows. Healthcare and financial services buyers in the United States are deploying these systems for pre-access scanning of patient records and trading communications. The displacement of deterministic regex engines is collapsing false-positive rates and reducing manual tuning overhead.
GDPR enforcement actions by CNIL and other European data protection authorities are mandating demonstrable data minimization practices. Organizations must prove deletion of personal data beyond retention periods, forcing investment in automated lifecycle management. German automotive and French luxury goods sectors are prioritizing platforms with immutable audit logs and cryptographic proof of erasure.
Enterprise buyers are consolidating vendor relationships through integrated data security platforms rather than standalone point solutions. CISO procurement teams favor suites combining file analysis, access governance, and threat detection over best-of-breed architectures. This preference shift is most pronounced among Fortune 500 manufacturers with complex multi-cloud footprints and limited security operations staffing.
File Analysis Software Market Segmentation
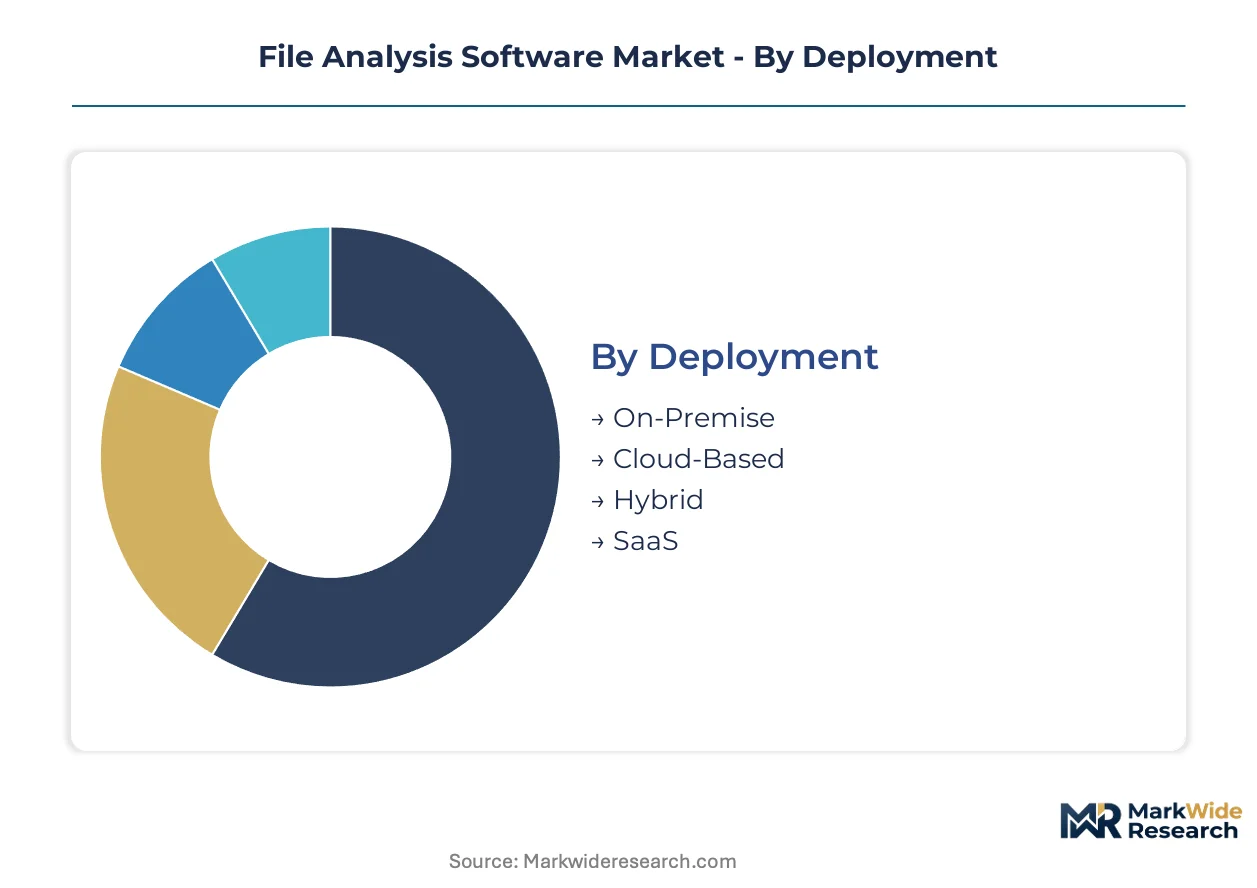
Segmentation in file analysis software reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and operational scale. Buyers select deployment models and feature sets based on data residency requirements, while end-user verticals drive specialized compliance workflows.
Deployment:
Domestic procurement concentrates in cloud-native and SaaS configurations, while hybrid and on-premise deployments persist in regulated sectors with data sovereignty constraints.
- Cloud-Based:Multi-tenant architectures with API-first metadata extraction dominate North American enterprise adoption. Healthcare systems in the United States favor this model for HIPAA-compliant patient data lakes, though AWS and Azure egress fees create total-cost uncertainty at petabyte scale.
- On-Premise:Air-gapped installations with localized classification engines serve defense contractors and critical infrastructure operators. German automotive manufacturers and French aerospace clusters mandate these configurations under GDPR Article 32 security requirements and national cyber defense protocols.
- Hybrid:Tiered architectures place sensitive indices on-premise while archiving cold data to cloud object storage. Financial services firms in Switzerland and Singapore deploy this model for trading record retention with jurisdictional flexibility.
- SaaS:Fully managed subscriptions with pre-trained compliance templates accelerate time-to-value for mid-market buyers. India's digitizing enterprises and Brazil's growing fintech sector represent concentrated demand for low-touch deployment.
Cloud-Based holds the largest share; momentum sits with Hybrid configurations as sovereignty requirements harden.
End User:
Cost tier stratification separates enterprise-grade governance investments from departmental point solutions across buyer categories.
- Healthcare:HIPAA Security Rule and FDA 21 CFR Part 11 mandates drive continuous monitoring of unstructured patient records. United States hospital systems deploy pre-access scanning for clinical trial data and insurance documentation, with audit-ready lineage tracking as non-negotiable procurement criteria.
- Financial Services:SEC cybersecurity disclosure rules and GDPR Article 30 obligations force real-time classification of trading communications and client portfolios. Swiss private banks and London trading desks prioritize platforms with immutable audit logs and cryptographic deletion proof.
- Retail:Customer transaction archives and loyalty program databases require automated lifecycle management. European fashion houses under CNIL enforcement pressure invest in data minimization workflows for consumer profiling records.
- Education:FERPA compliance and research data governance shape procurement for student information systems. United States universities with federal grant portfolios mandate export control classification for sensitive research outputs.
Financial Services commands premium pricing; Education represents the steepest expansion trajectory as research data volumes compound.
Feature:
Application maturity varies sharply, with compliance automation advancing fastest while visualization capabilities commoditize.
- Compliance Management:Automated policy enforcement engines with regulatory rule libraries dominate RFP requirements. Healthcare and financial buyers in the United States mandate pre-configured HIPAA, SOX, and GDPR workflow templates with zero-code customization.
- Automation:Agentic AI architectures enable autonomous classification without manual rule tuning. German industrial conglomerates deploy these systems for real-time sensitive data discovery across acquired subsidiary networks.
- Data Visualization:Governance dashboards with risk heat-mapping have become table stakes. Mid-market buyers treat this capability as baseline, limiting vendor differentiation.
- Reporting:Scheduled audit exports and executive summary generation serve compliance officer workflows. French and Italian enterprises under CSRD pressure prioritize carbon footprint integration with data storage reporting.
Compliance Management anchors procurement budgets; Automation is climbing the fastest as neural classification displaces regex engines.
Solution:
Volume concentration in security and governance reflects breach notification cost escalation and board-level risk accountability.
- Security Analysis:Behavioral analytics and anomaly detection command premium pricing due to ransomware exposure. United States critical infrastructure operators under CISA guidance deploy continuous access pattern monitoring for insider threat detection.
- Data Governance:Unified metadata repositories with cross-platform lineage tracking serve multi-cloud enterprises. Japanese automotive suppliers and South Korean electronics manufacturers mandate these capabilities for supply chain data transparency.
- Storage Optimization:Automated tiering and deduplication reduce capital expenditure for petabyte-scale environments. Cloud-native buyers treat this as cost-center efficiency rather than strategic investment.
- Performance Monitoring:Latency analytics and throughput optimization support high-frequency data pipelines. Quantitative trading firms in London and Singapore represent niche demand for sub-millisecond classification performance.
Security Analysis captures the largest revenue pool; Data Governance is gaining share fastest as CISOs consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States enterprise buyers who absorb premium security analysis tiers, while Indian mid-market procurement favors SaaS configurations with compressed implementation timelines.
United States
Healthcare systems and financial services firms drive concentrated demand for HIPAA-compliant and SEC-ready governance platforms. FDA 21 CFR Part 11 mandates force audit-ready data inventory systems into clinical trial operations. Hospital networks in the Boston-Cambridge corridor and trading desks in Manhattan represent the densest deployment clusters for continuous monitoring capabilities.
Germany
Automotive manufacturers and industrial conglomerates mandate air-gapped installations with localized classification engines for sensitive design data. GDPR Article 32 security requirements and national cyber defense protocols shape procurement specifications. The Stuttgart automotive cluster and Munich aerospace corridor anchor demand for immutable audit logs and cryptographic deletion proof systems.
United Kingdom
Financial services regulatory pressure from the Prudential Regulation Authority accelerates real-time classification adoption for trading communications. FCA operational resilience requirements force investment in automated lifecycle management for client portfolios. London trading desks and Edinburgh fintech clusters prioritize platforms with cross-border data lineage tracking for EU market access.
India
Enterprise digitization and RBI data localization mandates create first-mover positioning opportunities for cloud-native vendors. Mid-market buyers in Bengaluru and Hyderabad favor fully managed SaaS subscriptions with pre-trained compliance templates. The Mumbai financial district drives demand for automated policy enforcement without extensive professional services engagement.
Japan
Automotive suppliers and electronics manufacturers mandate unified metadata repositories for supply chain data transparency. METI cybersecurity guidelines and export control classifications shape procurement for research-intensive operations. The Nagoya automotive corridor and Osaka electronics cluster represent concentrated demand for multi-cloud governance with jurisdictional flexibility.
File Analysis Software Market Vendor Landscape
Concentration sits with integrated platform vendors who bundle file analysis into broader data security suites. The vendor base spans three distinct tiers: infrastructure incumbents with hardware-software bundles, pure-play specialists with deep metadata extraction capabilities, and cloud-native entrants with API-first architectures. Competitive dynamics center on M&A activity consolidating point solutions into unified suites and strategic partnerships embedding governance capabilities into managed security service offerings.
Within the infrastructure-anchored tier, Dell Technologies and Cisco Systems occupy positions defined by enterprise credibility and integrated deployment cycles. Varonis exemplifies the pure-play specialist archetype with concentrated investment in behavioral analytics and sensitive data discovery engines. IBM represents the cognitive classification approach through Watson-powered systems extending into regulated verticals with complex compliance requirements.
| Leading Market Players |
|---|
| Cisco Systems |
| Dell Technologies |
| International Business Machines Corporation |
| Varonis |
| OpenText |
| Securiti |
| Ground Labs |
| Formpipe Software |
| ActiveNav |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation cycles for enterprise file analysis deployments compress procurement timelines while amplifying vendor pricing power through professional services bundling. Cloud egress fee volatility from AWS and Azure data transfer charges feeds directly into total-cost-of-ownership negotiations, forcing buyers to trade off deployment flexibility against predictable budgeting.
Pricing Analysis
The customization-premium spread separates standard SaaS subscriptions from configured-to-order enterprise implementations by a factor of three to five in annual contract value. Subscription-tiered pricing dominates, with differentiation driven by compliance certification level (HIPAA, GDPR, SOX) and data volume scale. Pricing pressure stems from mid-market SaaS compression as Indian and Brazilian buyers demand compressed implementation timelines without professional services overhead. Healthcare systems in the United States show least price sensitivity due to audit-ready mandate urgency, while education sector procurement exhibits highest elasticity.
Supply Chain Analysis
Inbound logistics costs for specialized hardware appliances face intermittent pressure from port congestion on Asia-Pacific trade lanes serving Japanese and South Korean electronics manufacturers. Software supply chains draw from the United States, India, and Israel for machine learning engineering talent and classification engine development. Single-source vulnerability concentrates in cloud infrastructure dependencies on AWS, Azure, and Google Cloud for multi-tenant deployments. Distribution runs through direct enterprise sales teams and managed service provider channels embedding white-label capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
File analysis software exhibits structural fragmentation as regulatory divergence across HIPAA, GDPR, and state privacy laws creates specialized compliance niches that resist platform consolidation. Enterprise buyers increasingly demand vertical-specific workflow templates rather than horizontal generic capabilities.
For Market Incumbents: Compound platform stickiness through deep integration with SIEM and SOAR security stacks, creating switching cost barriers against cloud-native entrants. Acquire specialized classification engine providers to fill AI-powered sensitive data discovery gaps before neural architectures displace rule-based systems. Prioritize certification maintenance for FDA 21 CFR Part 11 and evolving state privacy mandates to defend enterprise healthcare and financial services accounts.
For New Entrants and Emerging Players: GDPR Article 30 fast-track certification programs in France and Germany open immediate positioning for automated record-keeping engines without incumbent technical debt. Target India's digitizing mid-market with fully managed SaaS configurations pre-trained on RBI data localization requirements. Pursue MSP channel partnerships as the primary go-to-market vector, embedding governance into multi-tenant security service bundles rather than direct enterprise competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as containerized microservices reduce infrastructure overhead relative to legacy on-premise stacks. Acquisition targets should exhibit concentrated behavioral analytics IP and established healthcare or financial services customer concentration with recurring revenue above eighty percent. Watch for CNIL enforcement action intensity as the signal indicating accelerated data minimization technology procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | SIEM and SOAR connectivity addresses CISO consolidation preferences across Fortune 500 manufacturers. |
| Acquisition of Specialist Firm | Neural classification engine providers fill capability gaps as regex systems face displacement. |
| Strategic Partnership | MSP channel embedding accelerates mid-market penetration without direct sales overhead. |
| Product Launch | Agentic AI architectures compress latency between data creation and policy enforcement. |
| Geographic Expansion | India's RBI localization mandates create first-mover positioning for SaaS-native vendors. |
Methodological Framework
Initial hypotheses were tested against primary input from CISOs, IT procurement officers, compliance officers, and MSP channel partners and refined through secondary validation against SEC cybersecurity disclosure filings, HIPAA audit documentation, GDPR enforcement action records from CNIL and other European data protection authorities, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing approaches.
Variance decomposition across deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level adoption curves weighted by compliance mandate enforcement intensity. Forecast inputs incorporated cloud egress fee trajectory assumptions and neural classification engine displacement timelines for rule-based pattern matching.
Decision-makers should treat outputs as directional under sustained regulatory fragmentation and cloud infrastructure concentration assumptions; material deviation in enforcement intensity or hyperscaler pricing would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
B2B Gateway Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Proposal Management Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
K8s Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
CAM Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Human Capital Management Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global App Builder Software Market