
 Global Proposal Management Software Market | 2026-2036
Global Proposal Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Proposal Management Software Market Foresight
Enterprise-grade security certification is bifurcating the competitive landscape into compliant and non-compliant tiers. PandaDoc leverages SOC 2 Type II accreditation to anchor its position in regulated financial services procurement. Deltek sustains dominance through deep specialization in government contracting workflows. RFPIO competes on AI-assisted response automation for high-volume RFP environments.
Proposal management software encompasses cloud-deployed and on-premise platforms that orchestrate document creation, workflow automation, and stakeholder collaboration across complex bidding processes, typically integrating CRM data and template libraries to compress proposal cycle times from weeks to days. The deployment dimension shows cloud-based architectures capturing the bulk of new implementations while hybrid configurations retain traction among defense and intelligence contractors with data sovereignty requirements. Within solution offerings, automation tools command the largest current revenue pool, though analytics software represents the fastest-expanding margin segment as buyers demand win-rate optimization and pipeline forecasting.
FDA 21 CFR Part 11 compliance requirements shape product development for life sciences proposal submissions, while the EU AI Act imposes algorithmic transparency obligations on automated scoring features. The SEC's cybersecurity disclosure rules are forcing financial services adopters to scrutinize vendor data handling practices. Stakeholders must weigh integration depth against compliance overhead when selecting platforms for multi-jurisdictional bidding operations.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are compressing vendor development cycles and forcing compliance-by-design architecture decisions across the proposal management software sector.
Growth Catalysts
- Federal procurement digitization:United States government contracting agencies are mandating automated proposal workflows to accelerate bid evaluation timelines and reduce manual processing overhead.
- GDPR-driven data residency requirements:European enterprise buyers are prioritizing platforms with EU-based infrastructure, creating pull for regional cloud deployment options.
- Natural language processing engines:AI-assisted response generation is compressing RFP turnaround times from weeks to days in high-volume bidding environments.
Market Restraints
- Enterprise security certification costs:SOC 2 Type II and FedRAMP accreditation processes impose six-figure compliance burdens that exclude smaller vendors from regulated sectors.
- Defense contractor data sovereignty requirements:Hybrid deployment mandates among United States intelligence agencies limit pure-cloud platform addressable market.
- Legacy CRM integration complexity:Proprietary API architectures in incumbent salesforce automation systems create switching friction for mid-market buyers.
Strategic Opportunities
- Indian government e-procurement expansion:The country's public sector digitization initiatives under the Digital India program are creating first-mover advantages for localized platform deployments.
- Life sciences submission automation:FDA 21 CFR Part 11 compliance tooling for pharmaceutical proposal workflows represents an underpenetrated vertical with specialized requirements.
- API-first ecosystem convergence:Native integration between proposal platforms and contract lifecycle management tools is opening new revenue pools in legal operations budgets.
Industry Challenges
- AI explainability engineering talent:The scarcity of specialists capable of implementing algorithmic transparency features is delaying EU AI Act compliance roadmaps.
- Cross-border data transfer protocols:Schrems II rulings are forcing vendors to rearchitect cloud infrastructure, consuming engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Proposal Management Software Market |
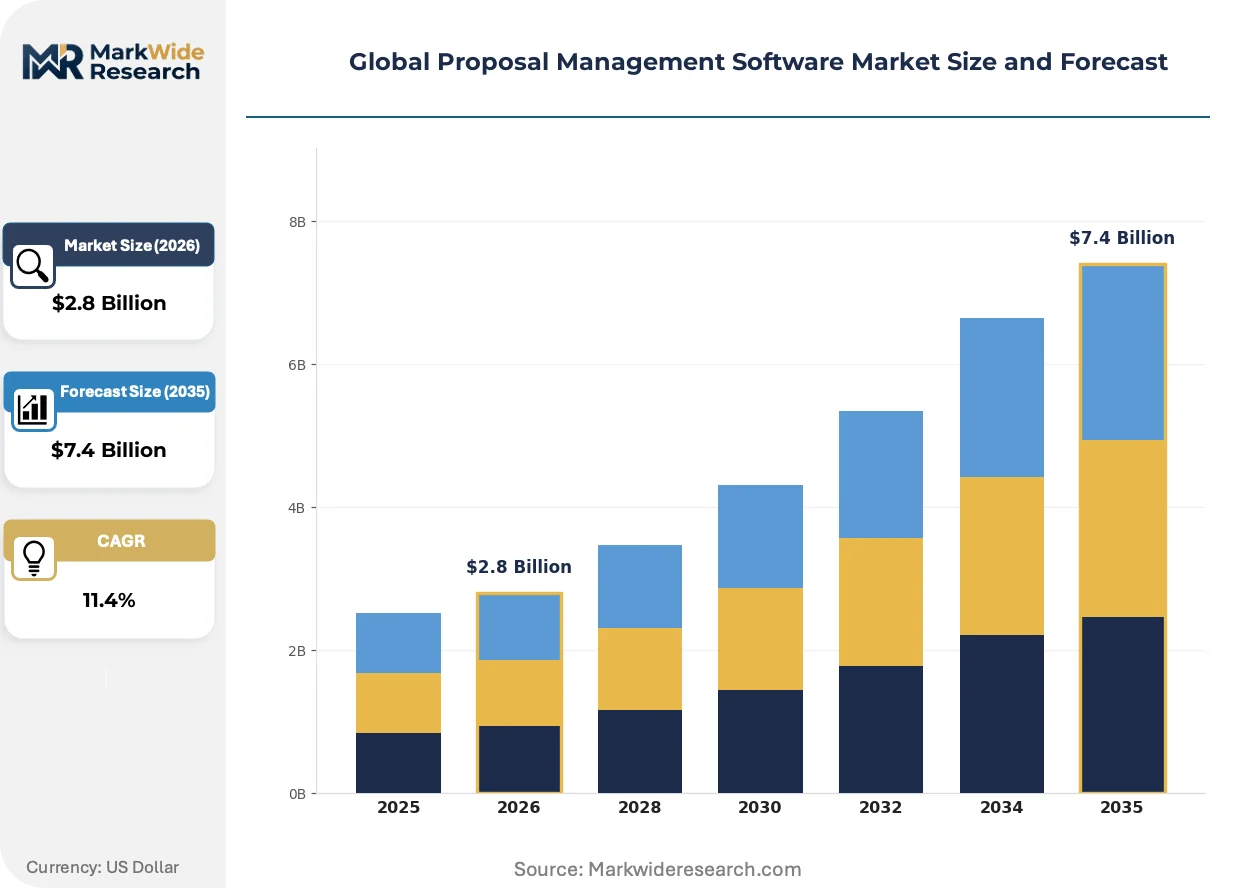
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution Offering: Automation Tools, Collaboration Platforms, Document Management, Analytics Software, Integration Services Use Case: Bid Management, Contract Creation, Client Onboarding, Compliance Tracking, Reporting End User Industry: Consulting Firms, IT Services, Construction, Telecommunication, Financial Services |
| Companies Covered | PandaDoc, Proposify, RFPIO, Deltek, Icertis, Loopio, GetAccept, Microsoft Corporation, Qvidian, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Proposal Management Software Market Shifts & Advancements
Generative AI capabilities are fundamentally restructuring how proposal content is authored, reviewed, and optimized, while regulatory pressure is hardening platform architecture requirements.
Large language model fine-tuning for RFP-specific language is decomposing traditional template-based document assembly. Defense contractors in the United States are piloting these systems for classified proposal drafts with air-gapped deployments. The technology is decomposing the role of dedicated proposal writers into AI supervisors who validate machine-generated outputs.
REACH chemical substance disclosure requirements are spilling into proposal management workflows as European industrial buyers demand supply chain transparency documentation. Vendors must now embed substance tracking modules to maintain platform relevance in EU manufacturing sectors. Chemical and materials science RFPs are most affected, with platforms racing to pre-populate compliance declarations.
Subscription fatigue among enterprise software buyers is compressing vendor evaluation cycles and privileging consolidated procurement suites over standalone proposal tools. Chief procurement officers in financial services are bundling proposal management into broader source-to-pay contracts. This pattern is most visible in London and New York banking headquarters where vendor consolidation mandates have accelerated.
Global Proposal Management Software Market Segmentation
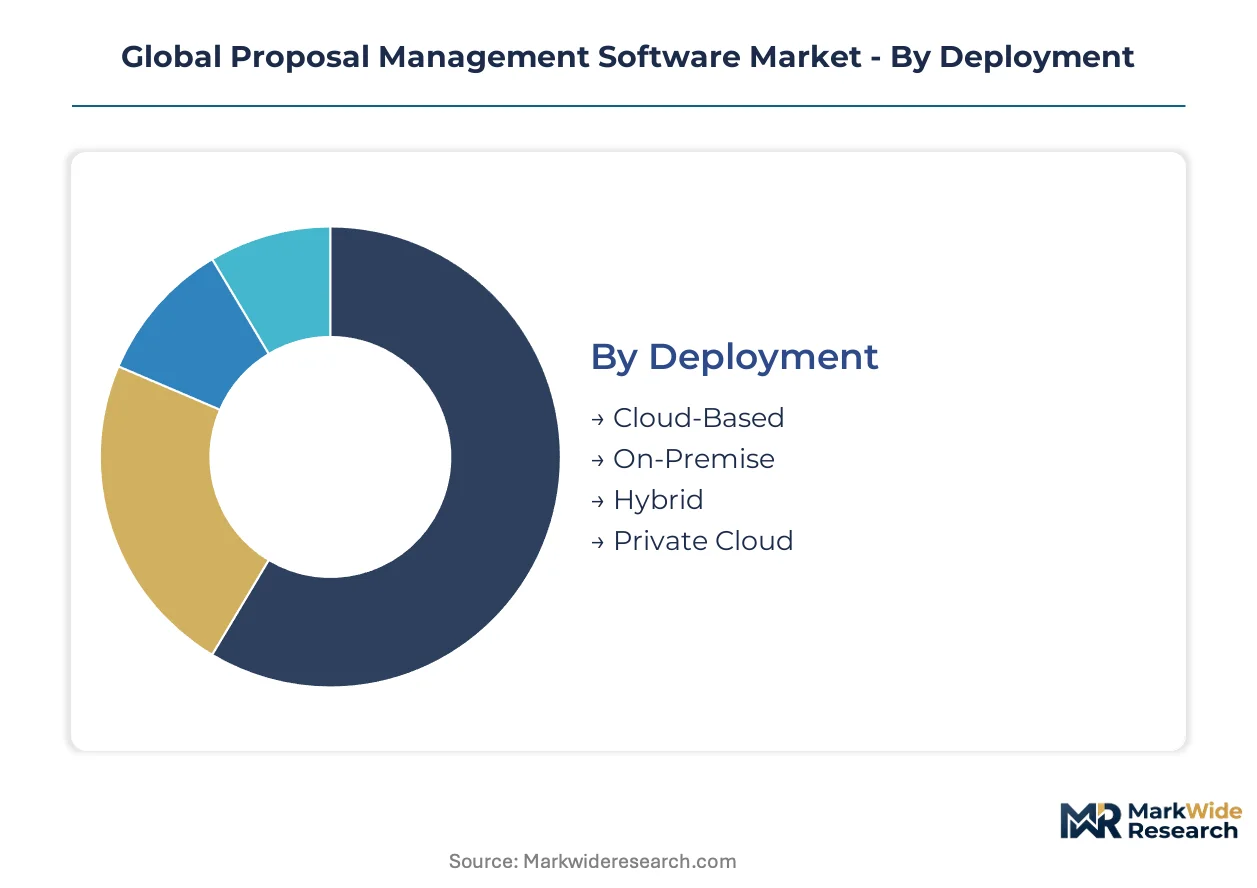
Segmentation in proposal management software reveals how procurement complexity, data sovereignty requirements, and workflow specialization fragment demand across deployment architectures and vertical applications. Buyers select configurations based on regulatory exposure, integration depth, and bid volume intensity.
Deployment:
Geographic demand splits sharply between jurisdictions with strict data residency mandates and those permitting cross-border cloud processing. North American federal contractors drive hybrid adoption, while European financial services concentrate in regional private cloud deployments.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and elastic scaling. United States commercial enterprises dominate consumption, prioritizing rapid deployment over customization depth. The EU AI Act's algorithmic transparency requirements are forcing vendors to embed compliance dashboards.
- On-Premise:Self-hosted installations behind corporate firewalls with full source code control. Defense and intelligence agencies in the United States mandate this mode for classified proposal drafts, accepting higher total cost of ownership for air-gapped security.
- Hybrid:Split configurations with sensitive data on-premise and collaborative tools in cloud. German automotive suppliers and Japanese trading houses favor this for multi-jurisdictional bidding with localized data pools.
- Private Cloud:Single-tenant dedicated instances with vendor-managed infrastructure. Swiss private banking and Singapore sovereign wealth funds select this for GDPR-equivalent privacy with reduced operational burden.
Cloud-Based commands the established base. The steepest expansion runs through Hybrid configurations as cross-border procurement intensifies.
Solution Offering:
Cost tier stratification separates commodity automation from premium analytics, with mid-market buyers bundling capabilities into platform subscriptions.
- Automation Tools:Template-driven document assembly and workflow routing engines. High-volume RFP responders in United States IT services consume these most heavily, compressing turnaround cycles through AI-assisted content generation.
- Collaboration Platforms:Real-time co-authoring environments with role-based access controls. British consulting partnerships and Australian engineering consortia deploy these for distributed bid teams across time zones.
- Document Management:Version control repositories with audit trails and e-signature integration. French public sector contractors require these for procurement law compliance.
- Analytics Software:Win-rate forecasting and pipeline optimization dashboards. Chief revenue officers at United States financial services firms pay premium pricing for predictive bidding intelligence.
- Integration Services:API connectors and custom middleware for CRM and ERP synchronization. Canadian energy sector buyers commission these for Salesforce and SAP harmonization.
Automation Tools anchor current revenue. Analytics Software is climbing the fastest as procurement leaders demand measurable ROI on bid investments.
Use Case:
Application maturity varies from transactional document production to strategic compliance infrastructure, with regulatory pressure elevating tracking and reporting functions.
- Bid Management:End-to-end RFP response orchestration from opportunity identification to submission. United States government contractors treat this as core infrastructure, with FedRAMP certification filtering vendor eligibility.
- Contract Creation:Clause libraries and negotiation playbooks accelerating legal finalization. Dutch multinational trading companies deploy these for standardized international terms.
- Client Onboarding:Proposal-to-implementation handoff automation with stakeholder alignment. Indian IT services exporters use these to compress time-to-revenue for offshore delivery contracts.
- Compliance Tracking:Regulatory requirement mapping and certification deadline management. FDA-regulated life sciences firms in Massachusetts and New Jersey mandate these for 21 CFR Part 11 adherence.
- Reporting:Executive dashboards and audit documentation for procurement governance. German automotive OEM supplier qualification programs require comprehensive bid documentation archives.
Bid Management retains dominant deployment share. Compliance Tracking is gaining share fastest as regulatory fragmentation intensifies across procurement jurisdictions.
End User Industry:
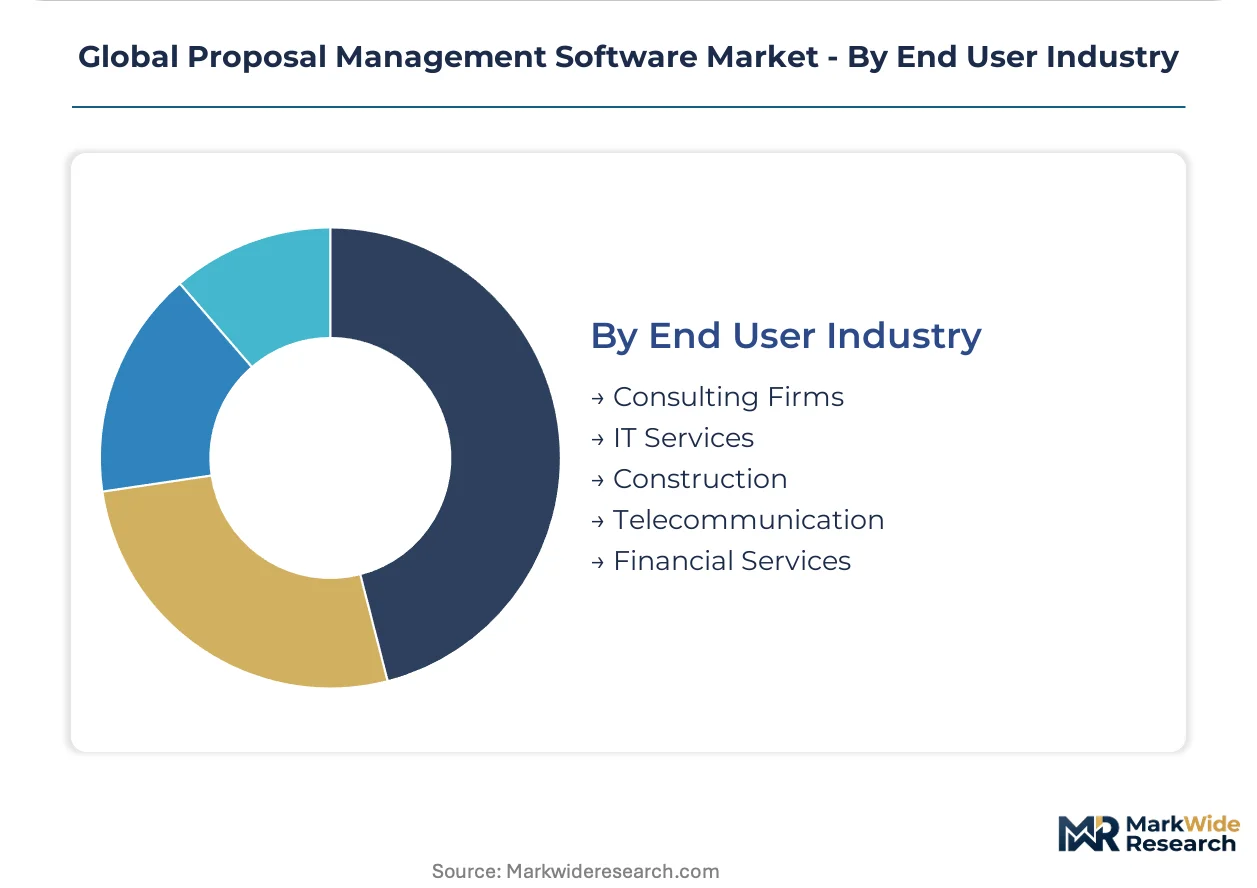
Customer type concentration reflects sector-specific procurement rhythms, with professional services and regulated industries driving platform sophistication requirements.
- Consulting Firms:Partnership-structured organizations with project-based revenue recognition. United States strategy consultancies and British advisory practices standardize on proposal platforms for brand-consistent pitch production.
- IT Services:Outsourcing and systems integration vendors with high bid-to-win ratios. Indian software exporters and Irish technology consultancies consume automation tools most intensively.
- Construction:Project-based contractors with joint venture complexity and bonding requirements. Australian infrastructure consortia and Canadian engineering firms prioritize document control for public-private partnership submissions.
- Telecommunication:Spectrum license applicants and network equipment suppliers with technical specification intensity. South Korean 5G infrastructure vendors and Finnish network equipment manufacturers require specialized compliance modules.
- Financial Services:Asset managers and insurance carriers with fiduciary documentation obligations. Swiss private banks and Singaporean wealth managers select platforms with encrypted data handling and audit-grade transparency.
Consulting Firms represent the most penetrated vertical. Financial Services is expanding most quickly as SEC cybersecurity disclosure rules elevate vendor scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in proposal management software exports, while Germany and the United Kingdom import specialized compliance modules to satisfy EU regulatory mandates. India and Japan represent emerging net importers of automation platforms as domestic procurement digitization accelerates.
United States
Federal procurement digitization drives platform demand across defense contractors and civilian agencies. FedRAMP certification requirements filter vendor eligibility for government contracts. The Washington D.C. metropolitan corridor concentrates implementation activity, with contractors in Northern Virginia deploying hybrid architectures for classified proposal workflows.
Germany
Automotive OEM supplier qualification programs mandate comprehensive bid documentation archives. REACH chemical substance disclosure requirements spill into proposal management workflows for supply chain transparency. Industrial buyers in Baden-Württemberg demand embedded substance tracking modules for compliance declarations.
United Kingdom
Financial services procurement leaders in London bundle proposal management into broader source-to-pay contracts. British consulting partnerships deploy real-time co-authoring environments for distributed bid teams across time zones. The City of London vendor consolidation mandates accelerate platform standardization among asset managers.
India
Public sector digitization initiatives under the Digital India program create first-mover advantages for localized platform deployments. Indian IT services exporters consume automation tools intensively to compress time-to-revenue for offshore delivery contracts. Software services clusters in Bangalore and Hyderabad drive domestic demand for client onboarding automation.
Japan
Trading houses and engineering consortia favor hybrid configurations for multi-jurisdictional bidding with localized data pools. METI industrial policy encourages procurement platform modernization among keiretsu supply chains. Tokyo-based financial institutions select private cloud deployments for GDPR-equivalent privacy with reduced operational burden.
Global Proposal Management Software Market Competitive Landscape
Listed leaders compete with private specialists across security certification tiers, creating a bifurcated structure where compliant and non-compliant vendors serve distinct customer segments. The market stratifies into three strategic archetypes: enterprise-grade platforms with federal accreditation, mid-market automation specialists, and verticalized compliance vendors. Dominant competitive moves include M&A activity to acquire security certifications and strategic partnerships to embed proposal tools into broader source-to-pay suites.
Within the government contracting tier, Deltek occupies a position exemplifying deep specialization in federal workflows. PandaDoc and RFPIO represent contrasting archetypes—PandaDoc anchors the financial services compliance segment through SOC 2 Type II accreditation, while RFPIO exemplifies AI-assisted response automation for high-volume RFP environments. These three vendors collectively illustrate how security certification and workflow specialization determine competitive positioning across regulated sectors.
| Leading Market Players |
|---|
| PandaDoc |
| Proposify |
| RFPIO |
| Deltek |
| Icertis |
| Loopio |
| GetAccept |
| Microsoft Corporation |
| Qvidian |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with hyperscaler cloud providers lock in infrastructure access and price visibility for proposal management vendors serving United States federal contractors. These multi-year commitments insulate platform providers from spot-price volatility in compute and storage while creating switching costs that stabilize customer pricing.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels based on FedRAMP certification status and API integration depth. Premium tiers command substantial markups for SOC 2 Type II and FedRAMP High accreditation, while economy tiers serve mid-market commercial buyers with stripped-down compliance tooling. Pricing pressure stems from subscription fatigue among enterprise software buyers bundling proposal management into broader source-to-pay suites. Chief procurement officers at financial services firms exhibit highest price sensitivity, whereas defense contractors with classified workflow requirements show lowest elasticity.
Supply Chain Analysis
Inventory lead times for GPU clusters and specialized AI training hardware now stretch 18-24 months, forcing vendors to pre-position compute capacity ahead of generative AI feature rollouts. Supply concentrates in United States hyperscaler regions, Irish EU data centers, and Singapore sovereign cloud zones for jurisdictional compliance. Raw material dependencies span NVIDIA H100 accelerators, high-bandwidth memory modules, and encrypted storage arrays. Single-source vulnerability around frontier AI chips creates procurement bottlenecks for algorithmic transparency engineering. Distribution runs through direct enterprise sales teams with embedded solutions architects for complex federal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among chief procurement officers mandating vendor consolidation into integrated procurement suites, fragmenting standalone proposal tool pricing power. This consolidation dynamic elevates platform breadth over point-solution depth in vendor selection criteria.
For Market Incumbents: Shield federal accreditation moats by accelerating FedRAMP High certification timelines before emerging cloud-native entrants achieve compliance parity. Deepen vertical integration into contract lifecycle management tooling to capture legal operations budgets currently allocated to separate vendors. Prioritize API-first architecture investments that embed proposal workflows into incumbent CRM systems, reducing switching friction that favors bundled competitors.
For New Entrants and Emerging Players: Anchor in Indian government e-procurement digitization under the Digital India program, where localized platform deployments face limited incumbent saturation. Target life sciences compliance tracking as the most penetrable vertical, with FDA 21 CFR Part 11 tooling requirements creating specialist openings too narrow for generalist platforms. Pursue partnership-first go-to-market angles with systems integrators holding existing relationships with pharmaceutical quality assurance departments.
For Investors and Strategic Acquirers: Specialist compliance vendors with embedded regulatory expertise represent the most defensible acquisition targets for platform consolidation plays. Long-term viability hinges on algorithmic transparency engineering capabilities that satisfy EU AI Act mandates across the projection horizon. Monitor Schrems II ruling implementations as the critical inflection signal—vendors forced into costly infrastructure rearchitecture will face margin compression that creates distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native CRM connectors reduce switching friction for mid-market buyers evaluating bundled suites. |
| Acquisition of Specialist Firm | Life sciences compliance vendors bring FDA 21 CFR Part 11 expertise that generalist platforms lack. |
| Geographic Expansion | EU data residency deployments capture GDPR-mandated demand from German automotive suppliers. |
| Strategic Partnership | Hyperscaler alliances secure GPU cluster access for generative AI feature development pipelines. |
| Product Launch | Air-gapped deployments for classified proposals unlock United States intelligence agency budgets. |
Research Methodology
Operator-level perspectives from proposal operations directors, federal contracting officers, chief procurement officers, and compliance automation engineers anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation across SEC cybersecurity disclosure filings, FedRAMP authorization databases, EU AI Act regulatory texts, and Digital India program procurement notices. Bottom-up sizing triangulated against top-down market aggregation across deployment models, solution tiers, and end-user industries.
Sensitivity analysis tested forecast robustness against alternative scenarios for federal digitization spending and EU AI Act enforcement timing across the analysis window. Segmentation dimensions modeled encompass deployment architecture, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated baseline estimates, with inputs including government IT modernization budgets, cloud infrastructure capex disclosures, and enterprise software procurement surveys.
Decision-makers should treat outputs as directional under assumptions of sustained federal procurement digitization and stable EU regulatory enforcement; material deviation would warrant model refresh. Specific risks that could revise forecasts include Schrems II infrastructure rearchitecture delays, AI explainability engineering talent scarcity, and hyperscaler pricing volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Game Development Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global Student Information System Market
Software & Services
Software Construction Components Market
Software & Services
Asia Pacific Content Services Platform Market
Software & Services
Lease Accounting and Management Software Market
Software & Services
Open Stack Service Market
Software & Services
Global Linux Operating System Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Virtual Studio Software Market
Software & Services
India Software Services Export Market
Software & Services
Statistics Software Market
Software & Services
Video Converter Software Market
Software & Services
Global Webinar Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Vehicle Embedded Software Market