
 Asia-Pacific Dairy Protein Market | 2026-2036
Asia-Pacific Dairy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dairy Protein Market Outlook
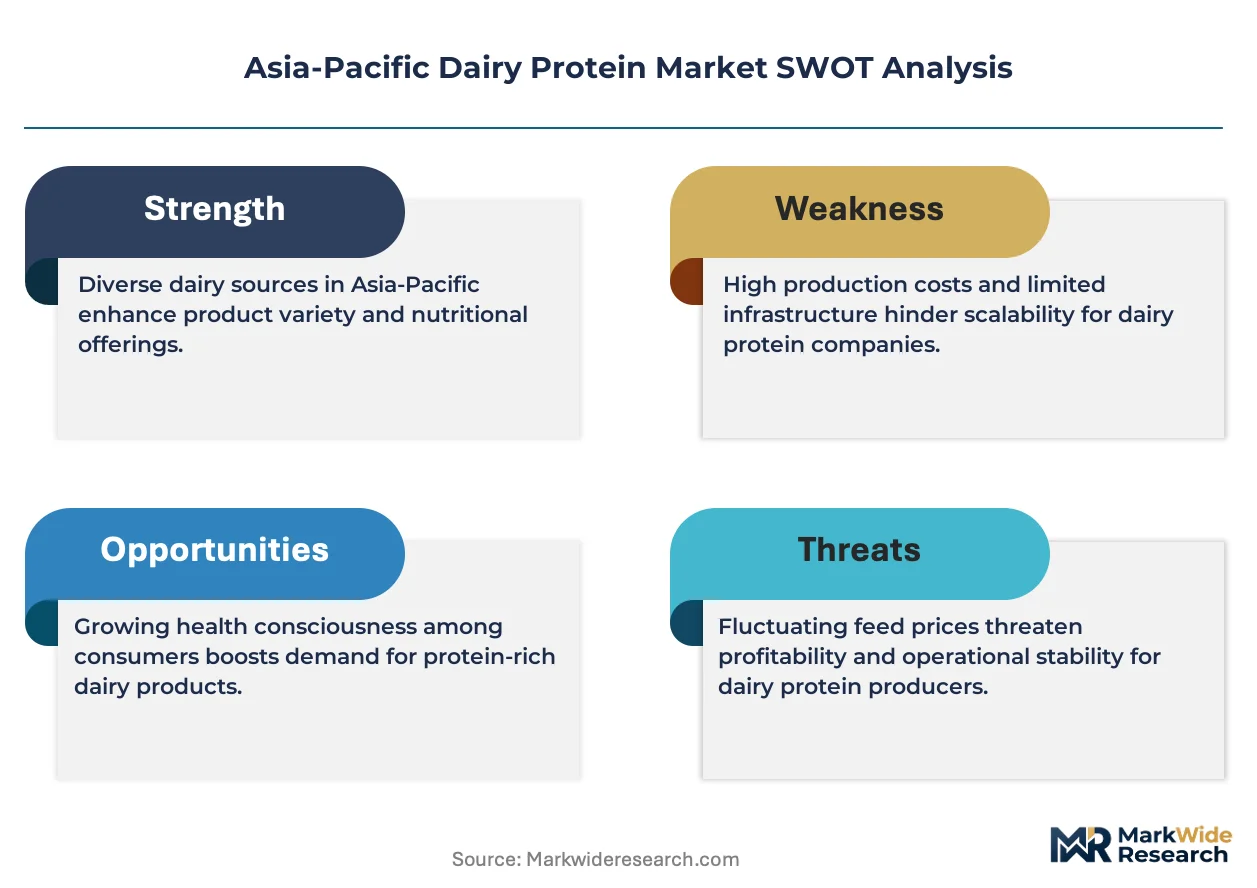
Plant-based protein isolates are recalibrating cost benchmarks for dairy protein formulators across Asia-Pacific. Fonterra Co-operative Group leverages its New Zealand grass-fed milk pool to sustain premium whey concentrate supply chains into Southeast Asian markets. Arla Foods Ingredients Group P/S anchors its position through specialized micellar casein production for medical nutrition applications. Glanbia Nutritionals competes on R&D intensity, operating innovation centers that develop heat-stable protein systems for ready-to-drink formats.
Asia-Pacific dairy protein encompasses whey, casein, milk protein concentrate, and caseinate fractions extracted through membrane separation, ion exchange, or acid precipitation, typically standardized to protein contents ranging from 34% to 90% on a dry basis, serving primarily as functional ingredients for muscle synthesis support, emulsification, and nutritional fortification. Whey protein dominates value contribution due to its superior leucine bioavailability and rapid absorption kinetics favored by sports nutrition brands. Casein protein occupies slower-release positioning in overnight recovery and clinical nutrition segments where sustained amino acid delivery commands formulation premiums. Infant formula applications concentrate demand for milk protein concentrates with specific mineral-adjusted profiles meeting compositional requirements for early-life nutrition.
China's SAMR enforces GB standards for dairy protein labeling and contaminant thresholds that determine factory licensing eligibility for domestic and imported ingredients. Japan's FSSC 22000-aligned dairy manufacturing rules administered under MHLW oversight constrain supplier qualification timelines but reinforce quality differentiation for export-oriented processors. Australia's FSANZ code governs protein content claims and novel ingredient approvals affecting product positioning in functional food channels. Stakeholders must monitor evolving protein origin verification protocols as regional trade agreements incorporate stricter sanitary certification requirements.
Market Dynamics
China's SAMR enforcement of GB standards for dairy protein traceability is forcing ingredient processors to reconfigure supply chain documentation systems ahead of licensing renewal deadlines.
Growth Catalysts
- Sports nutrition formulation expansion:Australian and Japanese functional beverage manufacturers are expanding whey protein procurement for ready-to-drink muscle recovery products.
- Infant formula cluster concentration:Eastern coastal provinces in China host dense processor networks near Shanghai and Jiangsu, creating localized demand pull for milk protein concentrates.
- Membrane separation technology maturation:Advanced ultrafiltration systems are lowering protein fractionation costs for regional dairy processors.
Market Restraints
- Grass-fed milk pool concentration:New Zealand's seasonal supply fluctuations constrain premium whey concentrate availability for Southeast Asian buyers.
- Plant protein substitution pressure:Soy and pea protein isolates are recalibrating cost benchmarks for formulators across Asia-Pacific beverage applications.
- Dual carbon compliance costs:China's MEE carbon intensity targets are elevating energy costs for membrane separation operations in Jiangsu processing zones.
Strategic Opportunities
- Medical nutrition specialization:Micellar casein production for clinical nutrition applications commands formulation premiums in Japan's aging demographic markets.
- Vietnam and Indonesia penetration:Underdeveloped sports nutrition channels in these Southeast Asian markets present first-mover positioning for heat-stable protein systems.
- FSSC 22000 alignment:Japan's MHLW-administered certification requirements create quality differentiation moats for export-oriented processors meeting extended supplier qualification timelines.
Industry Challenges
- Heat-stable protein R&D capability gaps:Ready-to-drink formulation expertise concentrates in specialized innovation centers, limiting regional processor autonomy.
- Mineral-adjusted profile certification delays:Infant formula compositional compliance timelines stretch 18-24 months for new milk protein concentrate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dairy Protein Market |
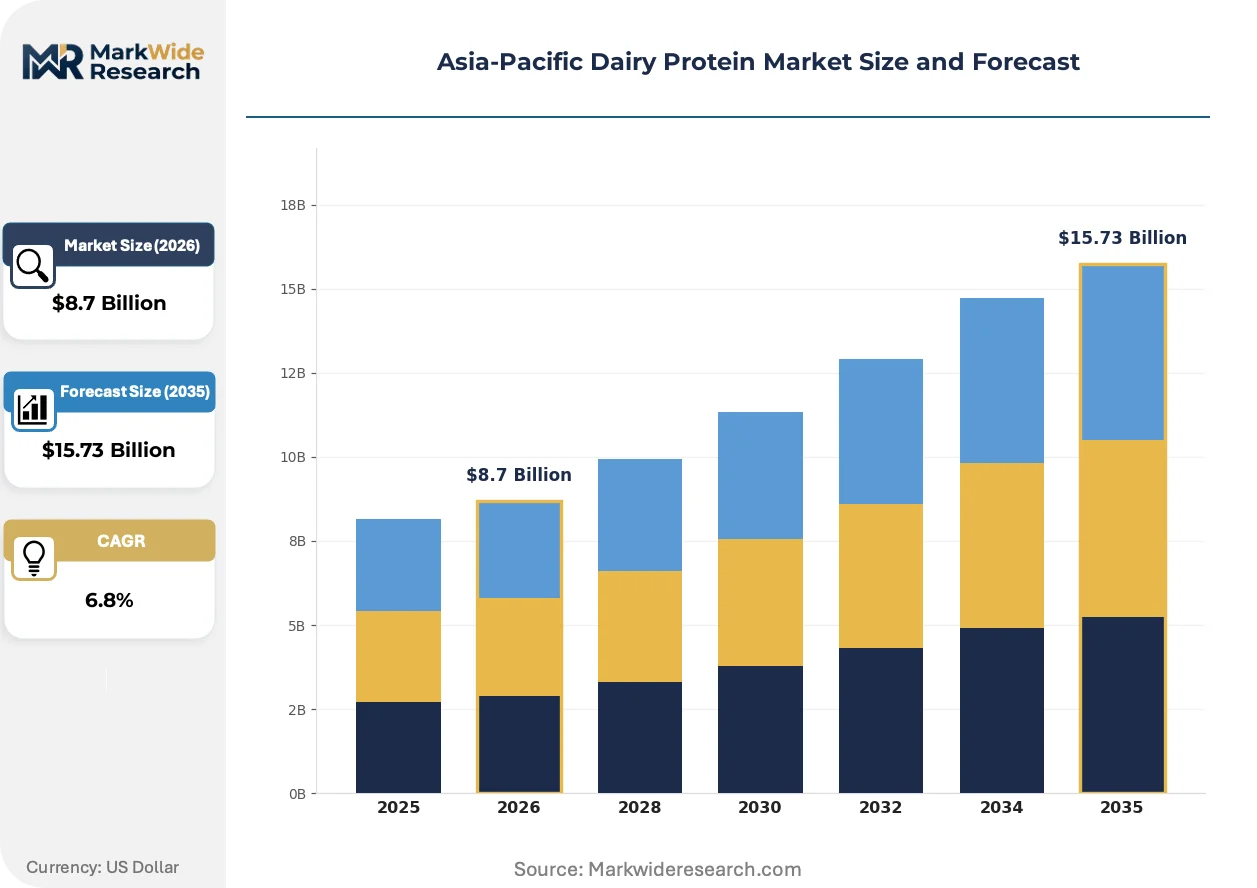
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Caseinates Application: Sports Nutrition, Food & Beverages, Infant Formula, Dietary Supplements End User: Manufacturers, Retail Consumers, Fitness Centers, Healthcare Providers Form: Powder, Liquid, Capsule, Ready-to-Drink |
| Companies Covered | Fonterra Co-operative Group, Arla Foods Ingredients Group P/S, Glanbia Nutritionals, Yili Group, Mengniu Dairy Company, China Feihe Limited, Meiji Holdings Co., Ltd., Hoogwegt, The Tatua Cooperative Dairy Company Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dairy Protein Market Strategic Shifts
Membrane filtration advances and regulatory traceability mandates are compressing traditional processing margins while opening specialized nutrition segments across Asia-Pacific dairy protein value chains.
Cross-flow microfiltration combined with ceramic membrane systems is overtaking conventional spiral-wound polymeric configurations in whey protein isolate production. Australian and New Zealand processors are adopting these systems at replacement cycle pace to achieve 90%+ protein purity with reduced thermal damage. The technology is overtaking legacy ion exchange methods in premium segment positioning by preserving native protein structures for sports nutrition brands.
China's SAMR has tightened GB 28050 nutritional labeling enforcement for dairy protein fortification claims, requiring batch-level origin verification documentation. Domestic and imported ingredient suppliers must now integrate blockchain-tracked supply chain records to maintain factory licensing eligibility. Infant formula processors in Shanghai-Jiangsu clusters are responding by consolidating supplier bases to reduce audit complexity.
Bulk commodity procurement for standard-grade concentrates is fragmenting as sports nutrition brands establish direct toll-manufacturing relationships with New Zealand and Australian processors. This disintermediation is compressing traditional distributor margins in Southeast Asian markets while accelerating customized formulation development cycles. The shift is most visible in Thailand and Malaysia where local brand owners are bypassing regional traders for grass-fed certified whey supply.
Asia-Pacific Dairy Protein Market Segmentation
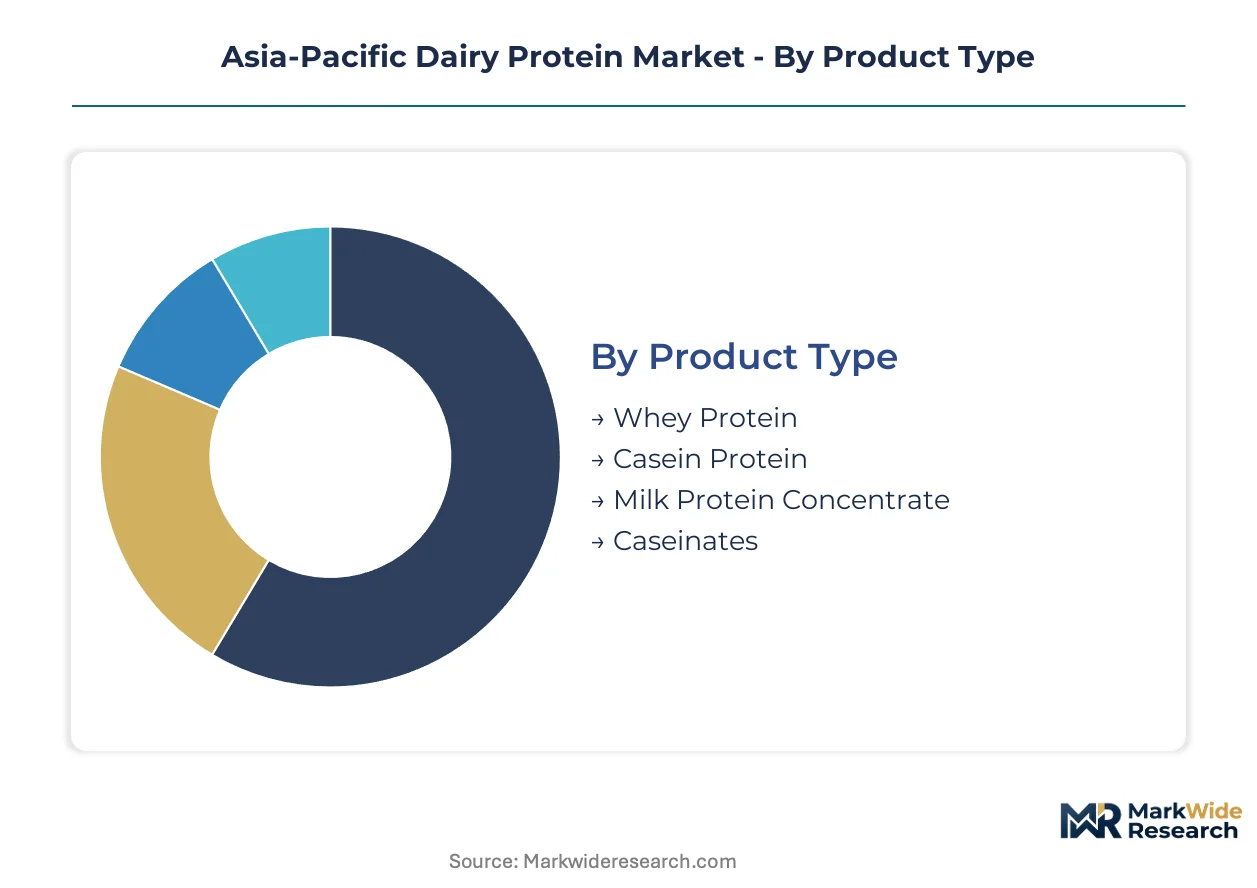
Asia-Pacific dairy protein segmentation reveals how functional requirements, regulatory compliance burdens, and channel economics split demand across distinct buyer profiles. Manufacturers prioritize protein fraction specifications and heat stability certifications, while retail consumers respond to flavor systems and convenience formats.
Product Type:
Buyers differentiate primarily by amino acid kinetics and emulsification properties required for their end formulations.
- Whey Protein:Rapid-absorption protein with superior leucine bioavailability standardized at 80-90% concentration. Sports nutrition brands in Australia and Japan concentrate procurement for ready-to-drink recovery beverages where absorption speed commands formulation premiums.
- Casein Protein:Slow-release micellar structure delivering sustained amino acid plasma elevation over 6-8 hours. Overnight recovery products and clinical nutrition applications in Japan's aging demographic markets absorb regional production from specialized fractionation facilities.
- Milk Protein Concentrate:Combined whey-casein fractions with mineral-adjusted profiles meeting infant formula compositional standards. Shanghai-Jiangsu processor clusters source specific MPC ratios for early-life nutrition compliance.
- Caseinates:Soluble salts of casein protein processed through alkali or calcium treatment for enhanced dispersibility. Southeast Asian beverage manufacturers utilize sodium caseinate for UHT-stable nutritional fortification.
Whey protein leads volumes today; casein protein is gaining share fastest in medical nutrition specialization.
Application:
Channel economics and regulatory stringency separate commercial buyers from consumer-facing brands.
- Sports Nutrition:Functional beverages and powder supplements targeting muscle protein synthesis optimization. Australian formulators expand whey procurement as protein-fortified RTD formats displace traditional powder sachets in convenience channels.
- Infant Formula:Mineral-balanced protein systems requiring 18-24 month certification timelines for new suppliers. Eastern coastal China processors consolidate supplier bases to reduce SAMR audit complexity under tightened GB 28050 traceability mandates.
- Food & Beverages:Emulsification and texture modification in processed dairy, bakery, and confectionery applications. Regional processors specify protein hydrolysates for clean-label positioning in premium positioning tiers.
- Dietary Supplements:Capsule and tablet formats targeting aging populations and clinical nutrition protocols. Japan's MHLW-administered FSSC 22000 alignment constrains supplier qualification but reinforces quality differentiation for export-oriented processors.
Sports nutrition dominates current procurement volumes; infant formula applications are expanding most quickly under China's revised food safety standards.
End User:
Scale requirements and technical capability determine procurement autonomy across buyer categories.
- Manufacturers:Industrial-scale buyers with direct toll-manufacturing relationships and formulation R&D capabilities. New Zealand and Australian processors increasingly bypass regional distributors to serve Thai and Malaysian brand owners directly.
- Fitness Centers:Channel intermediaries bundling protein supplements with membership services and personalized nutrition coaching. Urban centers in Vietnam and Indonesia present first-mover positioning for heat-stable protein system suppliers.
- Healthcare Providers:Clinical nutrition departments prescribing medical foods with sustained-release protein requirements. Japan's hospital networks specify micellar casein for post-surgical recovery and geriatric care protocols.
- Retail Consumers:Individual purchasers prioritizing flavor systems, convenience formats, and grass-fed certification claims. E-commerce platforms in China concentrate demand for blockchain-verified origin documentation.
Manufacturers absorb the largest volume flows; healthcare providers are climbing the fastest as medical nutrition specialization deepens.
Form:
Processing technology requirements and shelf stability economics segment buyers by supply chain sophistication.
- Powder:Spray-dried protein concentrates and isolates with extended ambient stability and flexible reconstitution. Standard-grade commodity procurement fragments as brands establish direct processor relationships.
- Ready-to-Drink:UHT-processed beverages requiring heat-stable protein systems and aseptic filling infrastructure. Innovation centers develop specialized formulations as regional processor autonomy remains limited by R&D capability gaps.
- Liquid:Refrigerated protein concentrates for industrial food manufacturing and beverage fortification. Australian and New Zealand processors deploy ceramic membrane systems to achieve 90%+ purity with reduced thermal damage.
- Capsule:Encapsulated protein isolates for dietary supplement convenience and precise dosing control. Mineral-adjusted profile certification delays constrain new supplier entry into infant formula adjacent segments.
Powder formats retain volume leadership; ready-to-drink applications show steepest expansion trajectory as functional beverage channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Jiangsu processor cluster concentrates Asia-Pacific dairy protein demand through infant formula manufacturing density and SAMR compliance infrastructure. China's eastern coastal provinces anchor procurement volumes for milk protein concentrates with mineral-adjusted profiles. Regional trade flows trace New Zealand grass-fed supply chains into Southeast Asian functional beverage channels.
China
SAMR's tightened GB 28050 traceability mandates force ingredient processors to reconfigure blockchain-tracked documentation systems ahead of licensing deadlines. The MEE's dual carbon intensity targets elevate energy costs for membrane separation operations in Jiangsu processing zones. Shanghai-Jiangsu clusters consolidate supplier bases to reduce audit complexity under infant formula certification protocols.
Japan
Medical nutrition applications absorb micellar casein production for overnight recovery and geriatric care protocols in aging demographic markets. MHLW-administered FSSC 22000 alignment constrains supplier qualification timelines but reinforces quality differentiation for export-oriented processors. Kanto-based hospital networks specify sustained-release protein systems for post-surgical nutrition protocols.
Australia
FSANZ code governance of protein content claims and novel ingredient approvals shapes functional food channel positioning for sports nutrition brands. Toll-manufacturing relationships expand as Thai and Malaysian brand owners bypass regional distributors for direct grass-fed whey procurement. Victorian and New South Wales processors deploy ceramic membrane systems to achieve premium isolate purity with reduced thermal damage.
New Zealand
Seasonal supply fluctuations in grass-fed milk pools constrain premium whey concentrate availability for Southeast Asian buyers. Cross-flow microfiltration adoption accelerates at replacement cycle pace to preserve native protein structures for sports nutrition brands. Canterbury-based cooperatives anchor supply chains into Indonesian and Vietnamese markets through direct brand relationships.
Vietnam and Indonesia
Underdeveloped sports nutrition channels present first-mover positioning opportunities for heat-stable protein system suppliers. Urban fitness center expansion drives demand for ready-to-drink recovery beverages in Ho Chi Minh City and Jakarta metro areas. Local brand owners seek toll-manufacturing partnerships to bypass traditional commodity distributors.
Asia-Pacific Dairy Protein Market Competitive Environment
Global majors compete with regional champions across supply chain control and certification infrastructure. The market structure tiers between scale-driven dairy cooperatives with captive milk pools and specialized ingredient divisions of multinational nutrition groups. Three archetypes dominate: grass-fed supply chain controllers, medical nutrition specialists, and heat-stable formulation developers. Competitive moves concentrate on direct toll-manufacturing relationships and FSSC 22000 certification alignment for Japanese market access.
Within the cooperative archetype, Fonterra Co-operative Group and The Tatua Cooperative Dairy Company Ltd exemplify New Zealand-based milk pool controllers leveraging grass-fed certification for Southeast Asian premium positioning. Among European specialists, Arla Foods Ingredients Group P/S occupies the medical nutrition tier through micellar casein production capabilities. Glanbia Nutritionals represents the R&D-intensive formulation developer archetype with innovation center infrastructure for heat-stable protein systems. Chinese dairy majors Yili Group and Mengniu Dairy Company sit within the domestic market consolidation tier, leveraging SAMR licensing proximity for infant formula supply security.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Arla Foods Ingredients Group P/S |
| Glanbia Nutritionals |
| Yili Group |
| Mengniu Dairy Company |
| China Feihe Limited |
| Meiji Holdings Co., Ltd. |
| Hoogwegt |
| The Tatua Cooperative Dairy Company Ltd |
| Others |
Value Chain & Pricing Dynamics
Grass-fed certification premiums bifurcate procurement economics between New Zealand-sourced whey concentrates and commodity-grade alternatives, compressing distributor margins while rewarding direct toll-manufacturing relationships that bypass traditional Southeast Asian trading layers. This tier divergence concentrates pricing power with Canterbury-based cooperatives holding captive milk pools, while Jiangsu membrane separation operators absorb carbon-compliance cost escalations that feed into contract renegotiations.
Pricing Analysis
Input-cost pass-through from seasonal grass-fed milk pool volatility anchors spot pricing for premium whey protein isolate, with Fonterra and Tatua Cooperative leveraging backward integration into captive supply to defend margin positions against commodity fluctuations. Three-tier pricing structure across grass-fed certified, standard dairy-derived, and plant-protein alternatives stratifies buyer segments, with sports nutrition brands in Thailand and Malaysia exhibiting highest price sensitivity due to direct toll-manufacturing access, while infant formula processors in Shanghai-Jiangsu clusters absorb premiums for mineral-adjusted profile certification. Pricing pressure stems from pea and soy protein isolate substitution in beverage applications, eroding standard-grade concentrate offtake.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-controlled protein concentrate returns remains underdeveloped across Southeast Asian distribution nodes, constraining quality assurance for UHT-ready-to-drink formulations with shortened shelf stability. Geographic supply concentration centers on New Zealand, Australia, and China's eastern coastal provinces, with raw material dependencies tethered to seasonal pasture conditions, ceramic membrane replacement cycles, and SAMR-traceable blockchain documentation systems. Single-source vulnerability concentrates in Canterbury grass-fed milk pools, while distribution runs through direct processor-brand relationships disintermediating regional commodity traders in Thailand, Malaysia, and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific dairy protein procurement functions as a geographic-arbitrage play between New Zealand's grass-fed premium positioning and China's carbon-regulated processing cost base, with MEE dual-carbon intensity targets in Jiangsu elevating energy costs against Canterbury's pasture-dependent supply stability.
For Market Incumbents: Acquire ceramic membrane filtration assets and FSSC 22000 certification infrastructure to defend against plant-protein substitution pressure and Japanese MHLW qualification barriers. Consolidate toll-manufacturing relationships with Vietnamese and Indonesian fitness center channels before heat-stable formulation R&D capability gaps close. Expand backward integration into mineral-adjusted milk protein concentrate production to capture infant formula certification timelines stretching 18-24 months. For New Entrants and Emerging Players: Launch via direct e-commerce platforms targeting Chinese retail consumers demanding blockchain-verified origin documentation, bypassing traditional distributor layers compressed by grass-fed premium bifurcation. Penetrate Vietnam and Indonesia sports nutrition channels where urban fitness center expansion outpaces heat-stable protein system supply. Position on micellar casein specialization for Japan's aging demographic medical nutrition protocols, exploiting extended MHLW supplier qualification timelines as defensive moats. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR traceability mandates and MEE carbon compliance costs fragment Jiangsu processing capacity, creating acquisition targets among mineral-adjusted profile specialists lacking direct brand relationships. Long-term viability favors operators with captive grass-fed milk pools and FSSC 22000 alignment for Japanese hospital network access. Monitor SAMR licensing renewal deadlines and blockchain documentation system deployment rates as inflection indicators for supplier base consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Toll-Manufacturing Expansion | Bypasses compressed Southeast Asian distributor margins while accelerating customized formulation cycles for Thai and Malaysian brand owners. |
| Ceramic Membrane System Deployment | Preserves native protein structures for sports nutrition brands, achieving 90%+ isolate purity with reduced thermal damage. |
| FSSC 22000 Certification Alignment | Unlocks Japanese MHLW-administered market access through extended supplier qualification timelines reinforcing quality differentiation. |
| Blockchain Traceability Integration | Satisfies SAMR GB 28050 batch-level origin verification requirements maintaining factory licensing eligibility for infant formula supply. |
| Medical Nutrition Specialization | Captures formulation premiums in Japan's aging demographic markets through micellar casein production for overnight recovery protocols. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sports nutrition formulators, infant formula procurement managers, membrane separation plant engineers, and SAMR compliance officers with secondary validation through customs trade databases, FSANZ code filings, and FSSC 22000 certification registries. Bottom-up protein fraction shipment data triangulated against top-down dairy cooperative production disclosures across the analysis window.
Comparable-period anchoring linked historical whey and casein price series to forward projection assumptions, modeling volume and value trajectories across product type, application, end user, and form segmentation dimensions. CAGRs derived from regression-adjusted growth rates incorporating membrane technology maturation curves, regulatory compliance cost escalations, and plant-protein substitution elasticity parameters specific to Asia-Pacific beverage formulation channels.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAMR enforcement intensity shifts, New Zealand pasture condition volatility, and MEE carbon target acceleration. Practitioners should monitor blockchain documentation system adoption rates, ceramic membrane replacement cycles, and Japanese hospital network micellar casein specification changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Casein Market
Dairy Products
Dairy Protein Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
North America Sour Cream Market
Dairy Products
Global Milk Protein Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Germany Milk Protein Market
Dairy Products
White Cheese Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Organic Milk Market
Dairy Products
Africa Yogurt Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Whipping Cream Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
South America Yogurt Market
Dairy Products
Low Temperature Yogurt Market