
 Clear Pouches Market | 2026-2036
Clear Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Clear Pouches Market Outlook
Modular pouch configurations with integrated zipper and spout features is consolidating buyer preference across fresh and frozen food categories. Amcor plc leverages its global film extrusion network to sustain cost advantages in high-clarity polyethylene laminates. ProAmpac Intermediate, Inc. anchors its position through specialized retort-compatible clear structures for ready-meal applications. Berry Global Group Inc. differentiates via vertical control from resin compounding to finished pouch conversion.
Clear pouches are transparent flexible packaging structures manufactured from mono- or multi-layer polymer films, typically 2-7 mils thick, with oxygen transmission rates engineered between 0.5 and 10 cc/m²/day depending on barrier requirements. These configurations serve primary functions of product visibility, shelf-life extension, and portion-controlled dispensing across retail and institutional channels. Stand-up pouches command premium positioning in the food industry due to superior shelf presence and reduced material intensity versus rigid alternatives. Zipper closure types are gaining share in retail snack and pet food segments where resealability drives repeat purchase behavior. Biodegradable films remain nascent but occupy strategic importance for cosmetics brands targeting regulatory thresholds in the EU Green Deal framework.
FDA food contact substance notifications govern material composition for US-bound clear pouch imports, while EFSA migration limits enforce stricter extractable thresholds for European market access. The EU Packaging and Packaging Waste Regulation, alongside state-level extended producer responsibility laws in California and New York, is reshaping design-for-recycling mandates. Stakeholders must monitor evolving mono-material specifications and chemical recycling infrastructure investments to align product development with compliance trajectories.
Market Dynamics
Mono-material specifications mandated by the EU Packaging and Packaging Waste Regulation are forcing converters to re-engineer multi-layer clear pouch structures without sacrificing optical clarity or barrier performance. This regulatory compression is reshaping R&D allocation across the value chain.
Growth Catalysts
- Retort-compatible barrier films:Advanced polyethylene terephthalate laminates enable clear pouches to penetrate ambient ready-meal segments previously dominated by metal cans and glass jars.
- California's SB 54 EPR framework:Extended producer responsibility laws in the US state create compliance-driven demand for recyclable mono-material structures with verified circularity pathways.
- Fresh produce visibility requirements:North American food retail chains are specifying high-clarity pouches for cut vegetables and prepared salads to reduce shrink and accelerate purchase decisions.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Barrier layer supply depends on a limited number of Asian petrochemical complexes, exposing converters to input cost volatility and allocation risk.
- Optical clarity versus recyclability trade-off:Current mechanical recycling infrastructure cannot process metallized or heavily printed clear films without contamination, limiting post-consumer feedstock quality.
- EFSA migration testing timelines:European Food Safety Authority protocols for new food contact substances extend approval cycles to 18-24 months, delaying product launches for reformulated structures.
Strategic Opportunities
- India's FSSAI packaging modernization:India's food safety regulator is tightening shelf-life labeling requirements, creating demand for oxygen-scavenging clear pouches in spice and dairy segments.
- Chemical recycling infrastructure:Pyrolysis and depolymerization investments in Germany and the Netherlands will unlock feedstock for food-grade recycled content in clear film applications.
- Smart dispensing integration:Convergence of flexible packaging with printed electronics enables temperature-indicating labels for cold-chain pharmaceutical and biologic applications.
Industry Challenges
- Multi-layer delamination expertise:Separating incompatible polymer layers for chemical recycling requires specialized solvent-based processes that few converters have operationalized at scale.
- Legacy filling equipment retrofit costs:Transitioning from pre-made pouches to form-fill-seal formats demands capital expenditure on servo-driven baggers with vision-based seal inspection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clear Pouches Market |
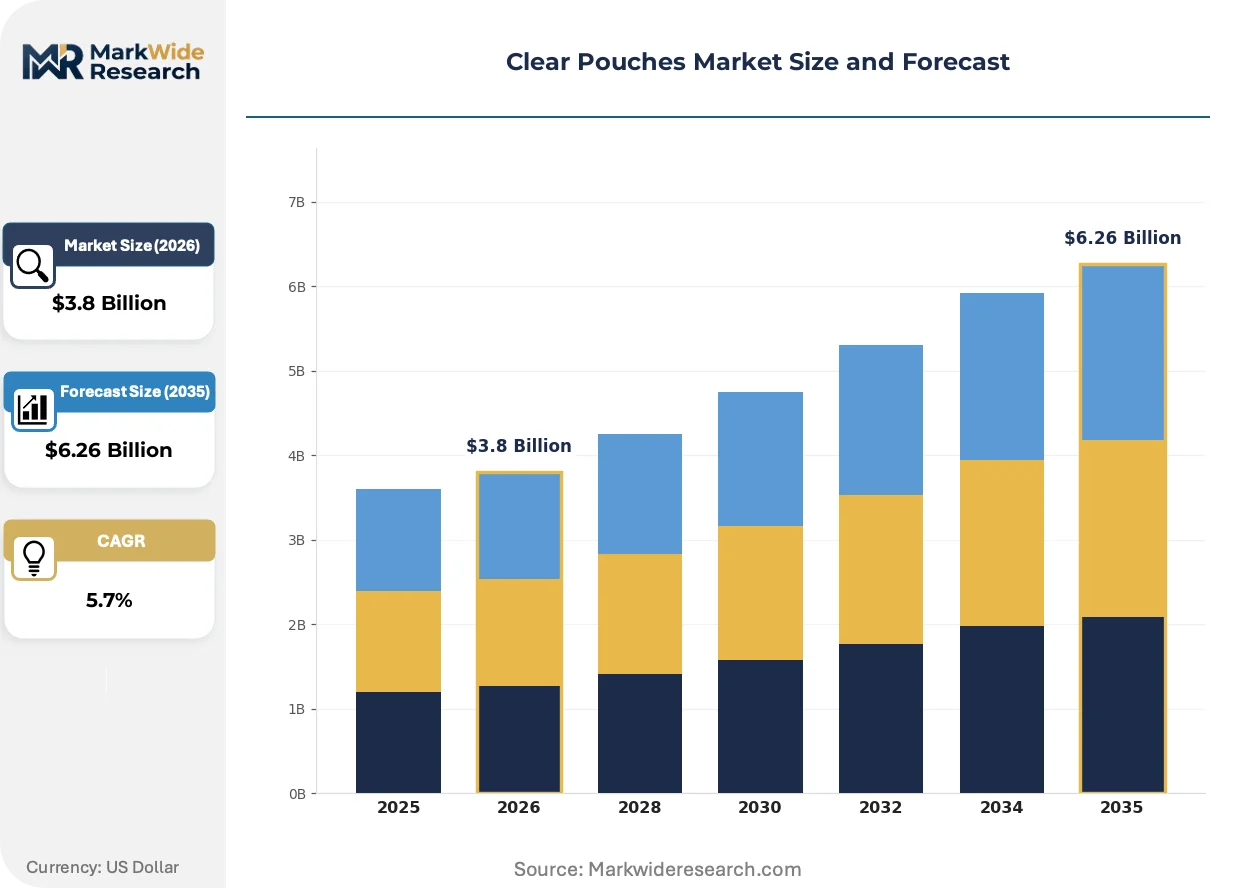
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Stand-Up Pouches, Gusseted Pouches, Zipper Pouches Material: Polyethylene, Polypropylene, PET, Biodegradable Films End User: Food Industry, Retail, Healthcare, Cosmetics Closure Type: Zip Lock, Heat Seal, Adhesive Seal, Others |
| Companies Covered | Amcor plc, ProAmpac Intermediate, Inc., Berry Global Group Inc., Mondi Group, Constantia Flexibles Group GmbH, Huhtamaki Oyj, Sonoco Products Company, Sealed Air Corporation, Bischof + Klein SE and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clear Pouches Market Strategic Shifts
Digital printing and inline quality inspection systems are compressing lead times for short-run clear pouch production. These capabilities are enabling mass customization while reducing working capital requirements for brand owners.
High-speed laser scoring technology is automating easy-open features in polyethylene and polypropylene laminates without compromising hermetic integrity. Snack food manufacturers in the United States are adopting this capability to eliminate mechanical tear notches and improve line efficiency. The technology is automating what previously required manual secondary operations, compressing total delivered cost for resealable pouch formats.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings from European food packaging applications. Converters are responding with plasma-enhanced chemical vapor deposition of silicon oxide barriers on polyester substrates. Ready-meal and bakery segments in Germany and France are absorbing higher unit costs to maintain regulatory compliance and shelf-life performance.
Direct-to-retail e-commerce channels are fragmenting traditional distributor relationships for specialty clear pouch converters. Small-batch cosmetic and nutraceutical brands in South Korea are sourcing custom-printed structures through digital procurement platforms rather than established packaging distributors. This channel disintermediation is compressing minimum order quantities and accelerating design iteration cycles for premium positioning.
Clear Pouches Market Segmentation
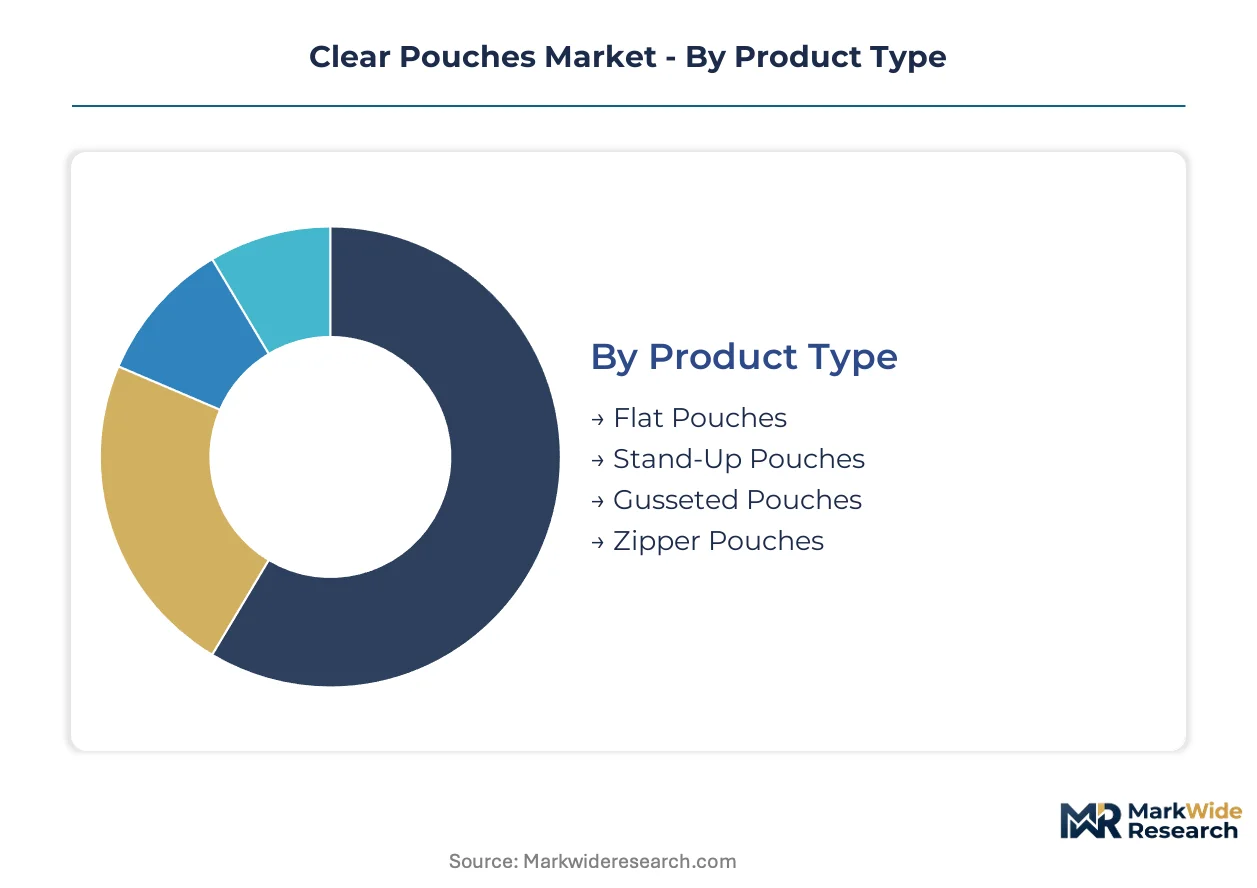
Clear pouch specifications diverge sharply across application contexts, with shelf-life requirements, optical clarity demands, and regulatory compliance thresholds driving distinct procurement patterns. Upgrade cycles in filling equipment and sustainability mandates are reshaping segment prioritization for converters and brand owners alike.
Product Type:
Equipment upgrade cycles favor formats that maximize line speed and shelf presence without retrofitting legacy machinery.
- Stand-Up Pouches:These configurations incorporate bottom gusset structures enabling vertical shelf display while reducing material intensity versus rigid alternatives. North American food retail chains specify stand-up formats for ambient ready-meals and fresh produce categories where visibility accelerates purchase decisions. Volume placements concentrate in Stand-Up Pouches; the faster expansion belongs to Zipper Pouches.
- Zipper Pouches:Integrated reseal mechanisms extend product freshness across multiple consumption occasions, commanding premium positioning in snack and pet food segments. California's SB 54 EPR framework drives specification of mono-material zipper structures with verified recyclability pathways.
- Flat Pouches:Two-dimensional formats minimize shipping cube and material cost for single-serve portions in institutional foodservice and sample distribution.
- Gusseted Pouches:Side-folded structures expand volumetric capacity for bulk dry goods and agricultural inputs where stacking strength matters.
Format selection tracks filling equipment vintage and retail channel requirements rather than material cost alone.
Material:
Regulatory compression on multi-layer structures is forcing material substitution decisions that trade barrier performance against recyclability credentials.
- Polyethylene:Linear low-density and metallocene grades dominate fresh produce and frozen food applications requiring cold-temperature toughness and heat-seal latitude. Germany's chemical recycling infrastructure investments will unlock food-grade recycled content streams for high-clarity polyethylene laminates.
- PET:Biaxially oriented polyester films deliver superior optical clarity and dimensional stability for retort applications and premium cosmetics where shelf differentiation commands priority. EFSA migration testing protocols extend approval timelines for new PET copolymer formulations, delaying product launches.
- Polypropylene:Cast and oriented polypropylene structures balance moisture barrier and cost efficiency for dry snack and bakery segments.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate alternatives occupy strategic positioning for EU Green Deal compliance despite limited industrial composting infrastructure.
Polyethylene captures the largest placement volumes; biodegradable alternatives are climbing the fastest despite unit cost premiums.
End User:
End-use concentration determines barrier specification intensity and regulatory scrutiny levels across the value chain.
- Food Industry:Oxygen transmission rates between 0.5 and 10 cc/m²/day protect shelf-stable and refrigerated categories from oxidative degradation. FDA food contact substance notifications govern material composition for US-bound imports.
- Retail:Private-label and branded merchandise demand short-run digital printing capabilities with inline quality inspection for rapid design iteration.
- Healthcare:Sterile barrier requirements and child-resistant specifications govern pharmaceutical and medical device packaging where seal integrity validation is mandatory.
- Cosmetics:Premium positioning drives high-clarity structures with metallized or holographic decorative layers for skincare and fragrance applications.
Food Industry placements dominate volume; cosmetics applications are gaining share fastest on premiumization trends.
Closure Type:
Dispensing convenience and reseal functionality are displacing single-use heat-seal formats in retail-facing categories.
- Zip Lock:Interlocking profile extrusions enable repeated opening and closing without tool assistance, driving repeat purchase behavior in snack and pet food segments. High-speed laser scoring technology automates easy-open features without compromising hermetic integrity.
- Heat Seal:Thermal fusion of compatible polymer layers delivers tamper-evidence and extended shelf life for ambient distribution, remaining cost-optimal for single-serve portions.
- Adhesive Seal:Pressure-sensitive cohesive coatings enable reseal functionality in structures incompatible with interlocking profiles, common in paper-based laminates.
- Others:Spout fitments, tear notches, and combination systems serve specialized dispensing requirements in liquid and powder applications.
Heat Seal retains volume concentration; zip lock mechanisms are expanding most quickly on convenience-driven specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and Mexico are attracting pouch converter investments through tariff exemptions and streamlined customs procedures. These zones concentrate new extrusion and printing capacity serving export-oriented food brands.
United States
California's SB 54 extended producer responsibility law mandates recyclable mono-material structures, driving specification shifts among snack food brands headquartered in Los Angeles and San Francisco. FDA food contact substance notifications govern material composition for interstate commerce. Chicago-area converters are retrofitting legacy filling equipment to handle stand-up pouch formats for Midwestern frozen food processors.
Germany
REACH restrictions on per- and polyfluoroalkyl substances are eliminating conventional grease-resistant coatings from food packaging applications. EFSA migration testing protocols enforce stricter extractable thresholds for European market access. The Ruhr industrial cluster hosts chemical recycling infrastructure investments unlocking feedstock for food-grade recycled content in clear film applications.
China
Dual carbon goals under MIIT guidance are pressuring converters to reduce energy intensity in film extrusion operations. GB standards govern food contact material safety for domestic distribution and export certification. The Yangtze River Delta concentrates pouch manufacturing serving e-commerce fresh produce channels with high-clarity polyethylene laminates.
India
FSSAI packaging modernization is tightening shelf-life labeling requirements, creating demand for oxygen-scavenging clear pouches in spice and dairy segments. DGFT import regulations affect barrier film resin availability for domestic converters. Gujarat's petrochemical corridor supplies polyethylene grades to pouch fabricators serving Mumbai and Delhi retail chains.
South Korea
MFDS pharmaceutical packaging standards are accelerating adoption of sterile barrier clear pouches for biologic cold-chain applications. The country's national sustainability framework pressures cosmetic brands toward biodegradable film alternatives. Seoul Capital Area converters integrate smart dispensing features with printed electronics for temperature-indicating labels.
Clear Pouches Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the clear pouches value chain. The market structure tilts toward consolidation at the film extrusion tier while remaining fragmented among regional converters serving local food brands. Three archetypes dominate: integrated resin-to-pouch operators controlling compounding through conversion, specialized barrier film developers targeting retort and pharmaceutical applications, and digital-first converters capturing short-run cosmetic and nutraceutical demand. Capacity expansion and portfolio diversification toward mono-material recyclable structures represent the dominant competitive moves.
Within the integrated resin-to-pouch tier, Amcor plc and Berry Global Group Inc. exemplify backward integration strategies spanning compounding operations through finished pouch conversion. ProAmpac Intermediate, Inc. occupies a specialized position among retort-compatible structure developers, reflecting the archetype of barrier-focused technology differentiation. These three entities represent the competitive spectrum from scale-driven vertical control to application-specific engineering depth.
| Leading Market Players |
|---|
| Amcor plc |
| ProAmpac Intermediate, Inc. |
| Berry Global Group Inc. |
| Mondi Group |
| Constantia Flexibles Group GmbH |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Sealed Air Corporation |
| Bischof + Klein SE and Co. KG |
| Others |
Value Chain & Pricing Dynamics
California's SB 54 extended producer responsibility mandate gates qualified supply access for converters serving West Coast food brands, while simultaneously stratifying pricing tiers between verified mono-material structures and legacy multi-layer alternatives. Premium-tier positioning now requires demonstrated circularity pathways, compressing margin structures for non-compliant suppliers.
Pricing Analysis
Margin tightening in standard-grade polyethylene laminates reflects ethylene-vinyl alcohol resin allocation constraints at Asian petrochemical complexes. Three-tier pricing structure across premium, standard, and economy levels separates retort-compatible PET structures with EFSA compliance from commodity fresh-produce formats. Cost-down pressure on economy-tier flat pouches accelerates because mechanical recycling contamination limits post-consumer feedstock quality. Private-label retail buyers exhibit highest price sensitivity; pharmaceutical and cosmetics segments absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale food processor demand, while specialized converters serve cosmetic and nutraceutical buyers through digital procurement platforms. Raw material supply concentrates in China, Germany, and the United States, with biaxially oriented polyester films and metallocene polyethylene grades anchoring cost structures. Barrier layer availability draws from limited Asian ethylene-vinyl alcohol production, exposing converters to input volatility. Distribution runs through regional converter networks with captive film extrusion, though single-source vulnerability persists for retort-compatible substrate qualifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race, with resin compounding capabilities and chemical recycling infrastructure emerging as the decisive upstream levers separating consolidators from contract-dependent competitors.
For Market Incumbents: To counter regulatory compression on multi-layer structures, Amcor plc and Berry Global Group should accelerate backward integration into mono-material resin compounding, while ProAmpac Intermediate invests in solvent-based delamination expertise for chemical recycling feedstock recovery. Captive supply of food-grade recycled polyethylene will defend margin position against virgin resin volatility. For New Entrants and Emerging Players: Capture India's oxygen-scavenging spice and dairy pouch segment where FSSAI modernization has outpaced domestic converter technical capability. Target South Korean cosmetic brands through biodegradable film alternatives under EU Green Deal alignment pressure. Digital-first sourcing platforms offer the lowest-friction go-to-market pathway for sub-10,000 unit runs. For Investors and Strategic Acquirers: Germany's chemical recycling infrastructure investment announcements are the leading indicator that food-grade recycled content economics will flip within the mid-window, favoring early positioning in pyrolysis and depolymerization technology holders. Acquisition focus should center on specialized barrier film developers with EFSA-approved retort structures and operational solvent-based separation processes. Monitor California SB 54 compliance verification timelines as the inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive polyethylene supply secures cost advantage against EVOH volatility for high-clarity laminates. |
| Chemical Recycling Infrastructure Investment | Pyrolysis capacity in Germany unlocks food-grade recycled content streams for EU Packaging and Packaging Waste Regulation compliance. |
| Retort-Compatible Barrier Film Development | EFSA-approved PET laminates penetrate ambient ready-meal segments previously dominated by metal cans. |
| Digital Printing Platform Deployment | Inline quality inspection compresses lead times for South Korean cosmetic brands sourcing through procurement platforms. |
| Mono-Material Zipper Structure Certification | Verified recyclability pathways satisfy California SB 54 mandates for snack food brand procurement specifications. |
Study Parameters
Document review covered trade customs data, FDA food contact substance notifications, EFSA migration testing protocols, and SEC filings from listed packaging conglomerates, complemented by interviews with film extrusion plant managers, retail category buyers, regulatory affairs specialists at converters, and downstream food processor procurement leads. Primary fieldwork across the United States, Germany, China, and India validated secondary estimates through bottom-up capacity assessments and top-down demand triangulation.
Segment-level value and volume trajectories emerged from modeling across product type, material grade, closure mechanism, and end-use concentration dimensions throughout the forecast period. CAGRs derived from regression analysis against historical placement data, with explicit incorporation of equipment upgrade cycle timing and regulatory compliance threshold implementation schedules as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chemical recycling infrastructure buildout pacing and EFSA approval timeline variability for new food contact substances. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Open Mouth Sacks Market
Pouch
Sterilization Pouches Market
Pouch
High-Barrier Pouches Market
Pouch
Bio PE Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Slider Pouches Market
Pouch
Dual-Chamber Pouches Market
Pouch
France Pouch Packaging Market
Pouch
Japan Pouch Packaging Market
Pouch
North America Pouch Packaging Market
Pouch
Europe Retort Pouches Market
Pouch
PCR Pouches Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Retort Pouch Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Box Pouch Market