
 Global Animal Feed Micronutrients Market | 2026-2036
Global Animal Feed Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Global Animal Feed Micronutrients Market Analysis
Commercial livestock integrators are reorganizing procurement priorities around precision nutrition programs that optimize feed conversion ratios and reduce environmental nitrogen loading. DSM-Firmenich leverages its premix and enzyme portfolios to anchor supply relationships with vertically coordinated poultry and swine operations across Southeast Asia and Latin America. BASF SE competes through specialty vitamin complexes that sustain formulation partnerships with multinational feed compounders seeking single-source micronutrient sourcing.
Animal feed micronutrients comprise trace minerals, fat- and water-soluble vitamins, and essential amino acids dosed at parts-per-million to grams-per-tonne levels to prevent deficiency disorders and optimize metabolic performance in food-producing animals. Industrial production employs spray-drying, microencapsulation, and chelation processes to enhance bioavailability and prevent degradation during pelleting at temperatures exceeding 85 degrees Celsius. Minerals occupies the largest value share due to established zinc, copper, and selenium supplementation protocols across ruminant and poultry sectors, while amino acids represents the fastest-expanding category as lysine and methionine inclusion rates climb in low-protein diet formulations mandated by sustainability targets. Aquaculture applications command premium pricing as shrimp and salmon diets require precise taurine and vitamin C derivatives that resist leaching in aqueous environments.
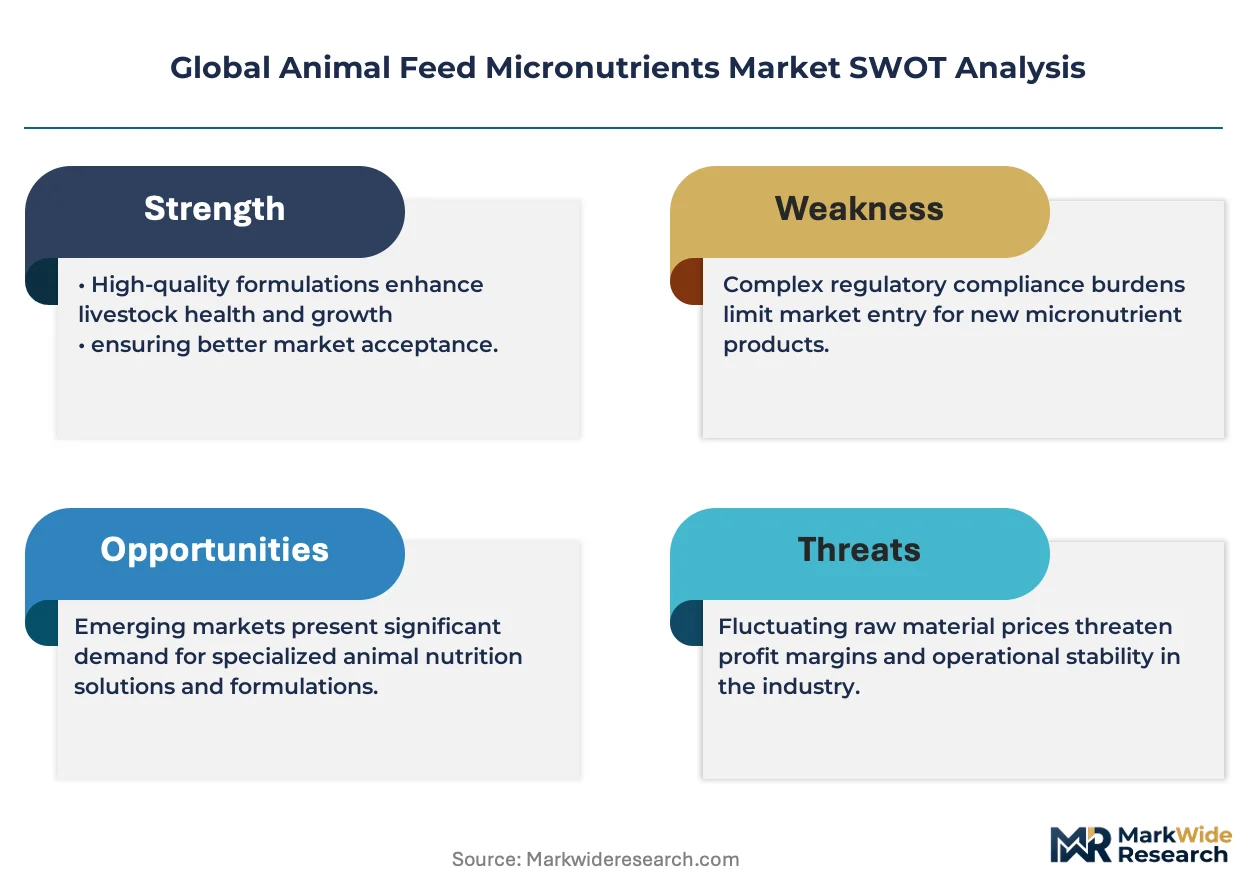
The European Food Safety Authority (EFSA) evaluates additive safety through reauthorization cycles that tighten purity thresholds and ban certain mineral oxide forms, while the FDA's Center for Veterinary Medicine enforces Good Manufacturing Practice standards for medicated and non-medicated feed mixing operations in the United States. China's Ministry of Agriculture and Rural Affairs implements GB standards that limit heavy metal carryover in mineral premixes destined for domestic pork and layer industries. Stakeholders must monitor regulatory divergence between jurisdictions that fragments formulation portfolios and elevates compliance costs for multinational premix suppliers serving integrated protein chains.
Market Dynamics
Precision nutrition programs are compressing formulation cycles as livestock integrators demand real-time diet optimization based on growth-stage metabolite monitoring, forcing premix suppliers to rebuild service models around on-farm analytics rather than bulk commodity supply.
Growth Catalysts
- EU Green Deal residue mandates:Tighter traceability requirements for feed additives are accelerating replacement of conventional mineral oxides with chelated and organic forms that demonstrate cleaner metabolic pathways.
- Brazil's central-west poultry belt:Contract grower network expansion by integrated protein companies is concentrating demand for standardized vitamin-mineral premixes that synchronize flock performance across dispersed operations.
- Low-protein diet formulations:Sustainability-driven lysine and methionine inclusion rate increases are displacing crude protein dependency in swine and poultry rations, expanding amino acid micronutrient volume.
Market Restraints
- Sulfate and oxide raw material volatility:Zinc and copper sulfate prices fluctuate with mining output disruptions and energy-intensive processing costs, compressing premix margin buffers.
- Chinese mineral premix concentration:Heavy reliance on domestic Chinese production of selenium yeast and trace mineral chelates creates geographic supply vulnerability for multinational compounders.
- EFSA reauthorization timelines:Extended safety evaluation cycles for novel organic mineral forms delay commercialization by 18-36 months, freezing formulation portfolios.
Strategic Opportunities
- Indonesia's aquaculture expansion:Shrimp and finfish farm intensification creates demand for leaching-resistant vitamin C derivatives and taurine formulations that command premium pricing.
- Microencapsulation-enzyme convergence:Combining heat-stable vitamin coatings with phytase and protease delivery systems enables single-premix solutions for high-temperature pelleting operations.
- US FDA medicated feed GMP alignment:Compliance infrastructure investments open pathways to co-position micronutrient and therapeutic premixes within vertically integrated swine systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in chelation chemistry and bioavailability modeling is concentrated among retiring cohorts, constraining R&D pipeline velocity.
- ISO 22000 feed safety certification:Multi-site audit complexity and documentation burdens extend compliance timelines for premix exporters serving fragmented EU member state requirements.
- Legacy ERP integration:Batch traceability systems for mineral premix production resist real-time connectivity with integrator nutrition management platforms, delaying precision service deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Animal Feed Micronutrients Market |
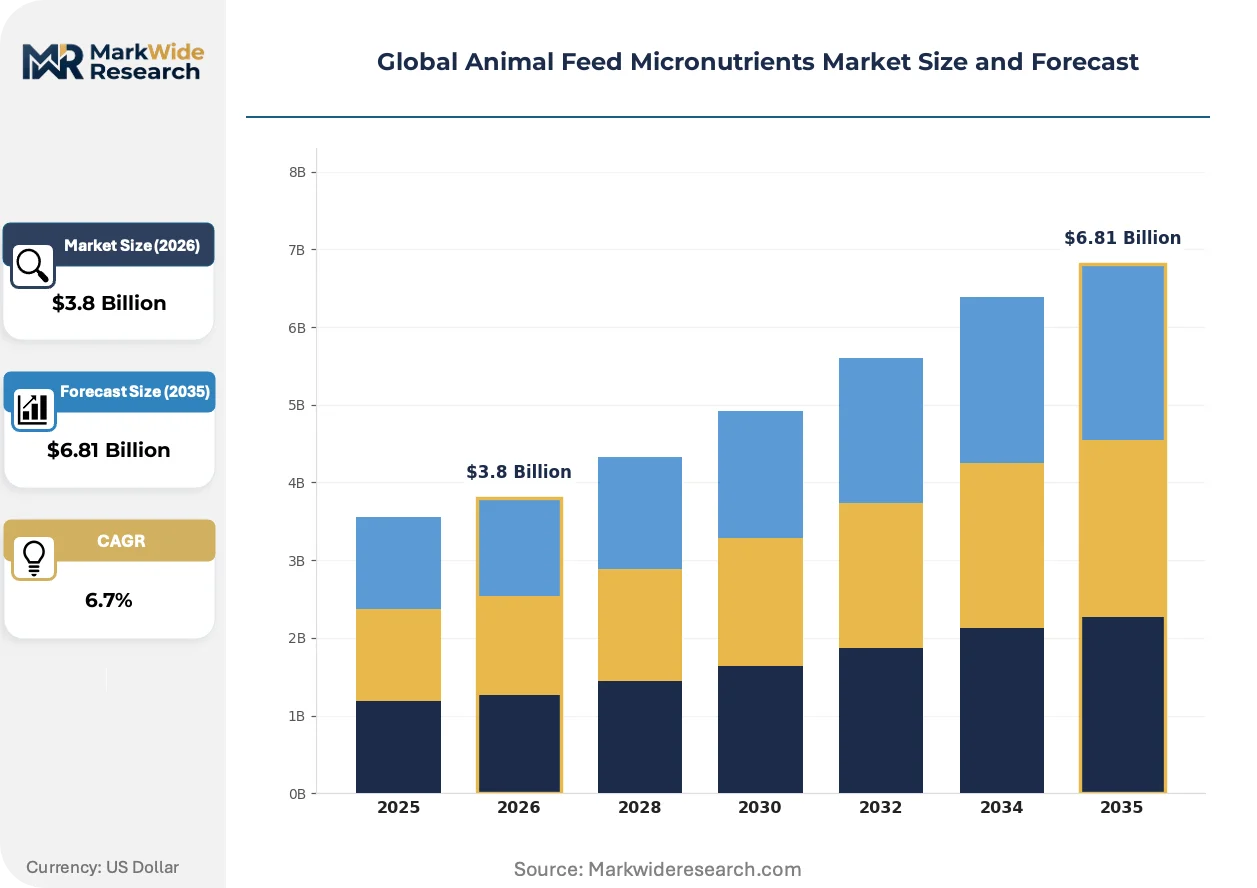
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minerals, Vitamins, Amino Acids, Others Form: Powder, Liquid, Granular, Pellet Application: Ruminants, Poultry, Swine, Aquaculture Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, DSM-Firmenich, BASF SE, Nutreco N.V., Kemin Industries, Inc., Alltech, Inc., Novus International, Inc., Zinpro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Animal Feed Micronutrients Market Emerging Trajectories
Active reformulation of mineral delivery systems is compressing the performance gap between commodity sulfates and premium chelates, while regulatory pressure on environmental loading accelerates adoption of precision dosing technologies.
Organic trace mineral complexes incorporating hydroxy- and protein-bound zinc, copper, and manganese are displacing inorganic sulfate forms in broiler and layer diets. Southeast Asian integrators are adopting these alternatives at rates exceeding 15% annual expansion in premix specifications. The technology is bifurcating the mineral segment into cost-optimized commodity tiers and performance-priced organic categories with distinct supplier bases.
REACH authorization restrictions on certain mineral oxide forms are compelling European compounders to reformulate premix portfolios ahead of sunset dates. Industrial consequence includes accelerated qualification of alternative selenium yeasts and iron glycinates that satisfy purity thresholds. Poultry layer operations in Germany and France are absorbing 8-12% formulation cost increases to maintain market access.
Buyer concentration among Brazilian and Thai contract growers is consolidating procurement authority at integrator headquarters, displacing distributed purchasing through local feed mills. Channel compression favors premix suppliers with direct technical service presence over distributor-dependent competitors. This pattern is most visible in Mato Grosso do Sul and São Paulo state poultry corridors.
Global Animal Feed Micronutrients Market Segmentation
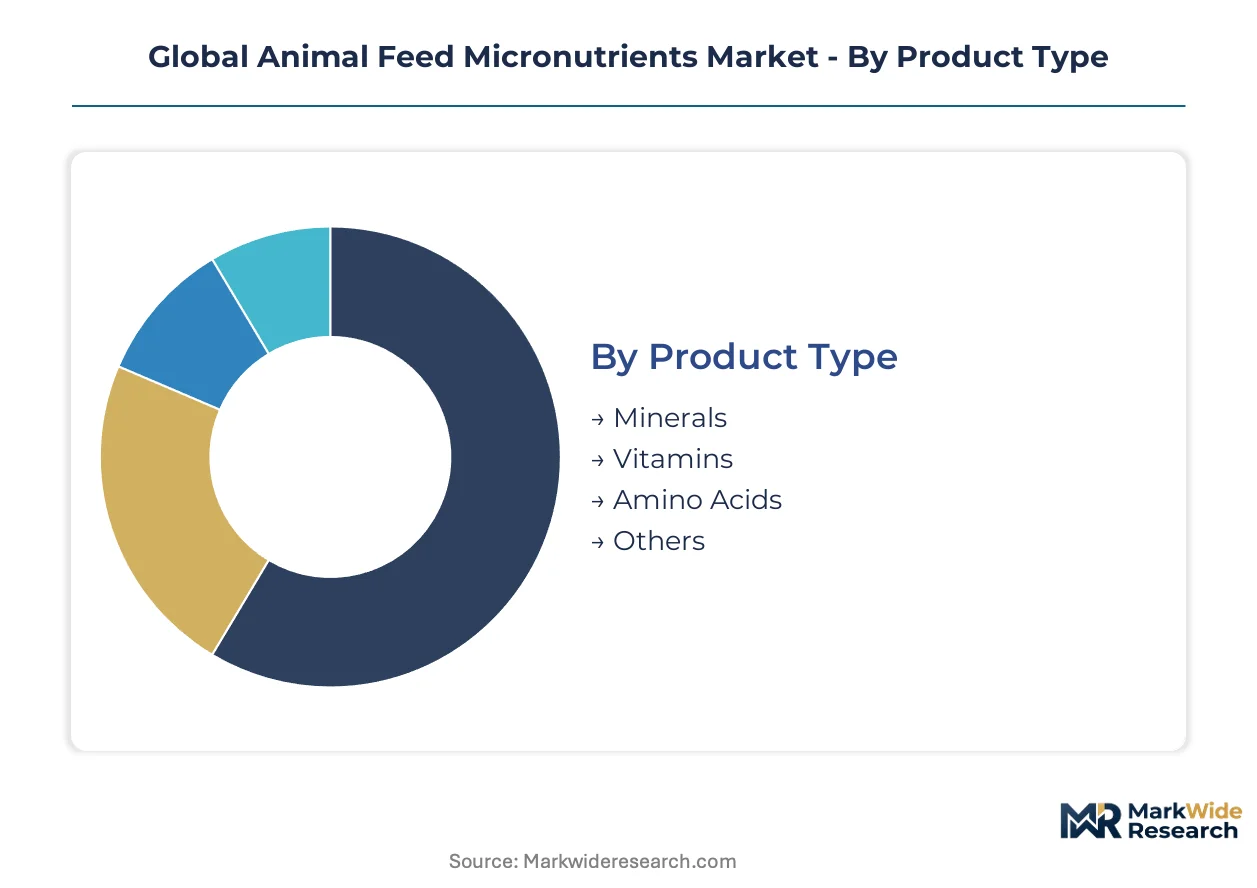
Segmentation in animal feed micronutrients reveals how formulation complexity varies across species physiology and processing requirements. Product chemistry, physical stability, and bioavailability specifications diverge sharply between ruminant fermentation systems and monogastric absorption pathways.
Product Type:
Substitution pressure concentrates in mineral forms as chelated and organic variants displace commodity sulfates under tightening residue regulations.
- Minerals:Zinc, copper, manganese, and selenium compounds dosed at parts-per-million levels to prevent deficiency disorders and optimize immune function in food-producing animals. Demand concentrates in Brazil's Mato Grosso do Sul poultry corridor where integrators specify hydroxy- and protein-bound forms to meet EU export residue limits.
- Vitamins:Fat-soluble (A, D, E, K) and water-soluble (B-complex, C) micronutrients requiring microencapsulation to withstand pelleting temperatures exceeding 85 degrees Celsius. German layer operations are absorbing 8-12% formulation cost increases to maintain market access under EFSA reauthorization timelines.
- Amino Acids:Lysine, methionine, threonine, and tryptophan supplementation enabling low-protein diet formulations that reduce environmental nitrogen loading. Lysine inclusion rates are climbing in swine rations across Vietnam and Thailand as sustainability targets displace crude protein dependency.
- Others:Enzymes, organic acids, and nucleotides occupying niche formulation roles for specific metabolic enhancement.
Minerals anchors the volume base while amino acids gains share at the steepest rate.
Form:
Cost tier differentiation separates heat-stable premium grades from commodity powders in high-temperature pelleting applications.
- Powder:Unprotected crystalline or spray-dried micronutrients serving low-temperature mash feed applications and on-farm mixing operations. Indonesian shrimp farms specify powder vitamin C derivatives for aqueous environment stability.
- Liquid:Solubilized concentrates for post-pelleting application and drinking water supplementation in intensive swine systems. Liquid methionine hydroxy analogues dominate US integrator procurement for finisher phase precision dosing.
- Granular:Agglomerated particles with enhanced flowability for automated premix blending lines serving multinational compounders.
- Pellet:Extruded carriers embedding heat-labile vitamins within protective matrices for high-temperature processing. Microencapsulation-enzyme convergence in pellet form enables single-premix solutions for Southeast Asian poultry integrators.
Powder retains the broadest application base while pellet commands the steepest pricing premium.
Application:
Volume concentration tracks protein demand geography with poultry integration density determining premix standardization requirements.
- Ruminants:Cobalt, selenium, and copper supplementation addressing rumen microbial synthesis limitations and grazing deficiency risks. Brazilian beef operations in Mato Grosso specify protected forms to bypass rumen degradation.
- Poultry:Precise vitamin-mineral premixes synchronizing flock performance across dispersed contract grower networks. Thailand's vertically integrated broiler sector concentrates procurement authority at headquarters, displacing distributed feed mill purchasing.
- Swine:Phase-feeding micronutrient programs optimizing lean tissue deposition and reproductive performance. US FDA medicated feed GMP alignment enables co-positioning of micronutrient and therapeutic premixes within integrated systems.
- Aquaculture:Leaching-resistant taurine and vitamin C derivatives for shrimp and salmon diets commanding premium pricing. Indonesia's intensifying shrimp and finfish farms drive specification innovation for aqueous environment stability.
Poultry anchors the volume base while aquaculture commands the steepest expansion trajectory in value terms.
Distribution Channel:
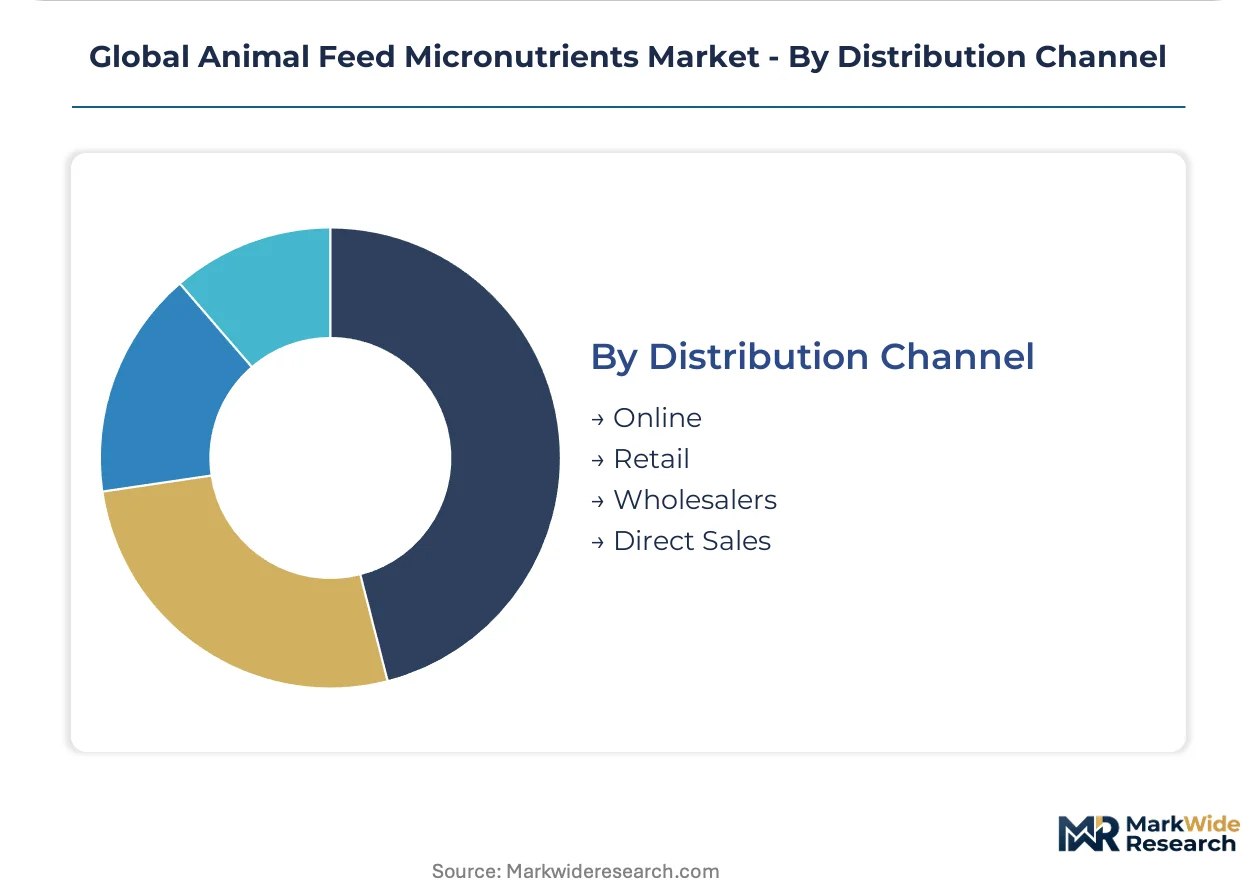
Customer type bifurcation separates integrator direct procurement from fragmented farm-level purchasing through intermediaries.
- Online:Digital platforms serving smallholder operations and specialty additive sourcing with batch traceability documentation.
- Retail:Farm supply stores and cooperatives distributing bagged premixes to independent livestock producers.
- Wholesalers:Regional distributors maintaining inventory buffers for feed mill customers with variable demand patterns.
- Direct Sales:Technical service teams embedding with multinational compounders and integrated protein companies. Channel compression in Brazil and Thailand favors suppliers with direct presence over distributor-dependent competitors.
Direct sales anchors the value base while online channels expand most quickly in smallholder-accessible geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated protein companies in Brazil and Thailand are compressing procurement channels, while European residue mandates and Indonesian aquaculture expansion reshape formulation demand across distinct regulatory environments.
Brazil
Contract grower network expansion in Mato Grosso do Sul and São Paulo state poultry corridors concentrates demand for standardized vitamin-mineral premixes. ANVISA alignment with EU export residue protocols drives hydroxy- and protein-bound mineral specifications. Integrator headquarters in Campinas and Chapecó now control procurement authority previously dispersed through local feed mills.
United States
Vertically coordinated swine operations in Iowa and North Carolina are consolidating micronutrient sourcing under single-supplier arrangements. FDA Center for Veterinary Medicine enforcement of medicated feed GMP standards creates compliance infrastructure requirements for premix suppliers. The US Midwest corn-soy belt anchors volume concentration for lysine and methionine inclusion in low-protein diet formulations.
Germany
Poultry layer operations in Lower Saxony and Bavaria absorb 8-12% formulation cost increases to maintain market access under EFSA reauthorization timelines. The EU Green Deal's Farm to Fork Strategy tightens traceability mandates for feed additives. REACH authorization restrictions on certain mineral oxide forms accelerate qualification of alternative selenium yeasts and iron glycinates.
Indonesia
Shrimp and finfish farm intensification in East Java and Sulawesi creates demand for leaching-resistant vitamin C derivatives and taurine formulations. The Ministry of Marine Affairs and Fisheries implements aquaculture zoning regulations that concentrate production in designated coastal belts. Surabaya-based feed compounders specify aqueous environment stability as a premium pricing criterion.
China
Domestic production concentration of selenium yeast and trace mineral chelates creates geographic supply vulnerability for multinational compounders. The Ministry of Agriculture and Rural Affairs enforces GB standards limiting heavy metal carryover in mineral premixes for pork and layer industries. Shandong and Guangdong provinces anchor industrial capacity for lysine and methionine fermentation output.
Global Animal Feed Micronutrients Market Vendor Landscape
Player mix skews toward diversified nutrition conglomerates with premix and enzyme portfolios, creating a tiered structure where specialty mineral chelate specialists occupy premium positions alongside commodity sulfate suppliers. Three archetypes dominate: integrated nutrition platforms spanning vitamins through enzymes, pure-play trace mineral innovators, and regional feed compounders with captive premix operations. Competitive moves center on direct technical service embedding with integrator headquarters and microencapsulation-enzyme convergence for high-temperature pelleting applications.
Within the integrated nutrition tier, DSM-Firmenich and BASF SE exemplify divergent strategic positioning. DSM-Firmenich anchors supply relationships across Southeast Asian and Latin American poultry and swine operations through combined premix and enzyme portfolios. BASF SE occupies a formulation partnership position with multinational feed compounders seeking single-source micronutrient sourcing for vitamin complexes. Nutreco N.V. represents the compounder-integrator convergence archetype, blending premix supply with direct technical service presence in Brazil and Thailand contract grower networks.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| BASF SE |
| Nutreco N.V. |
| Kemin Industries, Inc. |
| Alltech, Inc. |
| Novus International, Inc. |
| Zinpro Corporation |
| Others |
Supply Flow & Price Mechanics
Chelated zinc and copper displacing commodity sulfates under EU residue mandates is redrawing supply geography toward Chinese and Brazilian organic mineral producers while compressing margin buffers for European compounders absorbing reformulation costs. This substitution dynamic simultaneously elevates pricing premiums for bioavailable forms and concentrates procurement leverage among integrators with direct supplier relationships.
Pricing Analysis
The technology-generation pricing gap separating microencapsulated vitamin pellets from unprotected powder forms spans three distinct tiers: next-generation heat-stable coatings commanding premium positioning, current-generation spray-dried intermediates occupying standard tiers, and legacy crystalline powders serving economy segments. Price differentiation rests on certification grade for EFSA-compliant organic mineral forms and volume scale in contract grower network procurement. Pricing pressure stems from sulfate and oxide raw material volatility compressing premix margins, with Brazilian integrators exhibiting highest price sensitivity due to dispersed contract grower cost absorption limits, while aquaculture specialists in Indonesia show lowest sensitivity for leaching-resistant formulations.
Supply Chain Analysis
Inventory lead times for selenium yeast and trace mineral chelates have extended as Chinese domestic production concentration creates geographic vulnerability for multinational compounders. Supply draws from China for fermentation-derived amino acids, Brazil for hydroxy-mineral processing, and Germany for microencapsulation technology. Raw material dependencies center on zinc and copper sulfate mining outputs, vitamin precursor petrochemical feedstocks, and specialized protein substrates for chelation. Single-source vulnerability concentrates in Chinese selenium yeast capacity. Distribution runs through direct technical service teams embedding with integrator headquarters, displacing traditional wholesale channels in Brazil and Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The animal feed micronutrients market sits in a cyclical recovery phase driven by restocking cycles in Brazil's poultry belt following integrator network expansion and precision nutrition program adoption.
For Market Incumbents: Fortify formulation partnerships through backward integration into chelation chemistry capabilities to offset raw material volatility exposure. Expand captive microencapsulation capacity in Southeast Asian production hubs to capture aquaculture premium pricing. Invest in ISO 22000 certification infrastructure ahead of EU member state audit complexity escalation.
For New Entrants and Emerging Players: Anchor in Indonesia's shrimp and finfish farm intensification corridor where leaching-resistant vitamin C derivatives face limited domestic competition. Target aqueous environment stability specifications as the most penetrable technical gap. Pursue co-development partnerships with Surabaya-based compounders lacking in-house micronutrient R&D.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty mineral chelate innovators with established EFSA qualification pathways. Long-term viability over the coming decade rests on regulatory navigation capabilities rather than commodity scale. Acquisition targets should demonstrate proven organic mineral bioavailability data packages. The signal to watch is EFSA reauthorization timeline acceleration for novel selenium yeast forms as inflection indicator for formulation portfolio refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation-Enzyme Convergence | Combines heat-stable vitamin coatings with phytase delivery for high-temperature pelleting operations serving Southeast Asian poultry integrators. |
| Backward Integration into Chelate Production | Captures margin compression from sulfate raw material volatility while securing supply security for organic mineral specifications. |
| Direct Technical Service Embedding | Aligns premix supply with real-time precision nutrition programs at Brazilian and Thai integrator headquarters displacing distributor channels. |
| Aquaculture Formulation Specialization | Develops leaching-resistant taurine and vitamin C derivatives for Indonesia's intensifying shrimp and finfish production zones. |
| EFSA Compliance Infrastructure Investment | Accelerates novel organic mineral qualification ahead of REACH authorization sunset dates for oxide form restrictions. |
Methodological Framework
A standing panel of premix formulation chemists, integrator procurement directors, feed compounder technical managers, and regulatory affairs specialists provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings of listed nutrition conglomerates, EFSA additive reauthorization databases, and Brazilian ANVISA residue protocol documentation. Bottom-up volume modeling triangulated against top-down value estimates derived from procurement authority concentration patterns in contract grower networks.
Consistency checks validated segment-level outputs against external benchmarks including amino acid fermentation capacity disclosures, vitamin microencapsulation patent filings, and mineral premix trade flow patterns. The analytical framework modeled product type, application species, physical form, and distribution channel dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating low-protein diet formulation mandates and precision nutrition adoption rates. Industry-specific forecast inputs included lysine inclusion rate trajectories in Vietnamese swine rations and organic mineral specification shifts in EU export-oriented poultry operations.
Decision-makers should treat outputs as directional under assumptions of sustained integrator vertical coordination and stable EFSA reauthorization timelines; material deviation in regulatory cycle acceleration or raw material supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Nutritional Products
Feed Supplements Market
Veterinary Nutritional Products
Global Animal Growth Promoters and Performance Enhancers Market
Veterinary Nutritional Products
Trace Minerals Chelated Feed Market
Veterinary Nutritional Products
Mediterranean Pet Nutrition Ingredient Blends Market
Veterinary Nutritional Products
Essential Oils in Animal Nutrition Market
Veterinary Nutritional Products
Pet Premixes Market
Veterinary Nutritional Products
Animal Feed Trace Minerals Market
Veterinary Nutritional Products
Animal Based Protein Supplements Market
Veterinary Nutritional Products
Latin America Animal Feed Organic Trace Minerals Market
Veterinary Nutritional Products
Broiler Premix Market
Veterinary Nutritional Products
Nutritional Ingredients in Animal Feed Market
Veterinary Nutritional Products
China Animal Milk Replacer Market
Veterinary Nutritional Products
Animal Growth Promoter Market
Veterinary Nutritional Products
Animal Nutrition Chemicals Market
Veterinary Nutritional Products
Feed Carotenoids Market
Veterinary Nutritional Products
South America Feed Vitamins Market