
 Farming As a Service Market | 2026-2036
Farming As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Farming As a Service Market Intelligence
The gap between premium subscription platforms and commodity equipment-rental offerings is broadening across the Farming As a Service landscape. Deere & Company anchors its position through captive telematics networks that lock in recurring revenue from large agribusiness clients. Trimble Inc. competes via deep specialization in precision-guidance data layers for row-crop operators. Apollo Agriculture navigates emerging-market terrain by bundling credit, inputs, and digital advisory into single subscription products for smallholders.
Farming As a Service denotes the commercial provision of agricultural inputs, machinery access, and decision-support tools through recurring fee structures rather than outright ownership, typically integrating GPS-guided equipment, soil-moisture telemetry, and cloud-based analytics dashboards to optimize yield per hectare. Crop Management services currently command the deepest margin pools because they bundle agronomic advice with input procurement and harvest logistics. Equipment Rental retains volume leadership among smallholder customer types constrained by capital access, though IoT Devices and Smart Sensors within the technology dimension are gaining traction fastest as farms seek real-time field intelligence.
The EU Green Deal and F-Gas Regulation shape equipment specifications and carbon-reporting obligations for providers serving European agribusiness end users, while India's PLI scheme for drones and agricultural mechanization accelerates domestic platform deployment. The US EPA and USDA conservation programs increasingly tie cost-share funding to documented precision-agriculture outcomes, tilting procurement toward validated service providers. Stakeholders must weigh regulatory compliance costs against the stickiness of subscription revenue models when selecting geographic expansion priorities.
Market Dynamics
Subscription-based equipment access is compressing capital barriers for smallholder cooperatives while locking large agribusiness into multi-year telemetry contracts. The EU Green Deal's carbon-accounting mandates and India's PLI scheme for agricultural drones are accelerating platform standardization across divergent farm scales.
Growth Catalysts
- EU Green Deal carbon mandates:European agribusiness must document supply-chain emissions, forcing adoption of subscription-based precision-agriculture platforms that generate auditable field data.
- India's PLI scheme for drones:Domestic manufacturing incentives reduce hardware costs for agritech startups deploying aerial imaging services across the Indo-Gangetic Plain.
- Soil-moisture telemetry:Real-time irrigation optimization via cloud-connected sensors is displacing calendar-based watering schedules in water-stressed farming regions.
Market Restraints
- Equipment supply concentration:GPS-guided machinery manufacturing clusters in Germany and the United States create import dependency for service providers in emerging markets.
- F-Gas Regulation compliance costs:European providers face retrofit expenses for refrigeration-dependent cold-chain logistics services tied to harvest management subscriptions.
- Technical interoperability gaps:Proprietary telematics protocols from major equipment manufacturers prevent seamless data portability between competing platforms.
Strategic Opportunities
- Smallholder cooperatives in Bihar and Uttar Pradesh:Bundled credit-input-advisory subscriptions remain underpenetrated among India's 85 million marginal farmers.
- USDA conservation program tie-ins:Cost-share funding for documented precision-agriculture outcomes creates a channel for validated service providers to capture federal procurement flows.
- Edge computing and satellite imagery convergence:On-field processing of high-resolution crop health data reduces latency for automated pest-detection alerts.
Industry Challenges
- Agronomic data science talent scarcity:Platform operators struggle to hire analysts capable of translating telemetry streams into actionable prescription maps for farmers.
- Multi-season certification timelines:New sensor hardware requires 12-18 months of field validation before agribusiness clients accept yield-gain guarantees.
- Legacy farm management software integration:Established record-keeping systems in large enterprises resist API connections to cloud-based subscription dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farming As a Service Market |
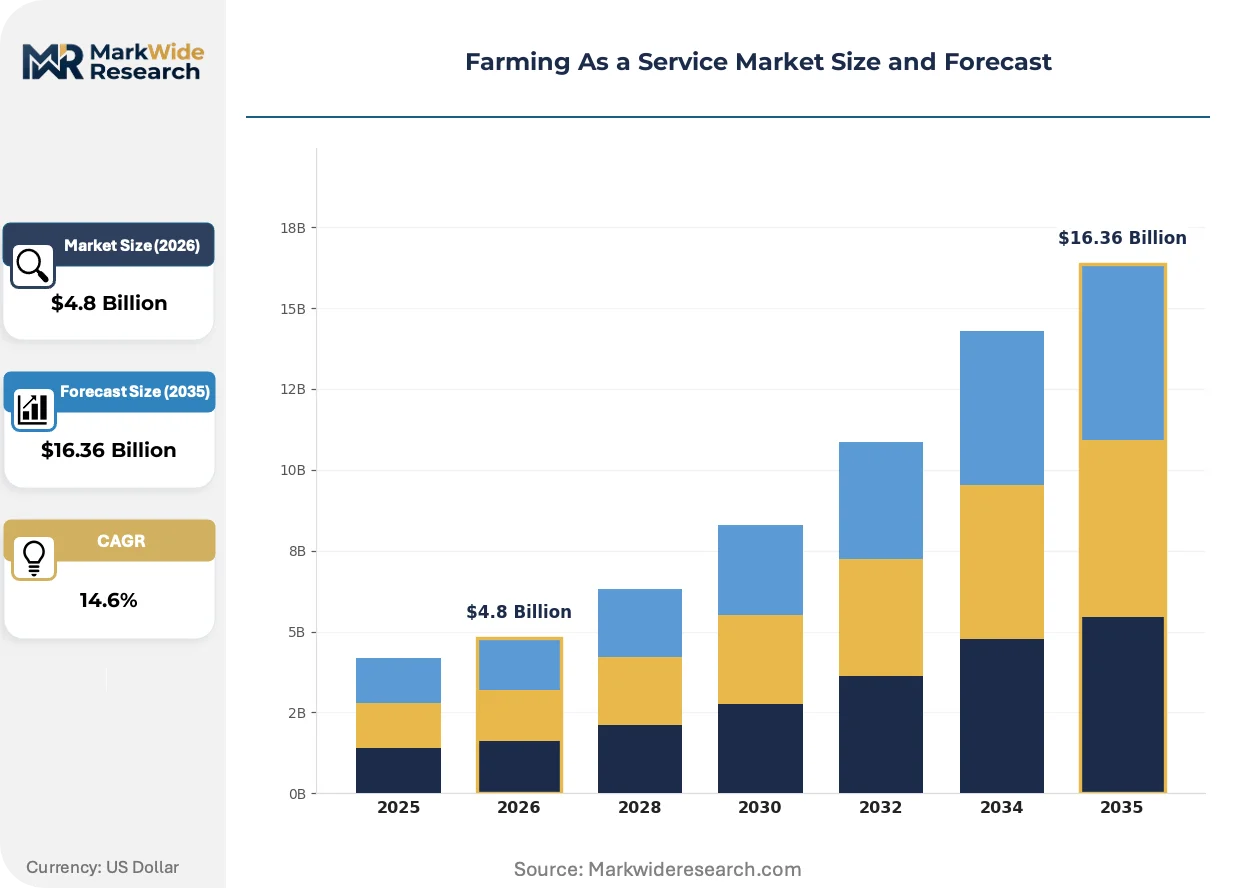
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Crop Management, Equipment Rental, Irrigation Services, Pest Control Customer Type: Smallholder Farmers, Large Enterprises, Cooperatives, Agritech Startups End User: Agribusiness, Food Processing, Research Institutions, Government Agencies Technology: Automation Solutions, Data Analytics, IoT Devices, Smart Sensors |
| Companies Covered | Deere & Company, Trimble Inc., Mahindra & Mahindra Ltd., AGCO Corporation, Apollo Agriculture, IBM Corporation, Accenture, BigHaat, Taranis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farming As a Service Market Strategic Shifts & Innovations
Edge-deployed inference engines and low-earth-orbit satellite constellations are collapsing the cost curve for real-time field intelligence. Platform providers now compete on data latency rather than hardware specifications.
Autonomous ground robots equipped with hyperspectral cameras are decentralizing crop-scouting operations that previously required manned aircraft or satellite passes. Mid-size row-crop operators in the US Corn Belt are piloting these units for weed identification at sub-inch resolution. The technology is decentralizing agronomic decision-making from centralized agronomist teams to on-field automated systems.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in refrigerated transport fleets serving subscription-based cold-chain logistics. Equipment rental providers must retrofit or replace cooling units to maintain European operating licenses. Horticulture exporters in Spain and Italy face the steepest compliance timelines given their perishable cargo volumes.
Cooperative procurement consortia are consolidating input purchasing power among smallholder groups that previously accessed machinery through informal village networks. These aggregators negotiate volume discounts with platform providers and demand outcome-based service level agreements. The pattern is most visible across India's farmer producer organizations, where 10,000-plus member cooperatives now contract directly with drone-spraying and soil-testing subscription services.
Farming As a Service Market Segmentation
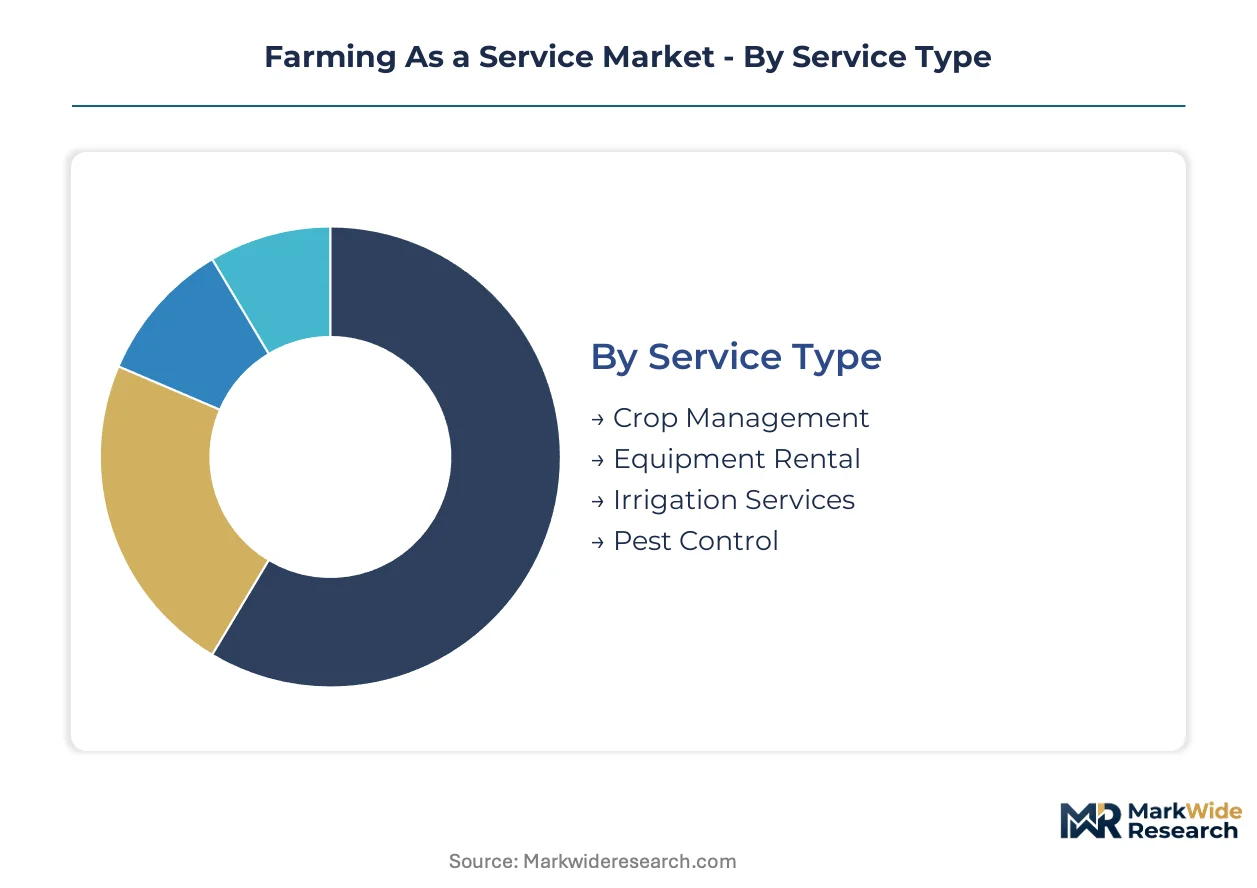
Service architecture in Farming As a Service diverges sharply by capital intensity and data maturity. Buyers select tiers based on whether they seek full agronomic outsourcing or targeted equipment access, with technology integration acting as the binding layer across all service contracts.
Service Type:
Cost tier separates subscription depth, from comprehensive crop lifecycle management to single-use equipment access.
- Crop Management:Bundles agronomic advice, input procurement, and harvest logistics into recurring fee structures. Large agribusinesses in the US Corn Belt and India's Punjab region prioritize these subscriptions for auditable yield optimization under carbon-accounting mandates.
- Equipment Rental:GPS-guided machinery access without ownership, dominated by seasonal leasing of tractors and harvesters. Smallholder cooperatives across Bihar and Uttar Pradesh drive volume through pay-per-use models constrained by capital access barriers.
- Irrigation Services:Cloud-connected soil-moisture telemetry replaces calendar-based watering schedules. Water-stressed farming regions in Spain and Australia's Murray-Darling Basin concentrate demand.
- Pest Control:Drone-based spraying and automated scouting subscriptions. India's PLI scheme for agricultural drones accelerates platform deployment across the Indo-Gangetic Plain.
Equipment Rental leads volumes today; Crop Management is gaining share fastest.
Customer Type:
Application complexity varies from credit-constrained smallholders to telemetry-heavy enterprise accounts.
- Smallholder Farmers:Marginal landholders accessing machinery through village-level aggregators and pay-per-use platforms. India's 85 million marginal farmers represent the deepest underpenetrated pool.
- Large Enterprises:Multi-year telemetry contracts with captive telematics networks lock in recurring revenue. EU Green Deal carbon-reporting obligations force adoption of precision-agriculture platforms generating auditable field data.
- Cooperatives:Consolidated procurement consortia negotiating volume discounts and outcome-based service level agreements. India's farmer producer organizations with 10,000-plus members now contract directly with drone-spraying subscriptions.
- Agritech Startups:Digital-native platforms bundling credit, inputs, and advisory for emerging-market smallholders. Apollo Agriculture's single-subscription products exemplify this model in East Africa and South Asia.
Smallholder Farmers dominate transaction counts; Cooperatives are expanding most quickly.
End User:
Margin structure shifts from yield-gain guarantees in commercial farming to research validation and public procurement.
- Agribusiness:Commercial farming operations seeking yield optimization and supply-chain emissions documentation. USDA conservation programs tie cost-share funding to documented precision-agriculture outcomes.
- Food Processing:Contract farming arrangements requiring standardized input application and harvest timing. European horticulture exporters in Spain and Italy face F-Gas Regulation compliance timelines for refrigerated transport fleets.
- Research Institutions:Field trial management and sensor validation services requiring 12-18 month certification timelines.
- Government Agencies:Public extension services and subsidy program administration through digital platforms.
Agribusiness commands revenue concentration; Food Processing shows the steepest expansion trajectory.
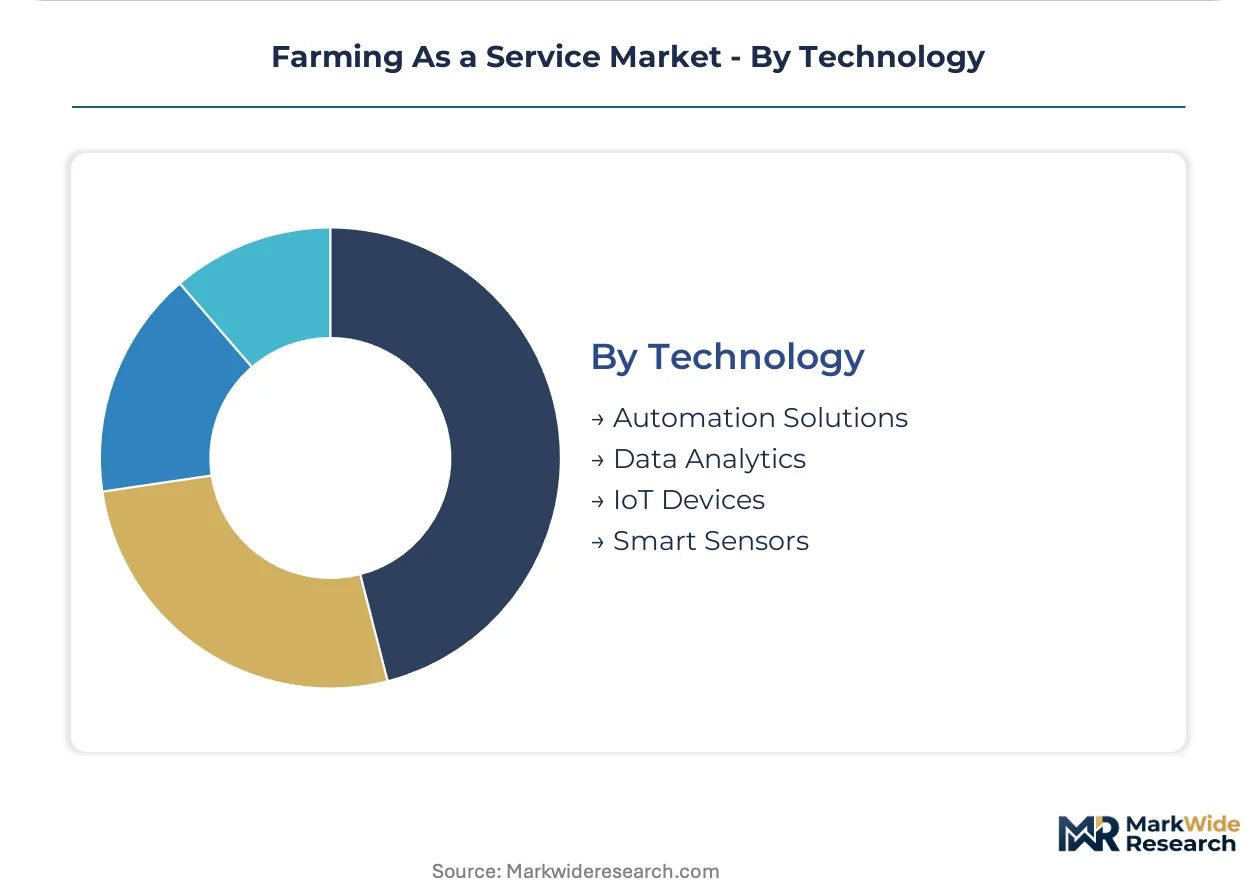
Technology:
Data latency now determines competitive positioning more than hardware specifications.
- Automation Solutions:Autonomous ground robots with hyperspectral cameras decentralizing crop-scouting operations. US Corn Belt mid-size operators pilot these for weed identification at sub-inch resolution.
- Data Analytics:Cloud-based prescription maps and yield forecasting models. Platform operators compete on analyst talent capable of translating telemetry into actionable agronomic recommendations.
- IoT Devices:Networked field hardware generating real-time telemetry streams. Edge computing convergence with satellite imagery reduces latency for automated pest-detection alerts.
- Smart Sensors:Soil-moisture and microclimate monitoring equipment. Proprietary telematics protocols from major manufacturers prevent seamless data portability between competing platforms.
IoT Devices anchor installed base; Automation Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's smallholder cooperatives drive platform adoption through bundled credit-input models, while Germany's precision-agriculture manufacturers anchor equipment supply chains for European carbon-accounting mandates. Divergent farm scales and regulatory frameworks shape distinct regional growth trajectories.
United States
Mid-size row-crop operators in the US Corn Belt pilot autonomous ground robots for sub-inch weed identification, while large agribusinesses lock into multi-year telemetry contracts. USDA conservation programs tie cost-share funding to documented precision-agriculture outcomes, tilting procurement toward validated service providers. The Mississippi River Valley corridor concentrates drone-spraying subscription services for soybean and corn operations.
Germany
GPS-guided machinery manufacturing clusters in Bavaria and Baden-Württemberg create supply concentration for European equipment-rental providers. The EU Green Deal's carbon-accounting mandates force agribusiness clients to adopt subscription platforms generating auditable field data. The F-Gas Regulation phases down hydrofluorocarbon use in refrigerated transport fleets, imposing retrofit costs on harvest logistics services.
India
Smallholder farmer cooperatives across Bihar and Uttar Pradesh access machinery through village-level aggregators and pay-per-use platforms constrained by capital barriers. The PLI scheme for agricultural drones accelerates domestic manufacturing incentives, reducing hardware costs for agritech startups deploying aerial imaging across the Indo-Gangetic Plain. Farmer producer organizations with 10,000-plus members now contract directly with soil-testing subscription services.
Spain
Horticulture exporters in Andalusia and Valencia face steep F-Gas Regulation compliance timelines for refrigerated transport fleets serving subscription-based cold-chain logistics. Water-stressed farming regions concentrate demand for cloud-connected soil-moisture telemetry replacing calendar-based irrigation schedules. The Guadalquivir Valley anchors precision-agriculture platform deployment for olive and citrus operations.
Australia
The Murray-Darling Basin drives adoption of irrigation services integrating real-time soil-moisture telemetry for water-stressed broadacre farming. Edge computing convergence with satellite imagery reduces latency for automated pest-detection alerts in wheat and canola belts. Queensland's sugarcane districts pilot bundled crop management subscriptions combining agronomic advice with input procurement.
Farming As a Service Market Key Industry Players
Top-tier vendors anchor multi-year telemetry contracts with large agribusiness clients, while emerging-market specialists compete through bundled credit-input-advisory subscriptions for smallholder cooperatives. The vendor base stratifies across captive telematics networks, precision-guidance data layers, and digital-native platform operators. Strategic archetypes include equipment manufacturers monetizing recurring software revenue, agritech startups bundling financial services, and IT consultancies integrating cloud analytics. Dominant competitive moves encompass geographic expansion into underpenetrated smallholder markets and portfolio diversification toward outcome-based service level agreements.
Within the equipment-manufacturer tier, Deere & Company and AGCO Corporation represent legacy machinery producers transitioning toward subscription revenue models through captive telematics networks. Among precision-agriculture specialists, Trimble Inc. exemplifies data-layer providers competing on guidance-system specialization for row-crop operators. Apollo Agriculture occupies a position within the emerging-market agritech archetype, bundling credit, inputs, and digital advisory into single subscription products for smallholders across East Africa and South Asia.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| Mahindra & Mahindra Ltd. |
| AGCO Corporation |
| Apollo Agriculture |
| IBM Corporation |
| Accenture |
| BigHaat |
| Taranis |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon-accounting mandates are forcing agribusiness procurement officers toward subscription platforms that generate auditable field data, compelling equipment manufacturers to reconfigure production lines for telemetry-integrated machinery and compressing margin structures for non-compliant hardware tiers.
Pricing Analysis
Capacity additions in India's drone manufacturing sector are reshaping price floors for aerial imaging subscriptions across the Indo-Gangetic Plain. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by data latency guarantees and after-sales agronomist support. Cost compression in economy tiers is intensifying because domestic PLI-subsidized hardware reduces entry barriers for agritech startups. Smallholder cooperatives in Bihar and Uttar Pradesh exhibit the highest price sensitivity, while large US Corn Belt agribusinesses prioritize premium tiers for multi-year telemetry lock-in.
Supply Chain Analysis
Direct-to-cooperative channels handle smallholder demand aggregation across India's farmer producer organizations. Manufacturing clusters in Germany, the United States, and India supply GPS-guided machinery and sensor hardware. Component sourcing draws from Taiwanese semiconductor foundries, South Korean battery cell producers, and Chinese rare earth processors. Single-source vulnerability in precision-guidance chipsets creates exposure to export control disruptions. Distribution runs through equipment-rental consortia and digital-native platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
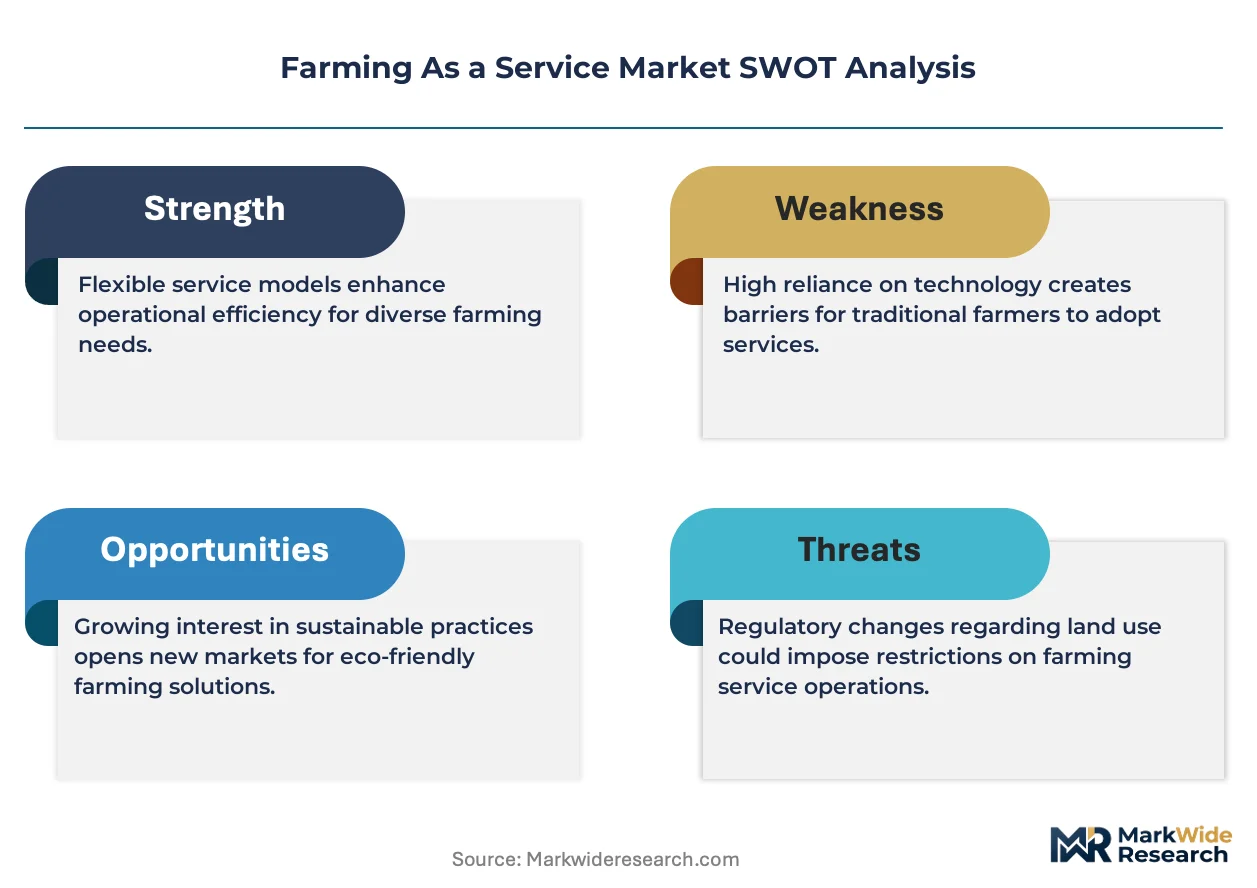
This market reads as a late-cycle quality story. Procurement officers at European agribusinesses now mandate auditable yield data as a baseline specification, elevating providers with certified telemetry networks over commodity equipment lessors.
For Market Incumbents: Deploy captive telematics network extensions to defend against digital-native entrants bundling credit and advisory. Backward integration into edge-computing hardware manufacturing secures supply continuity for real-time inference engines. Certification investment for EU F-Gas Regulation compliance protects European cold-chain logistics revenue pools from retrofit cost shocks.
For New Entrants and Emerging Players: Mobile-first platform distribution through village-level aggregators in India's eastern states offers the most penetrable white-space corridor. Bundled credit-input-advisory subscriptions for marginal farmers with sub-hectare holdings remain underserved by incumbent equipment manufacturers. Direct-to-cooperative sales models bypass capital-intensive dealership networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-agriculture data-layer specialists possessing validated yield-gain algorithms. Five-to-ten-year viability hinges on regulatory tailwinds for carbon-accounting standardization. Watch for USDA conservation program expansions tying cost-share funding to documented precision-agriculture outcomes as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Network Expansion | Captive data infrastructure locks large agribusiness into recurring revenue streams under EU Green Deal mandates. |
| Drone Manufacturing Scale-Up | Domestic PLI scheme incentives in India reduce hardware costs for aerial imaging service deployment. |
| Edge Computing Integration | On-field inference engines collapse latency for automated pest-detection alerts in water-stressed regions. |
| Cooperative Procurement Partnerships | Farmer producer organizations with 10,000-plus members negotiate volume discounts and outcome-based service agreements. |
| F-Gas Compliance Retrofit | Refrigerated transport fleet upgrades preserve European operating licenses for harvest logistics providers. |
Research Approach
Bottom-up smallholder cooperative modeling reconciled against top-down precision-agriculture equipment production tracking forms the analytical core of this study. Primary interviews with agritech platform founders, agricultural extension officers, cooperative procurement managers, and precision-guidance hardware engineers were validated against secondary sources including USDA conservation program filings, EU F-Gas Regulation compliance databases, India's PLI scheme beneficiary disclosures, and customs records for GPS-guided machinery imports.
Historical trendline analysis of subscription penetration rates across farm scale categories informed the projection framework. Segmentation dimensions modeled include service type, customer type, end-user application, and technology integration tier, with regional regulatory cluster overlays for carbon-accounting mandate intensity. CAGRs were derived from fitted adoption curves for telemetry-enabled equipment, stress-tested against input cost volatility scenarios and smallholder credit access constraints.
The model assumes a particular technology adoption path; alternative pathways for autonomous ground robot deployment would alter the outlook. Forecasts reflect base-case assumptions regarding PLI scheme continuity, EU Green Deal enforcement timelines, and soil-moisture telemetry reliability thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Agricultural Drones Market