
 Agricultural Drones Market | 2026-2036
Agricultural Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Drones Market Analysis
Precision viticulture and orchard management is broadening the addressable base beyond row-crop monocultures. DJI dominates hardware supply chains through manufacturing scale and integrated flight-control ecosystems. XAG Co., Ltd. anchors spraying specialization across East Asian and Latin American markets with payload-optimized multirotor platforms. Yamaha Motor Co., Ltd. sustains fixed-wing dominance in Japanese rice paddy operations through decades of aerial application heritage.
Agricultural drones are unmanned aerial vehicles engineered for farm-specific missions, typically integrating multispectral cameras, LiDAR, or variable-rate liquid dispersal systems with GPS-guided flight paths and real-time telemetry. Their primary commercial purpose centers on reducing input waste while generating sub-field resolution data for agronomic decision-making. Multirotor configurations lead in near-field maneuverability for targeted spraying and crop scouting, while fixed-wing platforms occupy large-acreage mapping and soil analysis where endurance and coverage speed matter. Machine learning integration within sensor suites is the fastest-expanding technology dimension, enabling automated pest detection and yield prediction without manual image interpretation.
The FAA governs commercial drone operations in the United States through Part 107 certification requirements and ongoing beyond-visual-line-of-sight rulemaking that directly shapes fleet scalability for American agronomists. EASA's EU-wide framework for unmanned aircraft operations, coupled with REACH chemical handling standards, dictates equipment compliance and spray authorization protocols across European cooperative societies. Stakeholders must monitor evolving BVLOS regulatory clarity and chemical dispersal restrictions as these frameworks will determine which technology configurations achieve operational scale in priority agricultural regions.
Market Dynamics
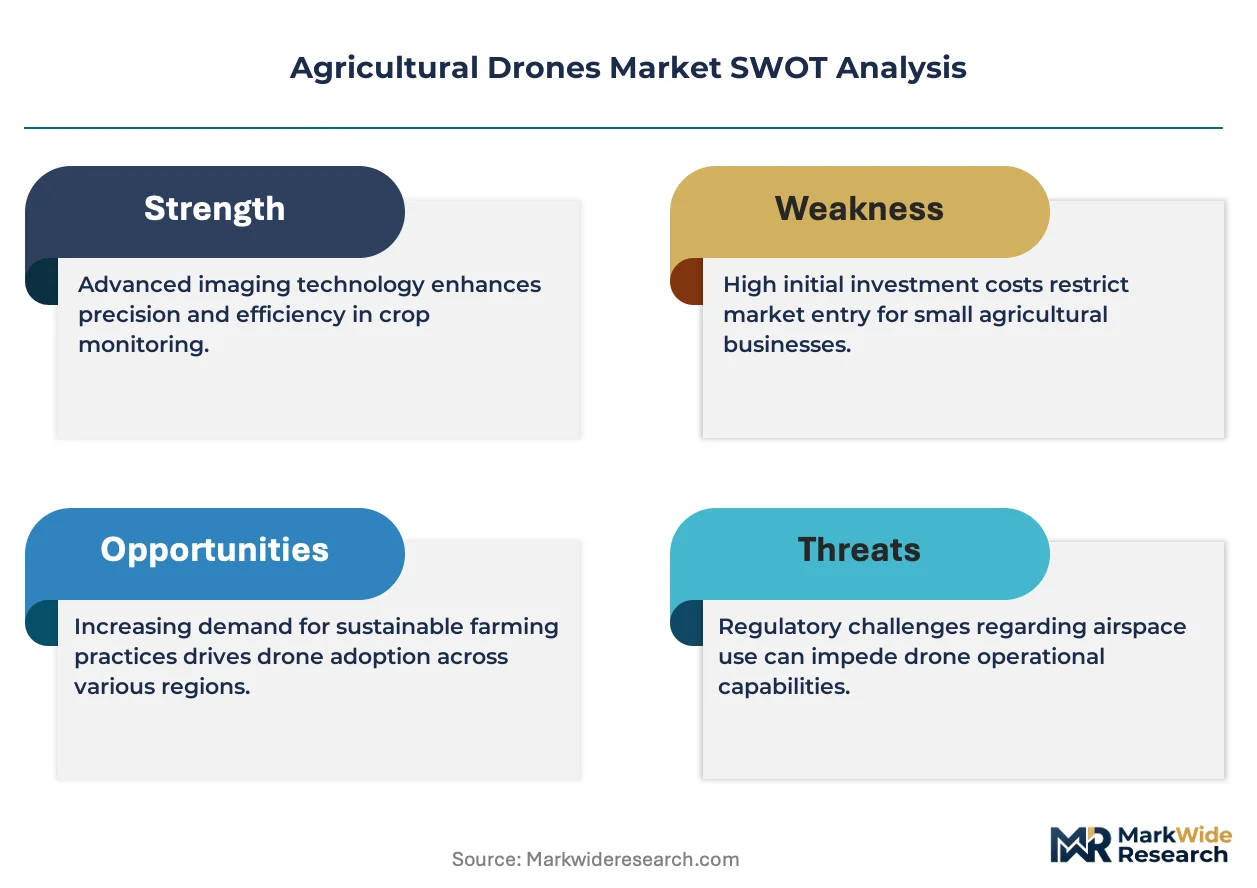
Beyond-visual-line-of-sight rulemaking by the FAA and EASA is compressing operational scalability timelines for commercial spraying fleets, forcing equipment procurement decisions ahead of regulatory clarity.
Growth Catalysts
- EU F-Gas restrictions:Chemical dispersal limitations under REACH and F-Gas Regulation are mandating precision application equipment upgrades across European cooperative societies.
- Multispectral imaging:Sub-field resolution data generation is converging with machine learning pipelines to automate pest detection without manual image interpretation.
- Brazil's soybean belt:Cooperative societies in Mato Grosso are driving fleet procurement of payload-optimized multirotor platforms for variable-rate spraying.
Market Restraints
- Lithium battery supply:Cell manufacturing concentration in East Asia creates input cost volatility and procurement lead-time risk for drone OEMs.
- BVLOS uncertainty:Pending FAA beyond-visual-line-of-sight rulemaking generates capital deployment hesitation among American agronomists.
- Fixed-wing substitution:Manned aerial application services in Japanese rice paddies retain cost advantages for large-scale operations.
Strategic Opportunities
- Precision viticulture:Orchard management and vineyard monitoring applications remain underpenetrated relative to row-crop monocultures.
- Swarm coordination software:Multiple-aircraft mission planning is converging with real-time telemetry to enable cooperative spraying across contiguous holdings.
- India's PLI scheme:Production-linked incentives for drone manufacturing are attracting component localization investments.
Industry Challenges
- Part 107 certification:Pilot qualification timelines limit fleet expansion velocity for American commercial operators.
- Sensor integration complexity:LiDAR and multispectral payload interoperability with legacy farm management software requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Drones Market |
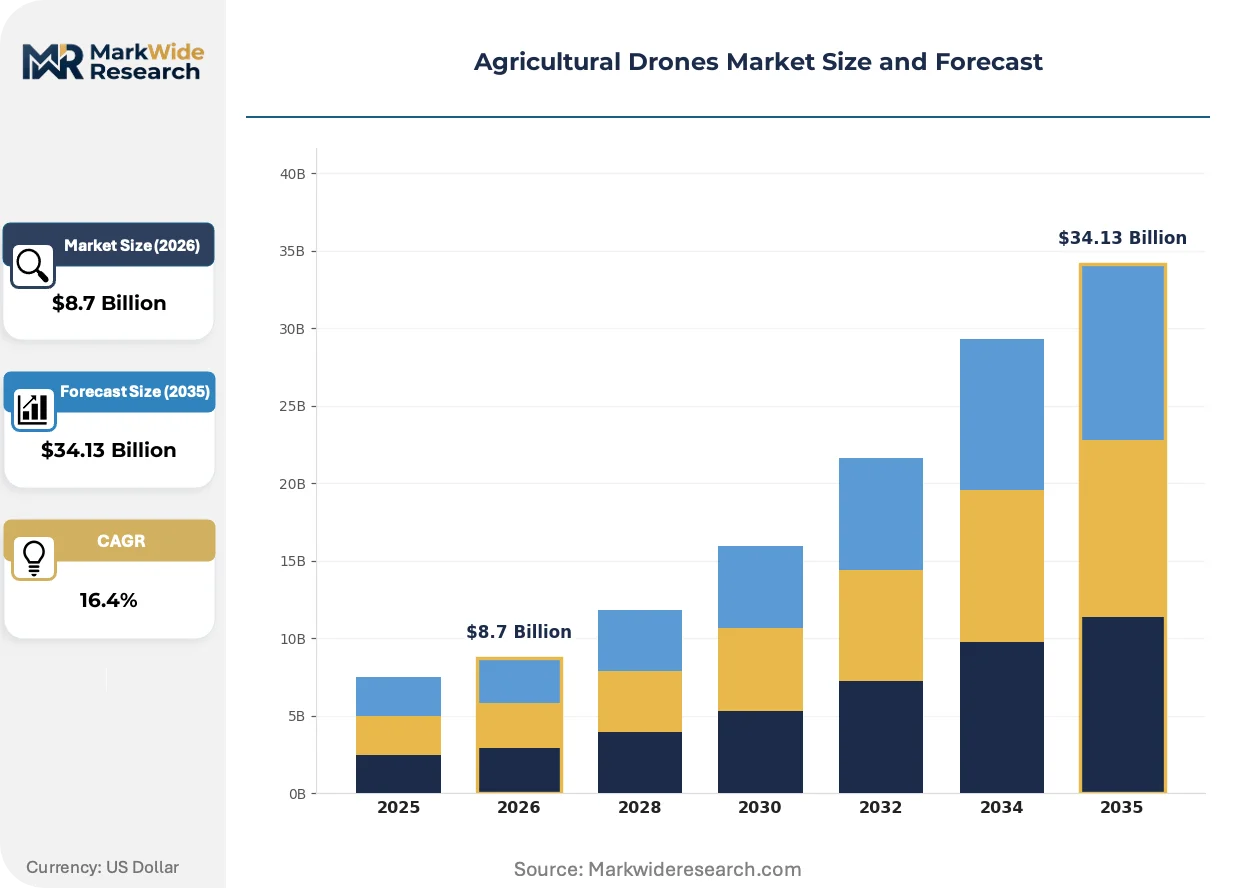
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: Fixed Wings, Multirotors, Hybrid, UAVs Application: Crop Monitoring, Soil Analysis, Spraying, Mapping End User: Farmers, Agronomists, Cooperative Societies, Research Institutions Technology: GPS, Machine Learning, IoT, Sensors |
| Companies Covered | DJI, Parrot, Yamaha Motor Co., Ltd., PrecisionHawk, XAG Co., Ltd., Trimble Inc., AgEagle Aerial Systems Inc., AeroVironment Inc., Sentera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Drones Market Emerging Trajectories
Machine learning integration within flight-control ecosystems is compressing the gap between data capture and agronomic decision execution, reshaping equipment specification priorities.
Edge computing architectures for onboard image processing are converging with GPS-guided variable-rate dispersal systems to enable real-time prescription adjustments during flight. Large-scale farming operations in Brazil and Argentina are adopting these platforms for immediate pest response. This convergence is eliminating the latency between detection and treatment that characterized ground-based scouting workflows.
EASA's unmanned aircraft operations framework, coupled with REACH chemical handling standards, is dictating spray authorization protocols and equipment compliance specifications across European markets. Agricultural cooperatives in France and Germany are restructuring procurement criteria to satisfy dual certification requirements. Fixed-wing platform manufacturers are adapting airframe designs to accommodate these dispersal restrictions.
Service-based fleet access models are displacing direct equipment ownership among mid-sized American agronomists. Regional dealer networks are unbundling hardware sales from per-acre spraying contracts to capture recurring revenue streams. This pattern is most visible in the Midwest corn belt, where capital constraints favor operational expenditure structures over asset ownership.
Agricultural Drones Market Segmentation
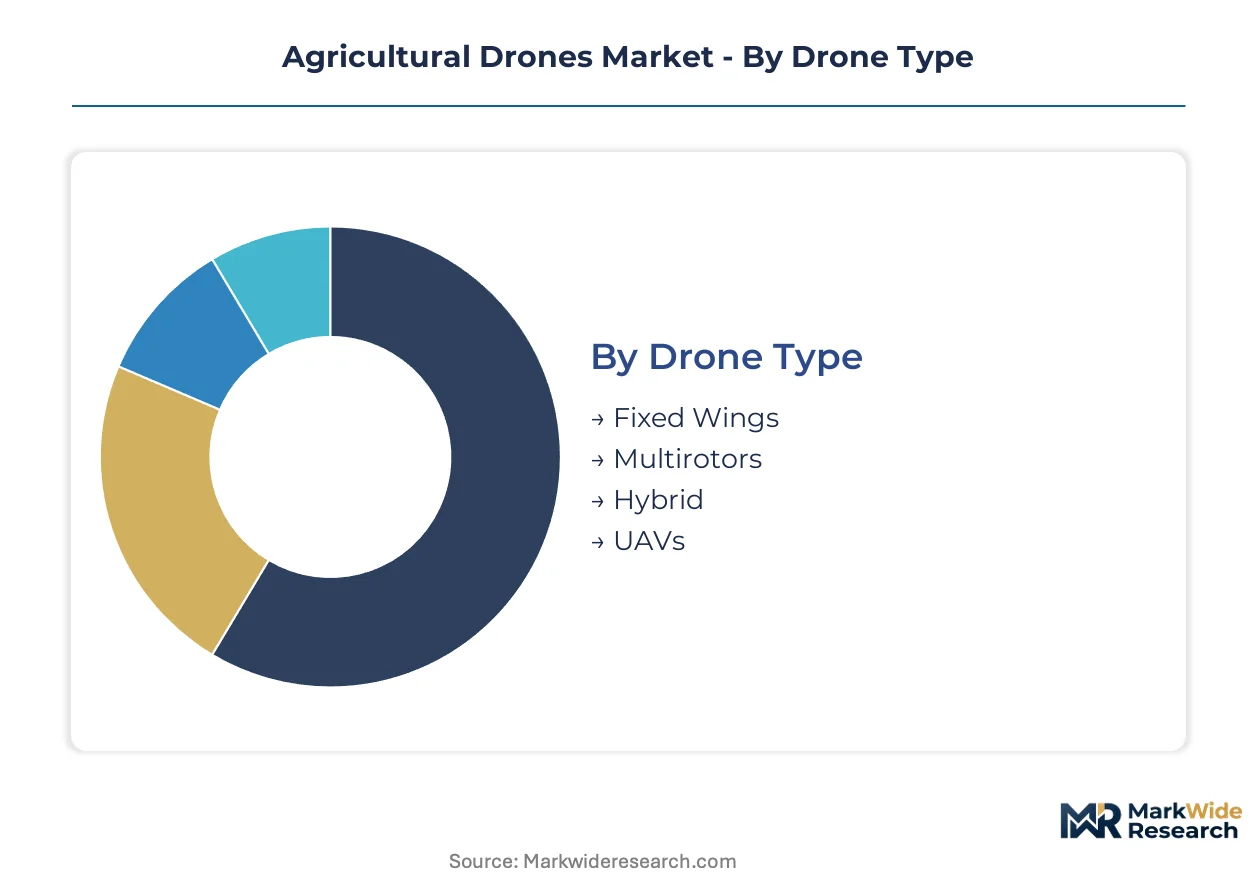
Equipment specification priorities diverge sharply across operational contexts, with payload capacity and endurance requirements dictating procurement patterns. Technology integration depth separates premium configurations from commodity hardware, while end-user sophistication determines software complexity and service bundling preferences.
Drone Type:
Capital intensity peaks with hybrid configurations that combine vertical takeoff capability with extended range, demanding dual propulsion engineering and redundant flight-control systems.
- Multirotors:Vertical takeoff and landing capability with near-field maneuverability suits targeted spraying and crop scouting in irregular field geometries. Demand concentrates in Brazil's Mato Grosso soybean belt, where cooperative societies prioritize payload-optimized platforms for variable-rate chemical dispersal under ANVISA aerial application mandates.
- Fixed Wings:Extended endurance and coverage speed optimize large-acreage mapping and soil analysis where straight-line efficiency dominates operational economics. Japanese rice paddy operations sustain procurement through decades of aerial application heritage, though cost pressure from manned services limits fleet expansion velocity.
- Hybrid:Dual-mode propulsion systems merge VTOL flexibility with fixed-wing range, commanding premium pricing for specialized topography applications.
- UAVs:Military-derived platforms adapted for agricultural missions carry hardened communications and extended-range telemetry for remote holdings.
Most installed capacity flows through multirotor configurations. Expansion is steepest in hybrid systems gaining share fastest among large-scale operations.
Application:
Revenue concentration tilts toward spraying missions where chemical input savings generate immediate payback calculations for procurement committees.
- Spraying:Variable-rate liquid dispersal systems with GPS-guided flight paths and real-time telemetry enable precision chemical application. EU F-Gas restrictions under REACH and evolving chemical dispersal limitations are mandating equipment upgrades across European cooperative societies in France and Germany.
- Crop Monitoring:Multispectral imaging generates sub-field resolution data for agronomic decision-making, converging with machine learning pipelines to automate pest detection without manual interpretation. Large-scale farming operations in Brazil and Argentina deploy these systems for immediate pest response, eliminating latency between detection and treatment.
- Soil Analysis:LiDAR and spectral payload integration supports nutrient mapping and moisture profiling for prescription agriculture planning.
- Mapping:Orthomosaic generation and elevation modeling serve drainage design and insurance documentation requirements.
Spraying commands the dominant revenue share. Crop monitoring represents the fastest-growing trajectory as sensor costs decline and interpretation automation matures.
End User:
Customer sophistication spans from individual owner-operators to institutional procurement committees with dedicated technical evaluation staff.
- Cooperative Societies:Pooled capital enables fleet-scale procurement and shared maintenance infrastructure, driving volume discounts and standardized training protocols. Brazilian and Argentine cooperative structures are expanding multirotor adoption for contiguous holding coverage.
- Farmers:Individual owner-operators favor service-based access models over direct equipment ownership, particularly in the American Midwest corn belt where capital constraints favor operational expenditure structures.
- Agronomists:Technical consultants prioritize data integration capabilities and middleware compatibility with legacy farm management software.
- Research Institutions:Academic and government experimental stations demand open-architecture platforms for custom sensor integration and algorithm development.
Cooperative societies deploy the largest fleet concentrations. Agronomists are expanding most quickly as service providers bundle analytics with flight operations.
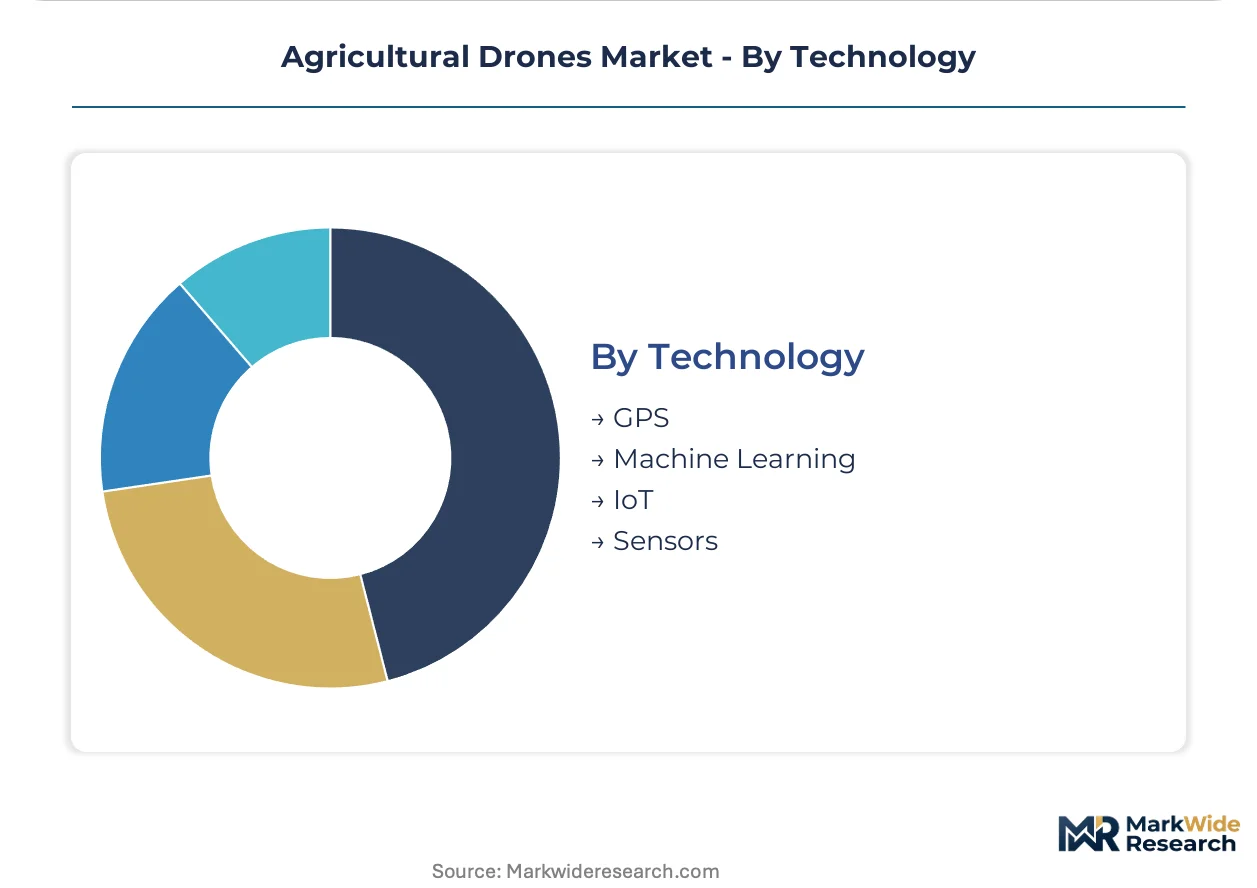
Technology:
Integration complexity escalates with sensor fusion requirements, separating platforms capable of standalone decision execution from data-capture-only configurations.
- Sensors:Multispectral, thermal, and LiDAR payload interoperability demands custom middleware development for legacy farm management software compatibility. Edge computing architectures for onboard image processing are converging with dispersal systems to enable real-time prescription adjustments during flight.
- Machine Learning:Automated pest detection and yield prediction algorithms compress the gap between data capture and agronomic decision execution. This dimension is expanding most quickly as training datasets mature and inference latency declines.
- GPS:Centimeter-level positioning accuracy enables sub-field resolution application and automated flight path adherence.
- IoT:Real-time telemetry and fleet coordination protocols support swarm mission planning across contiguous holdings.
Sensor packages constitute the primary hardware differentiation. Machine learning integration is climbing the fastest as equipment specification priorities shift toward autonomous decision capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as drone OEMs migrate assembly toward jurisdictions with streamlined unmanned aircraft certification pathways and localized component incentive schemes.
United States
Midwestern corn belt operators favor service-based fleet access over direct ownership, compressing dealer network economics. FAA Part 107 certification requirements and pending beyond-visual-line-of-sight rulemaking generate capital deployment hesitation among commercial agronomists. Chicago-based dealer networks are restructuring per-acre spraying contracts to capture recurring revenue from capital-constrained farmers.
Brazil
Cooperative societies in Mato Grosso drive multirotor procurement for soybean belt variable-rate spraying. ANVISA aerial application regulations mandate precision equipment specifications that reshape fleet procurement criteria. São Paulo industrial corridors host expanding maintenance infrastructure for payload-optimized platforms serving contiguous agricultural holdings.
China
Domestic manufacturing scale advantages anchor global hardware supply chains through integrated flight-control ecosystems. MIIT unmanned aircraft standards and dual carbon goals pressure domestic OEMs toward energy-efficient propulsion designs. Shenzhen manufacturing clusters concentrate LiDAR and multispectral sensor assembly for export markets.
Japan
Fixed-wing platforms sustain penetration in rice paddy operations through decades of aerial application heritage, though manned services retain cost advantages at scale. METI agricultural modernization programs subsidize precision equipment adoption among aging farmer populations. Nagoya industrial basins maintain specialized airframe fabrication for VTOL-fixed-wing hybrid configurations.
Germany
REACH chemical handling standards and F-Gas Regulation mandate precision dispersal equipment upgrades across cooperative societies. EASA unmanned aircraft operations framework dictates spray authorization protocols that restructure procurement criteria. Bavarian precision engineering clusters adapt sensor fusion middleware for legacy farm management software interoperability.
Agricultural Drones Market Vendor Landscape
Capacity expansion dominates the current landscape as established OEMs scale manufacturing footprints to capture procurement volumes from Brazil's cooperative societies and India's emerging PLI-subsidized production zones. The vendor base stratifies across three tiers: integrated flight-control ecosystem providers, payload-optimized spraying specialists, and regional hardware assemblers. Two strategic archetypes define competitive positioning: manufacturing-scale defenders leveraging component cost advantages, and software-centric challengers bundling analytics with flight operations. Geographic expansion and technology licensing represent the dominant competitive moves, with players securing local certification partnerships to accelerate market access.
Among Asia-Pacific hardware fabricators, DJI and XAG Co., Ltd. exemplify divergent specialization vectors within the manufacturing-scale tier. DJI anchors integrated ecosystem provision through flight-control software and sensor payload interoperability. XAG Co., Ltd. occupies a spraying-specialist position optimized for East Asian and Latin American chemical dispersal applications. Yamaha Motor Co., Ltd. represents the heritage-fixed-wing archetype, sustaining decades-long positioning in Japanese rice paddy operations through airframe durability and established dealer service networks.
| Leading Market Players |
|---|
| DJI |
| Parrot |
| Yamaha Motor Co., Ltd. |
| PrecisionHawk |
| XAG Co., Ltd. |
| Trimble Inc. |
| AgEagle Aerial Systems Inc. |
| AeroVironment Inc. |
| Sentera |
| Others |
Supply Flow & Price Mechanics
EU F-Gas restrictions on chemical dispersal equipment gate qualified supply access and premium-tier pricing for precision spraying platforms serving European cooperative societies. Manufacturers without REACH-certified dispersal systems face exclusion from procurement shortlists, compressing margin structures for non-compliant hardware while certified suppliers capture pricing premiums.
Pricing Analysis
Distributor margins in agricultural drone supply chains typically absorb 15-25 points before reaching end-users, with volume discounts compressing this spread for cooperative society fleet orders. Three-tier pricing structure across premium, standard, and economy levels separates GPS-guided variable-rate platforms from basic crop scouting configurations, with certification grade under EU F-Gas and ANVISA mandates driving the widest price differentiation. Cost compression in economy-tier multirotors is intensifying because lithium cell procurement lead-time volatility forces OEMs to absorb input spikes rather than pass through. Cooperative societies exhibit lowest price sensitivity due to pooled capital structures, while individual Midwestern farmers demonstrate highest elasticity, favoring service-based access over ownership.
Supply Chain Analysis
Trans-Pacific freight cost volatility has reshored component sourcing priorities for North American and European OEMs seeking tariff insulation. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen clusters dominating flight-control ecosystem fabrication and Nagoya industrial basins sustaining specialized airframe production. Raw material dependencies center on lithium carbonate, rare-earth magnets, and carbon-fiber composites, with cell manufacturing concentration in East Asia creating single-source vulnerability for battery pack assembly. Distribution runs through regional dealer networks in the American Midwest and cooperative procurement consortia in Brazil's Mato Grosso, with service bundling displacing pure hardware transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme subsidies and Brazil's ANVISA regulatory clarity attract manufacturing investment away from EU markets facing F-Gas compliance cost escalation.
For Market Incumbents: Cement manufacturing-scale advantages through backward integration into LiDAR sensor production and flight-control chipset sourcing, insulating margin structures from East Asian component volatility. Prioritize certification investment for EU F-Gas and REACH dual compliance to defend positioning against software-centric challengers bundling analytics with flight operations. For New Entrants and Emerging Players: Enter via precision viticulture and orchard management applications, the most penetrable white-space relative to row-crop monoculture saturation. Target service-based fleet access models in the American Midwest corn belt, where capital-constrained farmers favor operational expenditure structures over asset ownership, deploying per-acre spraying contracts through regional dealer partnerships. For Investors and Strategic Acquirers: Roll-up economics work for software-centric analytics platforms because cooperative societies and agronomist service providers demand middleware integration with legacy farm management systems, creating fragmented vendor bases ripe for consolidation. Monitor BVLOS regulatory clarity from FAA and EASA as the critical inflection signal determining which hardware configurations achieve operational scale.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment for Dual Compliance | REACH and F-Gas alignment unlocks procurement access across French and German cooperative societies. |
| Swarm Coordination Software Development | Real-time telemetry integration enables cooperative spraying across contiguous Brazilian holdings. |
| Component Localization Under PLI Schemes | India's production-linked incentives attract battery pack and sensor assembly investments. |
| Service-Based Fleet Access Model Expansion | Per-acre spraying contracts capture recurring revenue from capital-constrained Midwestern farmers. |
| Machine Learning Pipeline Integration | Automated pest detection compresses decision latency for Brazilian soybean belt operators. |
Methodological Framework
Direct dialogue with drone OEM product managers, cooperative society procurement committees, agronomist service providers, and FAA/EASA regulatory affairs specialists grounded qualitative assessments in operational reality. Secondary validation drew from SEC filings of listed hardware manufacturers, ANVISA aerial application regulatory databases, EU REACH chemical handling compliance registries, and customs trade data for lithium battery component flows. Bottom-up fleet deployment estimates across Brazil's Mato Grosso, the American Midwest, and Japanese rice paddy regions were triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Bottom-up modeling segmented volume and value projections across multirotor, fixed-wing, and hybrid configurations, with application splits for spraying, crop monitoring, soil analysis, and mapping missions. End-user stratification captured cooperative societies, individual farmers, agronomists, and research institutions, while technology integration depth separated sensor-only platforms from machine learning-enabled decision systems. CAGRs were derived from equipment replacement cycles, regulatory adoption timelines, and chemical input cost savings payback calculations across the analysis window.
Inputs from OEM production forecasts and cooperative procurement pipeline disclosures were available through the study window; gaps in real-time BVLOS rulemaking progress from FAA and EASA introduce uncertainty bands around fleet scalability assumptions. Forecasts reflect documented segmentation drivers and regional regulatory trajectories, with lithium supply concentration, pending aviation rulemaking, and chemical dispersal restriction evolution representing primary revision risks. Stakeholders should weight assumptions against their own operating context and regional certification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market