
 Global Agriculture Supply Chain Management Market | 2026-2036
Global Agriculture Supply Chain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agriculture Supply Chain Management Market Foresight
Smallholder cooperatives is collapsing as the dominant buyer archetype while large agribusiness conglomerates and vertically integrated food processors capture disproportionate platform investment. Deere and Company anchors its position through precision agriculture telemetry that feeds directly into supply chain orchestration layers. SAP SE competes by extending enterprise resource planning modules into farm-level contract management and sustainability scoring.
Agriculture supply chain management encompasses the digital coordination of input sourcing, cultivation monitoring, harvest logistics, storage, processing, and distribution through integrated software platforms that typically leverage IoT sensor networks, blockchain ledgers, and predictive analytics algorithms. Its primary commercial purpose is to reduce post-harvest loss, ensure batch-level traceability, and optimize working capital across geographically dispersed operations. Farm management software and traceability applications command the deepest margin pools as buyers prioritize field-to-fork visibility over generic inventory tools. Cloud-based deployment is displacing on-premises installations fastest among mid-market crop producers seeking lower capital commitments.
The EU Green Deal and its Farm to Fork Strategy mandate stricter pesticide residue documentation and carbon footprint disclosures, compelling platform vendors to embed compliance modules directly into workflow engines. The USDA enforces Country of Origin Labeling and organic certification standards that shape data architecture requirements for North American exporters. China's GB standards and dual carbon goals from MEE impose parallel traceability obligations on inbound agricultural commodities. Stakeholders must monitor whether regulatory divergence between major import jurisdictions fragments platform standardization or creates openings for modular compliance engines.
Market Dynamics
Cloud-based traceability platforms are compressing adoption cycles across agricultural value chains as multi-origin procurement complexity forces trading houses to abandon fragmented legacy systems for unified orchestration layers.
Growth Catalysts
- EU Green Deal compliance mandates:The Farm to Fork Strategy tightens pesticide residue documentation and carbon footprint reporting requirements, compelling platform vendors to embed compliance modules directly into workflow engines.
- Brazilian port logistics digitization:Soybean and corn export corridors are digitizing warehouse receipt systems to reduce post-harvest losses, concentrating demand for integrated supply chain management solutions.
- IoT sensor convergence with blockchain:Field-level telemetry networks feeding immutable ledgers enable batch-level traceability from cultivation through distribution, satisfying buyer transparency requirements.
Market Restraints
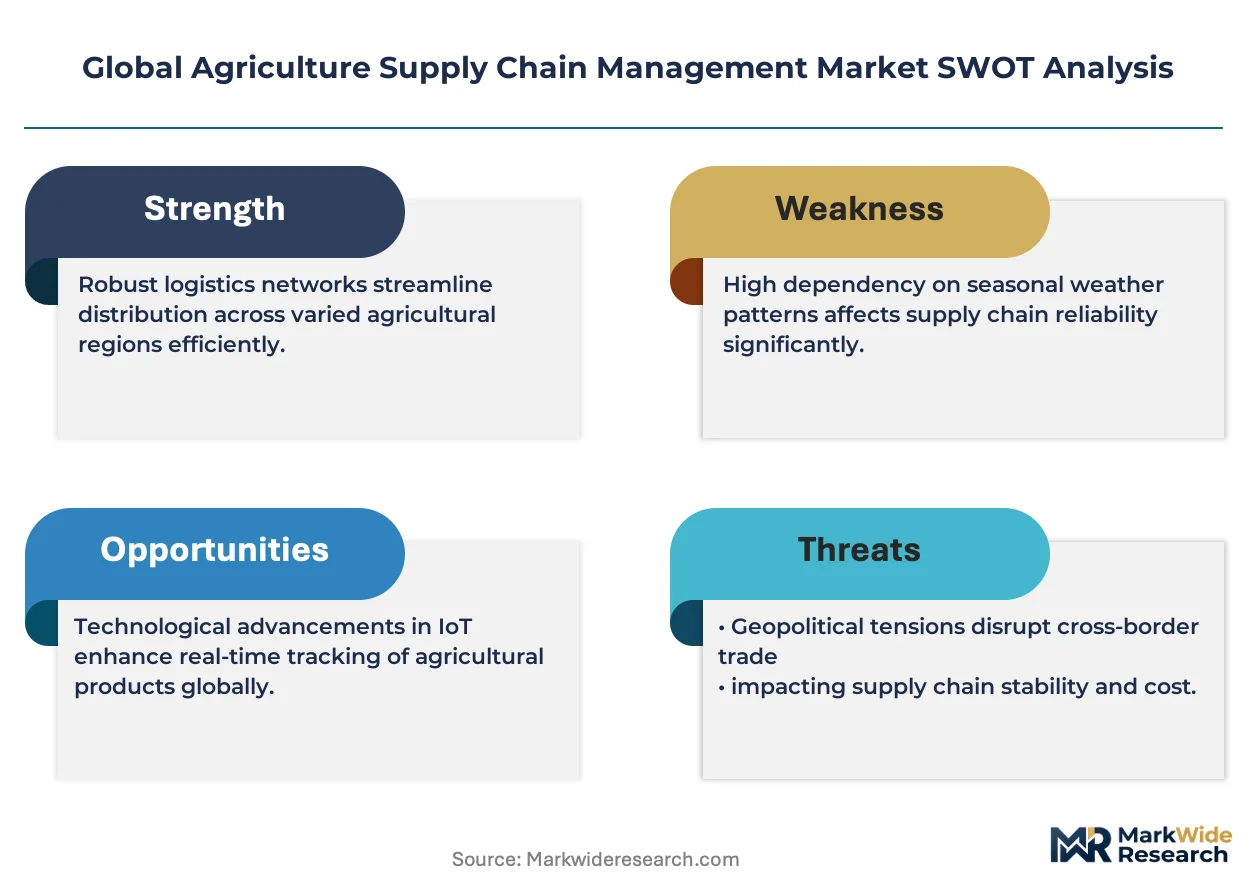
- High capital intensity of sensor deployment:Smallholder cooperatives lack balance sheet capacity to fund comprehensive IoT infrastructure across dispersed cultivation plots.
- Regulatory fragmentation across import jurisdictions:Divergent documentation standards between EU Green Deal requirements, USDA Country of Origin Labeling, and China's GB standards force redundant compliance architectures.
- Limited rural connectivity infrastructure:Remote agricultural regions in Sub-Saharan Africa and Southeast Asia lack reliable broadband coverage necessary for real-time data transmission.
Strategic Opportunities
- Underpenetrated Indian agricultural sector:The FSSAI's tightening traceability mandates for domestic food processors create first-mover advantages for platform vendors establishing localized compliance engines.
- Carbon credit verification integration:MEE's dual carbon goals in China and parallel EU emissions trading schemes create demand for supply chain modules that quantify and verify agricultural carbon sequestration.
- AI-driven predictive logistics:Machine learning algorithms converging with satellite imagery enable harvest timing optimization and transport routing that reduces spoilage in temperature-sensitive commodity flows.
Industry Challenges
- Scarce agritech-IT hybrid talent:Platform vendors struggle to recruit professionals combining domain expertise in crop science with software architecture and data engineering capabilities.
- Legacy ERP integration complexity:Established farm management systems from incumbent vendors resist API standardization, forcing costly middleware development for unified data orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agriculture Supply Chain Management Market |
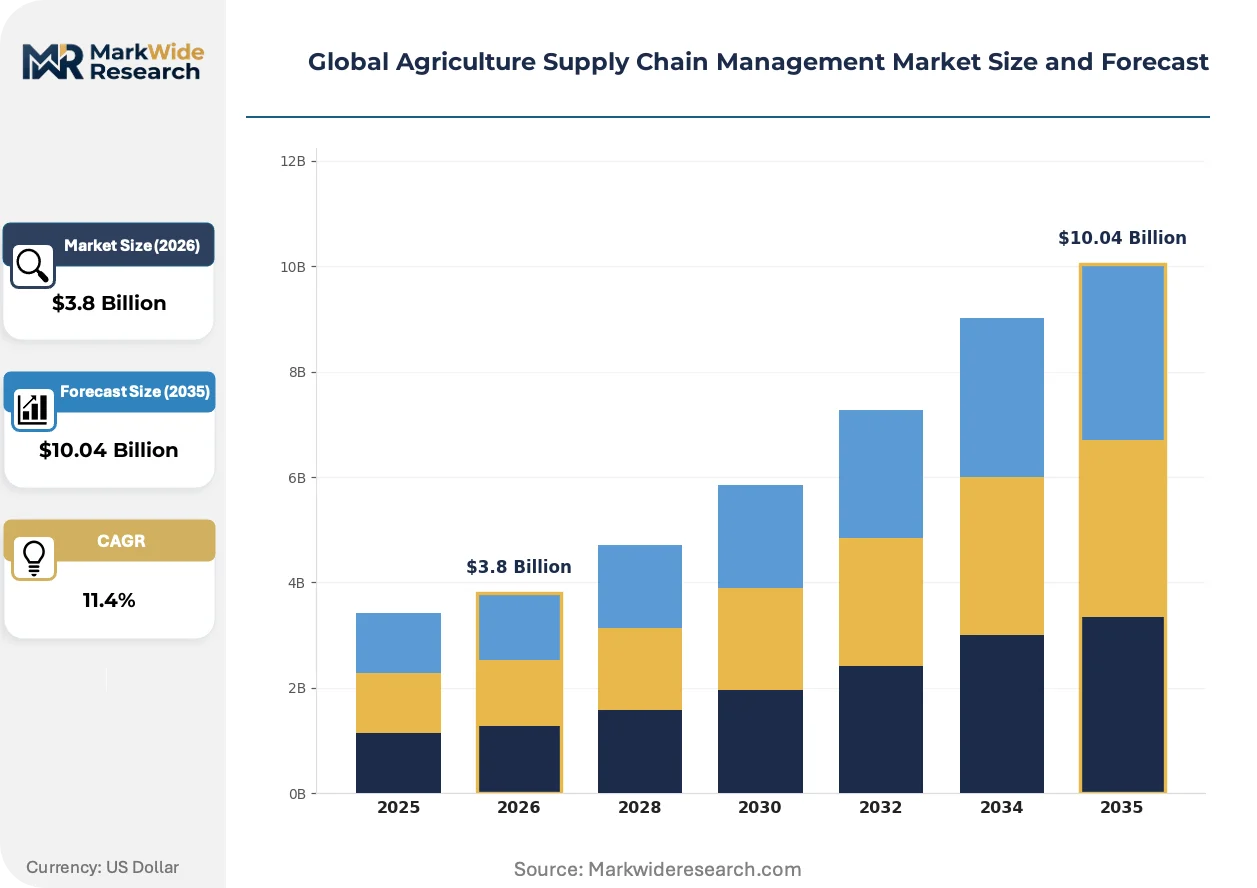
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Farm Management Software, Inventory Management, Transportation Management, Demand Forecasting, Quality Control End User: Crop Producers, Distributors, Warehousing Operators, Food Processing Units, Exporters Deployment Mode: Cloud-based, On-Premises, Hybrid, Edge Computing Application: Traceability, Inventory Optimization, Supplier Management, Logistics Planning, Risk Mitigation |
| Companies Covered | Deere and Company, Trimble Inc., SAP SE, Oracle Corporation, IBM Corporation, AGCO Corporation, Bayer AG, Descartes Systems Group, Raven Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agriculture Supply Chain Management Market Shifts & Advancements
Digital infrastructure is actively reshaping competitive positioning in agricultural supply chains as telemetry networks, automated compliance engines, and procurement centralization compress traditional coordination costs.
Blockchain-enabled provenance tracking is displacing paper-based chain-of-custody documentation across grain and oilseed trading. Large-scale cooperatives in Brazil and Argentina are adopting distributed ledger architectures at accelerating pace. This displacement eliminates reconciliation delays between port authorities, warehouse operators, and export inspectors.
REACH and CSRD disclosure requirements in Europe are forcing agricultural input suppliers to document chemical composition and lifecycle emissions across extended supply chains. The industrial consequence is mandatory data interoperability between farm management platforms and downstream food processors. Specialty crop exporters to EU markets are most affected, responding by pre-certifying entire cultivation batches before harvest.
Consolidated procurement by vertically integrated food processors is disintermediating independent grain traders from origin sourcing relationships. Direct contracting between processors and large-scale farming operations replaces spot-market intermediation. This pattern is most visible in North American corn and soybean value chains where protein processors and ethanol refiners capture upstream supply control.
Global Agriculture Supply Chain Management Market Segmentation
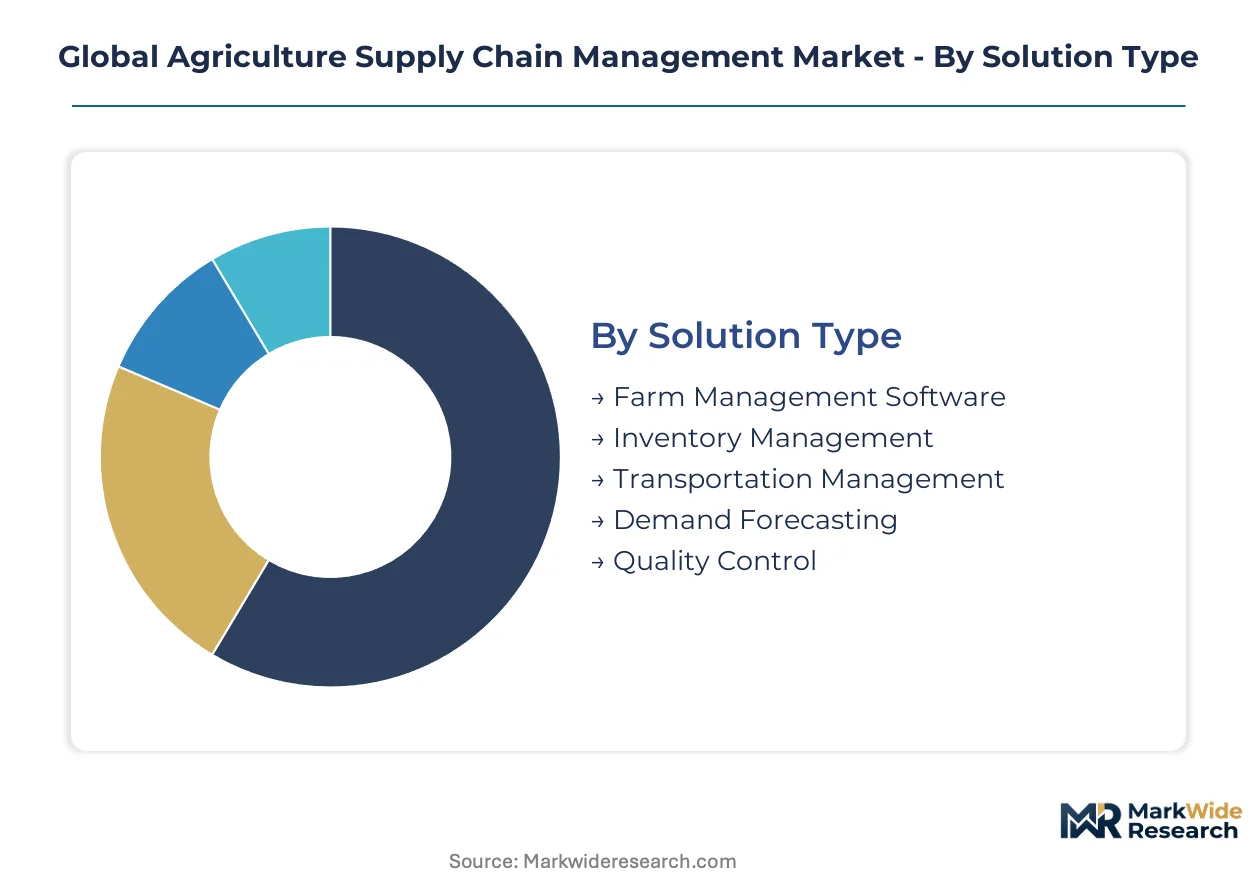
Agricultural supply chain platforms fragment across four critical dimensions. Solution architecture determines capital intensity and integration depth. Deployment mode shapes accessibility for smallholders versus conglomerates. End-user concentration dictates feature prioritization and pricing power.
Solution Type:
Farm management software and inventory tools flow through direct enterprise sales, while transportation and demand forecasting modules increasingly distribute via cloud marketplaces and system integrator channels.
- Farm Management Software:Telemetry-enabled platforms coordinate input sourcing, cultivation monitoring, and harvest scheduling through unified dashboards. Brazilian soybean cooperatives and North American corn operations concentrate procurement here as EU Green Deal compliance mandates force field-level data capture for pesticide documentation.
- Inventory Management:Warehouse receipt systems and silo-level tracking modules optimize working capital across geographically dispersed storage facilities. Argentine grain traders and Black Sea wheat exporters drive adoption to reduce post-harvest losses and enable commodity financing.
- Transportation Management:Route optimization and carrier coordination tools for bulk commodity logistics.
- Demand Forecasting:Predictive analytics modules converging satellite imagery with consumption pattern data.
- Quality Control:Batch-level testing documentation and certification management systems.
Farm management software dominates installed base. Demand forecasting is where expansion concentrates.
End User:
Cost tier stratification separates enterprise-grade platforms for vertically integrated processors from lightweight SaaS tools targeting independent distributors and mid-scale warehousing operators.
- Crop Producers:Large-scale farming operations and cooperative networks deploying precision agriculture telemetry. Brazilian corn and soybean producers, Ukrainian wheat growers, and Australian barley operations concentrate investment as digitization of origin sourcing accelerates.
- Food Processing Units:Protein processors, ethanol refiners, and oilseed crushers requiring upstream supply control. North American meatpackers and European dairy conglomerates drive demand for direct farm contracting modules that disintermediate spot-market traders.
- Distributors:Independent grain traders and agricultural input suppliers managing multi-origin procurement.
- Warehousing Operators:Port authorities and private silo operators digitizing receipt systems and inventory verification.
- Exporters:Trading houses navigating divergent documentation standards across EU, USDA, and Chinese import jurisdictions.
Food processing units command premium pricing tiers. Crop producers represent the steepest expansion trajectory as smallholder cooperatives collapse and large operations consolidate platform access.
Deployment Mode:
Volume concentration favors cloud architectures among mid-market producers, while on-premises and edge deployments retain share in remote regions with limited connectivity infrastructure.
- Cloud-based:Subscription models eliminating capital expenditure for sensor infrastructure and server deployment. Brazilian and Indian agricultural sectors show fastest uptake as FSSAI traceability mandates and port logistics digitization lower adoption barriers.
- Edge Computing:Localized data processing for real-time field telemetry in bandwidth-constrained environments. Sub-Saharan African cotton operations and Southeast Asian palm oil plantations deploy these architectures where rural broadband remains unreliable.
- On-Premises:Legacy installations among established agribusiness conglomerates with existing data center investments.
- Hybrid:Architectures splitting sensitive compliance data on-premises while leveraging cloud analytics.
On-premises systems retain installed base among incumbent conglomerates. Cloud-based deployment is gaining share fastest as trading houses abandon fragmented legacy systems.
Application:
Margin pools concentrate in traceability and inventory optimization as regulatory compliance and working capital efficiency drive procurement decisions.
- Traceability:Blockchain-enabled batch-level provenance tracking from cultivation through distribution. EU specialty crop exporters and Chinese inbound commodity traders mandate these capabilities to satisfy ECHA REACH documentation and MEE dual carbon disclosure requirements.
- Inventory Optimization:Dynamic positioning of commodities across storage networks to minimize spoilage and financing costs. Black Sea grain corridors and Brazilian port logistics digitization concentrate demand as warehouse receipt systems enable supply chain finance.
- Supplier Management:Contract lifecycle and sustainability scoring for direct farm relationships.
- Logistics Planning:Transport routing and carrier selection for temperature-sensitive flows.
- Risk Mitigation:Weather, price, and geopolitical exposure management through predictive modeling.
Traceability dominates compliance-driven procurement. Inventory optimization is where technology investment concentrates as post-harvest loss reduction delivers measurable ROI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos corridor underwrites Brazil's commanding position in agricultural supply chain digitization, handling over one-third of national grain exports through automated warehouse receipt systems.
Brazil
Soybean and corn export corridors drive cloud-based traceability adoption as trading houses abandon fragmented legacy systems for unified orchestration platforms. ANVISA's tightening documentation requirements for agricultural chemical residues force platform vendors to embed compliance modules directly into workflow engines. The Mato Grosso-Santos logistics axis concentrates investment as cooperatives digitize port logistics to reduce post-harvest losses.
United States
Protein processors and ethanol refiners demand upstream supply control through direct farm contracting modules that disintermediate spot-market traders. USDA Country of Origin Labeling and organic certification standards shape data architecture requirements for North American exporters. The Iowa-Illinois corn belt anchors precision agriculture telemetry deployment as Deere and Company feeds field-level data into supply chain orchestration layers.
China
GB standards and MEE dual carbon goals impose parallel traceability obligations on inbound agricultural commodities, compelling trading houses to document carbon footprints across extended supply chains. The Yangtze River Delta food processing clusters mandate batch-level provenance tracking for specialty crop imports. Shandong Province's port logistics digitization concentrates demand for integrated warehouse receipt systems.
India
FSSAI's tightening traceability mandates for domestic food processors create first-mover advantages for platform vendors establishing localized compliance engines. The PLI scheme for food processing infrastructure accelerates capital deployment into digitized cold chain networks. Maharashtra and Gujarat agricultural cooperatives drive cloud-based adoption as mid-market crop producers seek lower capital commitments.
Germany
EU Green Deal Farm to Fork Strategy mandates stricter pesticide residue documentation and carbon footprint disclosures across agricultural value chains. ECHA REACH and CSRD disclosure requirements force input suppliers to document chemical composition and lifecycle emissions. The Bavarian dairy and meat processing clusters pre-certify entire cultivation batches before harvest to satisfy downstream transparency requirements.
Global Agriculture Supply Chain Management Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and enterprise software vendors rather than pure-play agricultural specialists. The vendor base stratifies across three tiers: precision agriculture equipment manufacturers extending into telemetry-enabled supply chain layers, ERP giants embedding farm-level contract management into existing enterprise modules, and specialized logistics software providers targeting port and warehouse digitization. Competitive moves center on strategic partnerships between equipment manufacturers and cloud infrastructure providers, plus backward integration by food processors into origin sourcing platforms.
Within the precision agriculture tier, Deere and Company and Raven Industries exemplify equipment-to-software expansion archetypes. SAP SE and Oracle Corporation occupy positions as enterprise software incumbents extending ERP footprints into agricultural workflows. Among specialized logistics providers, Descartes Systems Group represents the global trade compliance and transportation management vector. AGCO Corporation and Trimble Inc. sit within the farm management software specialization, while IBM Corporation anchors the blockchain-enabled traceability segment. Bayer AG exemplifies the agricultural input supplier diversifying into digital platform services.
| Leading Market Players |
|---|
| Deere and Company |
| Trimble Inc. |
| SAP SE |
| Oracle Corporation |
| IBM Corporation |
| AGCO Corporation |
| Bayer AG |
| Descartes Systems Group |
| Raven Industries |
| Others |
Supply & Pricing Matrix
Cloud-based subscription models displacing perpetual licensing arrangements are simultaneously redrawing supplier geography toward Brazilian and Indian SaaS vendors while compressing margin structures for on-premises incumbents. This substitution dynamic concentrates pricing power with trading houses managing multi-origin procurement volumes.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade orchestration platforms from mid-market SaaS tools and lightweight traceability modules. Three-tier pricing stratification across premium compliance-integrated suites, standard farm management dashboards, and economy inventory trackers reflects certification depth and API connectivity breadth. Pricing pressure stems from Brazilian cooperatives consolidating procurement leverage through digitized warehouse receipt systems. Smallholder cooperatives exhibit highest price sensitivity, while vertically integrated North American protein processors absorb premium tiers for upstream supply control.
Supply Chain Analysis
Just-in-time telemetry deployment dominates Brazilian soybean corridors and Iowa corn belts where real-time harvest coordination minimizes spoilage, while strategic stockpiling of edge-computing hardware persists in Sub-Saharan African cotton operations lacking reliable rural broadband. Platform development draws from Taiwan semiconductor components, Indian software engineering capacity, and German precision sensor manufacturing. Single-source vulnerability concentrates in cloud infrastructure dependencies. Distribution runs through direct enterprise sales for farm management software and system integrator channels for transportation modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations bridging agronomic domain expertise with cloud architecture capabilities, a combination scarce enough to create sustainable differentiation for first movers. Talent acquisition friction between crop science and data engineering disciplines constrains expansion velocity across all vendor tiers.
For Market Incumbents: Shield installed base relationships by embedding EU Green Deal compliance modules directly into existing workflow engines before SAP SE and Oracle Corporation extend ERP footprints. Prioritize backward integration into IoT sensor manufacturing to reduce dependency on Taiwanese semiconductor supply chains. Defensive patent positioning around batch-level blockchain traceability prevents disintermediation by specialized logistics providers.
For New Entrants and Emerging Players: Differentiate on carbon credit verification integration targeting Chinese inbound commodity traders navigating MEE dual carbon disclosure requirements. White-space concentration sits with Indian mid-market crop producers responding to FSSAI traceability mandates without capital for enterprise-tier platforms. Go-to-market leverage through agricultural cooperative associations in Maharashtra and Gujarat lowers customer acquisition costs versus direct field sales.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision agriculture equipment manufacturers with captive telemetry networks over pure-play software vendors lacking hardware deployment capabilities. Long-term viability hinges on regulatory compliance engine modularity across EU, USDA, and Chinese jurisdictional divergence. Acquisition target archetype: farm management software specialists with established API ecosystems resisting middleware fragmentation. Signal to watch: ANVISA documentation requirement tightening accelerating Brazilian platform replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with ERP Systems | SAP SE and Oracle Corporation extend enterprise modules into farm-level contract management capturing food processor procurement centralization. |
| Strategic Partnership with Cloud Infrastructure Providers | Equipment manufacturers like Deere and Company secure scalable telemetry data pipelines enabling real-time supply chain orchestration layers. |
| Acquisition of Specialist Traceability Firm | Consolidated procurement by protein processors demands blockchain-enabled provenance capabilities eliminating paper-based chain-of-custody documentation. |
| Geographic Expansion into Brazilian Port Corridors | Santos-Mato Grosso logistics axis digitization concentrates demand for warehouse receipt systems reducing post-harvest losses. |
| Product Launch of Carbon Verification Module | EU emissions trading schemes and MEE dual carbon goals create compliance-driven procurement for agricultural sequestration quantification tools. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs data, SEC filings from diversified industrial conglomerates, EU regulatory disclosure databases, and Brazilian agricultural export statistics. Primary interviews incorporated crop producers in Mato Grosso and Iowa, supply chain executives at North American protein processors, platform engineers at precision agriculture equipment manufacturers, and compliance officers navigating EU Green Deal Farm to Fork mandates. Bottom-up triangulation across installed base estimates and top-down validation against enterprise software spending patterns ensured cross-verification.
Segmentation dimensions modeled span solution architecture, deployment mode, end-user concentration, and application priority across the projection horizon. CAGRs derive from regression analysis of historical adoption curves in comparable enterprise software verticals adjusted for agricultural sector capital intensity and regulatory compliance cycle timing. Forecast inputs incorporate IoT sensor cost decline trajectories and cloud infrastructure penetration rates in rural broadband-constrained regions.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, Brazilian port logistics digitization continuity, or Chinese inbound commodity traceability mandate maintenance would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization resistance and sensor deployment cost curves. Revision becomes warranted when rural connectivity infrastructure investment crosses threshold coverage levels enabling real-time telemetry ubiquity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Europe Agricultural Enzymes Market