
 Post Harvesting Technologies Market | 2026-2036
Post Harvesting Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Post Harvesting Technologies Market Analytics
Fresh produce distribution networks are reconfiguring around real-time quality monitoring and shelf-life prediction tools. John Bean Technologies Corporation leverages its processing equipment portfolio to anchor North American supply chains for fruits and vegetables. AgroFresh Solutions, Inc. specializes in 1-MCP-based freshness preservation, competing across controlled-atmosphere storage installations worldwide. BASF SE sustains R&D intensity in post-harvest crop protection chemistry, extending its reach into emerging markets.
Post Harvesting Technologies encompass mechanical, thermal, and atmospheric systems designed to preserve crop quality, reduce spoilage, and extend commercial shelf life after field collection through parameters such as temperature control, humidity regulation, and ethylene management. Drying equipment and controlled-atmosphere technology occupy distinct margin pools, with thermal processing systems serving grain-dominant geographies while automation platforms capture premium pricing in high-value fruit and vegetable operations. Handling systems and sorting equipment lead capital expenditure patterns across large-scale agriculture, where throughput capacity and defect detection precision determine procurement decisions.
The EPA regulates fumigant residues and atmospheric emissions from post-harvest treatment facilities in the United States, while the EU F-Gas Regulation phases down hydrofluorocarbon use in cold chain refrigeration across Europe. India's FSSAI enforces food safety standards for processed and stored agricultural output, shaping equipment specifications for domestic cold storage expansion. Stakeholders must monitor regulatory divergence between refrigerant-phaseout timelines and emerging national food-loss reduction targets to align capital deployment with compliance-ready technology platforms.
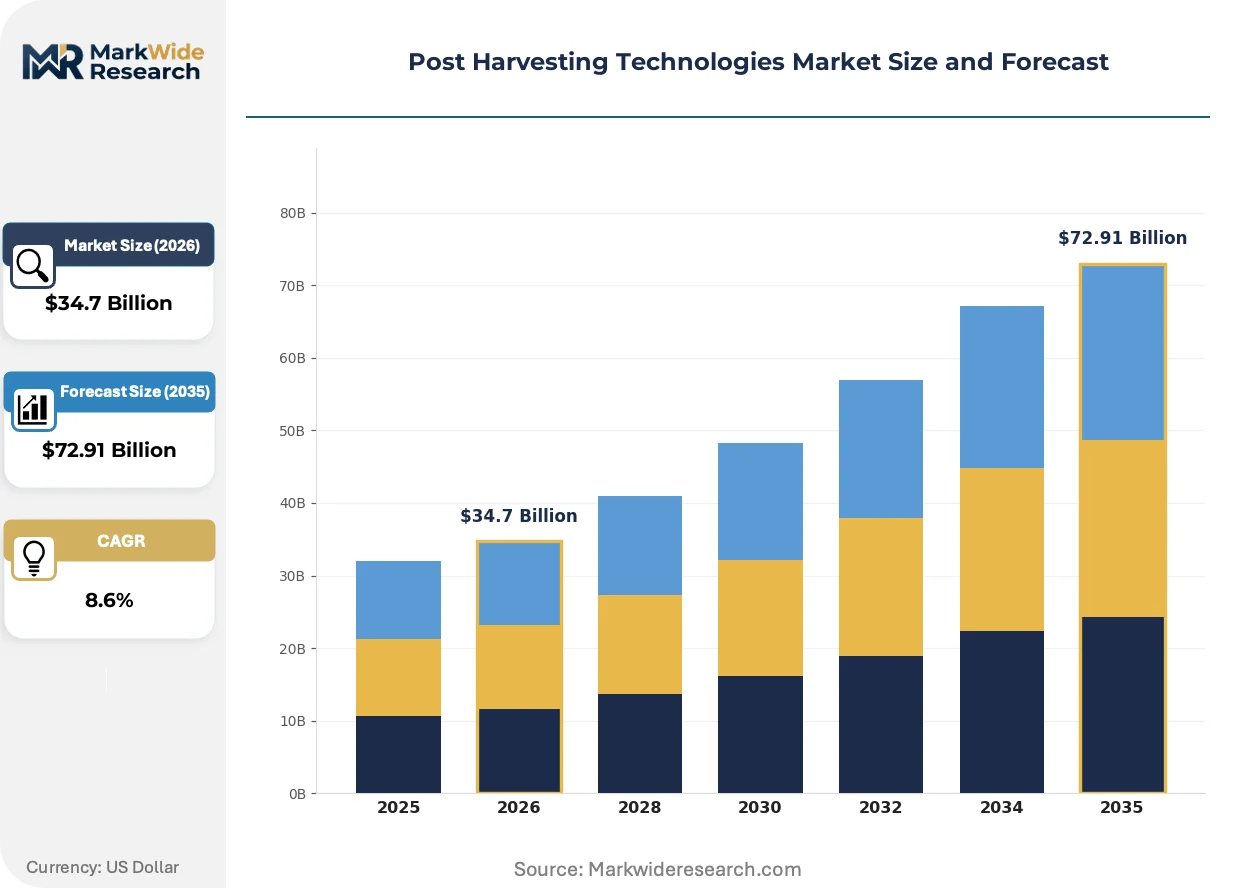
Market Dynamics
The EU F-Gas Regulation is forcing accelerated refrigerant transitions across cold chain infrastructure, compressing equipment replacement cycles and redirecting capital toward natural refrigerant platforms in processing and storage facilities.
Growth Catalysts
- India's PLI scheme for food processing:Central government incentives are expanding domestic cold storage capacity, pulling investment into controlled-atmosphere technology and automated sorting systems for fruit and vegetable operations.
- Freshness preservation chemistry:1-MCP-based treatments are extending commercial shelf life for climacteric fruits, reducing post-harvest losses in distribution networks serving retail and foodservice channels.
- Real-time quality monitoring:Sensor networks and predictive analytics platforms are embedding into supply chains, enabling dynamic routing decisions that minimize spoilage before retail handoff.
Market Restraints
- Copper and aluminum input volatility:Thermal processing equipment and refrigeration systems face margin pressure from base metal price swings, compressing returns for drying and cooling system manufacturers.
- Refrigerant phase-down timelines:The EU F-Gas Regulation mandates hydrofluorocarbon reductions that strand existing cold storage assets before full depreciation, creating stranded capital risk for facility operators.
- Grain-dominant geography concentration:Thermal drying systems serve markets with lower pricing power than high-value produce segments, limiting margin expansion for equipment suppliers concentrated in cereal and oilseed regions.
Strategic Opportunities
- India's food-loss reduction targets:National commitments to halve post-harvest losses are accelerating cold chain buildout in Maharashtra, Gujarat, and Punjab, creating demand for integrated handling and storage platforms.
- Controlled-atmosphere convergence with robotics:Automated pallet handling systems paired with dynamic atmosphere modulation are opening premium service tiers in high-value berry and stone fruit supply chains.
- Direct-to-retail channel expansion:Shortened produce supply chains are bypassing traditional wholesale markets, creating demand for modular, rapid-deployment cooling and sorting units at distribution hubs.
Industry Challenges
- Refrigeration technician scarcity:Natural refrigerant transitions require specialized handling protocols that outpace vocational training capacity, delaying equipment commissioning and maintenance response times.
- Legacy control system integration:New sensor networks and automation platforms face interoperability barriers with existing programmable logic controllers in established processing facilities, extending deployment timelines.
- FSSAI compliance certification:India's food safety authority mandates equipment validation protocols that create documentation burdens and extend procurement cycles for cold storage expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post Harvesting Technologies Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorting Equipment, Packing Machines, Drying Equipment, Handling Systems End Use Industry: Agriculture, Food Processing, Retail, Logistics Technology: Mechanical Systems, Thermal Processing, Controlled Atmosphere, Automation Application: Crops, Fruits, Vegetables, Grains |
| Companies Covered | John Bean Technologies Corporation, AgroFresh Solutions, Inc., BASF SE, Syngenta Group, UPL Limited, Hazel Technologies, Inc., Apeel Science, Nufarm Limited, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post Harvesting Technologies Market Evolving Landscape
Post-harvest technology stacks are converging around data-driven quality prediction and autonomous handling systems that compress decision cycles from field to retail shelf.
Hyperspectral imaging and computer vision platforms are digitizing defect detection and ripeness assessment in fruit and vegetable sorting operations. Large-scale packing houses in California and Spain are deploying these systems at line speeds exceeding twenty units per second. The technology is digitizing quality control labor, compressing headcount requirements while improving consistency in export-grade consignment preparation.
The EU F-Gas Regulation mandates an eighty percent hydrofluorocarbon phase-down by 2030, forcing equipment manufacturers to redesign compressor and heat exchanger architectures around CO2 and ammonia circuits. Cold storage operators in Germany and the Netherlands are front-loading capital expenditure to secure compliant installations before supply bottlenecks intensify. The regulation is accelerating vendor consolidation as smaller equipment makers lack R&D bandwidth for refrigerant platform transitions.
Consolidated retail procurement is displacing fragmented wholesale buying in fresh produce supply chains. Supermarket chains in the United Kingdom and Australia are imposing direct supplier relationships that mandate traceability systems and shelf-life guarantees. This concentration is compressing intermediary margins and forcing primary producers to invest in on-farm cooling and grading infrastructure previously handled by wholesalers.
Post Harvesting Technologies Market Segmentation
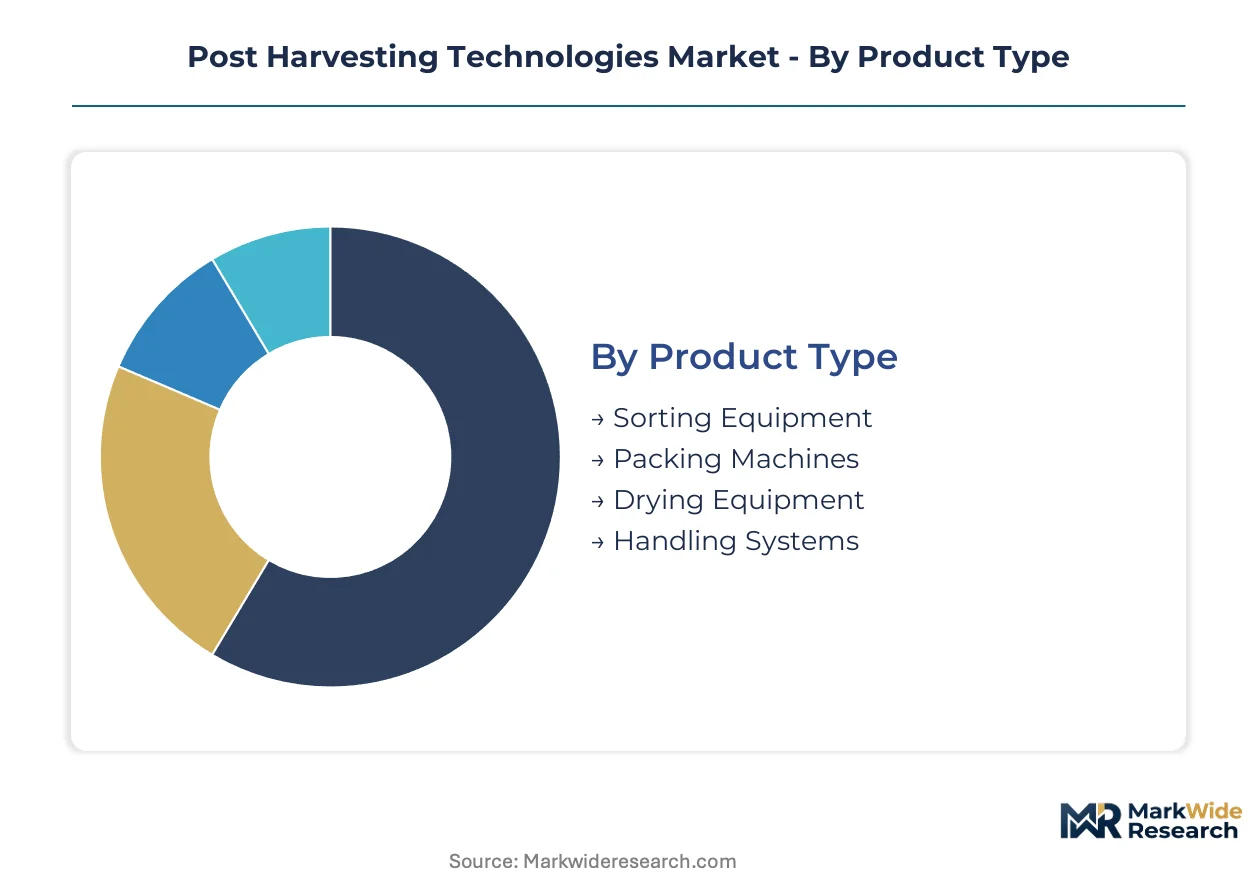
Post-harvest technology procurement varies sharply by crop value density, regulatory environment, and supply chain position. Equipment specifications diverge between grain elevators requiring throughput volume and berry packers demanding defect precision. Understanding these segment boundaries clarifies where margin pools concentrate and which technology platforms command pricing power.
Product Type:
Use cases span from high-speed grain handling to delicate produce grading, with capital intensity and replacement cycles varying by commodity processed.
- Sorting Equipment:Optical and weight-based systems separate produce by size, color, and defect density. California strawberry packers and Dutch bell pepper operations deploy hyperspectral imaging at line speeds exceeding twenty units per second to meet retail export standards.
- Packing Machines:Automated bagging, clamshell sealing, and palletizing systems integrate with upstream grading lines. Demand concentrates in Mexico's avocado export sector and Spain's citrus consortiums where labor cost escalation accelerates mechanization investment.
- Drying Equipment:Continuous-flow and batch thermal systems reduce moisture content in cereals and oilseeds.
- Handling Systems:Conveyors, elevators, and automated guided vehicles move bulk and packaged product through processing facilities.
The dominant share belongs to Sorting Equipment, while Packing Machines is closing the gap fastest.
End Use Industry:
Customer procurement authority shifts from farm-gate cooperatives to retail compliance departments as product moves downstream.
- Agriculture:Farm and cooperative installations emphasize durability and service network proximity over precision features. Brazilian soybean cooperatives and Ukrainian grain aggregators prioritize equipment with localized parts availability and technician coverage.
- Food Processing:Industrial-scale canneries, freezers, and dehydration plants integrate multi-stage handling lines. India's FSSAI certification requirements and the EU's hygiene package directives shape equipment specifications for export-oriented mango pulp and tomato paste facilities.
- Retail:Supermarket direct-procurement programs mandate traceability infrastructure and shelf-life guarantees.
- Logistics:Cold storage operators and third-party distributors manage inventory velocity across multiple commodity types.
Food Processing commands the largest equipment spend, though Retail is expanding procurement authority most rapidly.
Technology:
Technology selection trades capital efficiency against operating precision, with natural refrigerant transitions and sensor integration reshaping platform economics.
- Mechanical Systems:Conveying, grading, and packaging machinery using belts, rollers, and pneumatic actuation. Grain handlers in the US Plains and Black Sea corridor favor these systems for their operational simplicity and technician familiarity.
- Thermal Processing:Drying, cooling, and freezing equipment managing heat transfer and moisture removal. The EU F-Gas Regulation's hydrofluorocarbon phase-down is forcing German and Dutch cold storage operators toward CO2 and ammonia architectures ahead of depreciation cycles.
- Controlled Atmosphere:Oxygen, carbon dioxide, and ethylene management systems extend shelf life in sealed storage.
- Automation:Robotics, machine vision, and predictive control systems reducing labor dependence.
Mechanical Systems retains the installed base majority, yet Automation is climbing the fastest as labor costs rise and retail traceability mandates tighten.
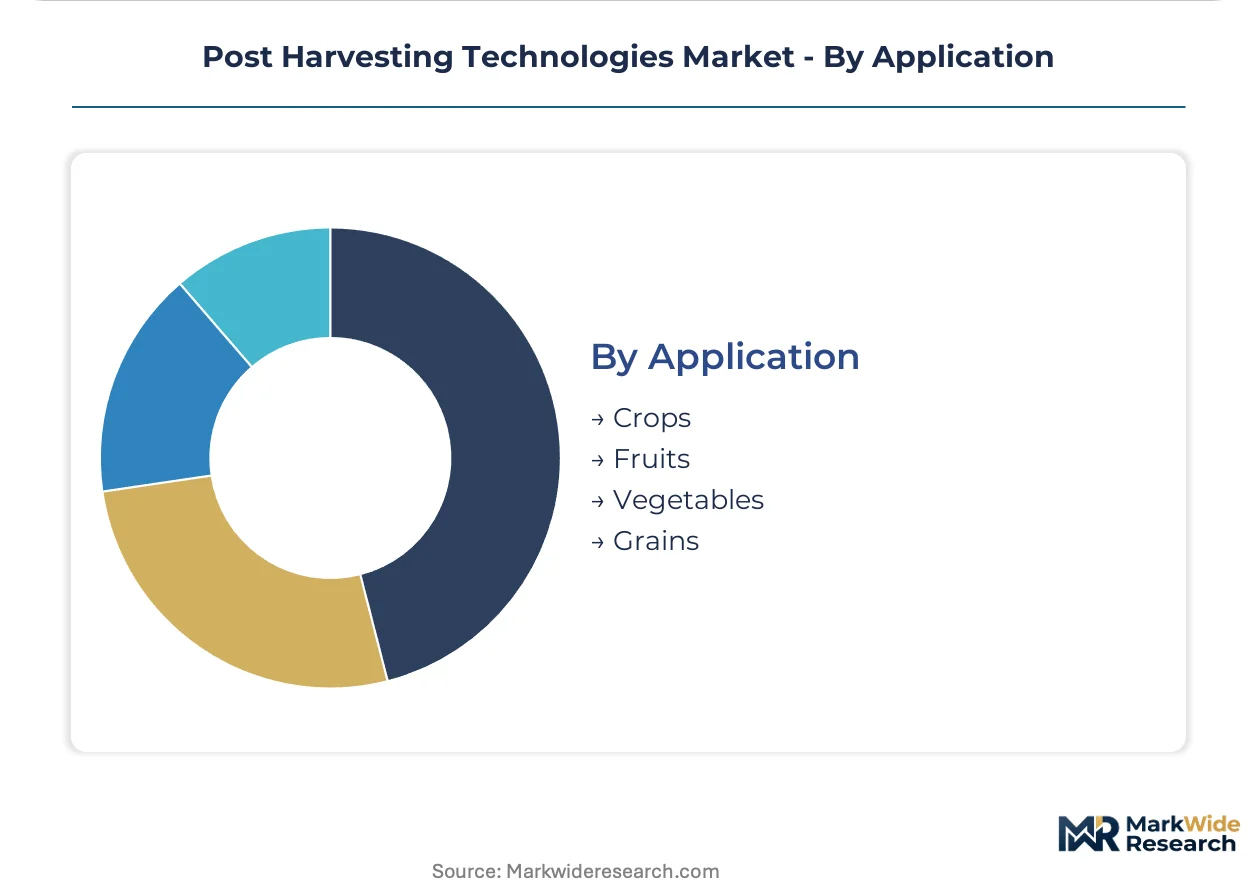
Application:
Commodity characteristics dictate equipment specifications, with respiration rates, bruise susceptibility, and value per kilogram driving technology selection.
- Crops:Post-harvest handling of root vegetables, tubers, and bulb crops emphasizing curing and storage disease management. Potato processors in Idaho and starch manufacturers in the Netherlands deploy specialized handling to minimize mechanical damage and sprouting losses.
- Fruits:Climacteric and non-climacteric varieties requiring distinct ripening protocols and ethylene management. Chilean cherry exporters and South African citrus shippers invest heavily in precooling and controlled-atmosphere containers to maintain arrival condition across extended ocean transit.
- Vegetables:Leafy greens, brassicas, and solanaceous crops with high respiration rates and moisture sensitivity.
- Grains:Cereals, oilseeds, and pulses where moisture content and temperature management dominate preservation strategy.
Grains represents the largest addressable equipment volume, though Fruits is gaining share fastest as export-oriented high-value production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain connectivity underwrites Europe's role in transcontinental produce logistics, while India's Jawaharlal Nehru Port anchors South Asian export corridors for temperature-sensitive commodities.
United States
California's Central Valley strawberry packers drive hyperspectral imaging demand for defect detection at export-grade line speeds. The EPA regulates fumigant residues from post-harvest treatment facilities, mandating emission controls that shape equipment specifications. Washington State's apple storage clusters in Yakima Valley are retrofitting controlled-atmosphere systems to meet retail traceability mandates.
Germany
Rhineland cold storage operators face compressed equipment replacement cycles from the EU F-Gas Regulation's hydrofluorocarbon phase-down timeline. The regulation mandates eighty percent reduction by 2030, forcing CO2 and ammonia refrigeration architectures ahead of depreciation cycles. Bavarian potato processors near Munich are deploying automated handling lines to offset labor cost escalation in starch manufacturing.
India
Maharashtra's grape export belt around Nashik is expanding precooling infrastructure to meet European supermarket shelf-life guarantees. The FSSAI enforces food safety validation protocols that extend procurement cycles for cold storage projects. Gujarat's mango pulp processors in Anand district are integrating multi-stage handling lines to satisfy EU hygiene package directives for export-oriented facilities.
Chile
Central Valley cherry exporters are investing in controlled-atmosphere containers to maintain arrival condition across extended Pacific transit to Asian markets. The country's national agricultural regulator enforces phytosanitary certification standards that shape post-harvest treatment protocols. Port infrastructure in Valparaíso is expanding refrigerated terminal capacity to handle peak seasonal export volumes.
Australia
Queensland banana packers are deploying automated grading systems as supermarket chains impose direct-procurement relationships with traceability requirements. The country's national food standards authority mandates equipment compliance documentation that influences technology selection. Victoria's stone fruit operations in the Goulburn Valley are retrofitting dynamic atmosphere modulation for premium berry and nectarine supply chains.
Post Harvesting Technologies Market Competitive Landscape
On the supply side, the industry is moderately consolidated with distinct tiering between integrated processing equipment conglomerates and specialized freshness preservation chemistry firms. Three strategic archetypes dominate: diversified industrial technology groups with broad handling portfolios, crop protection specialists extending into post-harvest applications, and venture-backed coating and sensor technology disruptors. Competitive intensity centers on M&A activity to secure refrigerant-transition capabilities and strategic partnerships to embed predictive quality analytics into retail supply chains.
Within the diversified equipment tier, John Bean Technologies Corporation and JBT Corporation exemplify integrated processing technology platforms with established North American supply chain anchoring positions. AgroFresh Solutions, Inc. and Hazel Technologies, Inc. occupy the specialized preservation chemistry segment, representing innovation-focused archetypes competing on shelf-life extension technology. BASF SE anchors the agrochemical conglomerate vector, leveraging crop protection R&D infrastructure to extend reach into emerging market post-harvest applications.
| Leading Market Players |
|---|
| John Bean Technologies Corporation |
| AgroFresh Solutions, Inc. |
| BASF SE |
| Syngenta Group |
| UPL Limited |
| Hazel Technologies, Inc. |
| Apeel Science |
| Nufarm Limited |
| JBT Corporation |
| Others |
Value Network & Pricing Analysis
Maharashtra's Nashik grape belt anchors export-grade precooling infrastructure, where capacity bottlenecks during peak harvest concentrate pricing power among operators with validated FSSAI compliance. Equipment procurement cycles extend when cold storage scarcity allows compliant facilities to command premium service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers capturing after-sales service bundling and certification documentation. Price differentiation rests on ISO hygiene compliance and remote monitoring integration. Cost compression in economy-tier thermal systems is intensifying because copper and aluminum input volatility squeezes manufacturer margins. Grain cooperative buyers exhibit highest price sensitivity, while retail-direct berry packers prioritize traceability over unit cost.
Supply Chain Analysis
Export-control restrictions on hyperspectral imaging sensors limit flows from US and German component suppliers to Indian and Chilean packer integrators. Manufacturing concentration centers on Germany, the United States, and China for compressor architectures and machine vision platforms. Supply chains draw from rare-earth magnet dependencies for servo motors and specialized aluminum alloys for heat exchangers. Single-source vulnerability in CO2 compressor valve assemblies creates commissioning delays. Distribution runs through OEM-direct channels for large packers and regional dealer networks for cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
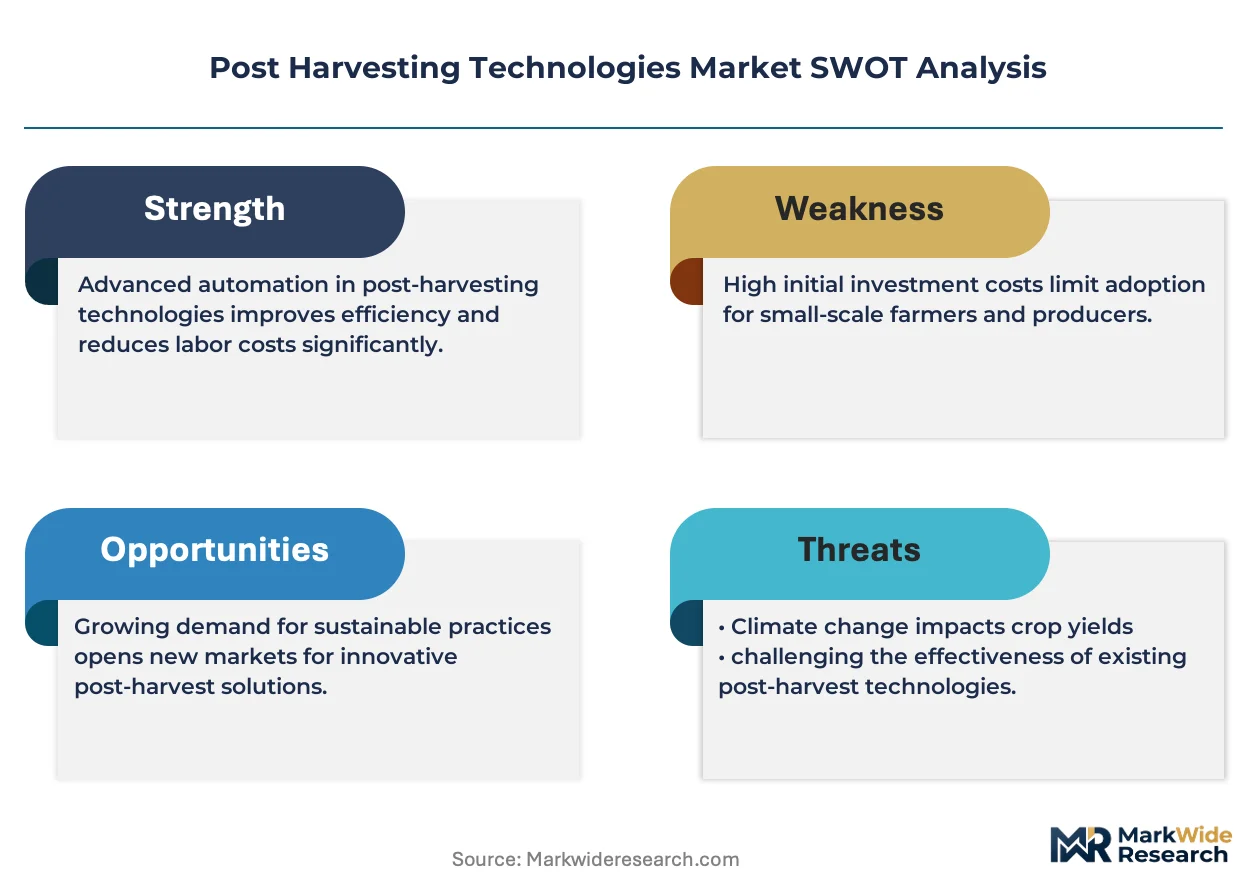
Natural refrigerant technician scarcity and FSSAI validation bottlenecks constrain capacity expansion, making certified installation capability the scarce asset determining market access.
For Market Incumbents: Build switching-cost moats through captive service networks and refrigerant-transition certification programs. Deepen backward integration into CO2 compressor manufacturing to secure supply amid EU F-Gas-driven demand surges. Anchor channel control by embedding predictive maintenance platforms that lock in aftermarket revenue streams. For New Entrants and Emerging Players: Mid-scale mango pulp processors in Gujarat's Anand district represent the most penetrable entry point, where FSSAI documentation burdens extend procurement cycles and create service gaps. Target modular rapid-deployment cooling units for direct-to-retail distribution hubs bypassing traditional wholesale markets. Pursue partnership-based go-to-market models with established regional equipment dealers lacking refrigerant-transition expertise. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controlled-atmosphere specialists with installed base conversion potential over greenfield automation entrants. Long-term viability hinges on refrigerant-platform R&D bandwidth and India market access credentials. Acquisition targets should demonstrate FSSAI validation track records and Maharashtra or Gujarat reference installations. Watch EU F-Gas compliance deadline acceleration as inflection signal for natural refrigerant equipment demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | CO2 and ammonia architecture investments secure EU market access ahead of F-Gas phase-down deadlines. |
| FSSAI Certification Pre-Validation | Documentation-ready equipment designs compress procurement cycles in India's expanding cold storage sector. |
| Sensor Network Integration | Hyperspectral imaging and ethylene monitoring embed incumbents into retail traceability mandates. |
| Technician Training Partnerships | Vocational pipeline investments address commissioning bottlenecks delaying natural refrigerant deployment. |
| Modular Rapid-Deployment Units | Containerized cooling and sorting systems capture direct-to-retail channel bypass opportunities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with cold storage facility managers, FSSAI compliance officers, OEM procurement leads, and aftermarket service technicians. Secondary validation drew from EU refrigerant-phase-down regulatory filings, Indian PLI scheme disbursement records, EPA emission control registrations, and customs data on thermal processing equipment trade flows. Bottom-up equipment shipment tallies and top-down cold chain capacity estimates were triangulated to anchor market sizing.
Calibration against historical refrigerant-transition cycles and grain-price volatility patterns informed projection mechanics across the analysis window. Segmentation modeling spanned product type, end-use industry, technology platform, and application commodity, with additional dimensioning by regulatory compliance tier. CAGRs were derived from equipment replacement cycle compression and cold storage capacity buildout trajectories. Forecast inputs incorporated EU F-Gas phase-down acceleration scenarios and India's food-loss reduction target commitments.
Macroeconomic conditions sit as an overlay; deviation in base metal prices, agricultural commodity export demand, or central bank infrastructure lending rates would shift the trajectory. Forecasts reflect documented assumptions on refrigerant-transition adoption curves and PLI scheme implementation pace. Material shifts in EU F-Gas enforcement timelines or India's FSSAI certification protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Europe Agricultural Enzymes Market