
 Global Food and Agriculture Technology and Products Market | 2026-2036
Global Food and Agriculture Technology and Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food and Agriculture Technology and Products Market Analysis
The EU Green Deal is expanding compliance burdens for crop protection chemistry across European supply chains. CropX leverages soil sensor networks to anchor its precision farming franchise in North American row-crop territories. Apeel Sciences differentiates through plant-derived edible coatings that extend produce shelf life without synthetic intervention. Nature's Fynd occupies fermentation-derived protein platforms, competing with conventional animal agriculture on land-use efficiency.
Food and agriculture technology and products encompass biotechnological inputs, precision equipment, and post-harvest systems engineered to optimize yield, reduce waste, and ensure safety across the farm-to-fork continuum. These systems integrate genomic markers, variable-rate application hardware, and controlled-environment protocols to achieve target output per hectare while minimizing environmental loading. Agricultural biotechnology leads margin capture among technology segments, with gene-edited trait stacks commanding premium positioning in soybean and corn seed markets. Precision farming sustains the fastest expansion trajectory, driven by satellite imagery subscription models and autonomous spraying rigs that cut input overapplication. Soil health products mature in Western European markets where regenerative agriculture mandates from regulators like EFSA and national environment agencies deepen farmer conversion.
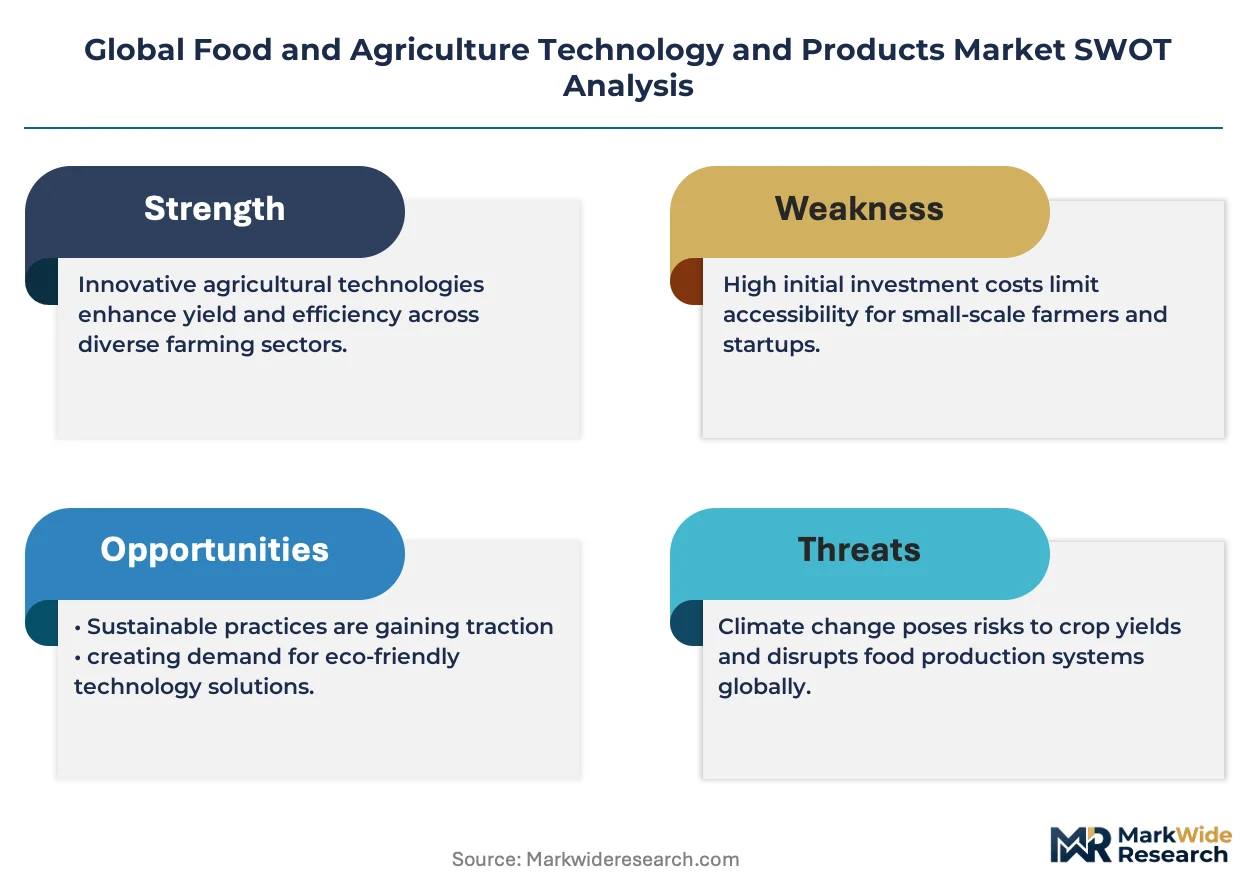
EPA residue tolerance frameworks in the United States and REACH chemical authorization in Europe jointly constrain active ingredient portfolios, forcing reformulation toward biological and mineral alternatives. India's FSSAI and China's MEE impose parallel tightening on import tolerances and domestic manufacturing emissions, fragmenting compliance architecture for multinational input suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which chemistry platforms retain market access versus face phasedown timelines.
Market Dynamics
Precision farming hardware and biological input portfolios are converging under unified data platforms, compressing the traditional separation between equipment manufacturers and agrichemical suppliers into integrated service ecosystems.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding residue limit reductions and input reauthorization timelines are forcing rapid portfolio turnover toward biological alternatives, opening substitution windows for fermentation-derived crop protection.
- Large-scale Brazilian agribusiness:Consolidated landholdings in Mato Grosso and Goiás are deploying autonomous spraying rigs and satellite-guided variable-rate application at scale, normalizing subscription-based precision farming business models.
- CRISPR trait stacks:Gene-edited soybean and corn varieties with stacked stress-tolerance traits are commanding premium seed pricing and displacing conventional breeding timelines in North American row-crop markets.
Market Restraints
- Phosphorus and potassium input cost volatility:Concentrated mining operations in Morocco, Russia, and Belarus expose fertilizer formulations to supply disruption and price spikes that compress downstream margins.
- EPA tolerance framework stringency:Active ingredient reauthorization timelines and residue threshold tightening are forcing premature portfolio obsolescence for synthetic chemistry platforms before R&D amortization completes.
- Biological input efficacy variability:Temperature-sensitive microbial inoculants and inconsistent field performance relative to synthetic benchmarks limit grower confidence and repeat purchase rates in temperate climates.
Strategic Opportunities
- India's Punjab-Haryana belt:Severe groundwater depletion and power subsidy rationalization are accelerating drip irrigation and biofertilizer penetration among smallholder wheat and rice cultivators.
- Controlled-environment agriculture convergence:Integration of LED spectral tuning with hydroponic nutrient film techniques is opening vertical farming deployments for leafy greens in peri-urban UAE and Saudi Arabia.
- Post-harvest edible coatings:Plant-derived shelf-life extension films are capturing premium produce logistics contracts from synthetic wax and chemical preservative incumbents in export-oriented Chilean and Peruvian fruit corridors.
Industry Challenges
- Data interoperability standards:Proprietary sensor protocols and platform silos from equipment OEMs are blocking seamless aggregation of soil moisture, weather, and imagery feeds into unified farm management systems.
- Biological product registration timelines:EFSA and EPA lack harmonized dossier requirements for microbial and biochemical active substances, extending approval cycles and freezing capital in pre-commercial pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food and Agriculture Technology and Products Market |
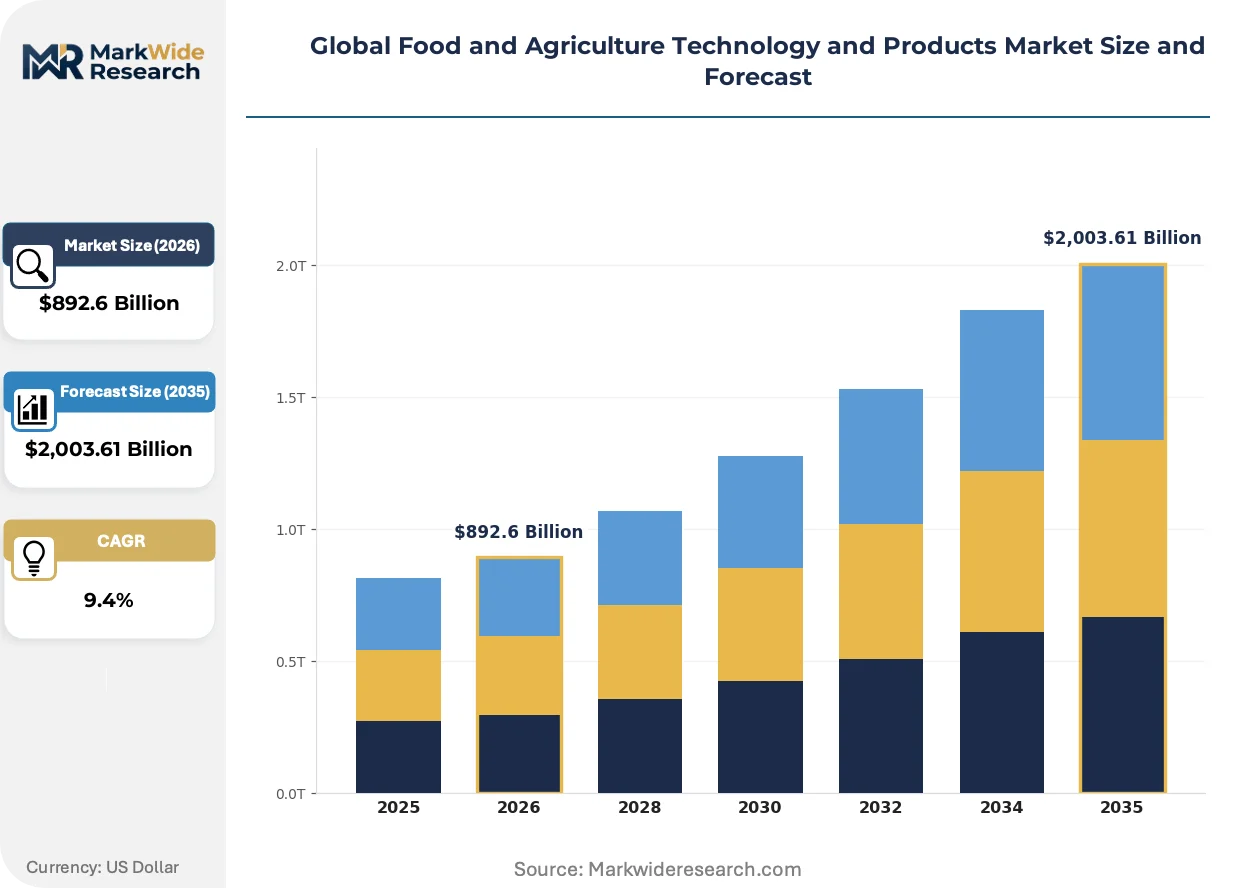
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $2,003.61 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Protection, Soil Health, Seed Treatment, Fertilizers Technology: Precision Farming, Agricultural Biotechnology, Irrigation Technologies, Automation End User: Farmers, Agribusinesses, Government Agencies, Research Institutions Application: Crop Production, Livestock Management, Pest Control, Food Processing |
| Companies Covered | Plantible, CropX, Apeel Sciences, Winnow, GrubMarket, ProducePay, Heura Foods, UPSIDE Foods, Nature's Fynd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food and Agriculture Technology and Products Market Emerging Trajectories
Biological input manufacturing and precision application hardware are fusing into closed-loop systems where real-time agronomic data directly triggers input dispensing decisions without human intervention.
Variable-rate irrigation and fertigation controllers are modularizing around plug-and-play sensor architectures that allow Brazilian and Australian broadacre operators to upgrade hardware components without replacing entire control systems. Mid-scale farms in Argentina's Pampas region are adopting these retrofit-friendly platforms to defer full system replacement capital outlays. The technology is modularizing supplier relationships, enabling growers to mix sensor brands and analytics providers rather than accepting captive equipment ecosystems.
REACH chemical authorization and the EU F-Gas Regulation are jointly constraining synthetic pesticide and controlled-environment cooling agent portfolios, forcing reformulation toward mineral oil and botanical extract alternatives. European greenhouse operators in the Netherlands and Spain are retrofitting heat pump systems to replace conventional refrigeration cycles. Protected horticulture segments face compressed operating margins during the transition period as capital-intensive equipment upgrades coincide with input cost inflation.
Consolidated retail and foodservice buyers are unbundling after-sales agronomic advisory from input procurement, contracting directly with independent precision farming consultancies for field-specific prescription services. North American grain elevators and Brazilian soy processors are inserting these advisory layers into their supplier financing programs. This disintermediation is most visible in Iowa and Illinois corn-soy rotations where cooperative extension influence has weakened and private data analytics firms have captured advisory relationships.
Global Food and Agriculture Technology and Products Market Segmentation
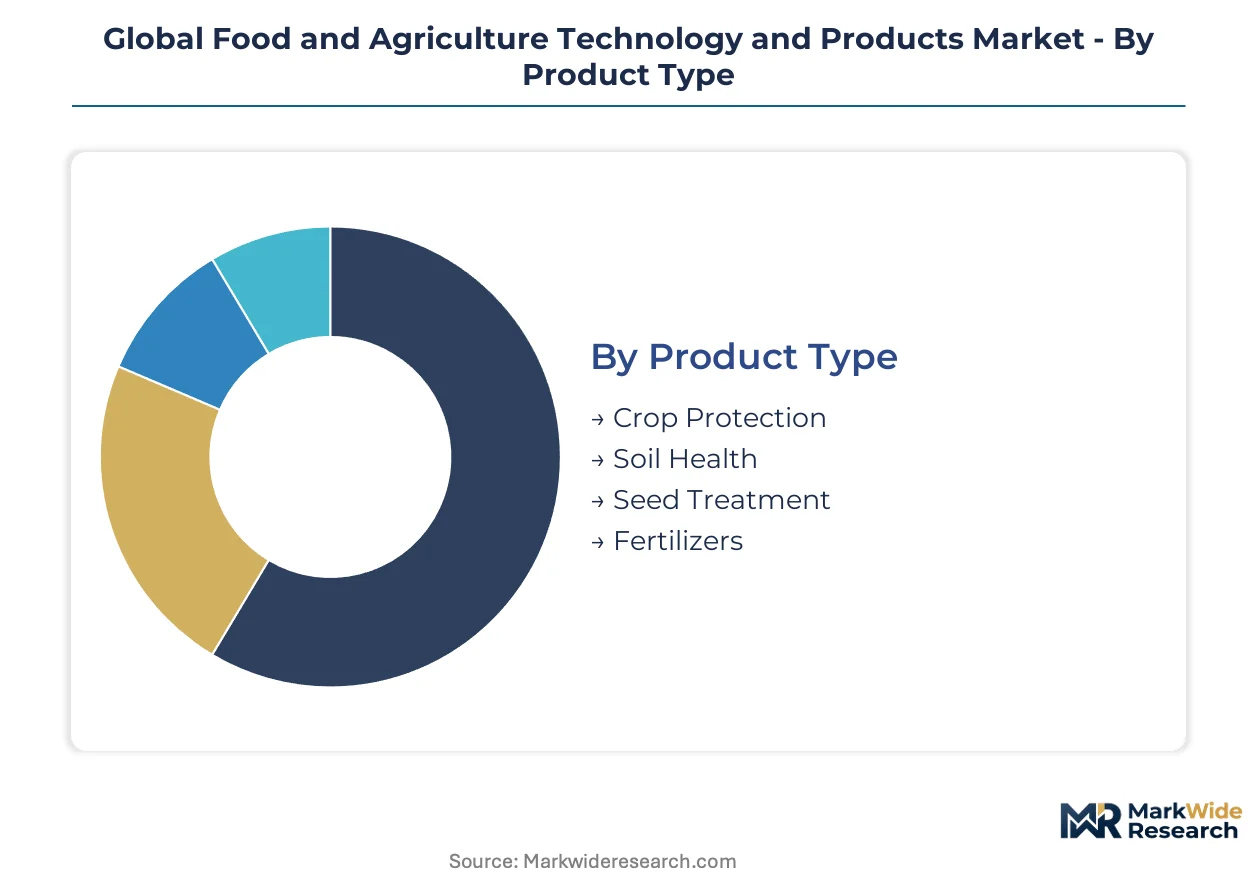
Segmentation in food and agriculture technology reveals how regulatory burden, farm scale, and crop system type dictate purchasing behavior. Distinct compliance pathways and capital intensity separate commodity input markets from precision equipment subscriptions.
Product Type:
EPA tolerance frameworks and EU REACH authorization requirements vary sharply across these segments, determining which chemistry platforms retain market access versus face phasedown timelines.
- Crop Protection:Synthetic pesticides and biological alternatives face divergent reauthorization cycles under EPA and EFSA regimes. Brazilian soy processors and Indian cotton belts drive formulation demand as residue limits tighten in export corridors.
- Soil Health:Microbial inoculants, biochar amendments, and cover-crop seed systems restore organic matter and nutrient cycling. Western European regenerative mandates from EFSA and national environment agencies accelerate farmer conversion in France and Germany.
- Seed Treatment:Coating technologies delivering fungicides, insecticides, or biological stimulants directly to germinating seed. Neonicotinoid restrictions under EU regulations force reformulation toward mineral and botanical alternatives.
- Fertilizers:Nitrogen, phosphorus, and potassium formulations plus controlled-release and stabilized variants. Moroccan and Belarusian supply concentration exposes pricing to geopolitical disruption.
Crop Protection sits at the top of the volume ranking, with Soil Health climbing the fastest.
Technology:
Capital deployment patterns separate subscription-based software services from hardware-intensive equipment platforms, with margin structures diverging accordingly.
- Precision Farming:Satellite imagery, soil sensor networks, and autonomous application rigs enable variable-rate input dispensing. Mato Grosso and Goiás agribusinesses in Brazil normalize subscription models for acreage-based service fees.
- Agricultural Biotechnology:Gene-edited trait stacks and marker-assisted breeding compress development timelines for stress tolerance. CRISPR soybean and corn varieties command premium positioning in North American row-crop territories.
- Irrigation Technologies:Drip, pivot, and micro-spray systems with fertigation integration reduce water application intensity. Punjab and Haryana smallholders in India adopt drip systems as groundwater depletion forces efficiency mandates.
- Automation:Robotic harvesting, autonomous tractors, and drone-based scouting reduce labor dependency. Australian broadacre operators deploy retrofit-friendly modular controllers to defer full system replacement.
Precision Farming holds the largest installed base, while Automation gains share fastest among capital-intensive operations.
End User:
Procurement scale and technical sophistication determine whether buyers prioritize price per hectare or total cost of ownership in equipment decisions.
- Farmers:Individual owner-operators and family enterprises managing under 500 hectares. Iowa and Illinois corn-soy rotations show weakening cooperative extension influence and rising private data analytics adoption.
- Agribusinesses:Consolidated landholding companies and integrated processors with internal agronomy teams. Brazilian soy processors and North American grain elevators insert precision advisory into supplier financing programs.
- Government Agencies:Extension services, research stations, and subsidy administrators shaping adoption incentives. India's power subsidy rationalization accelerates drip irrigation penetration among wheat and rice cultivators.
- Research Institutions:Universities and national agricultural research centers conducting field trials and germplasm development. Germplasm banks in Brazil and Argentina anchor regional trait development pipelines.
Agribusinesses dominate capital deployment, with Government Agencies expanding fastest through subsidy restructuring.
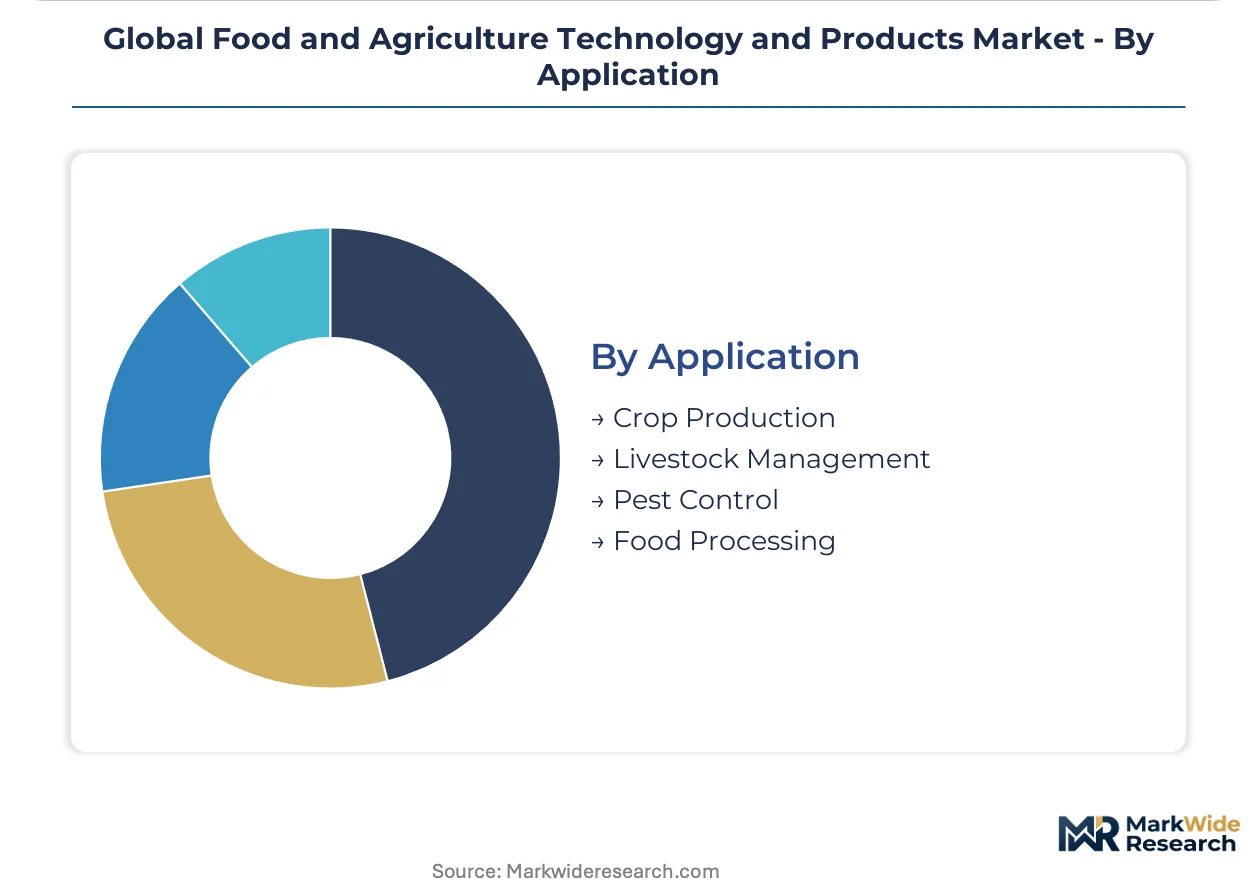
Application:
Biological and mechanical intervention points differ across plant and animal systems, with post-harvest segments showing distinct supply chain integration patterns.
- Crop Production:Input application, cultivation, and harvest optimization across row crops, specialty crops, and protected horticulture. Netherlands and Spanish greenhouse operators retrofit heat pump systems under EU F-Gas Regulation constraints.
- Livestock Management:Feed formulation, health monitoring, and waste processing systems for cattle, poultry, and swine operations. Fermentation-derived protein platforms from Nature's Fynd compete on land-use efficiency metrics.
- Pest Control:Integrated pest management combining biological controls, pheromone disruption, and targeted chemistry. Chilean and Peruvian fruit corridors adopt plant-derived edible coatings for export logistics premium.
- Food Processing:Sorting, washing, coating, and packaging systems extending shelf life and reducing waste. Apeel Sciences captures produce logistics contracts with synthetic-intervention-free shelf-life extension.
Crop Production maintains volume leadership, with Food Processing expanding most quickly through post-harvest technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern food and agriculture technology sector traces its commercial scaling to the Green Revolution's irrigation and hybrid seed platforms that first achieved mass adoption in the United States and Mexico during the 1960s. That foundational infrastructure now supports precision farming and biotechnology clusters across multiple continents. Today, regulatory divergence and water stress patterns determine where specific technology platforms penetrate fastest.
United States
Consolidated row-crop operations in Iowa and Illinois drive subscription adoption for satellite-guided variable-rate application systems. EPA tolerance framework stringency accelerates reformulation toward biological alternatives among Midwestern corn-soy cultivators. The Precision Agriculture Center at the University of Minnesota anchors field trial networks for autonomous spraying rig validation.
Brazil
Mato Grosso and Goiás agribusinesses deploy autonomous equipment at scale across consolidated soybean and cotton holdings. ANVISA residue monitoring aligns with EU import tolerance requirements for export-oriented processors. Campinas research clusters in São Paulo state anchor CRISPR trait development pipelines for tropical stress tolerance.
India
Punjab and Haryana smallholders accelerate drip irrigation penetration as groundwater depletion forces efficiency mandates on wheat and rice rotations. FSSAI tightening on import tolerances reshapes domestic biofertilizer registration priorities. Ludhiana and Hisar equipment manufacturing hubs scale modular fertigation controllers for retrofit installation.
Germany
Western European regenerative agriculture mandates from EFSA and national environment agencies deepen farmer conversion to microbial inoculants and cover-crop systems. REACH chemical authorization timelines force portfolio turnover toward mineral oil alternatives in Rhineland-Palatinate viticulture. The John Deere European Technology Innovation Center in Kaiserslautern anchors precision hardware R&D for continental deployment.
China
MEE emissions enforcement and dual carbon goals compress synthetic fertilizer application intensity in Yangtze River Delta greenhouse operations. GB standards harmonization with Codex Alimentarius reshapes export-oriented fruit coating formulation in Shandong Peninsula processing clusters. Shenzhen agtech venture networks finance controlled-environment agriculture deployments for peri-urban leafy green production.
Global Food and Agriculture Technology and Products Market Vendor Landscape
The competitive structure tilts toward technology-integrated input suppliers over standalone equipment or chemistry vendors. Tiered positioning separates precision farming platform operators from biological input specialists and post-harvest coating developers. Dominant competitive moves include strategic partnerships between sensor network providers and agronomic advisory services, plus portfolio diversification into adjacent input categories.
Among precision farming platform operators, CropX exemplifies the soil sensor network archetype, while Apeel Sciences occupies the plant-derived shelf-life extension segment. Nature's Fynd represents fermentation-derived protein platforms competing on land-use efficiency metrics. These three entities anchor distinct technology vectors within the broader competitive map, each sitting within specialized sub-segments that resist direct substitution.
| Leading Market Players |
|---|
| Plantible |
| CropX |
| Apeel Sciences |
| Winnow |
| GrubMarket |
| ProducePay |
| Heura Foods |
| UPSIDE Foods |
| Nature's Fynd |
| Others |
Supply Flow & Price Mechanics
Phosphate rock extraction costs in Morocco and Belarus cascade through fertilizer formulation tiers, compressing margins for nitrogen-phosphate-potassium blenders while concentrating pricing power among integrated mining-chemical conglomerates that control both extraction and downstream distribution.
Pricing Analysis
Subscription-based acreage fees for precision farming platforms separate hardware-intensive annual contracts from software-only monitoring tiers, with satellite imagery providers commanding premium positioning against sensor-hardware bundles. Price differentiation hinges on data integration depth and after-sales agronomic advisory bundling, with Brazilian agribusinesses showing lowest sensitivity due to financing program structures while Indian smallholders in Punjab face acute cost compression from groundwater depletion mandates. Pricing pressure intensifies in synthetic crop protection as EPA tolerance tightening accelerates portfolio obsolescence before R&D amortization completes.
Supply Chain Analysis
Microbial inoculant production rests on fermentation capacity concentrated in the United States, Germany, and India, with strain preservation and cold-chain logistics feeding temperate-climate field performance variability that limits grower confidence. Critical dependencies include phosphorus ore from Moroccan and Belarusian mining operations, CRISPR trait germplasm from Brazilian and North American research stations, and LED spectral components from Chinese and South Korean manufacturers. Single-source vulnerability concentrates in phosphorus supply given geopolitical disruption exposure in North Africa and Eastern Europe. Distribution runs through agribusiness procurement consortia and government subsidy channels rather than open retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal Farm to Fork Strategy operates as a regulatory compounder, with binding residue limit reductions and input reauthorization timelines forcing portfolio turnover that sustains substitution demand for biological alternatives across European supply chains.
For Market Incumbents: Extend precision farming platform capabilities through backward integration into sensor hardware manufacturing, capturing advisory relationships that cooperative extension services have relinquished in Iowa and Illinois. Anchor capacity in Brazil's Mato Grosso and Goiás to normalize subscription models before emerging data analytics firms capture financing-linked procurement channels. For New Entrants and Emerging Players: Begin with India's Punjab-Haryana belt where groundwater depletion mandates and power subsidy rationalization create urgent demand for modular drip irrigation and biofertilizer systems among price-sensitive smallholders. Target retrofit-friendly fertigation controllers that defer full system replacement capital outlays, using equipment financing partnerships as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Consolidation pressure builds where biological input registration timelines freeze capital in pre-commercial pipelines due to EFSA-EPA dossier harmonization gaps. Five-to-ten-year viability favors precision farming platform operators with established satellite imagery subscription bases over standalone chemistry vendors facing phasedown timelines. Watch EPA tolerance framework stringency as the inflection signal for synthetic portfolio write-down velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Input Portfolio Expansion | Captures substitution windows opened by EU Green Deal residue limit reductions and EPA reauthorization tightening. |
| Precision Platform Integration | Fuses soil sensor networks with autonomous application rigs into unified data ecosystems serving Brazilian agribusinesses. |
| Retrofit-Compatible Hardware Modularization | Enables Argentine Pampas and Australian broadacre operators to upgrade components without full system replacement. |
| Controlled-Environment Agriculture Convergence | Combines LED spectral tuning with hydroponic techniques for peri-urban UAE and Saudi Arabia leafy green production. |
| Post-Harvest Edible Coating Scale-Up | Displaces synthetic wax incumbents in Chilean and Peruvian fruit export corridors through plant-derived shelf-life extension. |
Methodological Framework
Multiple input streams — structured interviews with precision farming platform engineers, biological input R&D directors, and agribusiness procurement leads; regulatory filing analysis from EPA, EFSA, and ANVISA; and customs trade data on fertilizer component flows — were reconciled through bottom-up segment enumeration and top-down macro validation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, technology platform, end-user scale, and application system. CAGRs derived from fitted growth curves incorporating regulatory milestone timing, subsidy program restructuring, and technology adoption S-curves. Industry-specific inputs included groundwater depletion rates in India's northern agricultural belt and EU import tolerance harmonization schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory reversals, abrupt phosphorus supply disruptions from North African geopolitical events, and breakthrough efficacy improvements in temperature-sensitive microbial inoculants. Forecasts reflect documented assumptions about adoption curve slopes and subsidy continuity. A small set of named triggers — EPA tolerance framework amendments, EU F-Gas Regulation enforcement intensity, and India's power subsidy rationalization pace — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Broadacre Cropping Software Market