
 Broadacre Cropping Software Market | 2026-2036
Broadacre Cropping Software Market Size, Share, and Industry Trends Forecast 2026-2036
Broadacre Cropping Software Market Insights
The EU Green Deal is realigning the cost-of-entry calculus for broadacre software vendors seeking European market access. Trimble leverages its precision positioning infrastructure to sustain channel control across North American grain belts. John Deere anchors its competitive position through backward integration into proprietary hardware-software stacks. The Climate Corporation differentiates via machine learning models trained on proprietary weather and soil datasets.
Broadacre cropping software encompasses digital platforms that integrate satellite imagery, sensor telemetry, and agronomic algorithms to optimize planting density, input application, and harvest logistics across extensive row-crop and grain operations. These systems typically process spatial resolutions of 10-30 meters for field-scale decision support, with cloud architectures enabling real-time variable-rate prescription generation. SaaS deployment models now dominate new installations due to lower capital barriers and automatic algorithm updates, while on-premises configurations persist among cooperatives managing sensitive member data under strict governance protocols. Field Management applications currently occupy the largest revenue pool, though Data Analytics capabilities represent the fastest-expanding margin segment as growers seek predictive yield forecasting.
The EPA oversees pesticide application recordkeeping requirements that shape software feature mandates in the United States, while Australia's biosecurity regulator enforces traceability standards that drive platform compliance modules. REACH chemical registration protocols in Europe influence input tracking functionalities, and ISO 27001 certification increasingly gates procurement decisions among enterprise farming groups. Stakeholders must monitor how carbon credit verification standards reshape data architecture requirements before committing to platform investments.
Market Dynamics
Cloud-native SaaS architectures are compressing deployment cycles across broadacre operations while Australia's biosecurity framework and the EU Green Deal impose new compliance layers on platform vendors. This dual pressure is restructuring procurement criteria toward integrated traceability and carbon accounting modules.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:Sustainability disclosure requirements are forcing European grain cooperatives to adopt input-tracking software with verified carbon footprint calculations.
- Satellite imagery resolution advances:Commercial providers now deliver sub-10-meter spatial data that enables plant-level nitrogen stress detection across Brazilian soybean corridors.
- Australia's national biosecurity framework:Traceability standards for wheat and canola exports are mandating blockchain-integrated provenance logging for accredited farm management systems.
Market Restraints
- Connectivity infrastructure gaps:Rural cellular dead zones in Argentina's Pampas and Kazakhstan's northern grain belt limit real-time telemetry transmission for variable-rate application systems.
- Data sovereignty restrictions:Russia's data localization laws and China's cybersecurity regulations fragment cloud architecture options for multinational platform providers.
- Hardware sensor cost volatility:Lithium and rare earth price swings destabilize soil moisture probe and yield monitor procurement budgets for mid-scale operators.
Strategic Opportunities
- Carbon credit verification protocols:Australia's Clean Energy Regulator and California's Air Resources Board are developing standardized MRV (measurement, reporting, verification) frameworks that reward digitized farm records.
- Ukrainian Black Sea corridor reconstruction:Post-conflict agricultural modernization programs will require comprehensive farm management platforms to replace Soviet-era recordkeeping systems.
- Edge computing convergence with 5G:Low-latency field-level processing enables autonomous machinery coordination without continuous cloud uplink, opening bandwidth-constrained markets.
Industry Challenges
- Agronomic data science talent scarcity:The intersection of crop physiology, geospatial analytics, and machine learning engineering remains severely understaffed across platform development teams.
- ISO 27001 certification timelines:Enterprise farming groups now require 12-18 month third-party audit cycles that delay vendor onboarding and contract execution.
- Legacy equipment protocol fragmentation:Proprietary CAN bus implementations from 1990s-era tractors resist API integration with modern prescription mapping software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadacre Cropping Software Market |
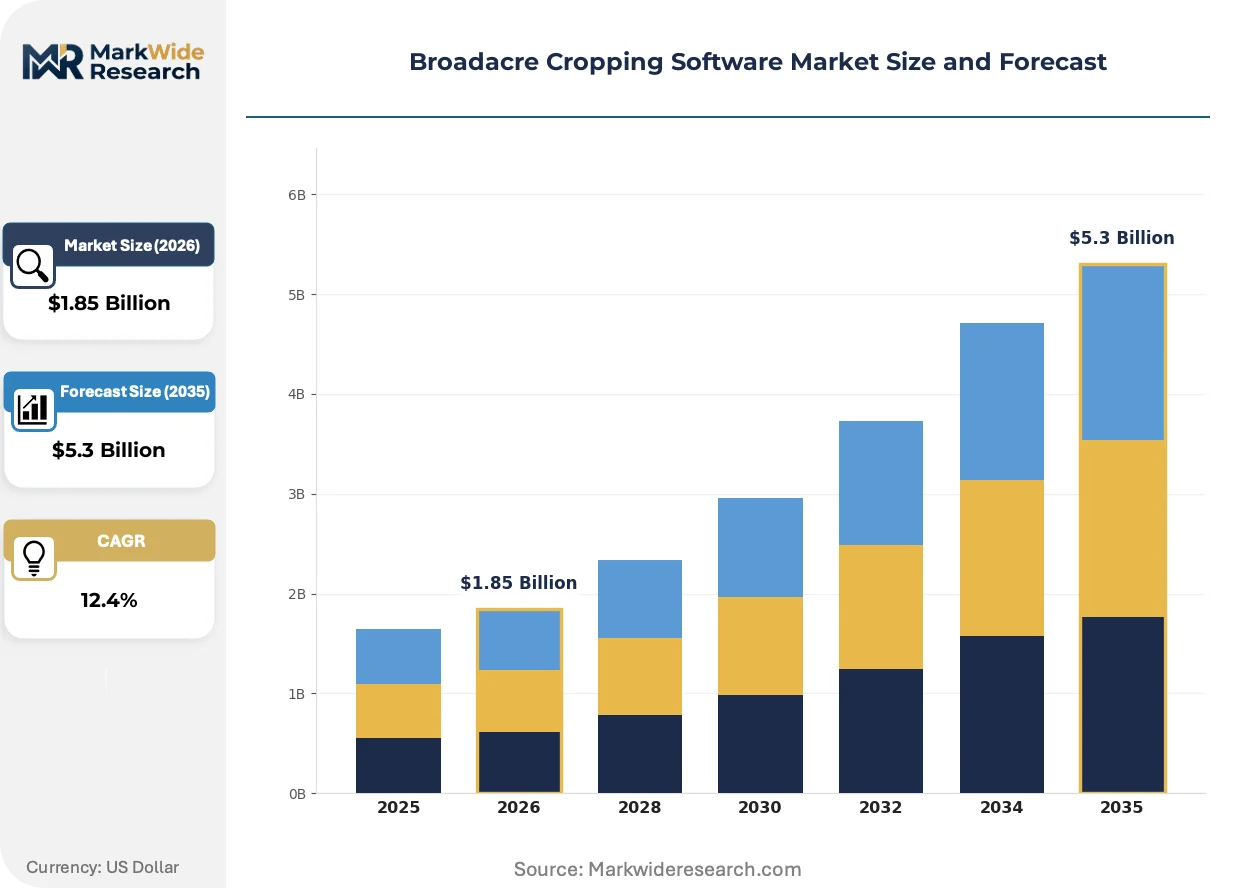
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Field Management, Crop Monitoring, Yield Analysis, Pest Control End User: Agronomists, Farmers, Cooperative Associations, Agricultural Consultants Technology: SaaS, On-premises, Mobile Applications, Web-based Platforms Application: Irrigation Management, Soil Analysis, Crop Rotation Planning, Data Analytics |
| Companies Covered | Trimble, John Deere, Ag Leader Technology, CNH Industrial, Raven Industries, Topcon Positioning Systems, The Climate Corporation, Granular, Farmers Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadacre Cropping Software Market Trends and Innovations
Machine learning inference at the field edge is displacing cloud-dependent analytics, while regulatory carbon accounting and procurement model restructuring reshape vendor-customer relationships. Three developments dominate current investment patterns.
SaaS deployment with automatic algorithm updates is overtaking on-premises installations as the default configuration for new farm management system contracts. Large-scale commercial operators in Brazil's Mato Grosso and Australia's wheat belt prioritize subscription models that eliminate capital expenditure spikes and ensure continuous model retraining on expanding yield datasets. This shift is compressing vendor revenue recognition timelines while deepening annual recurring revenue predictability.
The EU Green Deal's CSRD sustainability reporting requirements are mandating granular input tracking across European grain supply chains. Farm management platforms must now integrate fertilizer application logs, fuel consumption records, and soil carbon measurements into auditable disclosure templates. German and French cooperatives are responding by consolidating vendor relationships around providers with pre-built ESG reporting modules.
Outcome-based contracting is displacing seat-license pricing among North American enterprise farming groups. Buyers now demand yield improvement guarantees tied to software-enabled variable-rate prescriptions, with vendors assuming partial agronomic risk through performance-linked fee structures. This pattern is most visible across Iowa and Illinois corn-soy operations where input cost inflation has intensified scrutiny of technology ROI.
Broadacre Cropping Software Market Segmentation
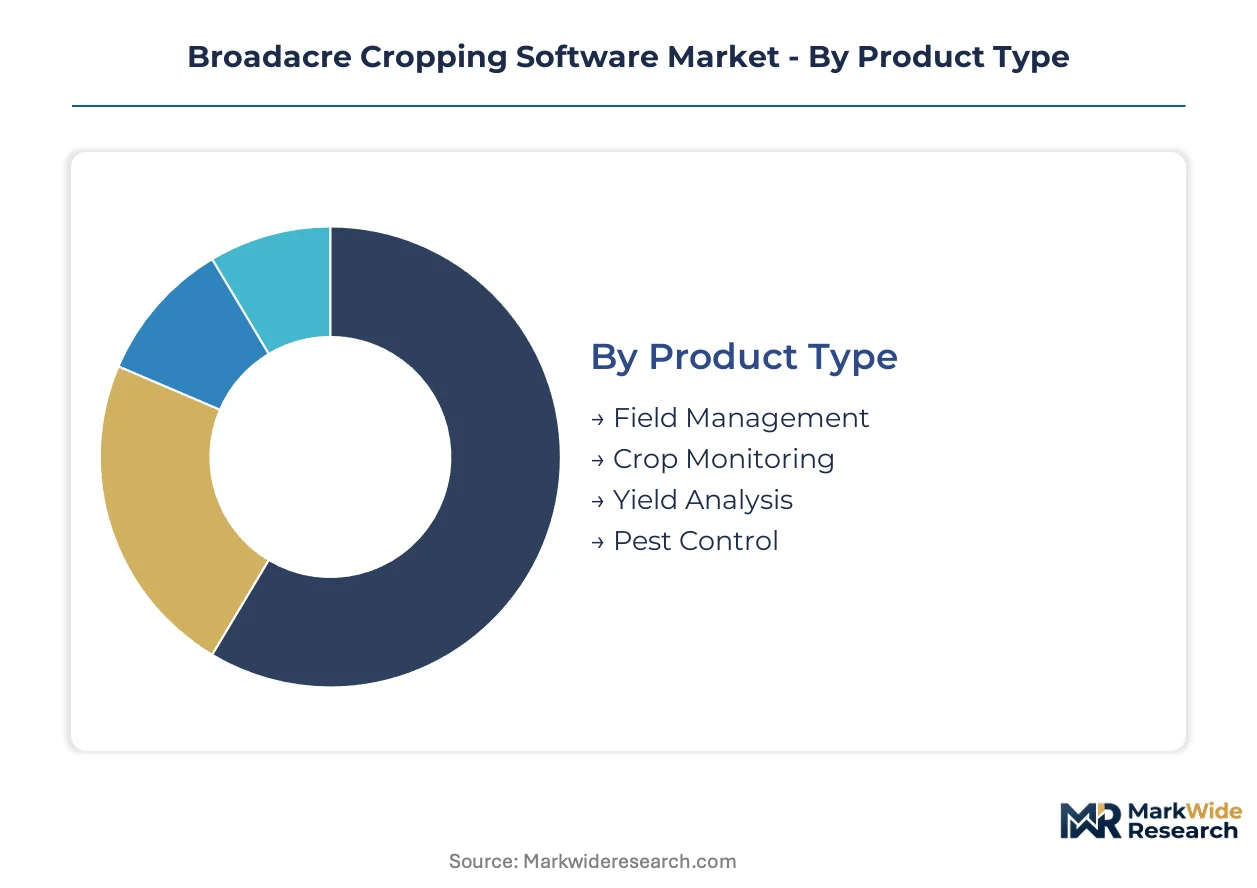
Segmentation in broadacre cropping software reveals how certification burdens, deployment economics, and user workflows reshape procurement patterns. Vendors must align platform architectures with distinct compliance requirements across product types, end-user categories, and technology stacks.
Product Type:
ISO 27001 certification gates enterprise procurement for platforms handling sensitive yield data, while EPA recordkeeping mandates shape feature requirements in the United States. Australia's biosecurity framework imposes blockchain-traceability standards on export-facing modules.
- Field Management:Platforms integrate satellite imagery, prescription mapping, and variable-rate application control for planting and input logistics. Australia's wheat belt and Brazil's Mato Grosso soybean corridor concentrate demand as large-scale operators seek unified command centers for fleet coordination and labor scheduling.
- Crop Monitoring:Systems process 10-30 meter spatial resolution imagery for nitrogen stress detection, disease onset identification, and growth stage tracking. Sub-10 meter commercial satellite availability is accelerating penetration across Argentine Pampas operations previously constrained by resolution limitations.
- Yield Analysis:Harvest data aggregation tools with moisture mapping and grain quality correlation.
- Pest Control:Application logging modules with buffer zone calculations and resistance management tracking.
Field Management sits at the top of the volume ranking, with Data Analytics capabilities climbing the fastest.
End User:
Cost tier segmentation separates capital-rich enterprise adopters from subscription-preferring mid-scale operators. Annual recurring revenue predictability varies sharply across user categories.
- Farmers:Individual operators managing 2,000-50,000 hectare grain operations prioritize SaaS models that eliminate upfront capital expenditure and ensure continuous algorithm retraining on expanding yield datasets. Iowa and Illinois corn-soy belts show intensifying scrutiny of technology ROI.
- Cooperative Associations:Member-governed entities across German and French grain regions consolidate vendor relationships around providers with pre-built ESG reporting modules for EU Green Deal compliance. On-premises configurations persist for sensitive member data under strict governance protocols.
- Agronomists:Crop advisors requiring multi-client dashboard access and prescription validation tools.
- Agricultural Consultants:Independent advisors serving diversified crop portfolios with portable audit capabilities.
Farmers dominate current installation volume, with Cooperative Associations expanding most quickly.
Technology:
Deployment model selection hinges on connectivity infrastructure maturity and data sovereignty requirements. Cloud-native architectures compress implementation cycles while edge computing opens bandwidth-constrained markets.
- SaaS:Cloud-hosted subscription platforms with automatic algorithm updates now dominate new contracts across Brazil's Mato Grosso and Australia's wheat belt. Lower capital barriers and continuous model improvements drive preference over perpetual license alternatives.
- On-premises:Server-based installations persist among cooperatives managing sensitive member data and operators in Russia and China facing data localization mandates. Higher upfront costs are offset by full data custody and offline operational resilience.
- Mobile Applications:Field-level data capture and offline prescription execution for machinery operators.
- Web-based Platforms:Browser-accessible dashboards for multi-site oversight and stakeholder reporting.
SaaS captures the largest share of new procurement, with edge-enabled hybrid architectures gaining share fastest.
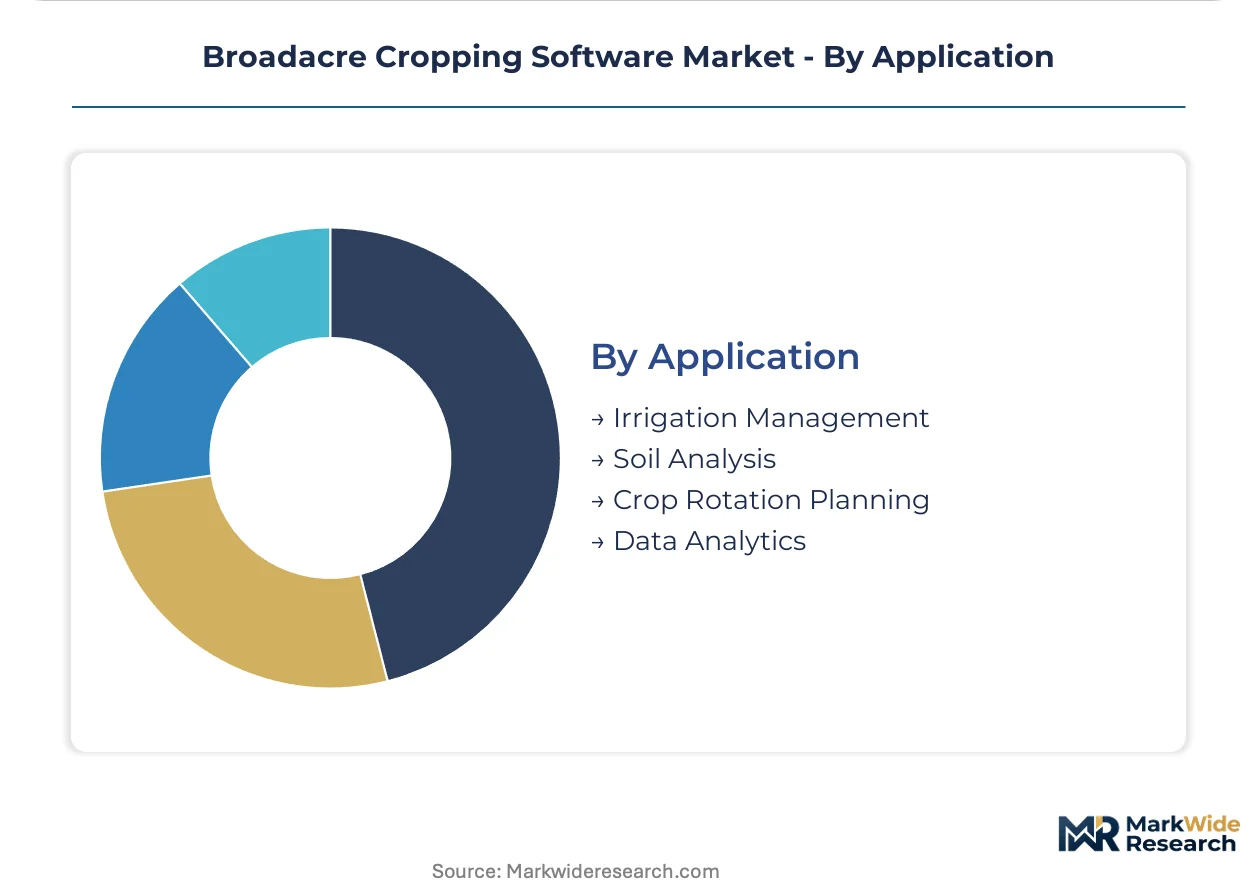
Application:
Margin concentration follows predictive capability depth. Basic logging functions commoditize while forecasting and optimization modules command premium pricing.
- Data Analytics:Machine learning models trained on proprietary weather and soil datasets enable predictive yield forecasting and input optimization. This segment represents the fastest-expanding margin pool as growers seek prescriptive recommendations beyond descriptive dashboards.
- Irrigation Management:Soil moisture probe integration with variable-rate pivot control and deficit scheduling algorithms. Water scarcity pressures across Australian dryland farming zones and California Central Valley operations intensify platform reliance.
- Soil Analysis:Spatial nutrient mapping with lime and fertilizer prescription generation.
- Crop Rotation Planning:Multi-year sequence optimization for disease breaking and carbon accounting.
Data Analytics commands the steepest expansion trajectory, with Irrigation Management holding the most mature installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic data science talent concentrates in Australia's wheat belt and Brazil's Mato Grosso corridor, anchoring platform development clusters that serve adjacent grain-producing regions.
United States
Enterprise farming groups across Iowa and Illinois corn-soy belts intensify scrutiny of technology ROI through outcome-based contracting models. The EPA mandates pesticide application recordkeeping that shapes software feature requirements nationwide. Chicago-area cooperatives consolidate procurement around platforms with pre-built ESG reporting modules for supply chain disclosure.
Brazil
Digital farm management penetration deepens fastest across Mato Grosso soybean corridors where large-scale operators seek unified command centers. ANVISA chemical registration protocols influence input tracking functionalities for export compliance. Campo Grande and Rondonópolis clusters drive SaaS adoption for fleet coordination and labor scheduling.
Australia
The national biosecurity framework mandates blockchain-integrated provenance logging for wheat and canola export accreditation. The Clean Energy Regulator develops standardized MRV frameworks rewarding digitized farm records for carbon credit verification. Perth and Adelaide software development hubs anchor precision agriculture platform engineering for domestic and Asian markets.
Germany
The EU Green Deal's CSRD sustainability reporting requirements force grain cooperatives toward granular input tracking with auditable disclosure templates. REACH chemical registration protocols shape platform compliance modules for fertilizer application logs. Bavarian and Lower Saxony farming associations consolidate vendor relationships around integrated traceability systems.
Argentina
Rural cellular dead zones across the Pampas limit real-time telemetry transmission for variable-rate application systems. The national grain export regulator enforces traceability standards that drive compliance-driven software procurement. Rosario and Buenos Aires provinces concentrate demand for satellite imagery-based nitrogen stress detection at sub-10 meter resolution.
Broadacre Cropping Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: precision positioning infrastructure owners, proprietary hardware-software stack integrators, and machine learning-native data analytics platforms. Dominant competitive moves include backward integration into captive sensor manufacturing and geographic expansion through compliance-certified localization.
Among precision positioning specialists, Trimble and Topcon Positioning Systems exemplify infrastructure-led competitive moats. John Deere represents the integrated equipment-software archetype through proprietary hardware-software stack control. The Climate Corporation and Granular sit within the data-native tier, anchoring positions around machine learning models trained on proprietary weather and soil datasets.
| Leading Market Players |
|---|
| Trimble |
| John Deere |
| Ag Leader Technology |
| CNH Industrial |
| Raven Industries |
| Topcon Positioning Systems |
| The Climate Corporation |
| Granular |
| Farmers Edge |
| Others |
Pricing and Supply Chain Analysis
Agronomic data science talent scarcity across Australia's wheat belt and Brazil's Mato Grosso corridor widens labor-cost differentials between premium-tier SaaS vendors and mid-market platform providers. This workforce concentration compresses margins for engineering-intensive feature development while amplifying pricing spreads between ISO 27001-certified enterprise suites and basic field-logging modules.
Pricing Analysis
The bundled-vs-unbundled service split separates full-stack farm management suites from modular point solutions. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and integration depth. Price differentiation hinges on ISO 27001 compliance status and volume-scale deployment commitments. Cost compression in the economy tier intensifies as open-source geospatial libraries erode basic prescription-mapping value. Cooperative associations exhibit lowest price sensitivity due to ESG reporting mandates, while individual farmers in bandwidth-constrained regions show highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Perth, Adelaide, and Campo Grande software development clusters tether platform engineering capacity to regional labor pools. Supply concentrates in Australia, Brazil, and the United States for core agronomic algorithm development. Raw material dependencies span commercial satellite imagery subscriptions, cloud compute infrastructure, and rare earth components for field-edge sensors. Single-source vulnerability runs through concentrated hyperscaler cloud regions serving agricultural data workloads. Distribution runs through direct enterprise sales teams for large-scale operators and agricultural equipment dealerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The broadacre cropping software market functions as a stable compounder anchored by compliance-driven replacement cycles. Australia's biosecurity framework and the EU Green Deal institutionalize recurring procurement mandates that sustain predictable revenue streams.
For Market Incumbents: Lock in channel control through backward integration into proprietary sensor hardware and exclusive equipment partnership agreements. Deepen ISO 27001 certification moats to delay vendor onboarding timelines for enterprise farming groups. The threat of machine learning-native entrants with superior yield prediction models demands continuous model retraining investments on expanding proprietary datasets. For New Entrants and Emerging Players: Mid-scale operators in Argentina's Pampas present an underserved buyer archetype with resolution-constrained satellite access and limited real-time telemetry infrastructure. White-space targets include edge-computing-native platforms for bandwidth-constrained grain belts and carbon credit verification modules for Australia's Clean Energy Regulator compliance. A hardware-agnostic go-to-market angle bypasses John Deere's proprietary stack lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play data analytics platforms lacking captive distribution channels. Long-term viability frames around ten-year windows as carbon accounting standardization consolidates vendor relationships. Acquisition target archetypes include machine learning-native yield forecasting specialists with proven MRV framework integrations. The signal to watch is California Air Resources Board protocol harmonization with Australian standards as an inflection indicator for cross-regional platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies satellite imagery, prescription mapping, and variable-rate control for Mato Grosso soybean operators. |
| Acquisition of Specialist Firm | Absorbs machine learning-native yield forecasting capabilities trained on proprietary weather datasets. |
| Geographic Expansion | Localizes compliance modules for EU Green Deal CSRD reporting across German grain cooperatives. |
| Strategic Partnership | Secures exclusive satellite imagery sub-10-meter resolution access for Brazilian nitrogen stress detection. |
| Product Launch | Introduces blockchain-integrated provenance logging for Australia's wheat and canola export accreditation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged farm management software CTOs, agricultural cooperative procurement leads, platform integration specialists, and agronomic data scientists across Australia's wheat belt and Brazil's Mato Grosso corridor. Secondary validation drew from EPA pesticide application filings, EU Green Deal regulatory texts, ANVISA chemical registration databases, and Clean Energy Regulator carbon protocol documentation. Bottom-up installation tracking across deployment models and top-down revenue estimation from public equipment manufacturer disclosures were triangulated against regional grain production statistics.
Segment-weighting approaches distributed value estimates across SaaS, on-premises, mobile, and web-based technology configurations. The analytical framework modeled Field Management, Crop Monitoring, Yield Analysis, and Pest Control product types alongside Data Analytics, Irrigation Management, Soil Analysis, and Crop Rotation Planning applications. CAGRs were derived from fitted growth curves against historical penetration rates and regulatory mandate implementation timelines. Forecast inputs incorporated satellite imagery resolution advancement trajectories and 5G edge computing deployment schedules for bandwidth-constrained markets.
Inputs from cooperative procurement leads and platform vendor executives were available through the study window; gaps in mid-scale operator pricing transparency introduce uncertainty bands around segment-level value estimates. Forecasts reflect documented assumptions regarding EU CSRD enforcement timing and Australian biosecurity blockchain mandate rollout schedules. Material deviation in carbon credit verification protocol harmonization across California and Australian regulators warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Agriculture Machine to Machine (M2M) Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market