
 Agriculture Machine to Machine (M2M) Market | 2026-2036
Agriculture Machine to Machine (M2M) Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Machine to Machine (M2M) Market Outlook
Market Context with Strategic Players
The capability gap between precision-hardware manufacturers and software-native entrants is rotating competitive capital allocation toward integrated platform development. Deere & Company leverages its dealership network to bundle telemetry subscriptions with equipment financing. Trimble Inc. anchors its position through GNSS correction services that lock in recurring revenue from precision agriculture workflows.
Technical Definition and Structural Segments
Agriculture Machine to Machine (M2M) denotes autonomous data exchange between connected field devices—encompassing soil moisture probes operating at sub-gigahertz frequencies, variable-rate actuators, and edge-computing gateways—without human mediation, primarily to optimize input efficiency and yield outcomes. Sensors dominate hardware attachment rates as farmers prioritize real-time microclimate and soil condition visibility. Cellular technology carries the largest installed base among connectivity options, though LoRaWAN is gaining traction in expansive ranchland where low-power wide-area architecture reduces subscription costs.
Regulatory Frame and Forward-Looking Close
The EPA governs chemical application rates that M2M systems must document for compliance, while the FAA regulates beyond-visual-line-of-sight drone operations critical to aerial crop monitoring. FCC spectrum allocations for rural broadband directly determine where cellular-based M2M networks achieve reliable coverage. Stakeholders must weigh spectrum auction outcomes against LoRaWAN network buildouts when selecting connectivity architectures for new deployments.
Market Dynamics
The agriculture M2M sector is consolidating around edge-computing architectures that process field data locally rather than transmitting raw telemetry to distant cloud servers, compressing latency for real-time irrigation and spraying decisions.
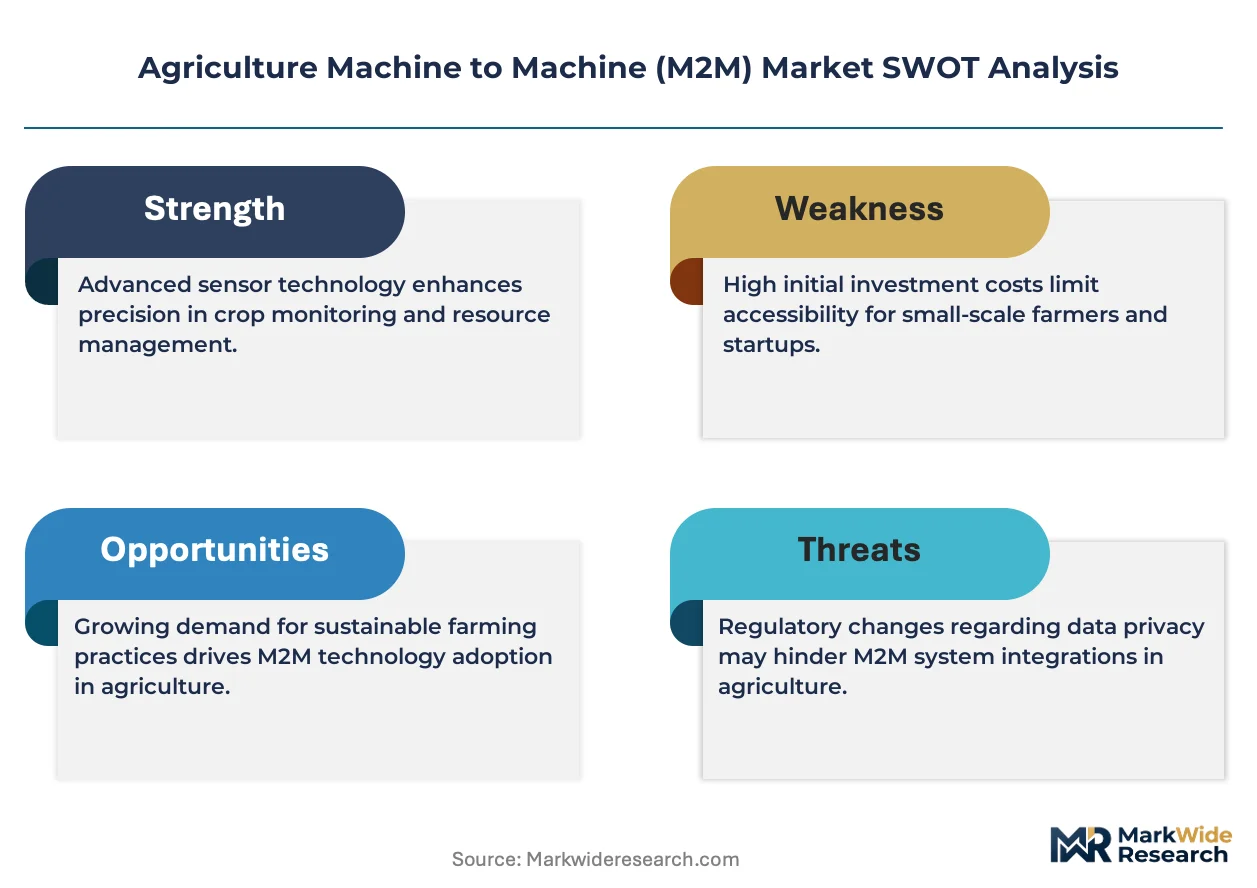
Growth Catalysts
- LoRaWAN deployment:Low-power wide-area networks are penetrating expansive ranchlands across Australia and Argentina where cellular infrastructure remains sparse, slashing connectivity subscription costs for remote moisture monitoring.
- EPA chemical documentation mandates:The US Environmental Protection Agency now requires granular application records for restricted-use pesticides, forcing growers to adopt automated logging systems that M2M platforms provide.
- Brazilian soybean digitization:Large-scale operators in Mato Grosso are retrofitting harvest fleets with telemetry to coordinate logistics across thousand-hectare blocks, creating concentrated demand clusters for integrated platforms.
Market Restraints
- Silicon supply concentration:Edge-computing gateway production depends on semiconductor fabrication concentrated in Taiwan and South Korea, exposing hardware manufacturers to geopolitical disruption risks.
- FAA operational friction:Beyond-visual-line-of-sight drone regulations in the United States require waivers for automated aerial crop monitoring, delaying deployment timelines for precision agriculture service providers.
- Lithium battery cost volatility:Sensor nodes and field gateways rely on lithium-ion power supplies whose input costs fluctuate with commodity markets, squeezing hardware margins for OEMs.
Strategic Opportunities
- Indian smallholder penetration:The country's agricultural regulator TRAI has allocated unlicensed spectrum bands for rural IoT, opening white space for low-cost M2M bundles targeting fragmented landholdings in Punjab and Haryana.
- Carbon credit verification:The EU Green Deal's Carbon Border Adjustment Mechanism creates demand for soil carbon sequestration documentation, positioning M2M soil monitoring as a compliance infrastructure layer.
- Computer vision convergence:On-device image processing at field gateways is merging with spectral drone sensors to enable real-time pest detection without cloud dependency, unlocking premium pricing for integrated hardware-software stacks.
Industry Challenges
- RF engineering talent scarcity:Sub-gigahertz sensor network deployment requires specialized expertise in propagation modeling for agricultural terrain, a skill set concentrated among legacy telecom engineers nearing retirement.
- Legacy equipment integration:Mixed fleets of decade-old tractors without CAN bus interfaces force retrofit hardware development, complicating platform standardization for OEMs targeting mid-size operations.
- CE marking timeline compression:European machinery safety directives now mandate cybersecurity certification for connected agricultural equipment, extending product launch cycles by 8-14 months for hardware vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Machine to Machine (M2M) Market |
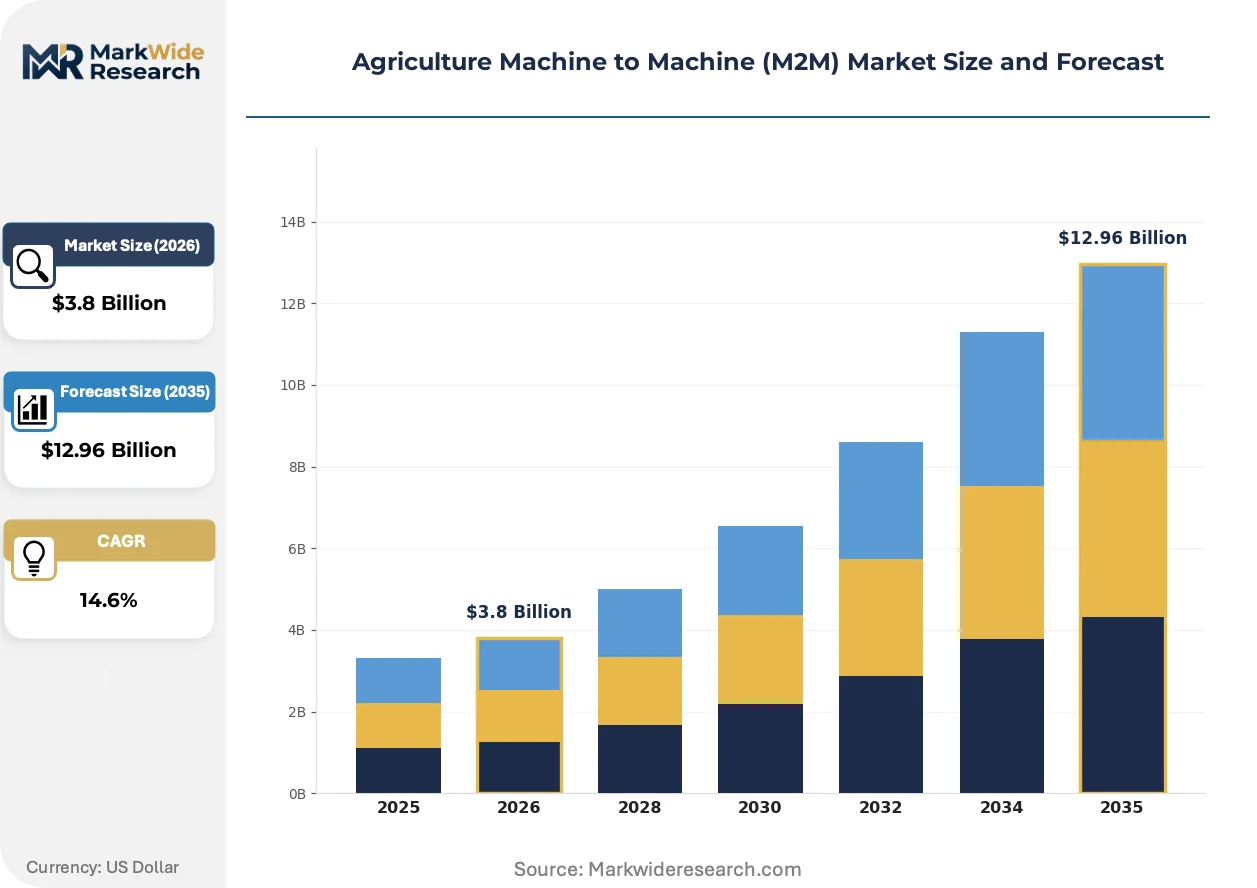
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Actuators, Software, Communication Modules Technology: NB-IoT, LoRaWAN, Zigbee, Cellular Application: Precision Farming, Livestock Monitoring, Soil Management, Crop Tracking End User: Farmers, Agricultural Cooperatives, Agribusinesses, Research Institutions |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., Trimble Inc., Topcon Corporation, Kubota Corporation, Hexagon AB, CLAAS KGaA mbH, Yanmar Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Machine to Machine (M2M) Market Strategic Shifts
Telemetry architectures are pivoting from cloud-centric models toward distributed edge intelligence, while regulatory pressure on chemical traceability and carbon accounting is rewriting procurement criteria for precision agriculture infrastructure.
Edge-computing gateways with on-board inference engines are supplanting raw data transmission to distant servers, enabling sub-second actuator response for variable-rate spraying. Large-scale Brazilian and Australian operators are deploying these units at field perimeter nodes. The shift is compressing bandwidth requirements and reducing recurring cellular subscription costs for expansive holdings.
The EU Green Deal's Farm to Fork strategy is mandating 50% reduction in chemical pesticide use by 2030, forcing M2M platform vendors to reposition around input optimization rather than volume-driven automation. German and Dutch precision agriculture adopters are prioritizing systems that document compliance with integrated pest management protocols. Hardware specifications now emphasize audit-trail granularity over raw throughput metrics.
Equipment-as-a-service contracting is displacing capital purchase models among North American mid-size growers who face compressed operating margins. John Deere Financial and regional ag-lenders are bundling telemetry subscriptions with operating leases, transferring technology obsolescence risk from farm balance sheets to OEMs. The pattern is most pronounced in Iowa and Illinois corn-soy rotations where equipment utilization rates justify per-acre pricing structures.
Agriculture Machine to Machine (M2M) Market Segmentation
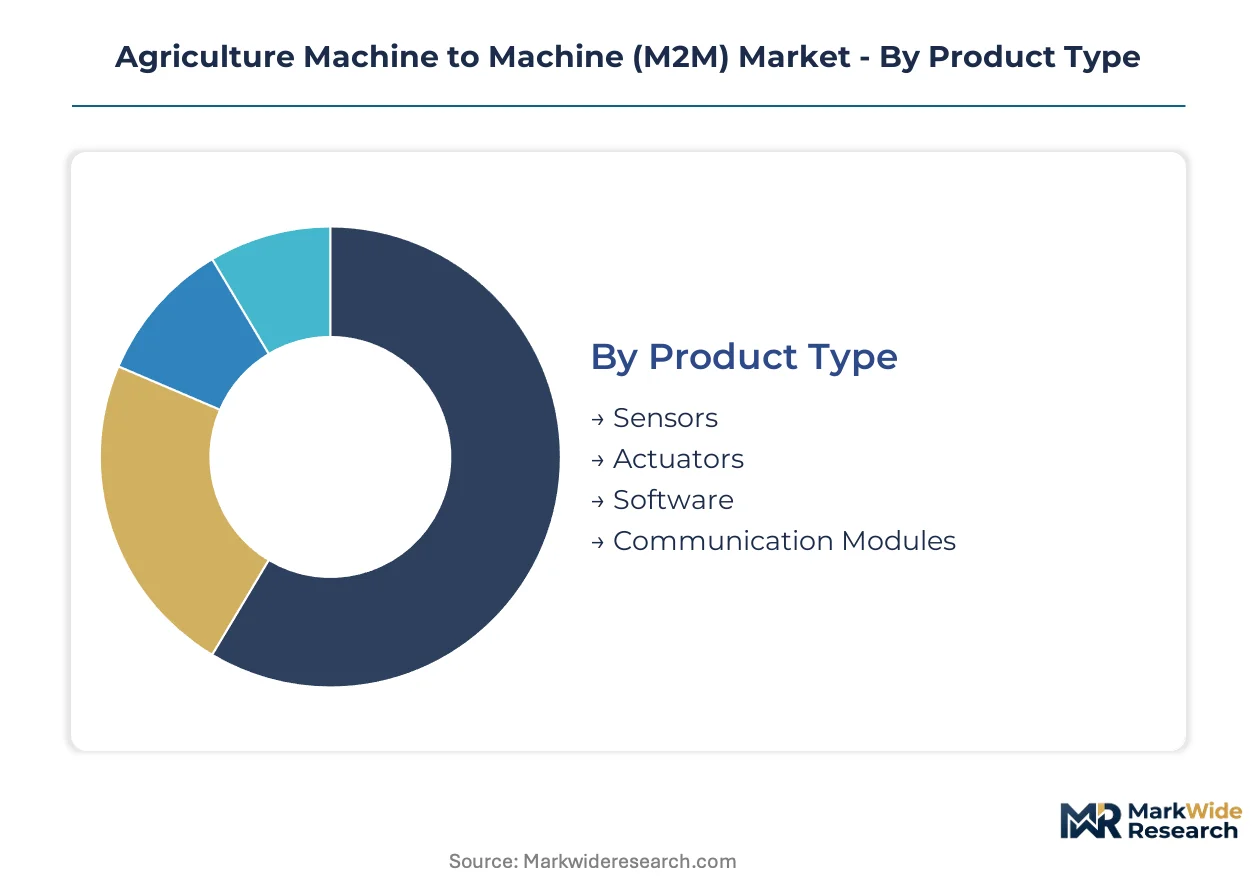
Agriculture M2M segmentation reveals divergent deployment economics across hardware, connectivity, and software layers. Product mix varies sharply between export-oriented precision farming markets and domestically focused livestock operations.
Product Type:
Sensors dominate Brazilian and Australian export agriculture where real-time telemetry justifies premium hardware spend. Software and communication modules concentrate in North American and European domestic deployments tied to regulatory compliance systems.
- Sensors:Soil moisture probes, microclimate stations, and spectral imaging units capture field-level data at sub-gigahertz frequencies. Brazilian Mato Grosso soybean operators and Australian wheatbelt growers drive concentrated demand for ruggedized IP67-rated units that withstand harvest-season dust exposure.
- Software:Edge-computing platforms and cloud analytics dashboards process telemetry into irrigation and spraying prescriptions. German and Dutch precision agriculture adopters prioritize audit-trail granularity for EU Green Deal chemical reduction mandates, compressing development cycles for compliance-focused vendors.
- Actuators:Variable-rate valves and autonomous spraying nozzles execute real-time input adjustments based on sensor feedback. These units cluster in US Corn Belt operations where EPA documentation requirements for restricted-use pesticides force automated logging integration.
- Communication Modules:Gateway hardware bridging field sensors to cellular or LPWAN backhaul. Argentine and Australian ranchland deployments favor solar-powered units with LoRaWAN chipsets to circumvent sparse cellular infrastructure.
Sensors command the established base. The steepest expansion runs through software as compliance documentation and carbon accounting rewrite procurement criteria.
Technology:
Cost tier differentiation separates subscription-heavy cellular deployments from capital-light LPWAN architectures. Volume concentration in expansive holdings favors low-power wide-area protocols over bandwidth-intensive alternatives.
- Cellular:LTE-M and 5G RedCap modules deliver high-bandwidth telemetry for drone imagery and real-time video analytics. US and German operators with reliable rural coverage pay premium subscription rates for guaranteed quality-of-service SLAs during critical planting windows.
- LoRaWAN:Unlicensed spectrum operation slashes connectivity costs for remote moisture monitoring across thousand-hectare blocks. Australian pastoralists and Argentine soybean growers deploy these networks where cellular towers remain economically unviable.
- NB-IoT:Narrowband cellular protocols balance power efficiency with licensed spectrum reliability. Indian Punjab and Haryana smallholders access TRAI-allocated rural IoT bands through low-cost bundled hardware.
- Zigbee:Mesh networking for localized sensor clusters in controlled-environment agriculture. Dutch greenhouse operators leverage these protocols for sub-second climate control feedback loops.
Cellular carries the revenue concentration. The fastest share gains accrue to LoRaWAN as ranchland digitization accelerates in South America and Oceania.
Application:
Customer type segmentation maps directly to application priority: agribusinesses prioritize precision farming at scale while cooperatives concentrate investment in crop tracking logistics.
- Precision Farming:Variable-rate input application guided by real-time soil and canopy data. Iowa and Illinois corn-soy rotations see concentrated equipment-as-a-service bundling through John Deere Financial and regional ag-lenders.
- Livestock Monitoring:Collar-mounted sensors tracking animal health, location, and estrus cycles in extensive grazing systems. Brazilian cattle operations in Mato Grosso and Queensland beef producers drive hardware attachment rates for GPS-enabled biologgers.
- Soil Management:Carbon sequestration documentation and nutrient mapping for compliance and optimization. EU Green Deal Carbon Border Adjustment Mechanism creates infrastructure demand among German and French arable farms.
- Crop Tracking:Harvest logistics coordination across fleet telemetry and grain elevator scheduling. Large-scale Brazilian operators retrofit combines and trucks to synchronize thousand-hectare block workflows.
Precision Farming anchors current installed value. Soil Management is climbing the fastest as carbon credit verification reshapes platform positioning.
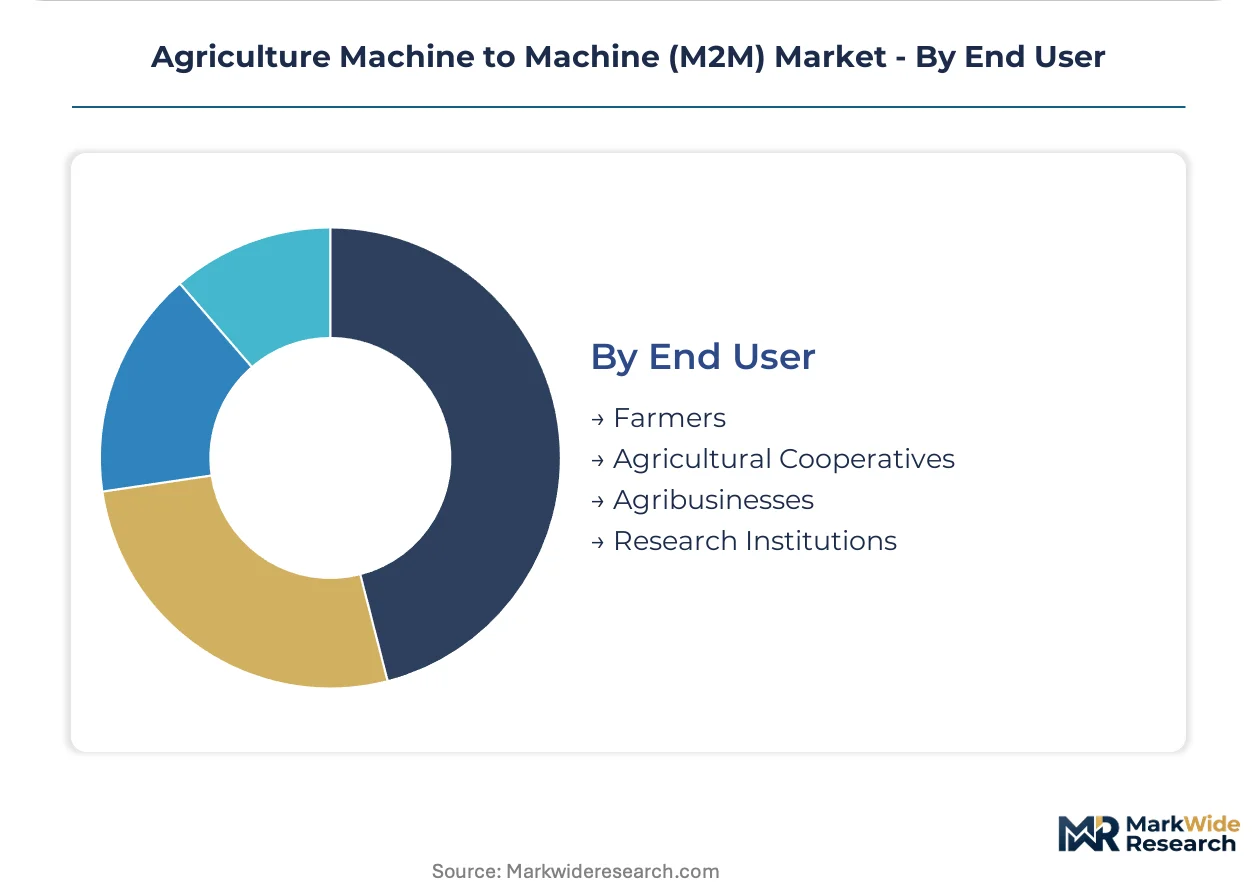
End User:
Maturity segmentation separates legacy equipment retrofit markets from greenfield integrated platform deployments. Margin structure favors full-stack vendors serving consolidated agribusinesses over fragmented smallholder segments.
- Agribusinesses:Thousand-hectare operators with capital budgets for integrated telemetry and autonomous equipment. These buyers command volume discounts and demand white-glove implementation support.
- Agricultural Cooperatives:Pooled procurement entities serving member farms with shared infrastructure. Iowa and Illinois grain cooperatives bundle M2M subscriptions with storage and logistics services.
- Farmers:Individual owner-operators ranging from mid-size US growers to Indian smallholders. Punjab and Haryana fragmentation forces vendors toward low-cost hardware-software bundles on TRAI-allocated unlicensed spectrum.
- Research Institutions:Universities and government extension services validating agronomic models. These users prioritize open data formats and interoperability over proprietary platform lock-in.
Agribusinesses dominate revenue concentration. The cooperative channel is expanding most quickly as equipment-as-a-service models transfer technology risk from farm balance sheets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Brazilian and Australian operators who command volume discounts on integrated telemetry bundles, while Indian smallholders access stripped-down hardware on TRAI-allocated unlicensed spectrum at fractionally lower unit economics.
United States
Mid-size Iowa and Illinois corn-soy growers drive equipment-as-a-service adoption through John Deere Financial bundling. The EPA mandates granular documentation for restricted-use pesticides, forcing automated logging integration. The US Corn Belt anchors variable-rate actuator deployment for compliance-driven spraying operations.
Brazil
Thousand-hectare Mato Grosso soybean operators retrofit harvest fleets with telemetry to synchronize logistics across dispersed blocks. ANVISA influences agricultural chemical traceability standards that M2M platforms must satisfy. The Cerrado belt concentrates demand for ruggedized IP67-rated sensors that withstand harvest-season dust exposure.
Germany
Precision agriculture adopters prioritize audit-trail granularity for EU Green Deal Farm to Fork chemical reduction mandates. The country's national machinery safety regulator enforces cybersecurity certification for connected equipment under CE marking directives. The Lower Saxony arable belt leads soil carbon sequestration documentation for Carbon Border Adjustment Mechanism compliance.
Australia
Pastoralists across Queensland and Western Australia deploy LoRaWAN networks where cellular infrastructure remains economically unviable. The TGA influences agricultural drone operational standards for beyond-visual-line-of-sight monitoring. The wheatbelt drives concentrated demand for solar-powered gateway hardware bridging remote moisture sensors.
India
Fragmented Punjab and Haryana smallholders access low-cost NB-IoT bundles through TRAI-allocated rural IoT spectrum allocations. The country's agricultural regulator mandates interoperability standards for cooperative-shared infrastructure. The Indo-Gangetic Plain clusters vendor activity around hardware-software bundles priced for sub-hectare landholdings.
Agriculture Machine to Machine (M2M) Market Competitive Environment
Concentration sits with integrated platform vendors who bundle telemetry subscriptions with equipment financing. The vendor base spans three tiers: legacy machinery manufacturers with captive dealership networks, GNSS correction service providers locking in recurring revenue, and software-native entrants building edge-computing stacks. Dominant competitive moves include equipment-as-a-service contracting that transfers technology obsolescence risk to OEMs, and strategic partnerships between hardware manufacturers and rural telecommunications carriers.
Within the legacy machinery tier, Deere & Company and CNH Industrial N.V. occupy positions defined by captive financing arms and dealership network density. Trimble Inc. exemplifies the GNSS-correction archetype through recurring service revenue models. Among Japanese diversified industrials, Kubota Corporation and Yanmar Holdings Co., Ltd. represent regional equipment specialists expanding telemetry integration across compact machinery portfolios.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| Trimble Inc. |
| Topcon Corporation |
| Kubota Corporation |
| Hexagon AB |
| CLAAS KGaA mbH |
| Yanmar Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
CE marking cybersecurity certification gates both European market access and price stratification across hardware tiers, compressing launch timelines for uncertified vendors while enabling premium positioning for compliant OEMs. This regulatory threshold simultaneously filters supply base qualification and segments buyers by risk tolerance.
Pricing Analysis
Configured-to-order telemetry bundles command 40-60% premiums over standard catalog SKUs due to integration engineering and white-glove deployment support. Equipment-as-a-service contracting dominates North American mid-size grower procurement, transferring technology obsolescence risk to OEMs through per-acre subscription structures. Price differentiation stems from certification grade and after-sales service bundling. Margins are tightening due to lithium battery cost volatility squeezing hardware economics. Indian smallholders on TRAI-allocated spectrum exhibit highest price sensitivity; Brazilian agribusinesses with thousand-hectare blocks demonstrate lowest sensitivity due to volume discount leverage.
Supply Chain Analysis
Taiwan Strait semiconductor fabrication concentration creates single-source vulnerability for edge-computing gateway production, with foundry capacity allocation determining hardware availability timelines. Taiwan, South Korea, and China anchor semiconductor supply for LoRaWAN chipsets and cellular modules. Lithium-ion cells, sub-gigahertz RF components, and IP67-rated sensor housings constitute critical input dependencies. Tariff exposure on Chinese-manufactured gateway hardware intensifies cost pressure for North American deployments. Distribution runs through captive dealership networks for legacy machinery OEMs and direct-to-grower digital channels for software-native entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among thousand-hectare Brazilian and Australian operators who command volume discounts, fragmenting pricing power away from mid-size growers toward consolidated agribusiness procurement desks.
For Market Incumbents: Compound platform stickiness through edge-computing gateway bundling that locks in recurring telemetry subscriptions alongside equipment financing. Deepen backward integration into semiconductor sourcing to mitigate Taiwan foundry concentration risk. Prioritize EPA compliance documentation automation as chemical traceability mandates tighten. Defend against software-native entrants by accelerating API interoperability for mixed-fleet retrofits. For New Entrants and Emerging Players: Cooperative-shared infrastructure in Iowa and Illinois grain logistics represents the most penetrable white space, where pooled procurement entities under-serve member farms with fragmented M2M adoption. Target Indian Punjab and Haryana smallholders through TRAI-allocated unlicensed spectrum bundles priced below cellular alternatives. Pursue carbon credit verification platform positioning as EU Green Deal compliance infrastructure demand accelerates among German arable operators. For Investors and Strategic Acquirers: FAA beyond-visual-line-of-sight waiver approvals reshape the acquisition landscape for drone-enabled precision agriculture service providers, signaling regulatory pathway clarity for automated aerial monitoring platforms. Five-to-ten-year viability favors integrated hardware-software vendors with edge-computing capabilities and recurring revenue lock-in. Acquisition target archetype: software-native entrants with computer vision IP and established LoRaWAN network deployments in Australian or Argentine ranchlands. Monitor EPA chemical documentation mandate enforcement intensity as inflection indicator for compliance-focused platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Gateway Development | Compresses latency for real-time spraying decisions in Brazilian Cerrado operations. |
| LoRaWAN Network Partnership | Slashes connectivity costs for Australian pastoralists beyond cellular coverage. |
| Carbon Accounting Platform Launch | Positions M2M soil monitoring as EU Green Deal compliance infrastructure layer. |
| Equipment-as-a-Service Expansion | Transfers technology obsolescence risk from Iowa corn-soy growers to OEM balance sheets. |
| Cybersecurity Certification Investment | Accelerates CE marking timelines for European market access under machinery safety directives. |
Study Parameters
Operator-level perspectives from precision agriculture directors, cooperative procurement managers, OEM telemetry product leads, and FCC spectrum policy specialists anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from SEC equipment manufacturer filings, EPA chemical application databases, FAA drone waiver records, and TRAI spectrum allocation notices. Bottom-up sensor deployment counts and top-down agribusiness capital expenditure estimates were triangulated to establish market sizing.
Sensitivity analysis tested forecast robustness against semiconductor supply disruption scenarios and regulatory timeline compression effects. The analytical framework modeled segmentation across hardware-software-actuator product types, cellular-LoRaWAN-NB-IoT technology tiers, precision farming-soil management-crop tracking applications, and agribusiness-cooperative-farmer end-user archetypes throughout the projection horizon. CAGRs were derived from installed base expansion curves and replacement cycle dynamics, with edge-computing adoption rates and carbon credit verification demand as agriculture-specific forecast inputs.
Forecasts assume regulatory continuity in EPA chemical documentation mandates and FAA beyond-visual-line-of-sight waiver frameworks; material policy shifts would require re-modeling. Semiconductor supply concentration and lithium commodity volatility constitute primary forecast revision risks. Practitioners should keep alternative scenarios live as spectrum auction outcomes and EU Green Deal implementation intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Technologies
Broadacre Cropping Software Market
Agricultural Technologies
Global Greenhouse Soil Market
Agricultural Technologies
Global Food and Agriculture Technology and Products Market
Agricultural Technologies
Post Harvesting Technologies Market
Agricultural Technologies
Europe Agricultural Enzymes Market
Agricultural Technologies
Plant Phenotyping Market
Agricultural Technologies
Agricultural Drones Market
Agricultural Technologies
Horticulture LED Lighting Market
Agricultural Technologies
Farming As a Service Market
Agricultural Technologies
Global Agriculture Supply Chain Management Market