
 Robot Mops Market | 2026-2036
Robot Mops Market Size, Share, and Industry Trends Forecast 2026-2036
Robot Mops Market Analytics
Domestic labor scarcity in developed economies is bifurcating the robot mops landscape into premium autonomous systems and budget-assisted devices. Ecovacs leverages its integrated manufacturing base in Suzhou to control component costs across the full product stack. iRobot sustains brand recognition in North American retail channels despite intensifying Asian competition. Dreame specializes in high-speed motor miniaturization, extending its vacuum expertise into mopping hybrids with self-cleaning dock systems.
Robot mops are autonomous or semi-autonomous floor-cleaning devices combining microfiber or rotary pad systems with water reservoirs, typically operating at 40-60 decibels with 90-150 minute battery cycles for residential and commercial hard-surface maintenance. The automatic product type dominates volume shipments due to hands-free docking and scheduling, while hybrid units capture expanding margin pools by merging vacuum suction with wet mopping in single-pass workflows. Laser navigation systems lead technology adoption in premium tiers, whereas infrared and gyroscope configurations occupy entry-level price bands through simplified obstacle mapping.
The US FCC certifies wireless connectivity modules for robot mops, while the EU's Ecodesign Directive and REACH framework constrain battery chemistry and water consumption thresholds for market entry. China's SAMR enforces GB standards on robotic appliance safety and electromagnetic compatibility, shaping domestic manufacturer R&D priorities. Stakeholders must monitor evolving right-to-repair mandates and battery recycling obligations, as regulatory compliance costs will increasingly determine which product architectures achieve scalable distribution across major economies.
Market Dynamics
Laser navigation systems are compressing price premiums across the robot mops category as Chinese manufacturers achieve component parity with established sensor suppliers, forcing incumbents to defend positioning through dock ecosystem integration rather than hardware differentiation alone.
Growth Catalysts
- Dual-income household density:Metropolitan corridors in Germany and China's first-tier cities generate concentrated demand for automated cleaning solutions as domestic labor availability tightens.
- REACH battery chemistry standards:EU constraints on hazardous substances are accelerating lithium iron phosphate adoption, reducing thermal risk profiles and enabling residential insurance acceptance.
- Smart home protocol convergence:Matter certification is eliminating fragmentation between proprietary IoT ecosystems, reducing consumer integration friction and expanding addressable base.
Market Restraints
- Lidar sensor supply concentration:Production of rotating laser modules clusters among Shenzhen and Suzhou component houses, creating single-source vulnerability for mid-tier manufacturers.
- GB standards compliance costs:China's SAMR electromagnetic compatibility testing mandates impose six-figure certification burdens that disproportionately burden sub-scale entrants.
- Manual mop substitution persistence:Hard-surface maintenance in emerging Southeast Asian markets retains labor-cost advantages that delay robot adoption.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for component localization offer tariff-advantaged assembly points for export-oriented brands.
- Commercial hospitality integration:Hotel chains and co-working operators represent untapped volume for fleet-managed units with centralized dock networks.
- EU right-to-repair mandates:Upcoming battery and motor accessibility requirements favor modular architectures designed for field serviceability over sealed disposable units.
Industry Challenges
- Embedded firmware talent scarcity:Simultaneous SLAM algorithm development and power management optimization demands specialized skill sets concentrated among Shenzhen and Bangalore engineering pools.
- Dock manufacturing capex intensity:Self-cleaning base stations require precision injection molding and fluid handling subsystems that strain capital allocation for sub-scale competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robot Mops Market |
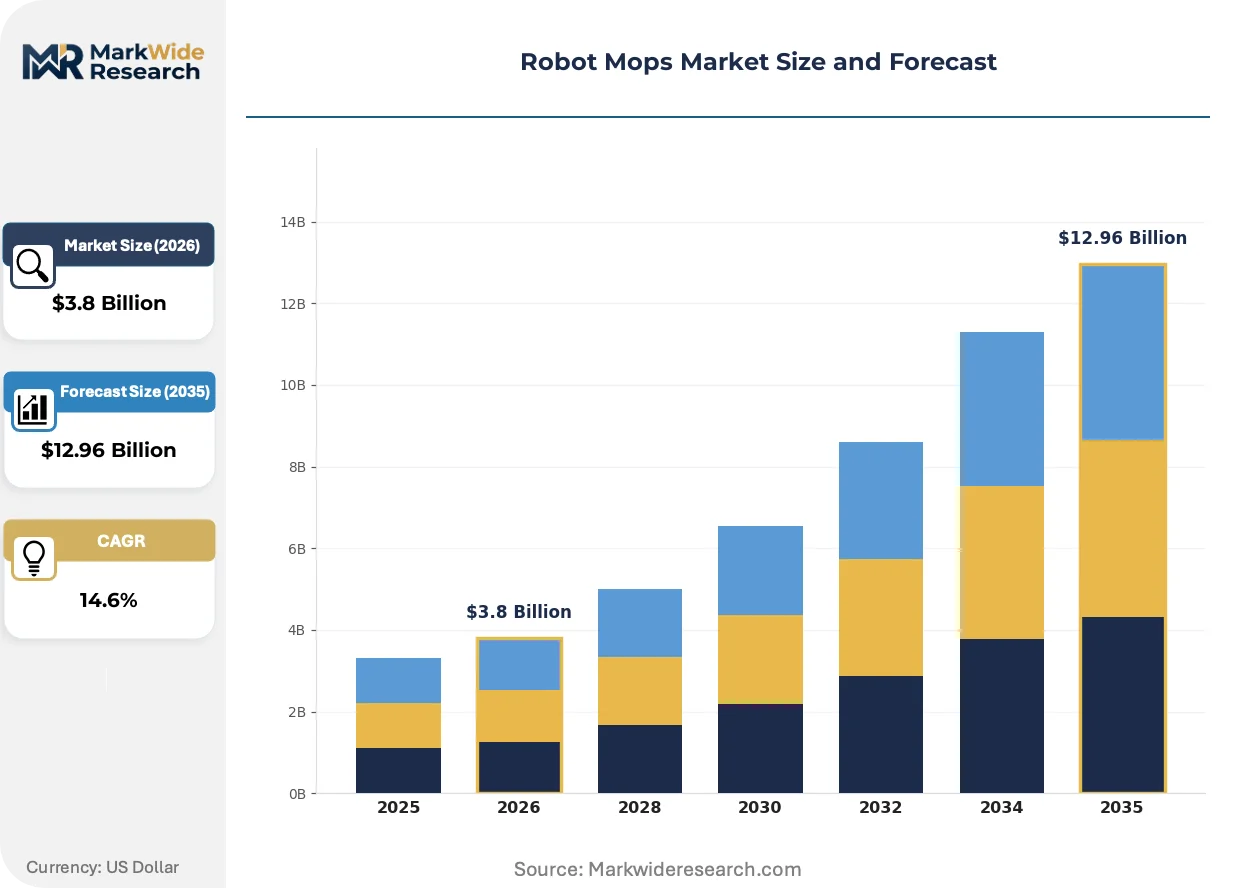
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Hybrid, Programmable End User: Residential, Commercial, Institutional, Industrial Technology: Laser Navigation, Visual Navigation, Gyroscope, Infrared Distribution Channel: Online Retail, Offline Retail, Distributors, Direct Sales |
| Companies Covered | Roborock, Dreame, Ecovacs, Narwal, Mova, iRobot, Eufy, Dyson, Lefant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robot Mops Market Evolving Landscape
Component miniaturization and regulatory pressure on battery chemistry are converging to reshape competitive advantage around thermal management and dock ecosystem completeness rather than raw suction specifications.
Vibration-based mopping modules are decomposing the traditional separation between wet-cleaning performance and mechanical complexity. High-frequency oscillation systems from Dreame and Roborock achieve stain removal parity with rotary pad configurations using fewer moving parts. Residential buyers in China's Yangtze River Delta are adopting these units at replacement-cycle velocity, compressing margin pools for legacy rotary motor suppliers.
EU Ecodesign Directive water consumption thresholds are tightening entry requirements for appliances sold across the single market. Manufacturers must now document liter-per-cycle efficiency across hard-surface categories, with non-compliant SKUs facing delisting from major retail channels. German and French distributors are prioritizing SKUs with certified efficiency ratings, shifting procurement criteria away from raw performance metrics.
Direct-to-consumer subscription models for consumable replenishment are displacing traditional retail attachment sales in North American and Western European markets. iRobot and Ecovacs now capture recurring revenue through automated pad and solution shipments tied to usage telemetry. This pattern concentrates among urban households with predictable cleaning schedules and reliable broadband infrastructure.
Robot Mops Market Segmentation
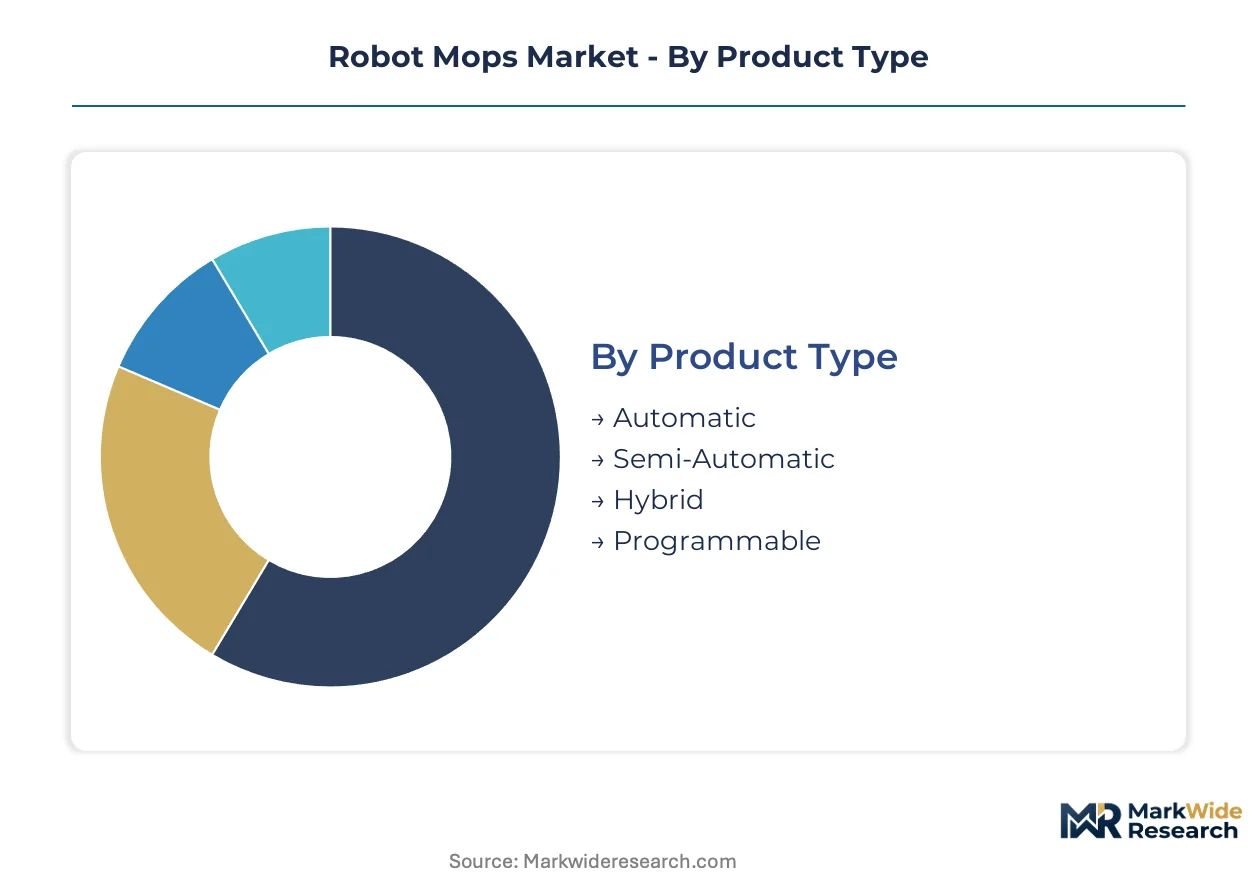
Robot mops segment across four dimensions that determine pricing architecture and channel strategy. Product type and technology selection drive component cost structures, while end-user classification shapes service attach rates and replacement cycles.
Product Type:
Margin pools concentrate in dock-integrated systems where consumable replenishment generates recurring revenue streams.
- Automatic:These units execute full cleaning cycles without human intervention, returning to charging docks upon completion. Demand clusters in Germany's metropolitan corridors and China's first-tier cities where dual-income households prioritize hands-free operation. SAMR's GB standards on electromagnetic compatibility add certification overhead that favors established manufacturers with testing infrastructure.
- Hybrid:Vacuum-mopping combinations capture expanding margin pools by consolidating floor maintenance into single-pass workflows. China's Yangtze River Delta shows replacement-cycle velocity for these units as consumers upgrade from single-function predecessors. Self-cleaning dock systems differentiate premium configurations.
- Semi-Automatic:Assisted devices require manual solution filling and pad attachment, occupying entry-level price bands.
- Programmable:Schedule-driven units appeal to tech-forward residential buyers with predictable cleaning routines.
Automatic holds installed capacity. Hybrid is rotating up the share rankings.
End User:
Application context determines duty-cycle intensity and service contract attach rates.
- Residential:Urban households in China's first-tier cities and Germany's metropolitan corridors generate concentrated demand for automated cleaning solutions. Smart home integration via Matter certification reduces friction for multi-device households with existing IoT infrastructure.
- Commercial:Hotel chains and co-working operators represent untapped volume for fleet-managed units with centralized dock networks and usage telemetry.
- Institutional:Educational and healthcare facilities require compliance with stricter sanitation protocols and higher duty-cycle durability.
- Industrial:Manufacturing floor applications demand sealed motor housings and chemical-resistant chassis for solvent exposure environments.
Residential commands volume leadership. Commercial is climbing the fastest.
Technology:
Sensor cost curves are redistributing competitive advantage across navigation tiers.
- Laser Navigation:Rotating LiDAR modules enable centimeter-precision mapping and multi-floor memory. Production concentrates among Shenzhen and Suzhou component houses, creating supply vulnerability for mid-tier manufacturers lacking dual-source arrangements.
- Visual Navigation:Camera-based SLAM reduces hardware cost while enabling object recognition for obstacle avoidance.
- Gyroscope:Inertial measurement units occupy entry-level price bands through simplified dead-reckoning without environmental mapping.
- Infrared:Proximity-sensor configurations serve basic collision-avoidance functions in budget-assisted devices.
Laser Navigation holds technology premium. Visual Navigation is gaining share fastest.
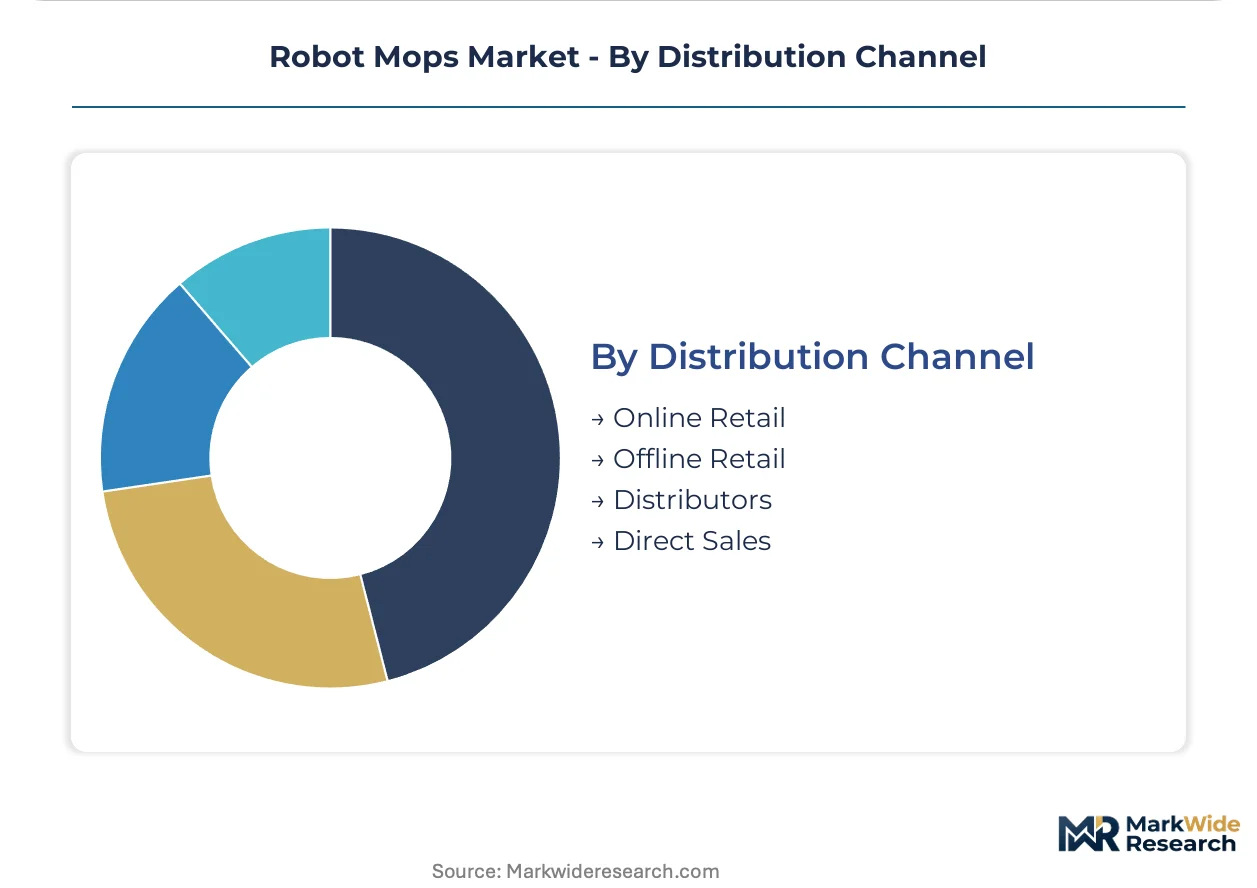
Distribution Channel:
Channel selection determines customer acquisition cost and lifetime value capture mechanics.
- Online Retail:Direct-to-consumer platforms enable subscription models for consumable replenishment tied to usage telemetry. Urban households with reliable broadband infrastructure show highest attach rates for automated pad and solution shipments.
- Offline Retail:Physical touchpoints sustain iRobot's brand recognition in North American channels despite intensifying Asian competition.
- Distributors:Wholesale networks serve commercial and institutional buyers requiring fleet-scale procurement and field service support.
- Direct Sales:Manufacturer-owned channels capture full margin stack in premium tiers with white-glove installation services.
Online Retail holds transaction volume leadership. Direct Sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR enforces GB standards on electromagnetic compatibility and appliance safety, anchoring China's regulatory framework for robotic cleaning devices. This shapes manufacturer R&D priorities across the dominant production geography.
China
Urban households in Shanghai, Beijing, and Shenzhen drive replacement-cycle velocity for hybrid vacuum-mopping units. SAMR's GB standards impose six-figure certification burdens that favor established manufacturers with testing infrastructure. The Yangtze River Delta manufacturing cluster concentrates integrated production of laser navigation modules and self-cleaning dock systems.
Germany
Dual-income households in Berlin, Munich, and Hamburg metropolitan corridors generate concentrated demand for automated cleaning solutions. The EU's Ecodesign Directive and REACH framework constrain battery chemistry and water consumption thresholds for market entry. Bavaria's industrial corridor hosts distribution hubs prioritizing SKUs with certified efficiency ratings.
United States
Urban households with reliable broadband infrastructure show highest attach rates for subscription-based consumable replenishment. The FCC certifies wireless connectivity modules for robot mops entering the market. California's tech-forward residential buyers accelerate adoption of Matter-certified devices for smart home integration.
Japan
Compact living spaces in Tokyo and Osaka metropolitan areas favor space-efficient autonomous cleaning systems. METI oversees appliance safety standards and energy efficiency labeling requirements. The Kanto region's retail channels sustain premium positioning for dock-integrated units with self-maintenance capabilities.
India
Emerging middle-class households in Mumbai and Delhi-NCR show early-stage adoption of entry-level assisted devices. The PLI scheme for electronics manufacturing offers tariff-advantaged assembly points for export-oriented brands. Karnataka's Bengaluru tech corridor attracts firmware engineering talent for SLAM algorithm development.
Robot Mops Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier controls captive manufacturing of navigation sensors and dock subsystems, while specialists concentrate on single-vector innovation in motor miniaturization or cleaning mechanics. Three archetypes populate the landscape: vertically integrated appliance conglomerates, component-specialist spinouts from parent electronics groups, and pure-play robotics startups. Competitive moves center on backward integration into laser module production and strategic partnerships for smart home protocol certification.
Among China-based integrated manufacturers, Ecovacs, Dreame, and Roborock exemplify the vertically consolidated archetype. These entities occupy positions spanning full product stack control from component fabrication to dock ecosystem deployment. iRobot represents the established Western incumbent navigating intensifying Asian competition through brand recognition in North American retail channels. The specialist tier includes Narwal and Eufy, which anchor positions in specific navigation or price-band vectors without full-stack integration.
| Leading Market Players |
|---|
| Roborock |
| Dreame |
| Ecovacs |
| Narwal |
| Mova |
| iRobot |
| Eufy |
| Dyson |
| Lefant |
| Others |
Value Network & Pricing Analysis
China's GB standards for robotic appliances simultaneously gate supply qualification and price differentiation, forcing manufacturers to absorb six-figure certification costs that filter sub-scale entrants into economy tiers while rewarding established players with premium positioning. This regulatory threshold compresses margin pools at the bottom and concentrates pricing power among integrated producers with captive testing infrastructure.
Pricing Analysis
Geographic price spreads widen substantially between China's first-tier cities and Southeast Asian emerging markets, with Shanghai and Beijing households absorbing 40-60% premiums for dock-integrated systems over Bangkok or Jakarta equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by laser navigation capability and self-cleaning dock inclusion, with certification grade under SAMR electromagnetic compatibility testing serving as the primary quality signal. Cost compression in the economy tier intensifies because Shenzhen component houses achieve laser module parity, eroding hardware-based differentiation. Commercial hospitality buyers show least price sensitivity due to fleet-scale procurement and centralized service contracts, while assisted-device households in India's emerging middle class exhibit highest elasticity.
Supply Chain Analysis
Inventory lead times for rotating LiDAR modules stretch disproportionately against gyroscope and infrared alternatives, with Shenzhen and Suzhou component houses operating at 8-12 week backlogs for premium sensor configurations. Manufacturing concentrates in China, Vietnam, and Mexico, with the Yangtze River Delta anchoring integrated production of dock subsystems and precision injection molding for fluid handling. Raw material dependencies center on lithium iron phosphate cells, rare-earth magnets for motor miniaturization, and optical-grade polycarbonate for sensor housings. Single-source vulnerability for mid-tier manufacturers lacking dual-source laser module arrangements constitutes the dominant supply chain risk. Distribution runs through direct-to-consumer platforms for subscription attach, offline retail for brand touchpoints, and wholesale networks for commercial fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter certification convergence constitutes a regulatory inflection that eliminates smart home fragmentation and accelerates mass-market penetration, positioning robot mops for high-growth disruption as integration friction collapses.
For Market Incumbents: Compound defensive positioning through backward integration into laser module production and strategic control over dock ecosystem completeness. iRobot and Ecovacs must anchor North American retail channel relationships against Asian competition while investing in SAMR pre-certification infrastructure to maintain premium tier access. Certification investment serves as the priority lever for margin defense.
For New Entrants and Emerging Players: Differentiate on commercial hospitality fleet management and India's PLI-advantaged assembly points for export-oriented production. India's emerging middle-class households represent the most penetrable geography, with Mumbai and Delhi-NCR showing early-stage assisted-device adoption velocity. A direct-to-consumer launch with localized firmware engineering in Bengaluru offers viable go-to-market positioning.
For Investors and Strategic Acquirers: EU right-to-repair mandates reshape the acquisition landscape toward modular architectures with field-serviceable battery and motor accessibility. Long-term viability across a 5-10 year window favors vertically integrated manufacturers with captive component production and dock subsystem control. Acquisition targets should display integrated sensor manufacturing and fluid handling precision molding capabilities. The signal to watch is SAMR enforcement intensity on electromagnetic compatibility retesting for product refresh cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Navigation Modules | Shenzhen component house acquisitions reduce single-source vulnerability for mid-tier manufacturers. |
| Self-Cleaning Dock Ecosystem Deployment | Consumable subscription models capture recurring revenue from urban households with reliable broadband. |
| Matter Certification Investment | Smart home protocol convergence eliminates IoT fragmentation and expands addressable household base. |
| Commercial Hospitality Fleet Partnerships | Hotel chains and co-working operators represent untapped volume for centralized dock network deployment. |
| India PLI-Scheme Manufacturing Localization | Karnataka and Tamil Nadu assembly points offer tariff-advantaged export positioning for global brands. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with robotics engineering leads, smart home platform managers, commercial procurement officers at hospitality chains, and SAMR certification consultants; alongside secondary validation through customs trade records, FCC equipment authorization databases, EU Ecodesign Directive compliance registries, and SEC filings from publicly traded appliance manufacturers. Bottom-up unit shipment modeling triangulated against top-down household penetration estimates across China's first-tier cities and Germany's metropolitan corridors.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, navigation technology tier, end-use application, and distribution channel, with hybrid vacuum-mopping units and laser navigation systems receiving discrete treatment. CAGRs derived from replacement-cycle velocity analysis, smart home adoption curves, and regulatory compliance cost trajectories. Forecast inputs incorporated lithium iron phosphate battery chemistry shifts, Matter certification penetration rates, and SAMR electromagnetic compatibility enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained dual-income household density growth, stable lithium supply pricing, or continued smart home protocol convergence would require recalibration. Forecasts reflect documented assumptions on replacement cycle timing, certification cost pass-through elasticity, and commercial hospitality adoption velocity. Supply chain disruption from tariff escalation or single-source laser module concentration poses specific revision risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Massage Pillow Market
Household Items
Europe Digital Showers Market
Household Items
Electric Mop Market
Household Items
Disposable Cutlery Market
Household Items
India Non-Stick Cookware Market
Household Items
Global Laptop Tables Market
Household Items
Saudi Arabia Cookware Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Candle Air Fresheners Market
Household Items
Asean Cookware Market
Household Items
Kitchen Towel Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Smart Fridge Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Crash Mat Market
Household Items
North America Car Air Freshener Market