
 Commercial Lawnmower Market | 2026-2036
Commercial Lawnmower Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Lawnmower Market Analytics
Modular attachment systems and à-la-carte service bundling is decoupling equipment sales from long-term maintenance contracts, shifting how landscaping firms evaluate total cost of ownership. Deere & Company leverages its precision agriculture heritage to embed telematics into commercial mower fleets. Husqvarna Group anchors its position through battery ecosystem interoperability across professional-grade tools. Toro Company specializes in zero-turn configurations for golf course superintendents seeking cut-quality consistency.
A commercial lawnmower is a motorized turf-cutting machine engineered for continuous duty cycles, typically featuring fabricated steel decks from 36 to 72 inches, hydrostatic transmissions, and blade tip speeds exceeding 18,000 fpm to deliver uniform clipping dispersion across large-scale maintained landscapes. Zero-turn riding mowers dominate margin pools in the landscaping contractor segment where maneuverability offsets higher upfront cost. Electric fuel type configurations represent the fastest-growing category as lithium-ion pack energy density improves and runtime anxiety diminishes for crews managing sub-ten-acre properties. Walk-behind units retain structural importance in municipalities with steep terrain restrictions where ride-on stability risks exceed productivity gains.
EPA Phase 3 emission standards for small spark-ignition engines compel gasoline model redesigns, while the EU Green Deal and F-Gas Regulation accelerate electric platform investment for equipment exported to Europe. OSHA noise exposure limits influence commercial buyer specifications, particularly for early-morning municipal contracts in noise-sensitive districts. Stakeholders must weigh battery infrastructure deployment against residual value uncertainty in internal combustion fleets as regulatory thresholds tighten across multiple jurisdictions.
Market Dynamics
EPA Phase 3 emission standards are forcing gasoline-powered commercial mower redesigns while lithium-ion energy density improvements enable electric platforms to capture municipal and suburban landscaping contracts previously locked to internal combustion.
Growth Catalysts
- California municipal green procurement mandates:Cities including Los Angeles and San Francisco now require zero-emission turf equipment for public contracts, redirecting fleet procurement toward battery-electric configurations.
- Lithium-ion pack energy density improvements:Cell chemistry advances extend runtime to 6-8 hours, eliminating range anxiety for crews managing sub-ten-acre commercial properties without midday charging.
- Germany's EU Green Deal implementation:National building codes and landscape maintenance contracts increasingly specify F-Gas-compliant, low-noise equipment for urban green spaces.
Market Restraints
- Steel and aluminum input cost volatility:Fabricated deck manufacturing faces margin compression from commodity price swings, constraining pricing flexibility for mid-tier equipment.
- Battery cell supply concentration:Cathode material processing and cell assembly cluster in China, creating geopolitical exposure for OEMs building electric platforms.
- Residual value uncertainty in gasoline fleets:Tightening emission thresholds across multiple jurisdictions depress trade-in valuations for internal combustion assets.
Strategic Opportunities
- Japan's aging groundskeeping workforce:Labor scarcity drives demand for autonomous and semi-autonomous mowing systems in golf course and estate maintenance.
- Telematics-embedded service bundling:Usage-based maintenance contracts and predictive parts replacement create recurring revenue streams decoupled from equipment sales cycles.
- OSHA noise exposure compliance:Early-morning municipal contracts in noise-sensitive districts specify sub-75 dB equipment, favoring electric configurations with premium pricing power.
Industry Challenges
- High-voltage technician certification gaps:Landscaping contractors face recruitment friction for crews qualified to service 48V and 72V battery systems.
- Interoperability standardization delays:Proprietary battery ecosystems across OEMs prevent cross-brand pack swapping, complicating fleet standardization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Lawnmower Market |
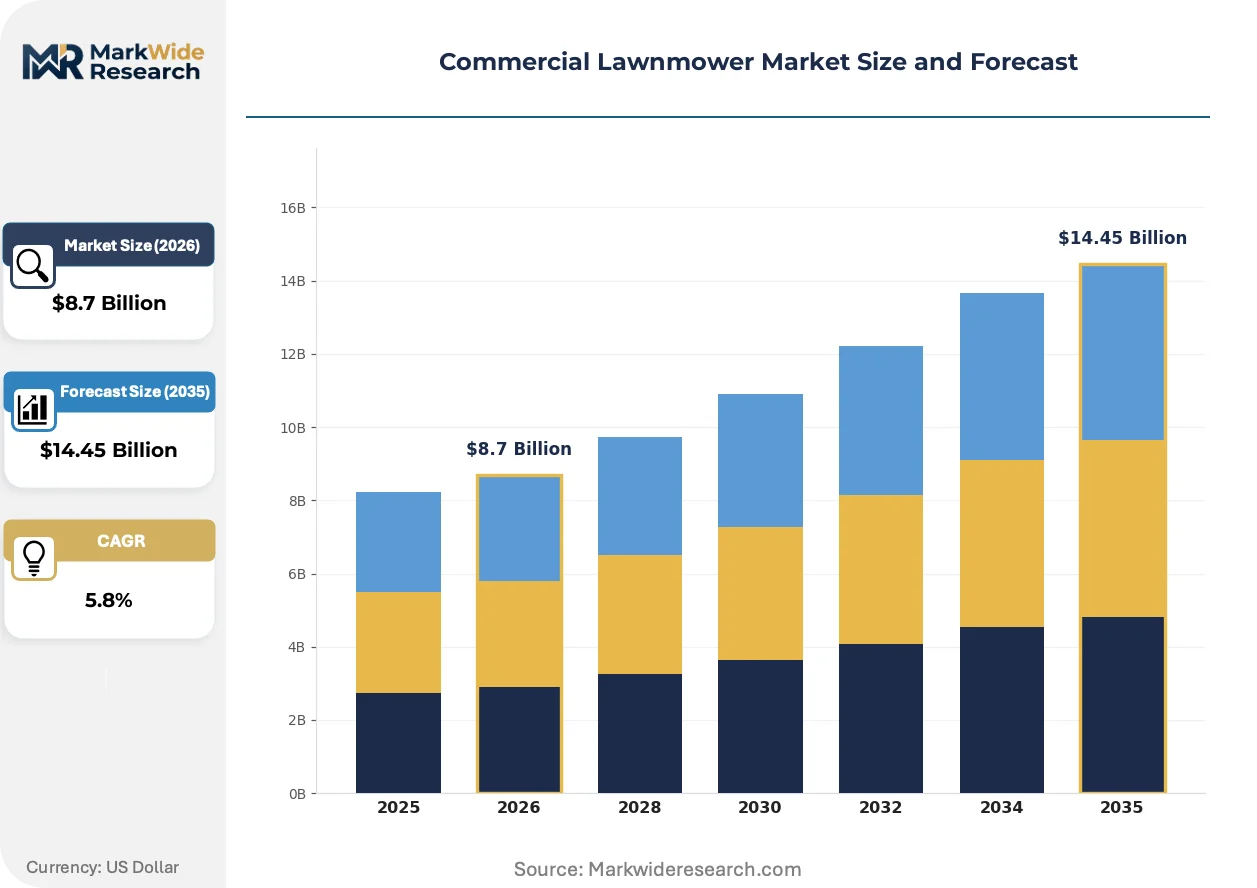
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Riding, Walk-Behind, Zero-Turn End User: Landscaping Companies, Golf Courses, Municipalities, Parks Departments Fuel Type: Gasoline, Diesel, Electric, Hybrid Deck Size: 36 Inch, 48 Inch, 60 Inch, 72 Inch |
| Companies Covered | Deere & Company, Husqvarna Group, Toro Company, Honda Motor Company, Kubota Corporation, MTD Products, Robert Bosch, STIGA Group, STIHL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Lawnmower Market Evolving Landscape
Commercial mower engineering is absorbing telematics, battery chemistry, and autonomous navigation advances that simultaneously compress operating costs and expand addressable contract types for landscaping service providers.
Brushless DC motor architectures paired with silicon carbide inverters are absorbing thermal management constraints that previously limited electric mower duty cycles. Golf course superintendents and municipal parks departments are adopting these configurations for 12-hour continuous operation. The technology is absorbing price premiums that internal combustion alternatives commanded in high-reliability segments.
REACH and F-Gas Regulation compliance deadlines are accelerating electric platform investment for equipment exported to Europe. OEMs must redesign refrigerant systems and battery thermal management to meet substance restrictions. Professional landscaping contractors in Germany and the Netherlands face compressed equipment replacement timelines as grandfathering provisions expire.
Service unbundling is fragmenting traditional equipment-plus-maintenance contracts into à-la-carte component sourcing. Large landscaping firms now procure mowers, blades, and telematics subscriptions from separate vendors. This pattern concentrates in California and Texas where private equity-backed rollups standardize procurement across acquired regional operators.
Commercial Lawnmower Market Segmentation
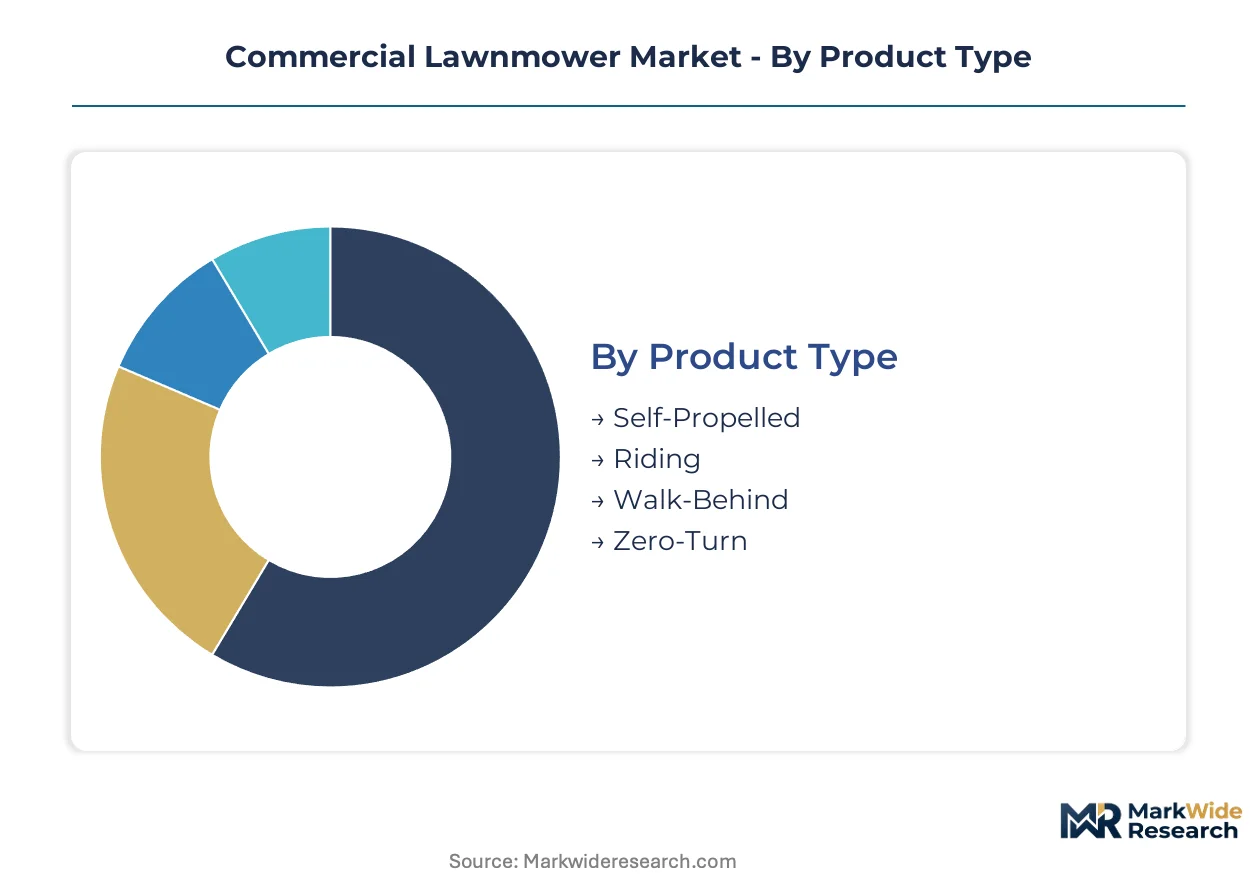
Commercial lawnmower purchasing decisions fragment across equipment configuration, operational scale, and regulatory exposure. Each segmentation dimension carries distinct margin structures and replacement cadences that reshape how OEMs allocate R&D and distribution resources.
Product Type:
Landscaping contractors prioritize maneuverability and operator fatigue reduction when selecting equipment platforms for sustained daily operation.
- Zero-Turn:Dual hydrostatic transmissions enable 360-degree pivoting without uncut circles, commanding premium pricing from golf course superintendents and large commercial contractors. Demand concentrates in Texas and Florida where expansive turf maintenance contracts reward productivity gains over upfront capital constraints.
- Riding:Front-engine configurations with fabricated steel decks dominate municipal fleet procurement for parks maintenance, balancing cut quality with operator comfort across 8-hour shifts. California municipalities specify these units with Tier 4-compliant engines to satisfy CARB procurement mandates.
- Self-Propelled:Rear-wheel or all-wheel drive systems suit sloped terrain where ride-on stability risks exceed productivity trade-offs.
- Walk-Behind:Compact footprints navigate gate-restricted residential complexes and cemeteries with steep grade limitations.
Zero-Turn leads on scale; Electric-compatible Walk-Behind configurations lead on momentum as battery density improves.
End User:
Contractor consolidation and municipal green procurement rules are diverging specification requirements across customer categories.
- Landscaping Companies:Private equity-backed rollups in California and Texas standardize fleet procurement across acquired regional operators, favoring telematics-embedded units with predictive maintenance contracts. Total cost of ownership calculations now dominate over sticker price in equipment selection.
- Municipalities:Los Angeles and San Francisco zero-emission mandates redirect public contract specifications toward battery-electric platforms with sub-75 dB noise profiles for early-morning residential district maintenance.
- Golf Courses:Japan's aging groundskeeping workforce drives autonomous and semi-autonomous system trials for fairway and rough maintenance.
- Parks Departments:Budget cyclicality and grant-dependent replacement schedules create lumpy demand concentrated in Q2 procurement windows.
Landscaping Companies anchor volume concentration; Municipalities are expanding most quickly as green procurement rules harden.
Fuel Type:
Regulatory threshold tightening across multiple jurisdictions is compressing residual value certainty for internal combustion assets.
- Electric:Lithium-ion pack energy density improvements extend runtime to 6-8 hours, eliminating range anxiety for crews managing sub-ten-acre commercial properties. Germany's EU Green Deal implementation accelerates platform investment for equipment exported to Europe.
- Gasoline:EPA Phase 3 emission standards compel small spark-ignition engine redesigns, raising manufacturing complexity for traditional fleet configurations.
- Diesel:Torque density advantages retain relevance for large-area municipal contracts with minimal noise restrictions.
- Hybrid:Parallel architectures bridge runtime gaps in transitional markets with incomplete charging infrastructure.
Gasoline retains installed base dominance; Electric gains share fastest as OSHA noise compliance and CARB mandates converge.
Deck Size:
Productivity-per-hour metrics and transport trailer constraints determine optimal cutting width selection for contract types.
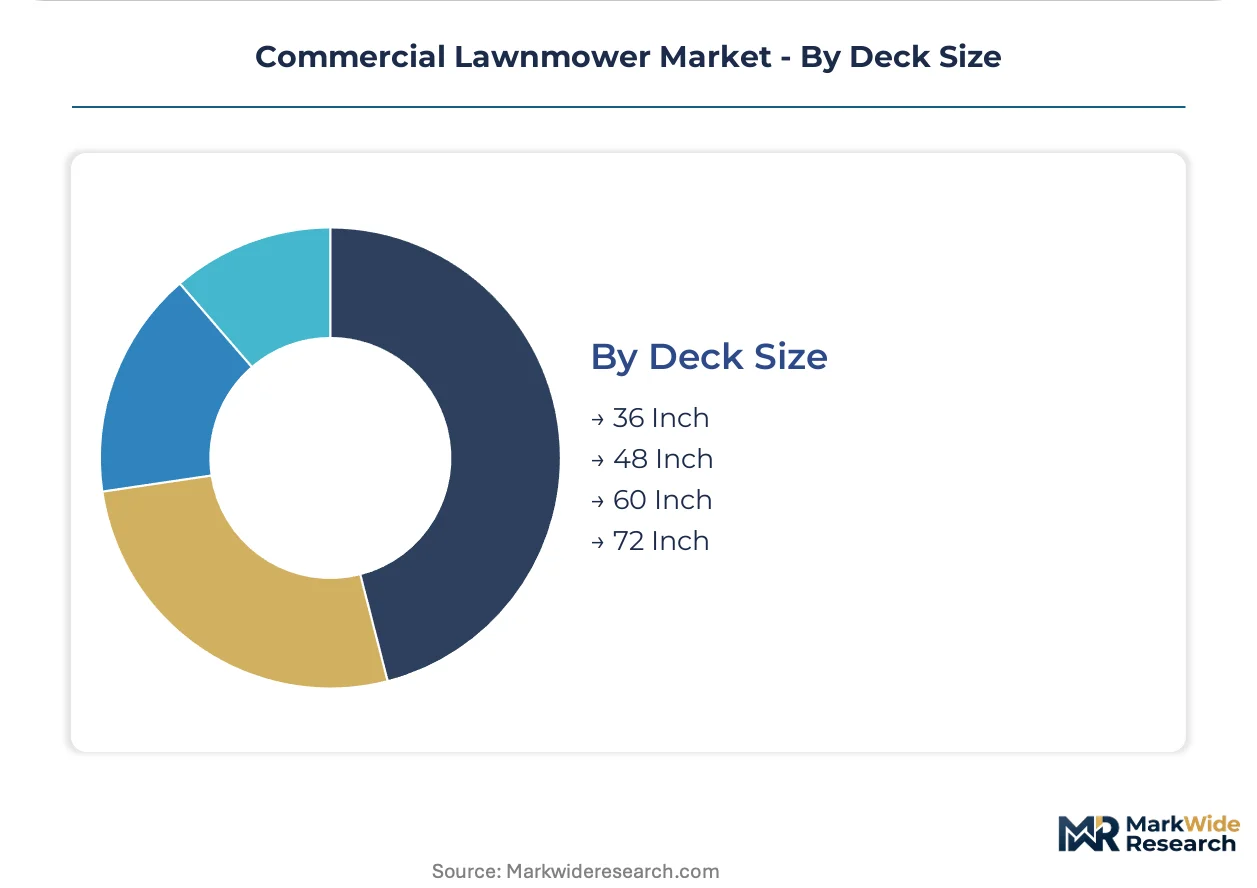
- 60 Inch:Fabricated steel decks at this width optimize the productivity-to-transportability ratio for regional landscaping contractors serving commercial office parks and retail centers.
- 72 Inch:Maximum width configurations serve golf course fairways and airport grounds where open acreage minimizes turning frequency.
- 48 Inch:Mid-range versatility suits mixed residential-commercial portfolios with varying turf geometries.
- 36 Inch:Compact decks navigate fenced athletic fields and cemetery sections with tight gate clearances.
60 Inch leads on scale; 72 Inch leads on momentum as golf course and airport contract values rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial lawnmower industry traces its industrial roots to midwestern United States manufacturing centers where agricultural equipment fabrication scaled into turf maintenance machinery during the post-war suburban expansion.
United States
Landscaping contractor consolidation and municipal fleet renewal programs drive equipment procurement across Texas and Florida metro areas. EPA Phase 3 emission standards for small spark-ignition engines compel gasoline model redesigns while CARB mandates in California redirect public contracts toward battery-electric platforms. Los Angeles and San Francisco zero-emission procurement rules concentrate electric mower trials in municipal parks departments.
Germany
Professional groundskeeping contractors and golf course operators anchor demand for precision cutting equipment in Bavaria and North Rhine-Westphalia. EU Green Deal implementation and F-Gas Regulation compliance deadlines accelerate electric platform investment for equipment serving urban green spaces. Stuttgart and Munich industrial clusters host precision manufacturing operations supplying deck fabrication and hydrostatic transmission components.
Japan
Aging groundskeeping workforce demographics and labor scarcity propel autonomous and semi-autonomous mowing system development for golf course and estate maintenance. METI industrial policy supports battery ecosystem standardization for professional-grade outdoor power equipment. Osaka and Nagoya manufacturing corridors concentrate component supply for electric drivetrain integration.
China
Export-oriented fabrication capacity and domestic landscaping service expansion create dual demand channels for commercial-grade turf equipment. MEE environmental standards and dual carbon goals pressure manufacturing efficiency improvements in gasoline-powered production lines. Zhejiang and Jiangsu province industrial zones supply fabricated steel decks and lithium-ion pack assembly for OEMs serving European and North American markets.
United Kingdom
Local authority parks maintenance budgets and private groundskeeping services sustain demand for mid-duty ride-on configurations. REACH chemical compliance and emerging low-emission procurement guidance influence fleet replacement timelines. West Midlands manufacturing heritage supports specialized component fabrication for European export markets.
Commercial Lawnmower Market Competitive Landscape
Premium-margin players sit above commodity-margin players across telematics integration and battery ecosystem interoperability dimensions. The vendor base organizes into three tiers: diversified agricultural equipment conglomerates with precision technology heritage, specialized outdoor power tool manufacturers with cross-platform battery strategies, and regional fabrication specialists serving price-sensitive fleet operators. Consolidation pressure concentrates among mid-tier players lacking proprietary battery ecosystems or predictive maintenance software capabilities. Strategic moves center on telematics-embedded service bundling and backward integration into lithium-ion pack assembly.
Within the diversified equipment tier, Deere & Company and Kubota Corporation represent archetypes of agricultural technology heritage applied to commercial turf maintenance. Husqvarna Group and STIHL occupy positions in the specialized outdoor power segment where battery ecosystem interoperability anchors competitive differentiation. Honda Motor Company exemplifies engine manufacturing expertise adapting to emission threshold compression across multiple jurisdictions.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| Toro Company |
| Honda Motor Company |
| Kubota Corporation |
| MTD Products |
| Robert Bosch |
| STIGA Group |
| STIHL |
| Others |
Value Network & Pricing Analysis
California municipal zero-emission procurement mandates are redirecting fleet specifications toward battery-electric platforms, forcing OEMs to absorb lithium-ion cell premiums and recalibrate pricing models across gasoline and electric configurations. Steel and aluminum commodity volatility further compresses margin flexibility for fabricated deck manufacturers serving mid-tier landscaping contractors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with differentiation driven by telematics integration depth and battery ecosystem interoperability. Premium tiers command position through predictive maintenance bundling and CARB-compliant electric platforms, while economy tiers face price erosion from commodity input cost compression. Landscaping companies backed by private equity consolidation show lowest price sensitivity, prioritizing total cost of ownership calculations over sticker price.
Supply Chain Analysis
Domestic-content requirements in EU public procurement rules are reshaping sourcing patterns for equipment exported to Germany and the Netherlands. Cathode material processing and cell assembly concentrate in China, South Korea, and Japan, creating geopolitical exposure for OEMs building electric platforms. Fabricated steel decks and hydrostatic transmission components draw from Zhejiang and Jiangsu province industrial zones. Single-source vulnerability in lithium-ion pack supply creates tariff exposure risk. Distribution runs through authorized dealer networks and direct municipal fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial lawnmower market represents a late-cycle quality story as landscaping contractors and municipalities shift procurement criteria toward precision telematics and zero-emission compliance specifications.
For Market Incumbents: Deepen backward integration into lithium-ion pack assembly to secure cell supply and capture margin pools currently flowing to third-party battery suppliers. Expand telematics-embedded service bundling to create recurring revenue streams that decouple from equipment sales cyclicality. Battery ecosystem interoperability gaps present competitive vulnerability against specialized outdoor power manufacturers. For New Entrants and Emerging Players: Enter via autonomous mowing system development for Japan's golf course and estate maintenance segment, where aging workforce demographics create structural demand for labor-substituting equipment. California municipal green procurement mandates offer the most penetrable white-space for battery-electric platform specialists lacking legacy gasoline engine infrastructure. Position through predictive maintenance software partnerships rather than capital-intensive manufacturing scale. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier OEMs possessing fabricated deck manufacturing expertise but lacking proprietary battery ecosystems, as consolidation pressure intensifies. Long-term viability over the projection horizon favors targets with installed telematics infrastructure and municipal contract relationships. Watch EPA Phase 3 implementation timelines and CARB mandate expansion as inflection indicators for gasoline fleet residual value compression.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Ecosystem Interoperability Investment | Cross-platform pack swapping reduces fleet standardization friction for landscaping contractors across California and Germany. |
| Telematics-Enabled Predictive Maintenance | Usage-based parts replacement contracts create recurring revenue independent of equipment replacement cycles. |
| Autonomous Navigation Platform Development | Japan's METI-supported labor scarcity solutions open premium pricing for golf course and estate applications. |
| Backward Integration into Cell Assembly | Captive lithium-ion supply mitigates China concentration risk and secures margin pools for electric platform OEMs. |
| Municipal Fleet Electrification Partnerships | Los Angeles and San Francisco zero-emission mandates redirect long-term contract specifications toward compliant suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with landscaping fleet managers, municipal procurement officers, golf course superintendents, and aftermarket service heads with secondary validation from EPA regulatory filings, CARB procurement databases, EU Green Deal implementation documents, and customs trade records. Bottom-up equipment shipment analysis and top-down market sizing triangulated volume and value estimates.
Comparable historical periods anchored the forecast framework across the projection horizon, with segmentation modeled by product type, fuel type, end user category, and deck size. CAGRs derived from equipment replacement cadence analysis and regulatory threshold implementation timelines. Forecast inputs incorporated lithium-ion energy density improvement curves and municipal green procurement mandate expansion patterns.
Inputs from OEM production disclosures and municipal contract award databases were available through the study window; gaps in autonomous system trial data and private landscaping contractor fleet composition introduce uncertainty bands around electric platform penetration assumptions. Forecasts reflect documented assumptions about regulatory implementation pacing and commodity cost stabilization. EPA Phase 3 compliance cost pass-through and CARB mandate geographic expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
India Cookware Market
Household Items
Barbeque Grill Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Lunch Box Market
Household Items
Residential Air Purifiers Market
Household Items
Shower Heads and Systems Market
Household Items
Neck Pillows Market
Household Items
Electric Shoe Dryer Market
Household Items
United States Barbeque Grill Market
Household Items
Infuser Water Bottles Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Bottle Openers Market
Household Items
Titanium Thermos Cup Market
Household Items
Saudi Arabia Cookware Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
LAMEA Robotic Pool Cleaner Market