
 T-Shirt Printing Machine Market | 2026-2036
T-Shirt Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
T-Shirt Printing Machine Market Analytics
Online businesses is rotating toward higher-specification digital systems as custom apparel demand shifts from brick-and-retail shops to e-commerce fulfillment models. Kornit Digital leverages single-pass inkjet architectures for same-day production cycles. Brother sustains strong channel control across entry-level direct-to-garment units for small custom shops. Epson anchors premium pigment-ink systems that target apparel manufacturers seeking color-fastness compliance.
A T-Shirt Printing Machine is an electromechanical device that deposits pigment, dye, or sublimation ink onto cotton, polyester, or blended fabric substrates using controlled printhead positioning, with typical resolutions ranging from 300 to 2400 dpi and throughput speeds of 30 to 200 garments per hour depending on technology class. Its primary commercial purpose is to enable short-run or mass-customized graphic application for wearable textiles without traditional screen-setup costs. Direct-to-garment systems lead installed value due to their elimination of stencil preparation, while heat transfer occupies the mid-market as a versatile bridge technology for mixed-fiber orders. Sublimation segments are gaining fastest in polyester-activewear niches where disperse dyes bond permanently with synthetic fibers.
The US Environmental Protection Agency regulates volatile organic compound emissions from textile screen-printing operations, pushing buyers toward water-based inkjet alternatives. The European Chemicals Agency enforces REACH compliance on textile inks, restricting certain azo dyes and phthalate plasticizers that historically dominated screen-printing formulations. China's Ministry of Ecology and Environment enforces GB standards on industrial wastewater discharge from garment printing clusters. Stakeholders must monitor how regional chemical compliance timelines reshape equipment replacement cycles and ink formulation roadmaps.
Market Dynamics
Digital inkjet deposition is compressing production cycles from days to hours, eliminating screen-setup overhead and enabling same-day fulfillment for e-commerce apparel decorators.
Growth Catalysts
- E-commerce on-demand fulfillment:Online apparel platforms require single-unit production capability that analog screen-printing cannot deliver, accelerating direct-to-garment system procurement.
- REACH chemical restrictions:The European Chemicals Agency's azo dye and phthalate limitations force screen-printing houses toward water-based inkjet alternatives, expanding addressable equipment markets.
- Polyester activewear expansion:Disperse dye sublimation systems capture demand from athletic apparel manufacturers seeking permanent synthetic-fiber bonding without hand-feel degradation.
Market Restraints
- Pigment ink cost volatility:Specialized textile ink formulations carry 3-5x cost premiums over standard graphics inks, compressing margins for entry-level equipment buyers.
- Printhead supply concentration:Precision piezoelectric deposition modules concentrate among Japanese and German component suppliers, creating single-source vulnerability for equipment assemblers.
- Substrate compatibility limits:Direct-to-garment systems require cotton or cotton-dominant blends; 100% polyester and dark-synthetic applications remain technically constrained without pre-treatment infrastructure.
Strategic Opportunities
- India small-batch manufacturing:Export-oriented garment clusters in Tiruppur and Surat lack digital decoration capacity, creating first-mover advantage for compact direct-to-garment system deployment.
- UV-curable hybrid convergence:Combination UV-LED and textile ink platforms enable mixed-media printing on non-apparel substrates, expanding equipment utilization rates for commercial decorators.
- US EPA VOC enforcement:Accelerated inspection timelines for volatile organic compound emissions create replacement demand cycles among screen-printing operations in California and Texas.
Industry Challenges
- Color-management expertise scarcity:ICC profile calibration for textile substrates requires specialized knowledge that traditional screen-printing operators lack, extending commissioning timelines.
- Pre-treatment workflow integration:Automated garment loading and chemistry application systems must synchronize with printhead firing sequences, complicating retrofit installations in existing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T-Shirt Printing Machine Market |
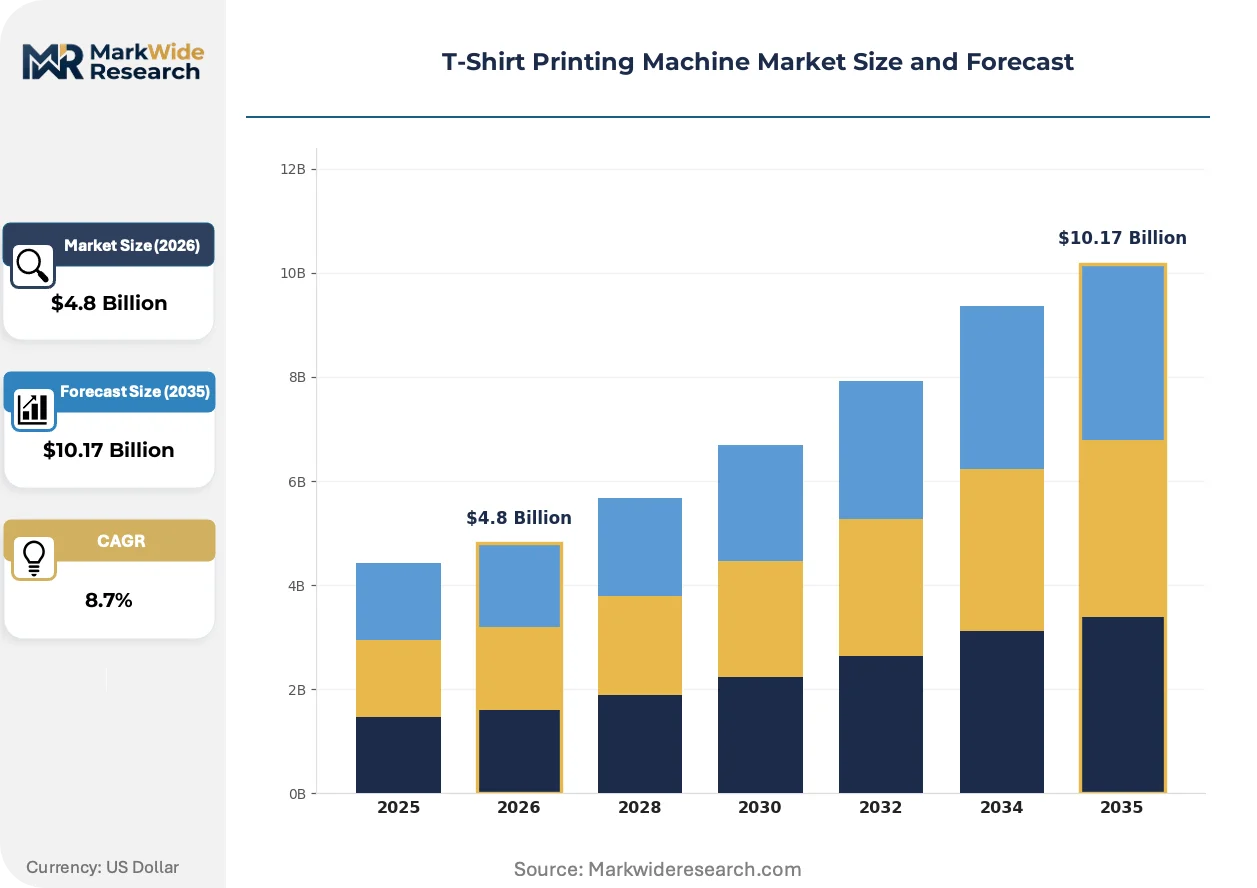
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-to-Garment, Screen Printing, Heat Transfer, Sublimation Technology: Inkjet, Laser, Digital, Hybrid End User: Retail Shops, Custom Shops, Online Businesses, Apparel Manufacturers Size: Small, Medium, Large, Extra Large |
| Companies Covered | Brother, Epson, Roland, Mimaki, Kornit Digital, The M&R Companies, TexJet, Ricoh Company, SPGPrints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T-Shirt Printing Machine Market Evolving Landscape
Equipment architectures are converging toward modular, software-defined production cells that decouple mechanical throughput from design complexity constraints.
Single-pass inkjet arrays are miniaturizing from industrial widths to compact flatbed configurations suitable for retail backroom deployment. Boutique custom shops in urban commercial districts adopt these systems to offer 30-minute turnaround on personalized merchandise. The footprint reduction is miniaturizing real estate requirements for viable on-site production, enabling placement inside shopping malls and event venues previously inaccessible to garment decoration equipment.
China's Ministry of Ecology and Environment enforces GB 4287 wastewater discharge standards on textile printing clusters in Guangdong and Zhejiang provinces. Industrial parks must install centralized effluent treatment or face production halts, accelerating capital deployment toward closed-loop ink recirculation systems. Equipment suppliers are integrating filtration modules as standard configurations for machines destined for Chinese manufacturing zones.
Brand licensors now mandate digital decoration for licensed character merchandise to eliminate minimum order quantities and reduce counterfeit vulnerability. Sports apparel and entertainment merchandise suppliers in North America and Western Europe retrofit facilities to comply with IP holder requirements. This specification cascade propagates from Disney, Warner Bros., and major athletic leagues downward through their authorized decorator networks, reshaping vendor qualification criteria.
T-Shirt Printing Machine Market Segmentation
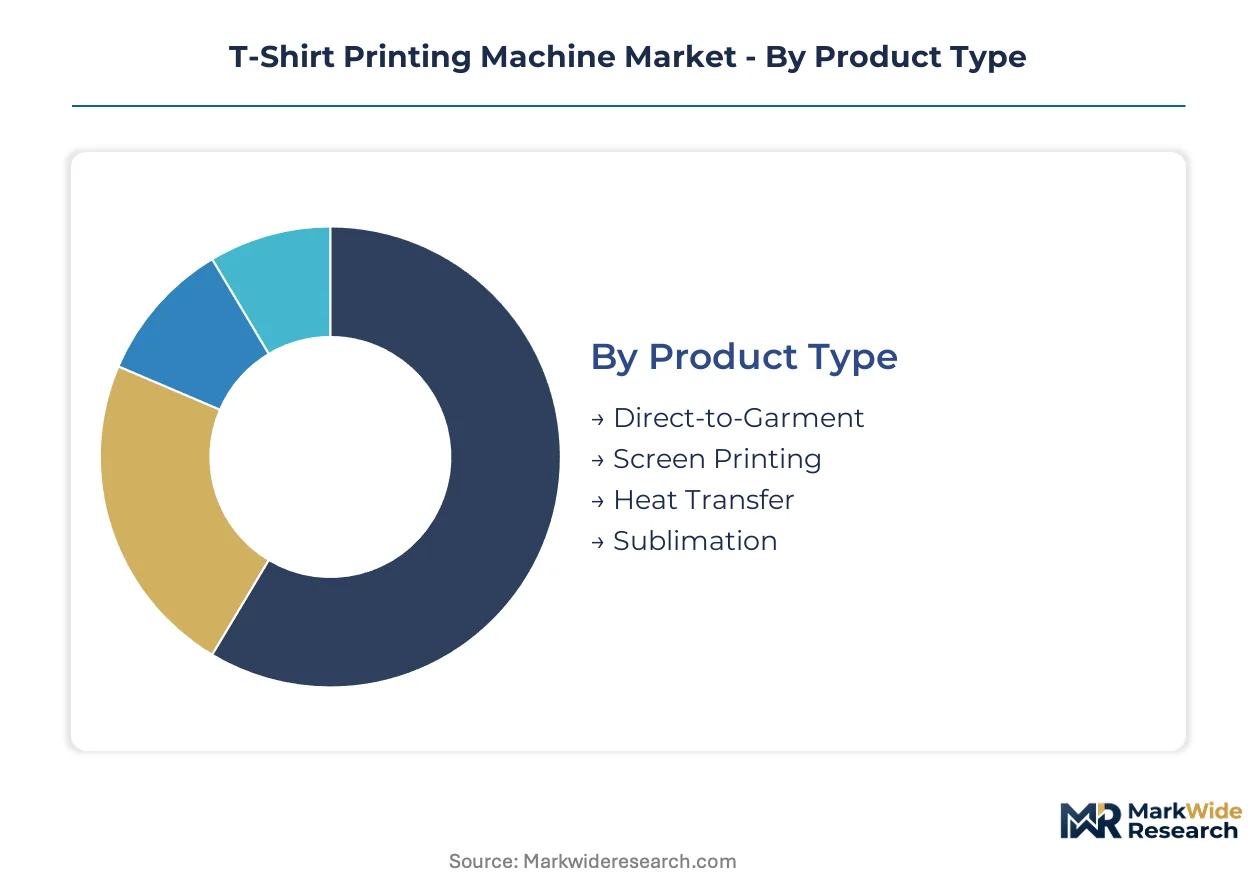
Segmentation in T-shirt printing equipment reveals how technology choices lock buyers into distinct margin structures and upgrade cycles. Equipment specifications determine substrate compatibility, throughput economics, and regulatory compliance pathways across decorator business models.
Product Type:
Margin pools concentrate in systems that eliminate consumable waste and reduce labor touchpoints per garment.
- Direct-to-Garment:Water-based pigment inkjet systems deposit CMYK+White inks directly onto cotton substrates without stencil preparation. Demand clusters with e-commerce fulfillment centers in the United States seeking same-day production cycles. The EPA's VOC enforcement on screen-printing operations accelerates replacement procurement toward these water-based alternatives.
- Sublimation:Disperse dye systems bond permanently with polyester fibers through heat-press transfer at 380-400°F. Athletic apparel manufacturers in Germany and China deploy these for activewear lines where synthetic-fiber permanence resists wash degradation. REACH chemical restrictions on azo dyes in Europe push decorators toward dye-sublimation for compliance.
- Screen Printing:Analog stencil-based systems dominate high-volume cotton decoration with thick ink deposits and vibrant opacity. Large contract decorators in India retain installed bases for bulk orders despite longer setup times.
- Heat Transfer:Intermediate technology using printed vinyl or paper intermediates applied via heat press. Small custom shops favor versatility across mixed-fiber orders without dedicated pretreatment infrastructure.
The dominant share belongs to Direct-to-Garment, while Sublimation is closing the gap fastest.
Technology:
Technology selection determines capital intensity and per-unit economics across production scales.
- Digital:Software-controlled deposition enables variable-data printing with no physical setup between designs. Online businesses in China adopt these for on-demand fulfillment with lot sizes of one unit.
- Inkjet:Piezoelectric printhead arrays dominate direct-to-garment and sublimation segments with resolutions from 600 to 2400 dpi. Entry-level custom shops in the United States source compact flatbed configurations for retail backroom deployment.
- Hybrid:Combination platforms merge digital front-ends with screen-printing stations for specialty inks and high-opacity whites. Commercial decorators seeking equipment utilization across diverse order types drive adoption.
- Laser:Thermal transfer and ablation systems for synthetic leather and technical textiles. Niche applications in industrial labeling and promotional products sustain limited demand.
Inkjet commands the installed base, though Hybrid configurations are gaining traction among mid-scale decorators seeking operational flexibility.
End User:
Customer type dictates batch size requirements and service-level expectations that equipment specifications must satisfy.
- Online Businesses:E-commerce platforms require single-unit production with automated file handling and direct integration with order management systems. These buyers prioritize throughput consistency over maximum speed.
- Apparel Manufacturers:Vertical garment producers integrate decoration into cut-and-sew operations for finished-goods control. Large-scale deployment in Bangladesh and Vietnam supports export-oriented production.
- Custom Shops:Independent decorators serving local markets with walk-in orders and event merchandise. Equipment footprints under 4 square meters enable mall and venue placement.
- Retail Shops:Brand-owned stores offering personalization as customer experience enhancement. Limited production volumes favor reliable entry-level systems over industrial throughput.
Online Businesses now represent the steepest expansion trajectory, while Apparel Manufacturers retain the largest aggregate equipment value.
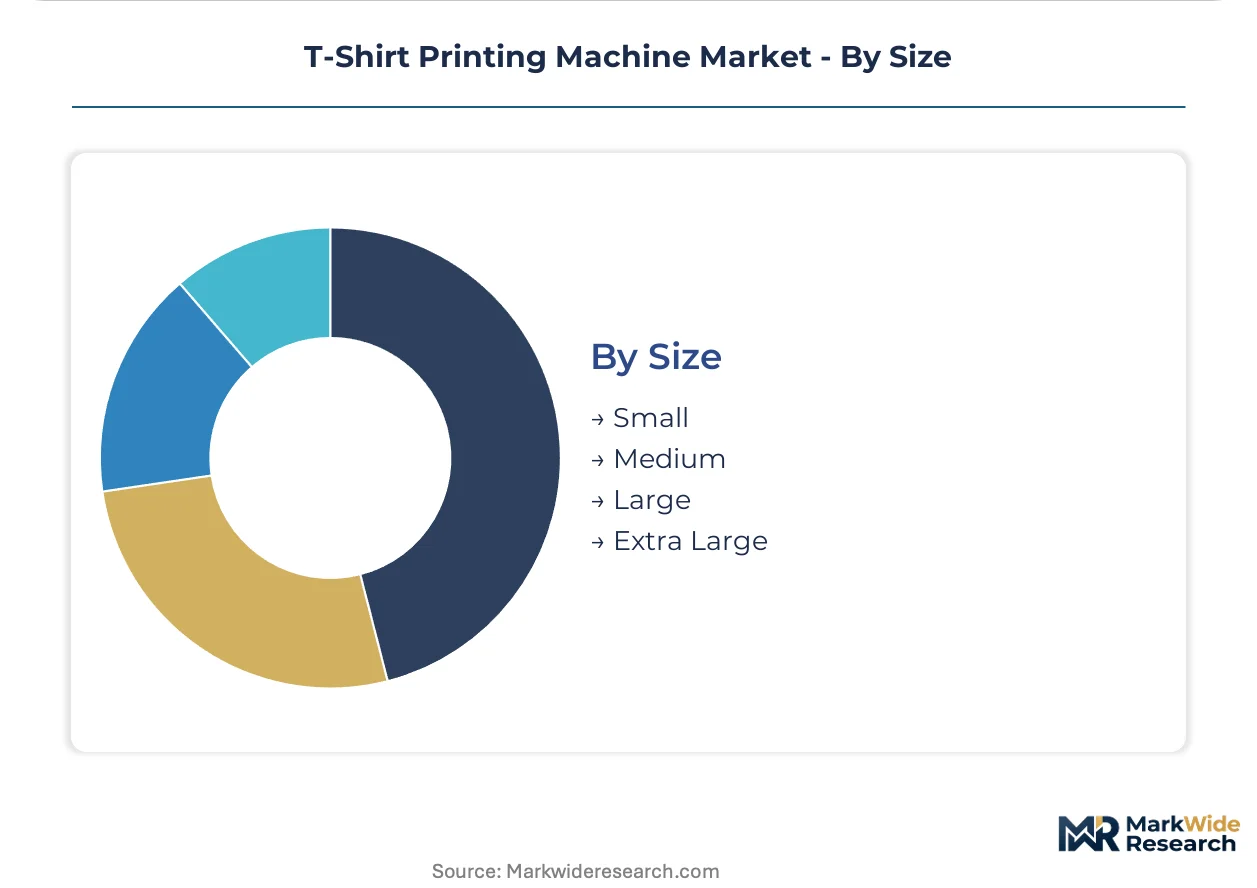
Size:
Physical machine dimensions correlate with real estate constraints and maximum printable area per cycle.
- Small:Desktop and benchtop units with 12x16 inch platen dimensions. Home-based entrepreneurs and mobile event decorators constitute primary demand.
- Medium:Freestanding systems with 16x20 to 20x24 inch platens balancing throughput and floor space. Independent custom shops in Germany standardize on this configuration.
- Large:Industrial frames with 24x36 inch or dual-platen configurations for simultaneous multi-garment printing. Contract decorators in Tiruppur, India deploy these for export order fulfillment.
- Extra Large:Conveyorized or roll-to-roll systems for all-over printing and cut-piece decoration prior to sewing. Specialty athletic and fashion producers in Los Angeles and Milan operate limited installations.
Medium systems hold the broadest installed base, though Small formats are proliferating fastest among micro-enterprises and mobile retail concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment exports supply garment decoration clusters across Southeast Asia and South Asia, while German and US manufacturers dominate premium digital system sales into European and North American fulfillment networks.
United States
E-commerce fulfillment centers in California and Texas drive procurement of compact direct-to-garment systems for same-day production cycles. The EPA enforces volatile organic compound emission limits on screen-printing operations, accelerating replacement demand toward water-based inkjet alternatives. Los Angeles hosts specialty athletic producers operating limited extra-large conveyorized installations for all-over printing applications.
China
Vertical garment producers in the Yangtze River Delta integrate decoration into cut-and-sew operations for finished-goods export control. The Ministry of Ecology and Environment enforces GB 4287 wastewater discharge standards on textile printing clusters in Guangdong and Zhejiang provinces. Industrial parks in these provinces must install centralized effluent treatment or face production halts, accelerating capital deployment toward closed-loop ink recirculation systems.
Germany
Athletic apparel manufacturers deploy disperse dye sublimation systems for activewear lines where synthetic-fiber permanence resists wash degradation. The European Chemicals Agency enforces REACH compliance restricting azo dyes and phthalate plasticizers, pushing decorators toward dye-sublimation for chemical compliance. Independent custom shops standardize on medium-format freestanding systems balancing throughput and floor space constraints.
India
Export-oriented garment clusters in Tiruppur and Surat lack digital decoration capacity, creating first-mover opportunity for compact direct-to-garment system deployment. The Bureau of Indian Standards oversees equipment safety certifications for imported printing machinery. Large contract decorators in Tiruppur deploy large-format industrial frames with dual-platen configurations for simultaneous multi-garment printing on export orders.
Japan
Precision piezoelectric printhead modules concentrate among Japanese component suppliers, creating single-source vulnerability for equipment assemblers sourcing deposition technology. The Ministry of Economy, Trade and Industry supports advanced manufacturing technology development through targeted industrial policy. Domestic equipment fabricators occupy specialized positions in high-resolution inkjet subsystem supply to global printer manufacturers.
T-Shirt Printing Machine Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and geographic reach dimensions. The vendor base spans publicly traded digital printing specialists and privately held analog equipment fabricators with entrenched channel relationships. Three archetypes dominate: single-pass inkjet innovators, entry-level desktop system suppliers, and hybrid platform integrators. Consolidation activity concentrates on digital asset acquisitions by legacy screen-printing equipment manufacturers, while capacity expansion focuses on compact system production for retail backroom deployment.
Within the listed-entity tier, Kornit Digital and Ricoh Company exemplify scale-driven positions anchored in industrial deposition technology. Epson occupies a premium-system archetype representing pigment-ink specialization for color-fastness compliance. Among private specialists, The M&R Companies and SPGPrints sit within established analog-to-digital transition pathways, reflecting heritage screen-printing expertise evolving toward hybrid configurations.
| Leading Market Players |
|---|
| Brother |
| Epson |
| Roland |
| Mimaki |
| Kornit Digital |
| The M&R Companies |
| TexJet |
| Ricoh Company |
| SPGPrints |
| Others |
Value Network & Pricing Analysis
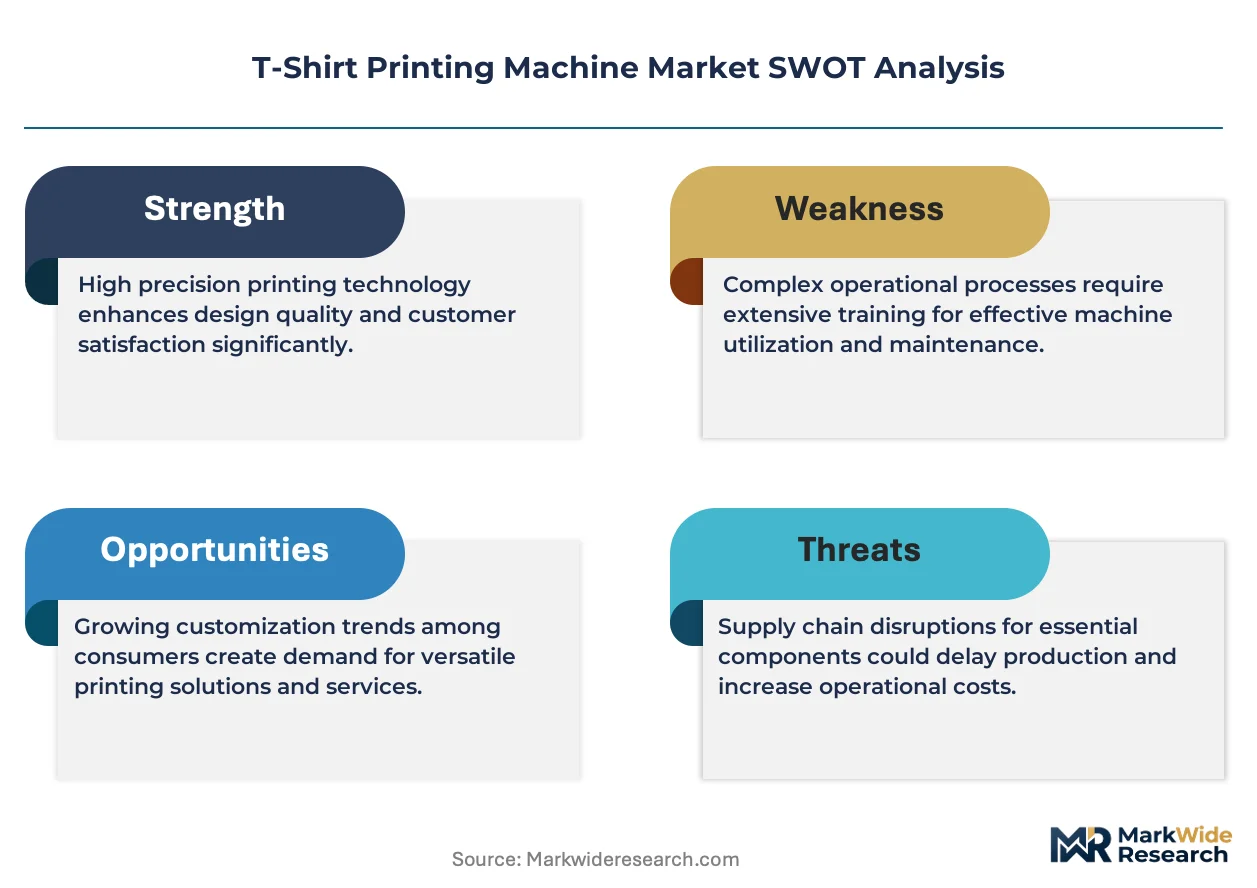
Fourteen-day printhead procurement lead times concentrate pricing power with Japanese and German component suppliers, compressing margins for equipment assemblers while elevating costs for buyers locked into single-source deposition modules. This supply structure rewards vertical ink formulation control and penalizes assemblers without backward integration into consumable chemistry.
Pricing Analysis
Next-generation single-pass inkjet systems command 40-60% premiums over prior-generation flatbed configurations, while entry-level desktop units face sustained cost compression from Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels differentiates by throughput capability, with CE marking and EPA compliance certifications adding 15-25% uplifts. Pricing pressure stems from pigment ink cost volatility, with specialized textile formulations carrying 3-5x premiums over standard graphics inks. Online businesses exhibit highest price sensitivity due to thin e-commerce margins, while apparel manufacturers prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Japan and Germany anchor precision piezoelectric printhead fabrication, while China dominates compact system assembly and textile ink formulation. Equipment production draws from specialized nozzle plate substrates, ceramic actuator materials, and water-based pigment chemistry. Single-source vulnerability concentrates in deposition module supply, with Japanese suppliers controlling 70%+ of industrial-grade piezoelectric arrays. Distribution runs through authorized dealer networks for entry-level systems and direct OEM sales for industrial configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as e-commerce order management systems demand direct API integration with production equipment, transforming standalone machines into software-defined production nodes. Interoperability with Shopify, WooCommerce, and proprietary fulfillment platforms has become the primary vendor selection criterion.
For Market Incumbents: Consolidate control over ink formulation supply chains through captive chemistry operations or exclusive supplier agreements, neutralizing margin erosion from volatile pigment costs. Acquire compact system specialists in China to defend against indigenous manufacturers capturing Southeast Asian export markets. Prioritize software platform certification investments that embed equipment into e-commerce fulfillment workflows.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission enables rapid European market entry ahead of REACH enforcement deadlines. Target India's Tiruppur and Surat garment clusters with compact direct-to-garment systems priced below incumbent offerings. Pursue channel partnerships with regional textile trade associations to bypass established dealer networks.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because equipment margins compress while ink and maintenance contracts generate sustained cash flows. Target acquisition candidates with vertical integration into water-based pigment chemistry and established e-commerce platform integrations. Monitor EPA VOC enforcement inspection timelines in California and Texas as replacement demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Chemistry | Captures margin pools from volatile pigment supply and locks in consumable recurring revenue. |
| E-Commerce Platform Certification | Enables direct API integration with Shopify and WooCommerce order management systems. |
| Compact System Production Scale-Up | Addresses underpenetrated India garment clusters and mobile retail deployment opportunities. |
| Closed-Loop Filtration Module Integration | Ensures GB 4287 wastewater compliance for Chinese manufacturing zone equipment sales. |
| Hybrid Platform Development | Combines digital front-ends with screen-printing stations for operational flexibility across order types. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, equipment manufacturer SEC filings, and textile industry association reports. Primary interviews engaged equipment procurement managers at e-commerce fulfillment centers, plant engineers at garment manufacturing clusters, aftermarket service heads at regional dealer networks, and regulatory compliance officers at ink formulation facilities. Secondary validation drew from EPA enforcement databases, ECHA REACH restriction updates, and China's MEE discharge standard notifications. Bottom-up equipment shipment analysis triangulates against top-down market size estimates derived from consumable chemistry volume flows.
Segmentation dimensions modeled include product type, technology class, end-user archetype, and physical machine size across the projection horizon. Direct-to-garment, sublimation, screen printing, and heat transfer categories anchor product segmentation. Digital, inkjet, hybrid, and laser technologies define technology stratification. Online businesses, apparel manufacturers, custom shops, and retail shops constitute end-user segmentation. CAGR derivation incorporates equipment replacement cycles, regulatory compliance timelines, and e-commerce penetration trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EPA VOC enforcement, stable REACH chemical restriction timelines, and continued e-commerce platform expansion; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Technical Textile Production Equipment Market
Textile Machinery and Equipment
Mexico Screen Printing Mesh Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Plasma Surface Treatment Machine for Leather Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Compact Spinning Machine Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Global Spinning Machinery Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Electric Fabric Shaver Market