
 UAE Geospatial Analytics Market | 2026-2036
UAE Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Geospatial Analytics Market Insights
Modular platform bundling is rebalancing procurement patterns across UAE government and enterprise accounts. Esri leverages its ArcGIS ecosystem to anchor federal mapping contracts, while Bayanat sustains sovereign capability through its space-derived imagery and analytics stack. Hexagon AB competes on sensor-to-software integration for precision infrastructure surveys.
Geospatial analytics encompasses the computational processing of location-referenced data through geographic information systems, remote sensing platforms, and spatial statistics to extract actionable intelligence for physical environment management. Cloud-Based Solutions now dominate new deployments as MOHAP and municipal clients prioritize scalable infrastructure without capital-intensive server commitments. Remote Sensing commands premium pricing where satellite constellations deliver sub-meter resolution for oil field and maritime border surveillance. Government Agencies represent the deepest procurement pool, though Construction Firms represent the fastest-growing user segment as BIM-to-GIS interoperability becomes standard on megaproject tenders.
MOHAP oversees health facility mapping standards, while the UAE Space Agency regulates satellite imagery distribution and national security clearances for foreign platform operators. The Telecommunications and Digital Government Regulatory Authority shapes cloud residency requirements that constrain where geospatial data may physically reside. Stakeholders must weigh sovereign data localization mandates against the interoperability costs of fragmented national cloud architectures.
Market Dynamics
Cloud migration mandates from the Telecommunications and Digital Government Regulatory Authority are compressing procurement cycles across UAE federal agencies, forcing legacy on-premise GIS installations into accelerated retirement timelines.
Growth Catalysts
- Smart city infrastructure mandates:Dubai's municipal agencies are embedding geospatial platforms into traffic management and utility networks, creating recurring subscription demand for real-time analytics layers.
- MOHAP health facility mapping standards:The national health regulator requires standardized geocoding for all medical infrastructure, compelling emirate-level health departments to upgrade spatial data management systems.
- Sovereign satellite capacity expansion:The UAE Space Agency's domestic imagery constellations are reducing foreign dependency for sub-meter resolution data, accelerating clearance timelines for sensitive border and energy asset monitoring.
Market Restraints
- Specialized sensor hardware costs:LiDAR and synthetic aperture radar units for precision infrastructure surveys carry price premiums that exclude smaller emirate municipalities from competitive tendering.
- Cloud residency fragmentation:The Telecommunications and Digital Government Regulatory Authority's data localization rules prevent seamless multi-cloud architectures, forcing vendors to maintain redundant sovereign-hosted instances.
- High-resolution radar substitution:Autonomous drone swarms with onboard edge processing are displacing satellite subscriptions for localized construction site monitoring in Abu Dhabi's megaproject corridors.
Strategic Opportunities
- Ras Al Khaimah coastal zone management:This underpenetrated emirate lacks dedicated marine spatial planning infrastructure, creating first-mover advantage for integrated bathymetric and shoreline erosion analytics.
- BIM-to-GIS interoperability mandates:Abu Dhabi Department of Municipalities and Transport is requiring unified digital twins on all infrastructure tenders above specified thresholds, opening workflow integration contracts.
- AI-augmented change detection:Machine learning inference on satellite imagery streams is electrifying automated infrastructure monitoring, reducing manual analyst hours for road network condition assessments.
Industry Challenges
- Geospatial data scientist scarcity:The domestic talent pool lacks sufficient practitioners combining remote sensing expertise with Python-based spatial statistics, forcing vendors to recruit from European and South Asian markets.
- Legacy CAD-GIS integration friction:Engineering consultancies in Sharjah and Ajman maintain decades of AutoCAD archives that resist automated conversion to geodatabase schemas, delaying cloud migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Geospatial Analytics Market |
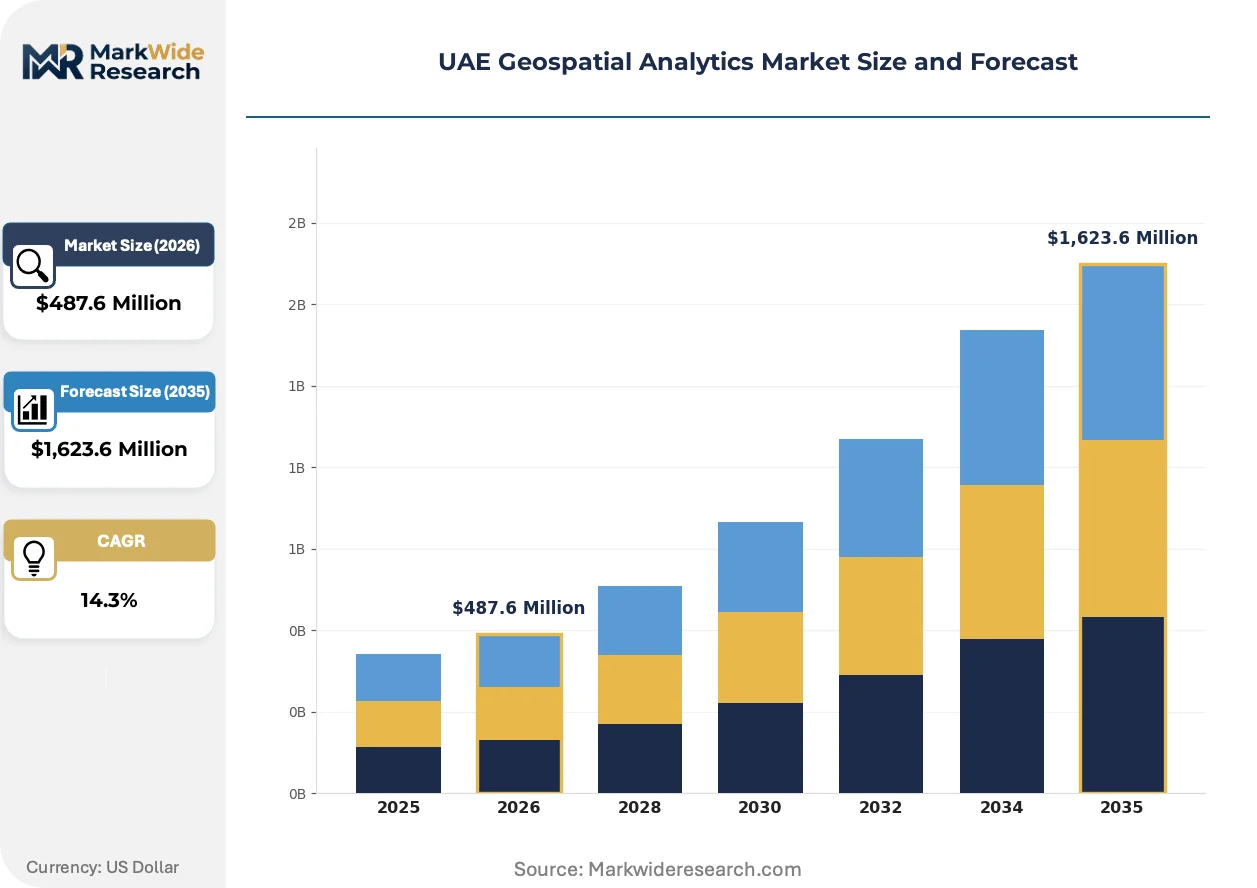
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,623.6 Million |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Disaster Management, Transportation Analysis Technology: GIS Software, Remote Sensing, GPS, Cloud-Based Solutions End User: Government Agencies, Construction Firms, Logistics Companies, Environmental Organizations Deployment: On-Premises, Cloud, Hybrid, Mobile |
| Companies Covered | Esri, Hexagon AB, Trimble Inc., HERE Technologies, Google LLC, Oracle Corporation, Bayanat, Space Imaging Middle East, Khatib & Alami, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Geospatial Analytics Market Trends and Innovations
Digital twin convergence with real-time IoT sensor feeds is compressing the latency between physical infrastructure changes and analytical insight generation across UAE municipal operations.
AI-augmented satellite imagery classification is electrifying automated feature extraction for urban sprawl monitoring. Dubai Municipality's planning department has deployed convolutional neural networks on monthly Pleiades captures, reducing manual digitization labor for building footprint updates. The technology is compressing traditional six-month mapping cycles into continuous monitoring streams that flag unpermitted construction within 72 hours.
The Telecommunications and Digital Government Regulatory Authority's cloud residency certifications are reshaping vendor qualification requirements. Foreign platform operators must now demonstrate physical server presence within UAE sovereign territory to bid on federal contracts, raising compliance costs for providers without regional data center partnerships. Abu Dhabi's energy sector buyers are prioritizing certified vendors for upstream asset monitoring tenders, accelerating localization investments by incumbent analytics firms.
Subscription-based platform access is displacing perpetual license purchases among mid-sized engineering consultancies. Firms in Dubai's Design District and Abu Dhabi's Reem Island are trading capital-intensive ArcGIS Enterprise deployments for metered cloud credits that scale with project pipelines. This consumption pattern is most visible in the construction vertical, where tender volatility makes fixed software commitments financially untenable for specialized survey contractors.
UAE Geospatial Analytics Market Segmentation
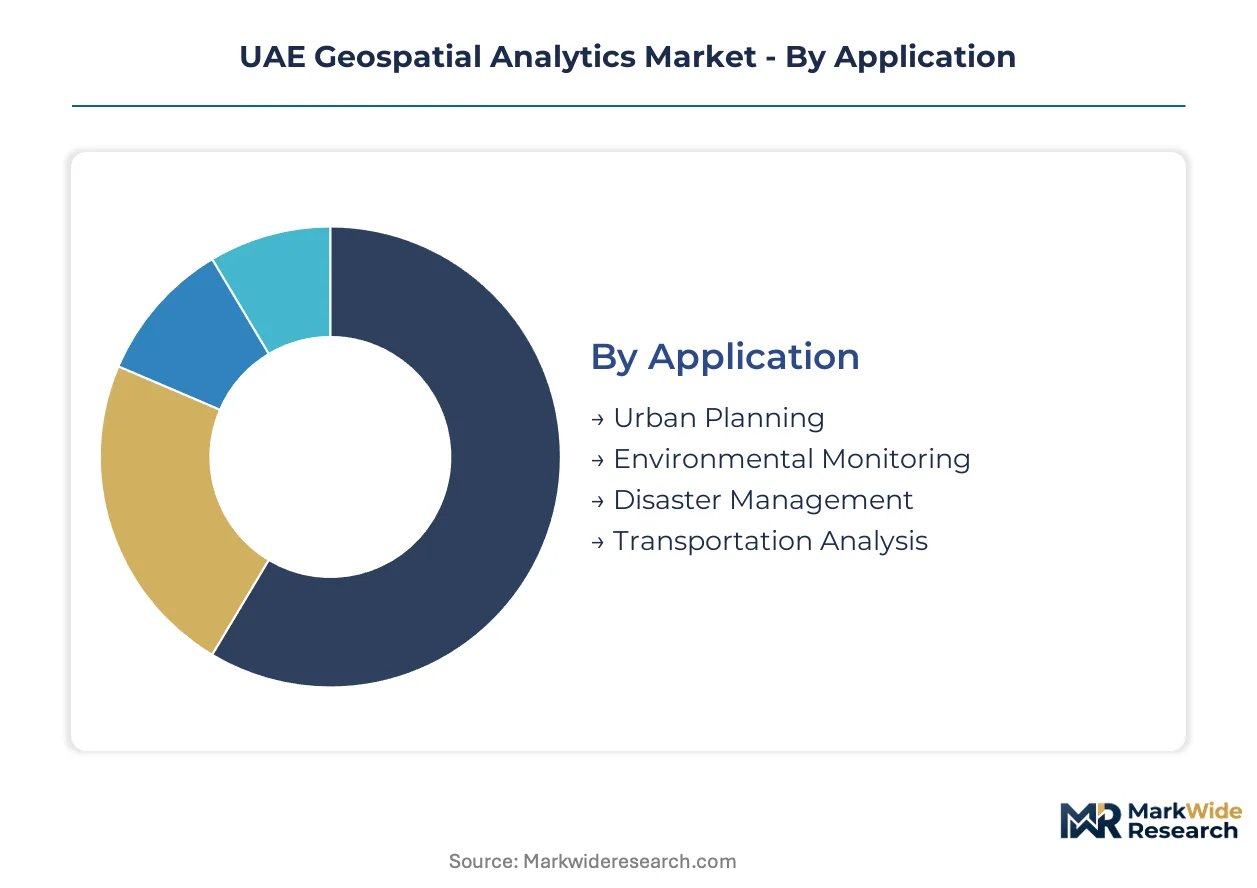
Segmentation in the UAE geospatial analytics market reveals distinct procurement patterns across federal agencies and private operators. Each dimension carries specific compliance burdens and capability requirements that shape vendor selection criteria.
Application:
Capital intensity varies sharply across use cases, with sensor deployment costs and data processing infrastructure driving divergent investment profiles.
- Urban Planning:Municipal agencies deploy 3D city modeling and zoning analytics for Dubai's master planning exercises. Dubai Municipality consumes the majority of subscription capacity for real-time building footprint monitoring and development permit verification.
- Environmental Monitoring:Coastal erosion tracking and desertification mapping require satellite constellation access and specialized bathymetric sensors. Abu Dhabi's Environment Agency commands premium analytics services for marine spatial planning around offshore energy infrastructure.
- Disaster Management:Federal Emergency and Crisis Management Authority coordinates flood and sandstorm response protocols.
- Transportation Analysis:RTA Dubai leverages traffic flow optimization and route planning for metro expansion corridors.
Most installed capacity flows through Urban Planning. Expansion is steepest in Environmental Monitoring.
Technology:
Technology selection determines interoperability costs and data sovereignty compliance pathways for federal contractors.
- GIS Software:ArcGIS Enterprise deployments anchor federal mapping standards with embedded MOHAP health facility geocoding modules. Esri's platform dominates emirate-level procurement where legacy schema migration creates switching costs.
- Remote Sensing:Sub-meter resolution satellite imagery from UAE Space Agency constellants serves border surveillance and upstream oil asset monitoring. Sovereign clearance protocols accelerate deployment timelines for sensitive energy infrastructure.
- GPS:Precision positioning infrastructure supports construction surveying and autonomous vehicle corridors.
- Cloud-Based Solutions:TDRA-certified sovereign hosting satisfies data residency mandates for healthcare and defense clients.
Procurement volume concentrates in GIS Software. Remote Sensing claims the steepest expansion trajectory as domestic satellite capacity matures.
End User:
End-user sophistication determines pricing tier access and support service levels across vendor portfolios.
- Government Agencies:Federal and emirate-level departments mandate TDRA cloud certification and MOHAP data standards in tender specifications. Multi-year enterprise agreements predominate where budget cycles support capital planning.
- Construction Firms:BIM-to-GIS interoperability requirements from Abu Dhabi Department of Municipalities and Transport drive workflow integration spending. Megaproject contractors prioritize digital twin capabilities for tender compliance.
- Logistics Companies:Fleet routing optimization and warehouse site selection consume location intelligence services.
- Environmental Organizations:Non-governmental conservation groups access subsidized imagery for protected area monitoring.
Contract value concentrates with Government Agencies. Construction Firms are gaining share fastest as infrastructure tender mandates proliferate.
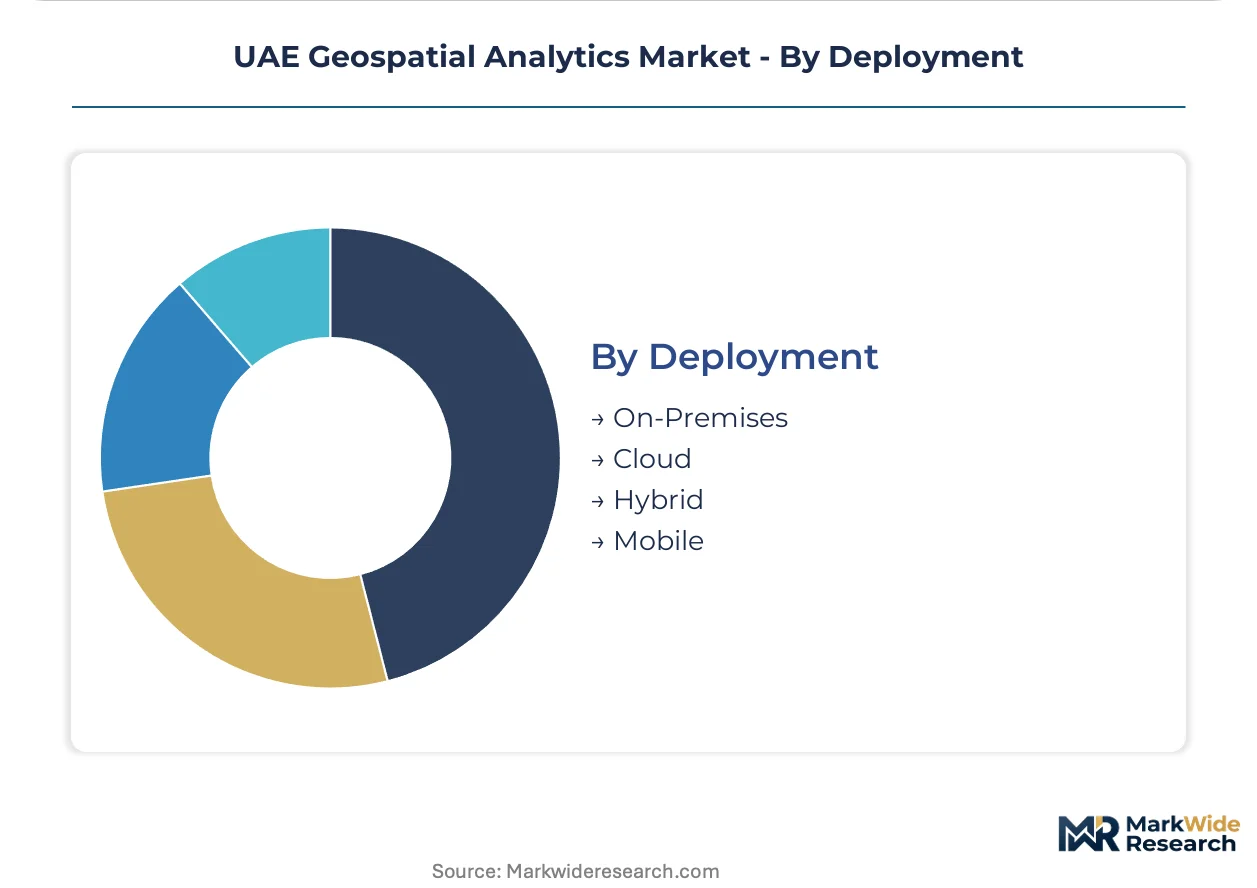
Deployment:
Deployment architecture selection reflects data sensitivity classifications and legacy system integration burdens.
- Cloud:TDRA-certified sovereign instances enable federal health and defense contracts without cross-border data transfer. Metered consumption models reduce capital commitment for mid-sized engineering consultancies in Dubai Design District.
- On-Premises:Classified border surveillance and energy asset monitoring require air-gapped installations with dedicated security clearances. National security protocols prevent cloud migration for specific Space Agency imagery streams.
- Hybrid:Split architectures balance sensitive processing on-premises with scalable analytics in certified cloud environments.
- Mobile:Field survey teams and emergency response units deploy tablet-based data collection with offline synchronization.
New procurement favors Cloud deployment. Hybrid architectures are climbing fastest as security-conscious agencies seek architectural flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geospatial analytics capabilities first scaled through Dubai's municipal modernization programs in the early 2000s, establishing the emirate as the regional center for spatial data infrastructure deployment before federal standardization spread capabilities nationwide.
Dubai
Dubai Municipality consumes the majority of urban planning analytics capacity for real-time building footprint monitoring and development permit verification. The Roads and Transport Authority mandates geospatial platforms for traffic flow optimization across metro expansion corridors. Dubai Design District hosts mid-sized engineering consultancies trading perpetual licenses for metered cloud credits.
Abu Dhabi
The Department of Municipalities and Transport requires unified digital twins on infrastructure tenders above specified thresholds, opening workflow integration contracts for BIM-to-GIS interoperability. The Environment Agency commands premium analytics for marine spatial planning around offshore energy infrastructure. Reem Island construction firms prioritize consumption-based platform access over capital-intensive deployments.
Sharjah
Engineering consultancies maintain decades of AutoCAD archives that resist automated conversion to geodatabase schemas, delaying cloud migration timelines. The emirate's municipal agencies lag Dubai in real-time analytics adoption but represent expansion opportunity for legacy system modernization vendors. Sharjah's logistics corridor consumes fleet routing optimization services.
Northern Emirates
Ras Al Khaimah lacks dedicated marine spatial planning infrastructure, creating first-mover advantage for integrated bathymetric and shoreline erosion analytics. Ajman's smaller municipalities face exclusion from competitive tendering due to specialized sensor hardware costs for precision surveys. The region's coastal zone management requirements outpace current analytics deployment capacity.
UAE Geospatial Analytics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across data sovereignty certification and specialized sensor integration capabilities. Federal mapping standards and TDRA cloud residency requirements create tiered qualification barriers that concentrate contract value among certified vendors. Three archetypes dominate: sovereign satellite operators with domestic imagery constellations, platform-integrated sensor-to-software providers, and cloud-native subscription services. Competitive moves center on localization partnerships for data center presence and workflow integration alliances with construction software vendors.
Within the sovereign capability tier, Bayanat and Space Imaging Middle East anchor domestic imagery and analytics stacks that satisfy UAE Space Agency clearance protocols for sensitive border and energy asset monitoring. Esri represents the platform-integrated archetype through federal mapping contract anchoring, while Hexagon AB occupies a position on precision infrastructure survey integration. Khatib & Alami exemplify regional engineering consultancy players building internal geospatial competencies for tender compliance.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Trimble Inc. |
| HERE Technologies |
| Google LLC |
| Oracle Corporation |
| Bayanat |
| Space Imaging Middle East |
| Khatib & Alami |
| Others |
Pricing and Supply Chain Analysis
Sub-meter resolution satellite imagery pricing on international commodity exchanges cascades through UAE vendor tiers, compressing margins for foreign constellation operators while amplifying pricing power for domestic Bayanat and Space Imaging Middle East stacks cleared under sovereign protocols.
Pricing Analysis
Subscription-based SaaS tiers with consumption-scaled credits dominate federal and municipal procurement, separating TDRA-certified sovereign cloud instances from standard international hosting. Price differentiation hinges on data residency certification grade and sensor-to-software integration depth. Cost compression in mid-tier engineering consultancy segments intensifies as Dubai Design District firms trade perpetual ArcGIS licenses for metered cloud access. Government agencies exhibit lowest price sensitivity given security clearance requirements, while Sharjah and Ajman municipalities face exclusion from precision survey tenders due to specialized LiDAR hardware premiums.
Supply Chain Analysis
Refurbished sensor hardware and remanufactured satellite component flows from European and South Asian secondary markets feed UAE system integrators seeking cost advantages on precision survey equipment. Manufacturing concentration centers on Germany, the United States, and China for LiDAR units, synthetic aperture radar systems, and edge-computing drone platforms. Raw material dependencies include rare earth elements for sensor magnetics, gallium arsenide for RF components, and high-purity optical glass for lens assemblies. Single-source vulnerability persists for sub-meter resolution satellite payloads cleared under UAE Space Agency protocols. Distribution runs through certified system integrators with federal security clearances rather than open channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE geospatial analytics market functions as a geographic-arbitrage play where TDRA cloud residency mandates impose compliance costs on foreign vendors that domestic sovereign satellite operators bypass entirely.
For Market Incumbents: Deepen vertical integration into domestic satellite constellation operations to secure imagery pipeline control against autonomous drone swarm substitution threatening localized construction monitoring contracts. Anchor federal mapping standards through ArcGIS ecosystem lock-in while accelerating TDRA certification for redundant sovereign-hosted instances. Esri and Hexagon AB must prioritize UAE data center partnerships before foreign platform exclusion hardens. For New Entrants and Emerging Players: Capture Ras Al Khaimah coastal zone management white space where dedicated marine spatial planning infrastructure remains undeveloped. Target BIM-to-GIS interoperability workflow contracts in Abu Dhabi's megaproject corridors where Department of Municipalities and Transport mandates create tender compliance urgency. Lead with AI-augmented change detection capabilities that compress infrastructure monitoring cycles from months to hours. For Investors and Strategic Acquirers: Asymmetric upside sits with sovereign satellite operators possessing UAE Space Agency clearance protocols and domestic imagery constellation assets. Long-term viability favors vertically integrated platforms controlling sensor hardware through analytics software stacks rather than pure-play SaaS vendors exposed to cloud residency fragmentation. Monitor TDRA certification expansion timelines as inflection signal for foreign vendor market access contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Satellite Constellation Expansion | UAE Space Agency domestic capacity reduces foreign dependency for sensitive border and energy asset monitoring. |
| TDRA Cloud Certification Investment | Physical server presence within UAE territory qualifies vendors for federal health and defense contracts. |
| BIM-to-GIS Workflow Integration | Abu Dhabi Department of Municipalities and Transport mandates unify digital twins on infrastructure tenders. |
| AI-Augmented Imagery Classification | Convolutional neural networks on Pleiades captures compress six-month mapping cycles into 72-hour unpermitted construction detection. |
| Geospatial Data Scientist Recruitment | Domestic talent scarcity in Python-based spatial statistics forces competitive sourcing from European and South Asian markets. |
Research Methodology
Direct dialogue with UAE Space Agency regulatory officers, MOHAP health facility mapping leads, Dubai Municipality urban planning directors, Abu Dhabi Department of Municipalities and Transport procurement managers, and TDRA cloud certification specialists grounded qualitative findings. Secondary validation drew from UAE federal budget disclosures, satellite imagery distribution licenses, municipal tender specifications, and hyperscaler UAE data center capex announcements. Bottom-up project pipeline aggregation triangulated against top-down federal spending envelope analysis.
Segment-level value outputs across the projection horizon reflect modeled deployment architecture splits, application intensity coefficients, and end-user sophistication tiers including government agencies, construction firms, logistics operators, and environmental organizations. CAGRs derived from emirate-level procurement cycle analysis, sovereign satellite capacity buildout schedules, and smart city infrastructure mandate implementation trajectories. Cloud migration velocity and AI-augmented analytics adoption curves served as primary forecast inputs.
Underlying measurement precision varies by segment; government agency contract values carry tighter precision than fragmented engineering consultancy subscription estimates. Forecasts embed assumptions regarding TDRA certification timeline adherence and domestic satellite constellation launch schedules. Practitioners should monitor autonomous drone swarm cost curves and BIM-to-GIS interoperability standard finalization for early demand substitution signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Big Data Analytics in Semiconductor and Electronics Market
Analytics
Saudi Arabia Geospatial Analytics Market
Analytics
Document Analytics Market
Analytics
Japan Geospatial Analytics Market
Analytics
Global High Performance Data Analytics (HPDA) Market
Analytics
App Analytics Market
Analytics
Data Analytics in Telecom Market
Analytics
Europe Mobile Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Global People and HR Analytics Software Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Global Big Data Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Global System Monitoring Market