
 Exchange Traded Fund Market | 2026-2036
Exchange Traded Fund Market Size, Share, and Industry Trends Forecast 2026-2036
Exchange Traded Fund Market Analysis
Retail investor fragmentation across digital platforms is rebalancing how ETF products reach end users. BlackRock leverages its iShares platform to sustain scale advantages across equity and fixed income wrappers. Vanguard competes on cost structure, while JPMorgan Chase differentiates through actively managed strategies and thematic fund construction.
An exchange traded fund is a pooled investment vehicle that trades on exchanges like individual stocks, with creation and redemption occurring through authorized participants using in-kind baskets of underlying securities to maintain tight net asset value tracking. Its primary commercial purpose is to deliver diversified, liquid, low-cost exposure to targeted asset classes or strategies for both retail and institutional portfolios. Equity index strategies anchor the largest asset class segment by cumulative flows, while actively managed and thematic structures represent the fastest-growing margin pools as fee compression squeezes traditional passive products. Fixed income ETFs occupy a maturing but expanding niche as trading liquidity improves in corporate and municipal bond markets.
The SEC regulates ETF product registration, disclosure standards, and trading mechanics under the Investment Company Act of 1940, while FINRA governs broker-dealer sales practices and suitability requirements that shape distribution channel access. The CFTC intersects where commodity and currency ETFs hold derivatives positions, creating layered compliance obligations for multi-asset products. Stakeholders must monitor how regulatory clarity on spot cryptocurrency products and ESG disclosure mandates reshape permissible fund structures and distribution economics.
Market Dynamics
The SEC's ETF Rule modernization is compressing product launch timelines from months to weeks, forcing asset managers to rebuild distribution infrastructure around faster approval cycles and real-time portfolio transparency requirements.
Growth Catalysts
- Institutional reallocation:Corporate pension funds in the United States are shifting defined contribution plan menus toward passive equity wrappers. This rotation is accelerating inflows into fixed income and multi-asset structures.
- Regulatory streamlining:The SEC's 2019 ETF Rule permits custom basket creation without individualized exemptive relief. This framework has halved time-to-market for novel product architectures.
- Fixed income electronification:Corporate bond market liquidity improvements enable tighter NAV tracking for credit-focused funds. Authorized participants now price baskets with reference to composite trading feeds rather than dealer runs.
Market Restraints
- Fee compression mechanics:Passive equity products now carry expense ratios below 0.03 percent. This pricing floor squeezes revenue per dollar of assets under management across core categories.
- Authorized participant concentration:Creation and redemption infrastructure depends on a shrinking cohort of broker-dealers with balance sheet capacity. This concentration creates systemic liquidity risk during market stress.
- Tax-loss harvesting substitution:Direct indexing platforms now offer personalized portfolio construction at scale. These tools replicate factor exposures without fund wrapper constraints or embedded capital gains.
Strategic Opportunities
- Thematic product white space:Climate transition and artificial intelligence sector exposures remain underrepresented in European retail distribution. UCITS-compliant wrappers can capture this demand gap.
- Defined contribution integration:Target-date collective investment trusts are migrating to ETF share classes. This channel shift opens access to trillions in retirement plan assets previously locked in mutual fund formats.
- Tokenized settlement infrastructure:Distributed ledger technology convergence with traditional custody rails promises T+0 creation and redemption. This compression eliminates counterparty exposure windows for authorized participants.
Industry Challenges
- Quantitative research talent scarcity:Portfolio construction for smart-beta and factor products requires PhD-level expertise in cross-sectional asset pricing. Firms compete for this skill set against hedge funds and technology platforms.
- ESG data integration complexity:Divergent scoring methodologies across MSCI, Sustainalytics, and ISS create portfolio construction ambiguity. Managers must reconcile conflicting ratings for identical issuer positions.
- Legacy system interoperability:Transfer agency and record-keeping infrastructure at retirement plan administrators predates ETF operational conventions. Migration to modern data formats demands multi-year capital commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exchange Traded Fund Market |
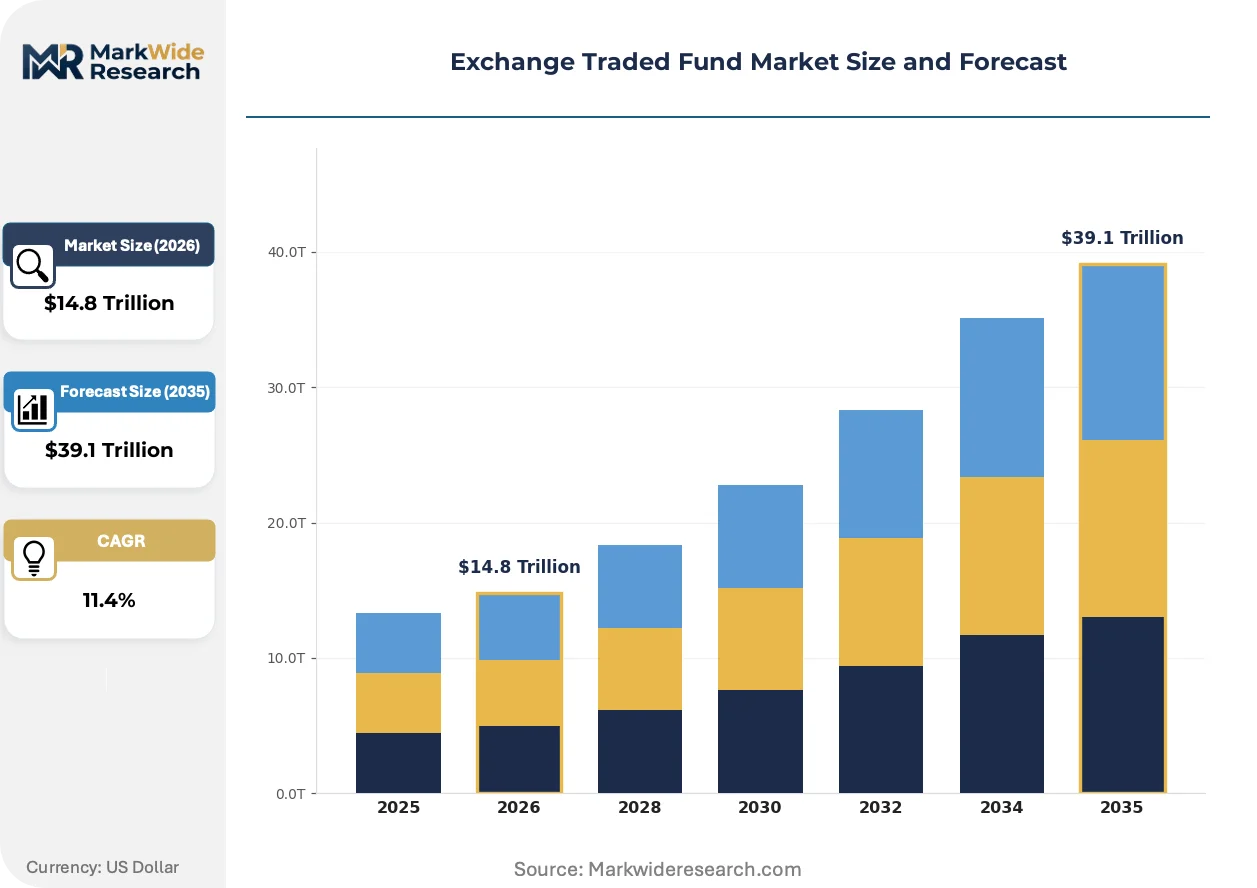
| Market Size in 2026 | $14.8 Trillion |
| Market Size in 2035 | $39.1 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Growth, Value, Income, Defensive Asset Class: Equity, Fixed Income, Commodity, Currency Distribution Channel: Online Brokerage, Financial Advisor, Direct Purchase, Institutional Fund Structure: Open-End, Closed-End, Actively Managed, Index |
| Companies Covered | Invesco, JPMorgan Chase, BlackRock, Global X, WisdomTree, Vanguard, Charles Schwab, ProShares, State Street, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exchange Traded Fund Market Emerging Trajectories
Active management is reclaiming product development bandwidth as fee compression renders pure passive strategies economically marginal. Managers are embedding derivatives overlays, options strategies, and direct lending exposures into exchange-traded wrappers.
Semi-transparent active ETFs are expanding into equity factor and alternative strategy domains. Precidian's ActiveShares model and Fidelity's proprietary structures shield daily portfolio positions while maintaining intraday liquidity. Large registered investment advisors are adopting these vehicles for tax-efficient core-satellite construction. This architecture is compressing the traditional mutual fund distribution monopoly over active management.
The SEC's spot cryptocurrency approval framework is reshaping permissible underlying assets for 1940 Act products. Bitcoin and ether ETPs now trade alongside traditional commodity funds, creating novel custody and valuation obligations for fund administrators. European UCITS regulators are evaluating parallel frameworks, with the Central Bank of Ireland and Luxembourg CSSF coordinating disclosure standards. Retail brokerage platforms are responding by expanding due diligence infrastructure for digital asset products.
Advisory fee unbundling is accelerating direct-to-consumer platform adoption. Zero-commission trading at Schwab, Fidelity, and Vanguard has eliminated distribution friction for self-directed investors. This channel shift is concentrating flows into lowest-cost share classes and compressing revenue for intermediated distribution. The United States exhibits the most pronounced migration, though European neo-broker platforms are replicating the model.
Exchange Traded Fund Market Segmentation
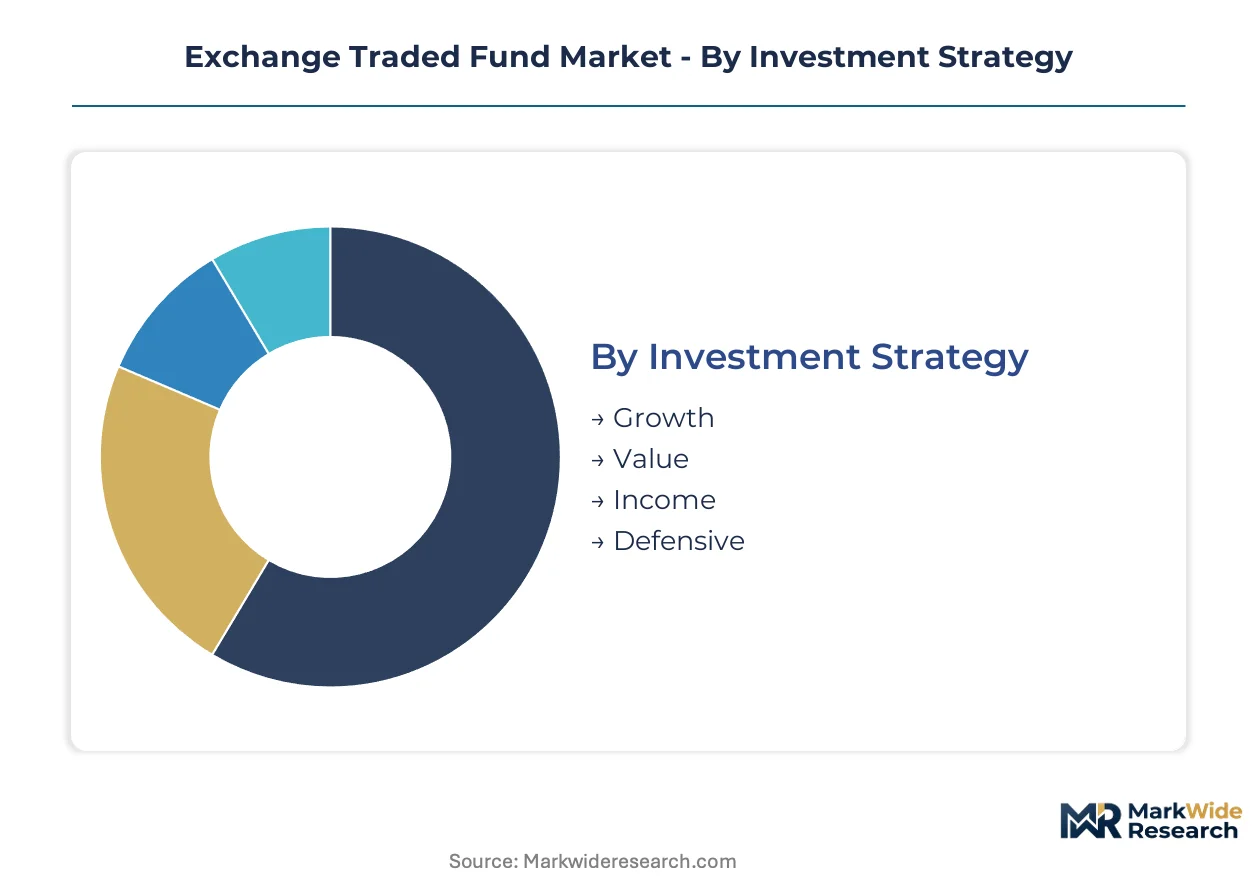
ETF segmentation reveals how product architecture and distribution pathways determine revenue capture. Each dimension carries distinct margin profiles and regulatory obligations that shape competitive positioning.
Investment Strategy:
Strategy concentration tilts toward institutional liability-matching requirements, with pension funds driving demand for predictable cash flow profiles.
- Growth:Targets capital appreciation through equity exposure to high-revenue-expansion companies. Demand concentrates in technology-heavy defined contribution plans where younger cohorts accept volatility for long-term accumulation.
- Value:Seeks undervalued securities trading below intrinsic metrics. Rotational inflows from insurance general accounts in the United States favor this segment during rate uncertainty.
- Income:Prioritizes yield generation through dividend equities and credit instruments. Retiree-facing advisory platforms in Florida and Arizona steer allocations here.
- Defensive:Emphasizes capital preservation through low-beta holdings and volatility dampening. Corporate treasury cash management programs utilize these structures.
Today's leader: Income. Tomorrow's challenger: Growth.
Asset Class:
Asset class economics diverge sharply on creation basket complexity and authorized participant participation.
- Equity:The most liquid creation mechanism relies on continuous market trading of underlying shares. US large-cap products dominate flow volume through 24-hour market access and tight spreads.
- Fixed Income:Corporate and municipal bond liquidity improvements enable tighter NAV tracking. European pension funds are expanding allocations as composite pricing feeds replace dealer-run valuations.
- Commodity:Physical storage obligations for precious metals or futures roll management for energy exposure create operational complexity. CFTC registration requirements add compliance layers.
- Currency:Delivers exposure to foreign exchange rate movements through spot or forward contracts. Treasury departments at multinational corporations use these for hedge accounting efficiency.
Equity commands current assets. Fixed income is climbing the fastest as electronification advances.
Distribution Channel:
Channel economics are fragmenting as zero-commission platforms disintermediate traditional advisory relationships.
- Online Brokerage:Self-directed investors execute trades through digital platforms with minimal friction. Schwab and Fidelity custody relationships concentrate flow into lowest-cost share classes.
- Financial Advisor:Intermediated distribution through RIAs and wirehouses sustains higher-fee product viability. Suitability documentation requirements under FINRA shape product access.
- Direct Purchase:Investors acquire shares directly from fund sponsors or transfer agents. Vanguard's proprietary platform exemplifies this model with expense ratio advantages.
- Institutional:Defined benefit plans and insurance companies deploy block trades with customized liquidity terms. Securities lending revenue sharing distinguishes competitive offerings.
Institutional anchors dollar volume. Online brokerage is gaining share fastest among retail cohorts.
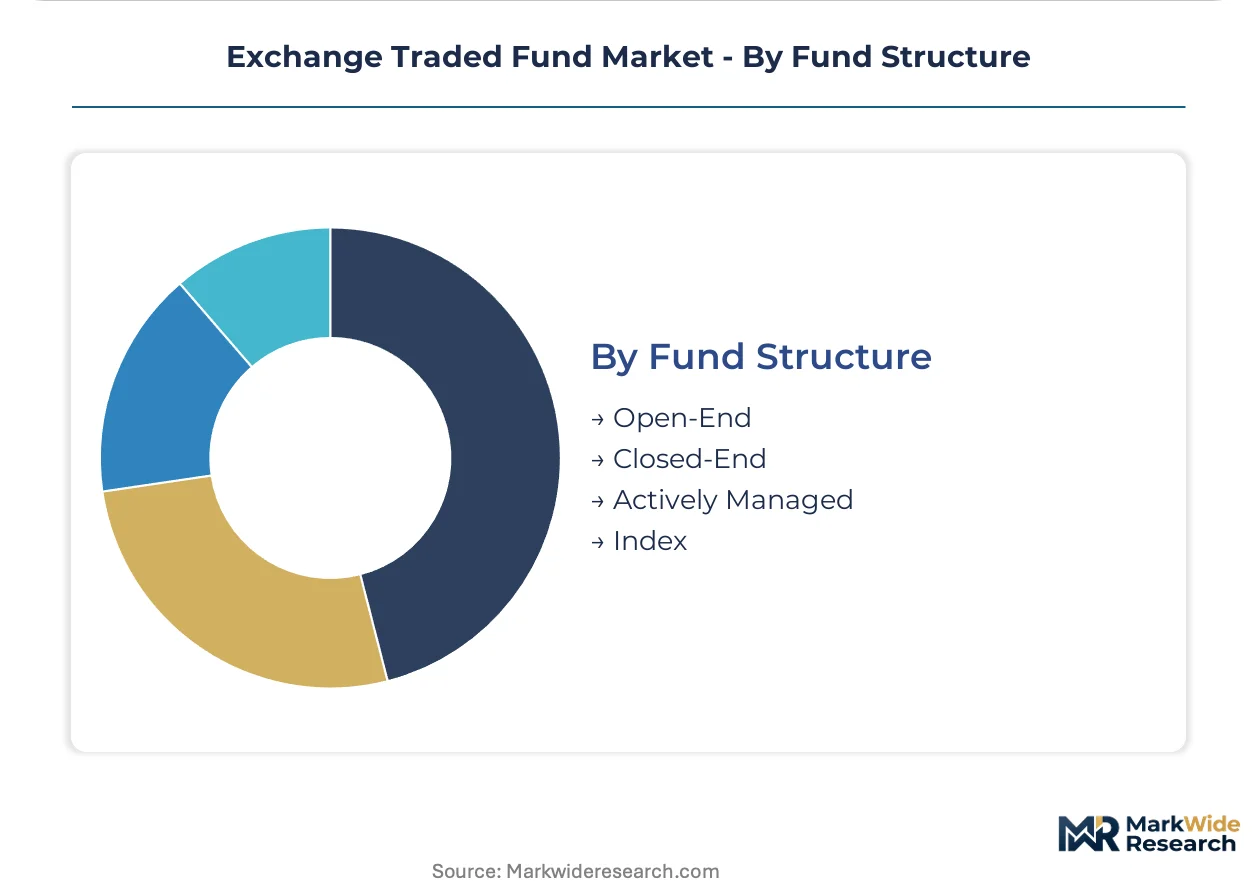
Fund Structure:
Structural choice determines transparency obligations and tax efficiency parameters.
- Open-End:Continuous creation and redemption at NAV accommodates variable asset flows. The 1940 Act framework governs most US-domiciled products with daily disclosure requirements.
- Closed-End:Fixed share supply trades at market-determined premiums or discounts to NAV. Leverage capacity through preferred shares attracts income-focused investors.
- Actively Managed:Portfolio managers deviate from benchmark indices with discretionary security selection. Semi-transparent models from Precidian and Fidelity shield daily positions while maintaining intraday liquidity.
- Index:Rules-based replication minimizes tracking error and expense ratios. Smart-beta variants embed factor tilts with quantitative construction methodologies.
Index structures dominate assets. Actively managed products are expanding most quickly as fee compression squeezes pure passive economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ETF assets dwarf Canadian and Mexican markets combined, yet regulatory harmonization across North America is accelerating cross-border product distribution. Institutional adoption patterns diverge sharply between defined benefit systems and retail brokerage channels.
United States
Corporate pension funds and 401(k) plan sponsors drive institutional flows into passive equity and fixed income wrappers. SEC Rule 6c-11 streamlines exemptive relief for novel product architectures, compressing approval timelines. New York and Boston asset management clusters dominate smart-beta and thematic fund construction, with BlackRock and Vanguard headquarters anchoring product innovation pipelines.
Canada
Canadian pension funds and insurance general accounts expand ETF allocations for liability-matching strategies. CSA National Instrument 81-102 governs investment fund structures, permitting derivative overlays within exchange-traded wrappers. Toronto's Bay Street financial district concentrates fund administration and custodial services, with major banks integrating ETF platforms into wealth management distribution.
Germany
German insurance companies and retail banks channel savings into UCITS-compliant equity and fixed income products. BaFin supervision of investment funds under KAGB mandates transparency standards for synthetic replication structures. Frankfurt's fund management ecosystem specializes in ESG-integrated strategies, with DWS and Commerzbank units developing climate-transition thematic offerings.
United Kingdom
British defined contribution schemes and self-invested personal pension holders sustain demand for low-cost index trackers. FCA authorization requirements for fund managers shape product distribution through platforms and advisers. London's City district hosts European ETF trading infrastructure, with primary listings and market-making operations concentrated in the Square Mile.
Japan
Japanese government pension investment fund and regional banks increase ETF holdings for domestic equity market stabilization. FSA guidelines on investment trusts govern exchange-traded product disclosure and suitability. Tokyo's Marunouchi and Nihonbashi districts house asset management headquarters, with Nomura and Daiwa Securities developing quantitative factor strategies.
Exchange Traded Fund Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across product architecture and distribution channel dimensions. The market structure concentrates around three dominant asset managers controlling core passive flows, while specialized boutiques capture thematic and alternative strategy niches. Strategic archetypes separate scale-driven index providers, active management specialists, and distribution-integrated platforms. Competitive moves center on fee compression races in vanilla products and acquisition of quantitative research capabilities for smart-beta construction.
Within the scale-driven tier, BlackRock and Vanguard exemplify divergent approaches to cost leadership and proprietary platform control. JPMorgan Chase occupies a position bridging institutional active management and retail distribution integration. These three anchors represent distinct competitive vectors: BlackRock's iShares ecosystem sustains product breadth, Vanguard's mutual ownership model eliminates profit extraction, and JPMorgan's banking relationships unlock defined contribution channel access.
| Leading Market Players |
|---|
| Invesco |
| JPMorgan Chase |
| BlackRock |
| Global X |
| WisdomTree |
| Vanguard |
| Charles Schwab |
| ProShares |
| State Street |
| Others |
Supply Flow & Price Mechanics
ESG disclosure mandates under the SEC's climate reporting framework gate access to premium-tier distribution channels for ETF sponsors, as institutional buyers now require granular carbon footprint data before committing to authorized participant relationships. This regulatory filter simultaneously concentrates qualified supply among asset managers with dedicated sustainability data infrastructure and compresses pricing power for generic passive products lacking differentiated ESG integration.
Pricing Analysis
Capacity additions in thematic and actively managed strategies are reshaping price floors across the ETF landscape, forcing traditional index providers to defend share through expense ratio compression. Three-tier pricing structure across premium active, standard smart-beta, and economy pure-passive levels stratifies the market, with fee differentiation driven by portfolio transparency obligations and quantitative research intensity. Pricing pressure stems from zero-commission brokerage platforms concentrating flows into lowest-cost share classes. Retail self-directed investors exhibit highest price sensitivity, while institutional defined contribution plans prioritize liquidity terms over basis point differences.
Supply Chain Analysis
Domestic-content mandates for retirement plan fiduciary oversight are reshaping sourcing requirements for ETF sponsors serving US defined contribution channels. Supply concentration centers on the United States, Ireland, and Luxembourg as primary domiciles for fund structuring and UCITS compliance. Raw material dependencies include Bloomberg and Refinitiv data feeds, MSCI and FTSE index licensing, and custodial services from BNY Mellon and State Street. Single-source vulnerability in authorized participant relationships creates systemic liquidity risk during market stress. Distribution runs through broker-dealer platforms, RIA networks, and direct-to-investor proprietary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ETF market functions as a regulatory compounder, with each SEC modernization cycle expanding permissible product architectures and deepening institutional adoption. The 2019 ETF Rule's exemptive relief framework remains the pivotal milestone, compressing launch timelines and accelerating demand from pension funds seeking operational efficiency.
For Market Incumbents: Anchor scale advantages through exclusive authorized participant relationships with Goldman Sachs and Jane Street, insulating creation-redemption infrastructure against balance sheet constraints. Defend against direct indexing substitution by embedding tax-loss harvesting capabilities into semi-transparent active wrappers. Prioritize vertical integration into proprietary data feeds for ESG scoring to resolve conflicting MSCI and Sustainalytics methodologies.
For New Entrants and Emerging Players: European retail banks underserved by climate-transition thematic products present the most penetrable entry point for UCITS-compliant artificial intelligence and clean energy wrappers. Target German insurance general accounts and British self-invested personal pension holders through platform distribution partnerships with Hargreaves Lansdown and AJ Bell. Lead with factor-based fixed income strategies exploiting electronification-driven NAV tracking improvements.
For Investors and Strategic Acquirers: Roll-up economics work for quantitative research boutiques because smart-beta construction requires PhD-level cross-sectional asset pricing expertise that scale players cannot replicate internally. Five-to-ten year viability hinges on capturing defined contribution channel migration from mutual fund share classes to ETF wrappers. Watch the SEC's spot cryptocurrency approval velocity as the inflection signal for digital asset custody infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Semi-Transparent Active ETF Launch | Precidian's ActiveShares model enables tax-efficient core-satellite construction for RIAs. |
| Defined Contribution Channel Migration | Target-date collective investment trusts shifting to ETF share classes unlocks trillions in retirement assets. |
| Tokenized Settlement Infrastructure | Distributed ledger convergence with custody rails promises T+0 creation and redemption cycles. |
| ESG Data Integration Investment | Proprietary scoring methodologies resolve MSCI-Sustainalytics divergence for institutional mandates. |
| Quantitative Research Acquisition | PhD-level factor construction capabilities differentiate smart-beta products in fee-compressed markets. |
Methodological Framework
Bottom-up defined contribution plan modeling reconciled against top-down authorized participant flow tracking forms the analytical core of this study. Primary interviews with ETF product strategists, pension fund consultants, SEC regulatory affairs specialists, and broker-dealer trading desk heads combined with secondary validation against SEC exemptive relief filings, FINRA regulatory notices, ICI flow data, and Morningstar expense ratio databases. Triangulation between sponsor-reported AUM figures and custodial position records ensures measurement consistency.
Input-output matrices map creation-redemption mechanics to NAV tracking precision across equity, fixed income, and alternative asset classes throughout the forecast period. Segmentation dimensions include investment strategy, asset class, distribution channel, and fund structure, with CAGRs derived from regression analysis of historical flow velocity against regulatory approval timelines. Forecast inputs incorporate electronification indices for corporate bond liquidity and pension fund reallocation velocity metrics.
Underlying measurement precision varies by segment; passive equity and fixed income categories carry tighter precision than thematic and cryptocurrency products given disclosure standardization differences. Forecasts reflect assumptions around SEC regulatory continuity and institutional adoption curves, with revision risk concentrated in spot cryptocurrency approval delays and ESG mandate litigation outcomes. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe Mutual Fund Market