
 Shadow Banking Market | 2026-2036
Shadow Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Shadow Banking Market Analysis
Modular product bundling across structured credit and direct lending offerings is realigning institutional procurement patterns. Goldman Sachs leverages its balance sheet strength to anchor large-scale specialty financing mandates. Ares Management sustains dominant positioning in private debt through captive origination networks. Deutsche Bank competes across European asset-backed securities distribution with integrated structuring desks.
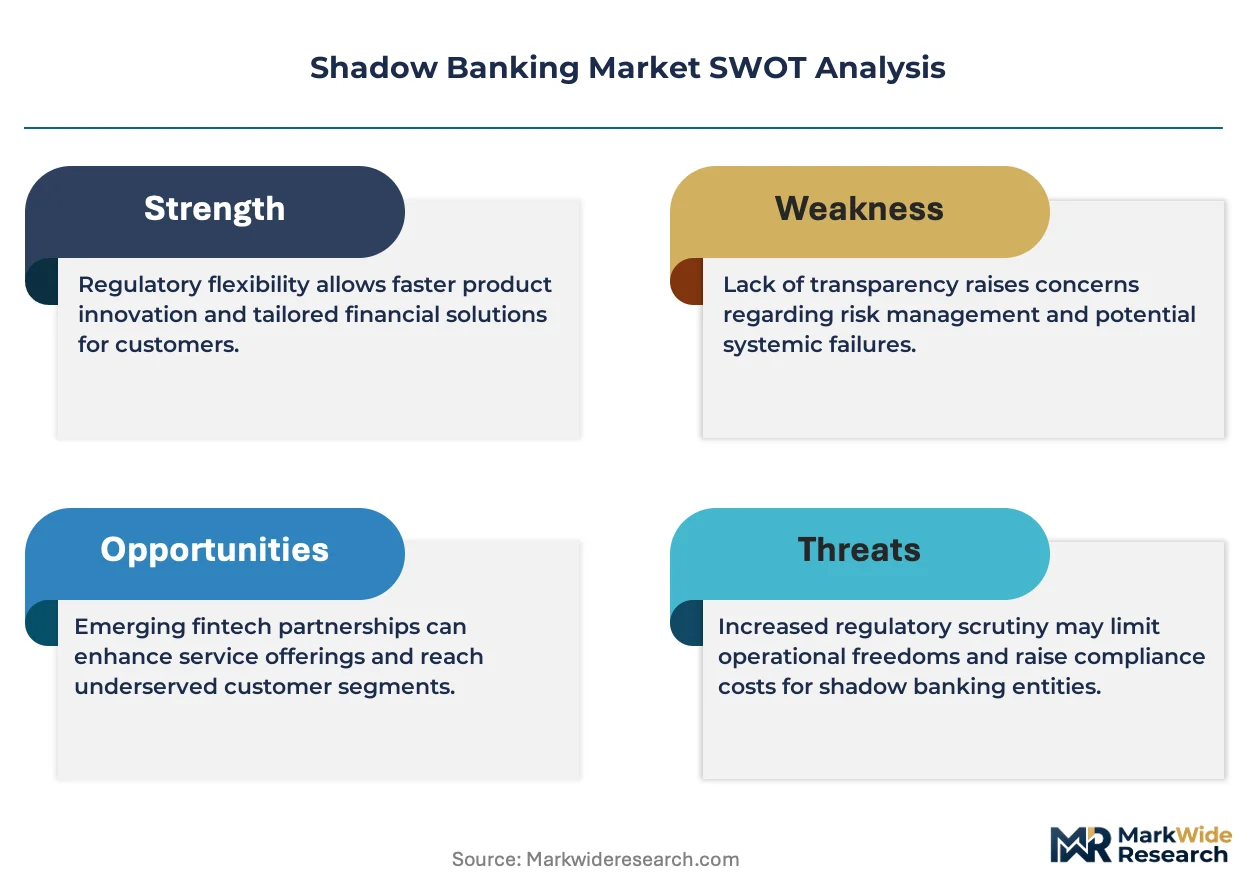
Shadow banking encompasses non-bank financial intermediaries that perform maturity transformation, credit intermediation, and liquidity provision without holding deposit-taking licenses, typically operating through structured vehicles, repo markets, and securitization conduits. These entities channel institutional capital into credit markets with greater leverage flexibility and lighter prudential oversight than regulated depositories. Private debt and direct lending segments command expanding margin pools as banks retreat from middle-market corporate lending under Basel III constraints. Hedge funds and asset-backed securities offerings retain structural importance for yield-seeking pension funds navigating prolonged low-rate environments.
The SEC's private fund adviser rules and the EU's Alternative Investment Fund Managers Directive impose escalating transparency and custody requirements across shadow banking operations. The Federal Reserve's oversight of systemically important non-banks and the FSB's global monitoring framework for non-bank financial intermediation constrain leverage accumulation and liquidity mismatch risks. Stakeholders must calibrate capital deployment strategies against divergent jurisdictional enforcement intensities and evolving systemic risk designations.
Market Dynamics
Basel III capital adequacy constraints on regulated depositories are accelerating capital migration into private debt vehicles and specialty finance conduits. This structural displacement is reshaping credit intermediation architecture across developed economies.
Growth Catalysts
- SEC Private Fund Adviser Rules:Enhanced disclosure mandates are standardizing operational frameworks across US-registered alternative investment managers, reducing due diligence friction for institutional allocators.
- Pension fund yield compression:Defined-benefit plans in the United States and United Kingdom are expanding allocations to direct lending strategies as traditional fixed income returns deteriorate.
- Technology-enabled loan origination:Machine learning credit scoring platforms are compressing underwriting timelines for middle-market borrowers, expanding addressable deal flow.
Market Restraints
- Leverage limit uncertainty:The Financial Stability Board's evolving framework for non-bank financial intermediation creates capital structure planning ambiguity across multi-jurisdictional vehicles.
- Libor transition execution:Contractual fallback language inconsistencies in legacy securitization documentation generate legal remediation costs for European asset-backed securities issuers.
- Repo market concentration:Tri-party repo infrastructure dependence on two US clearing banks creates systemic liquidity chokepoints during stress periods.
Strategic Opportunities
- Climate transition finance:The EU Green Deal's sustainable finance taxonomy is directing institutional capital toward green private debt strategies with preferential regulatory treatment.
- India infrastructure debt:National Investment and Infrastructure Fund structures are creating first-mover advantages for foreign managers with rupee-denominated origination capabilities.
- Tokenized fund interests:Distributed ledger settlement infrastructure is enabling secondary liquidity for previously illimited partnership stakes, attracting new investor categories.
Industry Challenges
- Valuation methodology standardization:Divergent private credit mark-to-model practices across US and European jurisdictions complicate portfolio benchmarking for allocators.
- Cybersecurity infrastructure:Alternative investment managers face escalating SEC examination focus on custody technology controls and third-party vendor risk management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shadow Banking Market |
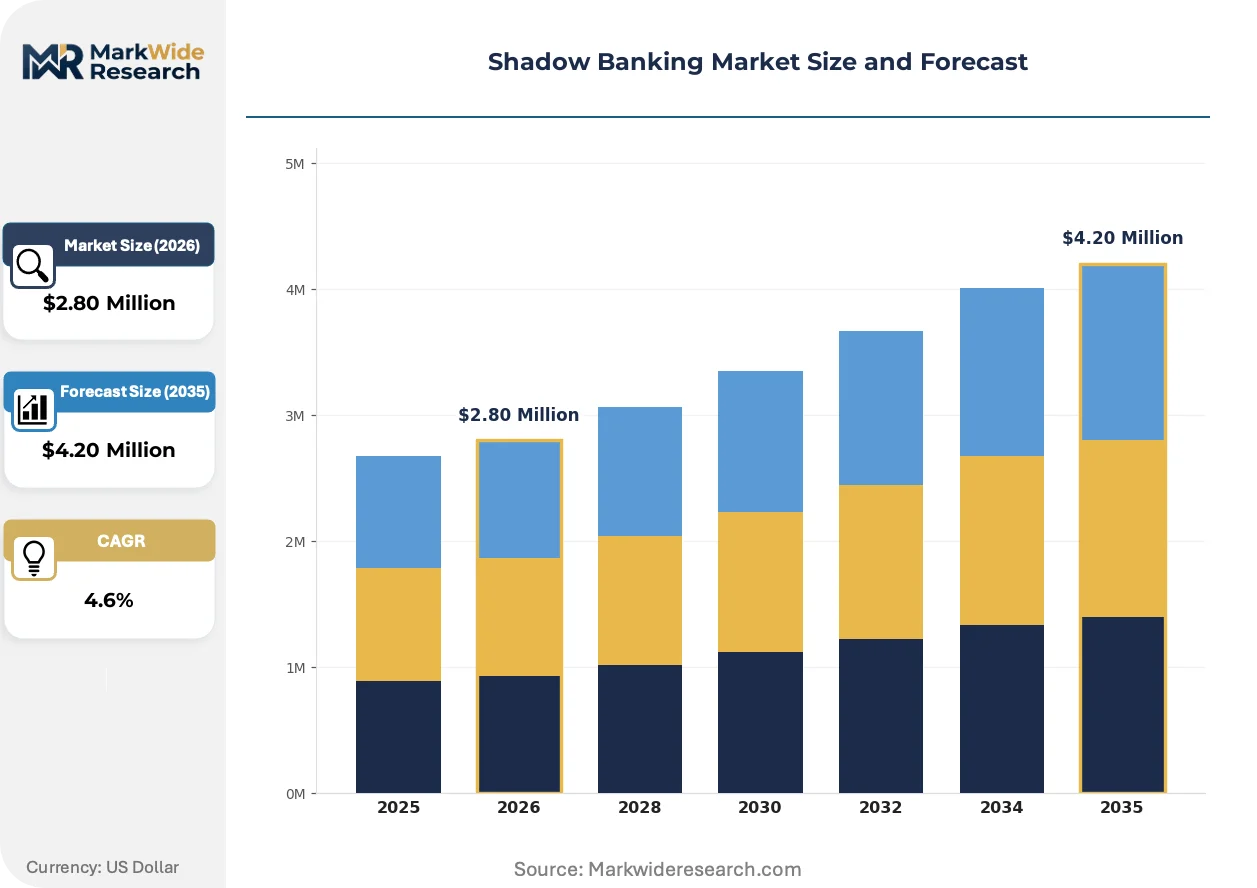
| Market Size in 2026 | $2.80 Million |
| Market Size in 2035 | $4.20 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Asset Management, Investment Funds, Private Debt, Hedge Funds Client Type: Pension Funds, Insurance Companies, High-Net-Worth Individuals, Corporations Investment Stage: Venture Capital, Growth Equity, Mezzanine Financing, Exit Financing Offering: Structured Products, Asset-Backed Securities, Direct Lending, Specialty Financing |
| Companies Covered | Credit Suisse, Deutsche Bank, Bank of America Merrill Lynch, Morgan Stanley, Goldman Sachs, Barclays, Citibank, Ares Management, HSBC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shadow Banking Market Emerging Trajectories
Digital infrastructure is compressing settlement cycles and enabling real-time portfolio monitoring across previously opaque private credit structures. These capabilities are altering how institutional capital evaluates and prices illiquidity premiums.
Application programming interfaces connecting loan origination platforms with portfolio management systems are unifying data flows across previously siloed credit functions. Asset managers deploying these integrations report materially faster covenant monitoring and workout response capabilities. The structural consequence is compressing the information advantage that proprietary sourcing networks previously conferred.
The EU's Alternative Investment Fund Managers Directive sustainability disclosure requirements are mandating granular carbon footprint reporting across private debt portfolios. European fund administrators are investing in climate data vendor partnerships to meet these obligations. Middle-market direct lending strategies with heavy industrial exposure face the steepest compliance adaptation costs.
Institutional buyers are consolidating manager relationships around multi-strategy platforms offering integrated private credit, real assets, and specialty finance capabilities. Single-product boutiques face sustained fee pressure as allocators negotiate cross-vehicle economic arrangements. This concentration pattern is most pronounced among US public pension plans with staffs too lean to monitor fragmented manager rosters.
Shadow Banking Market Segmentation
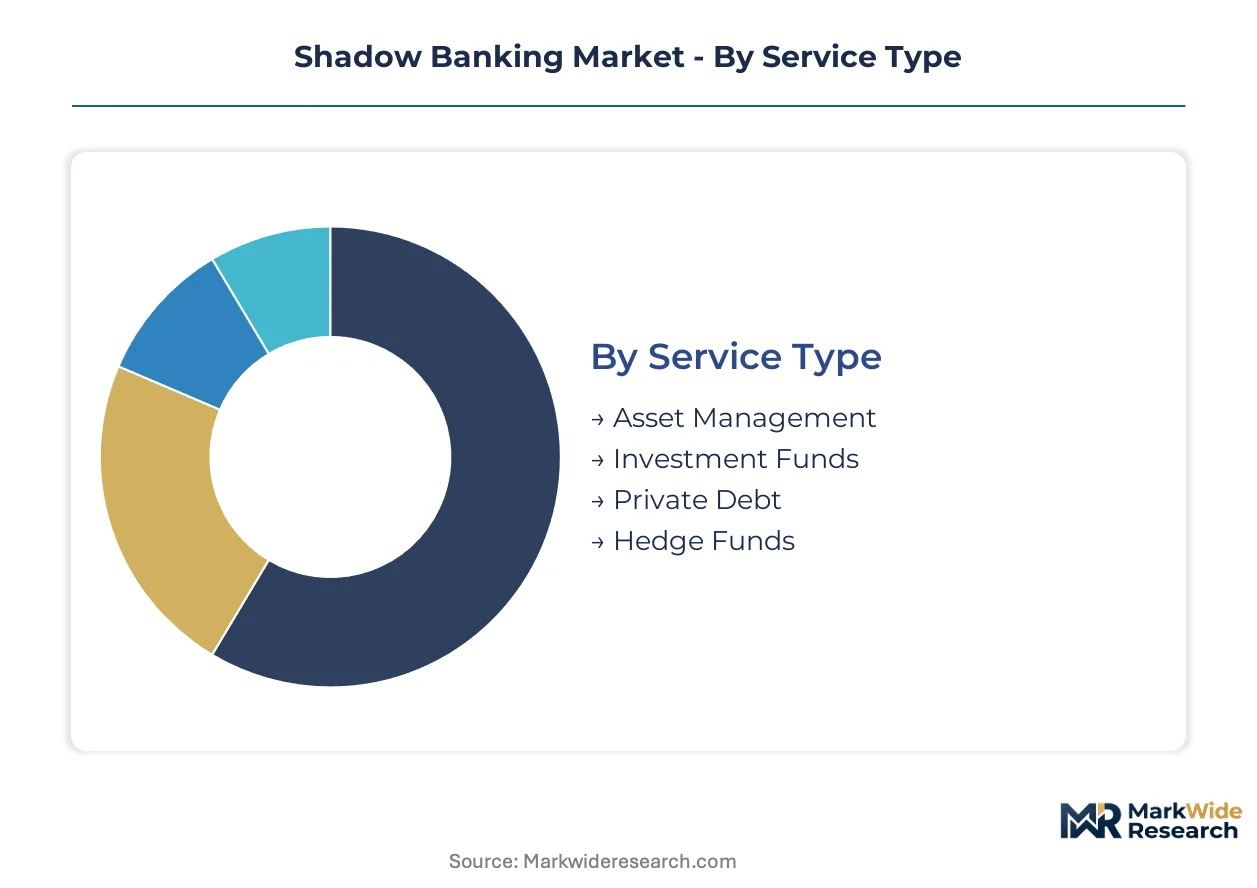
Shadow banking's fragmentation across service models and client archetypes demands granular segmentation. Each dimension reveals distinct capital flows, regulatory exposures, and margin structures that shape competitive strategy.
Service Type:
Replacement cycles in shadow banking services accelerate as institutional clients rebalance away from traditional bank intermediation toward specialized credit vehicles.
- Private Debt:Direct lending to middle-market borrowers through non-bank structures, typically floating-rate with covenant protection. Demand concentrates among US public pension funds seeking yield replacement as Basel III compresses bank lending capacity; the segment captures the steepest inflows as duration risk shifts off regulated balance sheets.
- Asset Management:Discretionary portfolio construction across liquid and illiquid credit strategies, bundled with risk analytics and reporting infrastructure. European insurance companies dominate allocations here, driven by Solvency II yield desperation and matching-adjustment eligibility for certain private credit structures.
- Investment Funds:Pooled vehicles accessing specialty finance, distressed credit, and structured equity through limited partnership structures. Singapore sovereign wealth vehicles anchor Asia-Pacific demand for dollar-denominated exposure.
- Hedge Funds:Absolute return strategies employing leverage, derivatives, and event-driven positioning across credit markets. Family offices in Greenwich and London sustain capacity despite fee compression.
Volume placements concentrate in Private Debt; the faster expansion belongs to Asset Management as insurance regulatory capital treatment evolves.
Client Type:
Cost tier stratification separates fee-sensitive institutional allocators from price-agnostic strategic capital.
- Pension Funds:Defined-benefit plans with liability-driven investment mandates, deploying shadow banking as duration-matched yield. US state plans in California and New York lead deployment scale.
- Insurance Companies:Life insurers with long-dated liability books, utilizing private debt for asset-liability management. German and Japanese carriers show fastest allocation growth.
- High-Net-Worth Individuals:Family offices and private banks channeling personal capital into co-investment structures alongside institutional sponsors. Swiss and Singapore booking centers dominate custody.
- Corporations:Treasury departments deploying excess cash into money market funds and short-duration credit vehicles. Technology sector cash concentration drives North American demand.
Deployment scale concentrates with Pension Funds; Insurance Companies are climbing the fastest as regulatory capital rules recalibrate.
Investment Stage:
Application maturity divides early-cycle venture exposure from late-cycle liquidity provision.
- Growth Equity:Minority stakes in revenue-stage companies with proven unit economics, structured as preferred equity or convertible instruments. US technology crossover funds anchor deployment.
- Venture Capital:Seed through Series C equity and debt to pre-revenue or early-revenue enterprises. Silicon Valley and Tel Aviv ecosystems concentrate manager presence.
- Mezzanine Financing:Subordinated debt with equity kickers, filling capital structure gaps beneath senior secured positions. European buyout markets sustain volume.
- Exit Financing:Bridge loans and recapitalization facilities supporting secondary buyouts and IPO preparation. London and New York sponsor activity drives flow.
Transaction volume concentrates in Growth Equity; Mezzanine Financing is gaining share fastest as leveraged finance markets recalibrate.
Offering:
Margin structure separates bespoke structuring from standardized securitization.
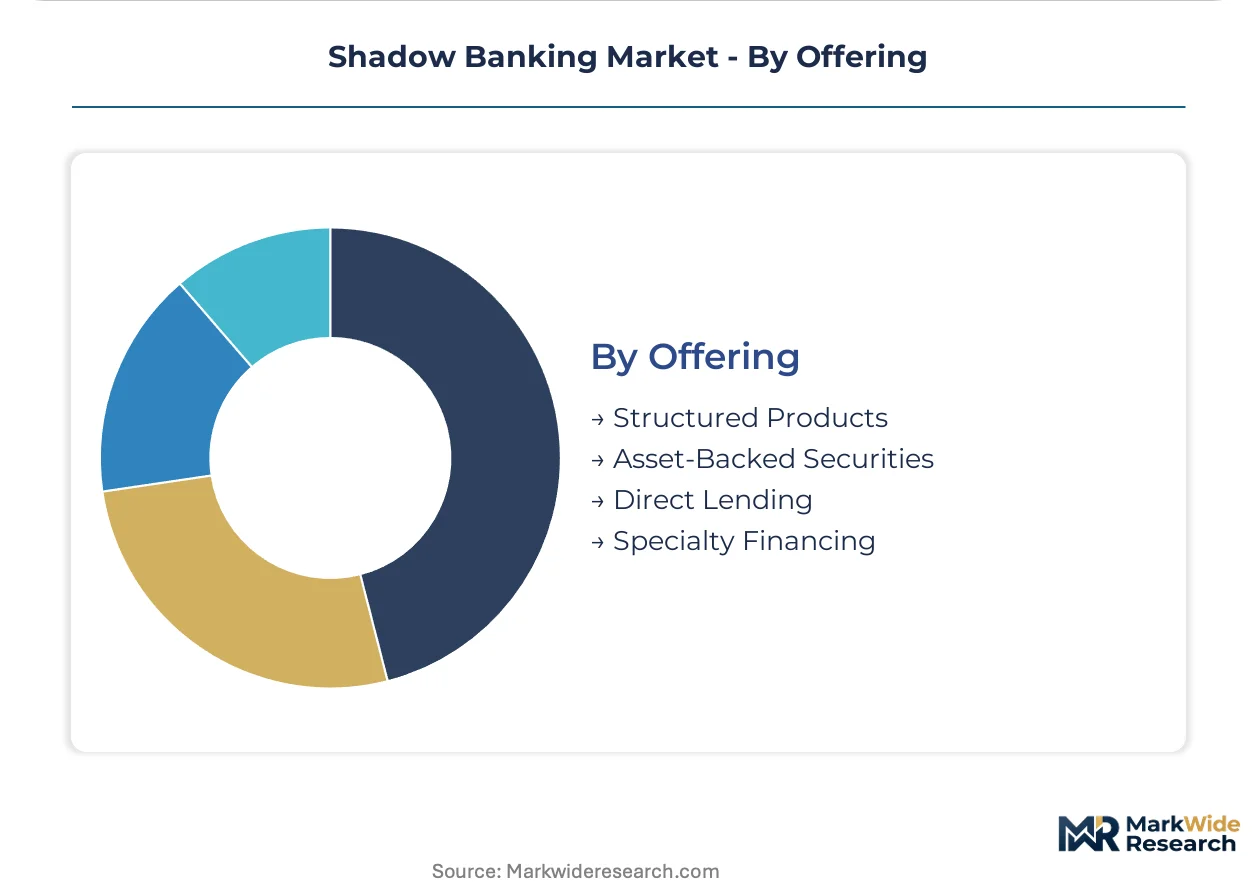
- Direct Lending:Bilateral or clubbed loans originated outside bank syndication, with negotiated covenants and collateral packages. US middle-market sponsors in Chicago and Dallas anchor origination networks.
- Structured Products:Customized notes combining derivatives, credit enhancement, and embedded options for specific risk-return profiles. Japanese banks and European insurers dominate buyer bases.
- Asset-Backed Securities:Term securitization of receivables, leases, or consumer loans into rated tranches. Auto and marketplace lending collateral concentrate issuance.
- Specialty Financing:Niche credit solutions for aircraft, shipping, infrastructure, or intellectual property assets. Dublin and Singapore leasing platforms sustain deal flow.
Origination volume concentrates in Direct Lending; Specialty Financing shows the steepest expansion trajectory as asset class diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shadow banking activity concentrates where regulatory arbitrage meets institutional capital depth. The United States generates the largest transaction volumes, while European and Asian markets exhibit divergent growth trajectories shaped by local prudential frameworks.
United States
US public pension funds and insurance companies deploy the world's largest shadow banking allocations, seeking yield outside Basel III-constrained bank balance sheets. The SEC's enhanced private fund adviser rules standardize disclosure frameworks for registered alternative investment managers. New York and Chicago anchor origination networks for middle-market direct lending, with Dallas emerging as a specialty finance hub.
United Kingdom
Defined-benefit pension schemes facing liability-driven investment mandates expand allocations to private debt vehicles as gilt yields compress. The Financial Conduct Authority's implementation of the Investment Firms Prudential Regime recalibrates capital requirements for non-bank intermediaries. London's City and Mayfair districts concentrate hedge fund and private credit manager presence, with secondary buyout financing driving transaction flow.
Germany
German life insurers with long-dated liability books utilize private debt for asset-liability management under Solvency II matching-adjustment eligibility. The Federal Financial Supervisory Authority's oversight of alternative investment funds intensifies transparency requirements for cross-border vehicles. Frankfurt's financial district hosts integrated structuring desks competing across European asset-backed securities distribution.
Singapore
Sovereign wealth vehicles and family offices anchor Asia-Pacific demand for dollar-denominated shadow banking exposure. The Monetary Authority of Singapore's framework for fund management companies imposes custody and risk management standards on private fund operations. The city-state's booking centers dominate custody for high-net-worth capital deploying into co-investment structures.
India
Foreign managers with rupee-denominated origination capabilities target infrastructure debt opportunities through National Investment and Infrastructure Fund structures. The Securities and Exchange Board of India's regulations for alternative investment funds govern foreign sponsor participation in domestic credit markets. Mumbai and Delhi-NCR concentrate domestic non-bank financial company activity, with specialty financing expanding across industrial corridors.
Shadow Banking Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across shadow banking's fragmented architecture. Universal banks leverage balance sheet scale to anchor large-scale specialty financing mandates, while independent asset managers sustain dominant positioning through captive origination networks. The competitive terrain separates integrated multi-strategy platforms from single-product boutiques facing sustained fee pressure. Consolidation concentrates around cross-vehicle economic arrangements and technology-enabled loan origination capabilities.
Among US-based diversified financial institutions, Goldman Sachs and Morgan Stanley exemplify balance sheet-driven competitive positioning, while Ares Management occupies a specialist archetype built around private debt origination networks. These three entities represent divergent strategic paths: universal bank platform deployment versus independent asset manager focus.
| Leading Market Players |
|---|
| Credit Suisse |
| Deutsche Bank |
| Bank of America Merrill Lynch |
| Morgan Stanley |
| Goldman Sachs |
| Barclays |
| Citibank |
| Ares Management |
| HSBC |
| Others |
Supply Flow & Price Mechanics
Capital commitment fees from institutional limited partners cascade through fund economics to determine management fee tiers and carried interest thresholds across private debt strategies. These fee structures concentrate pricing power with managers demonstrating sustained net IRR performance through multiple credit cycles.
Pricing Analysis
Margin tightening in core direct lending reflects fee compression as allocators consolidate relationships around multi-strategy platforms. Three-tier pricing structure across premium, standard, and economy levels separates top-quartile performers with captive origination networks from commodity middle-market lenders. Pension funds exhibit highest price sensitivity, while family offices absorbing co-investment economics show lowest fee elasticity. Pricing pressure stems from allocator staff constraints limiting manager monitoring bandwidth.
Supply Chain Analysis
Dual-sourcing requirements from US public pension funds mandate multiple administrator and custodian qualifications across fund structures. Origination networks concentrate in the United States, the United Kingdom, and Singapore, with deal flow generation resting on sponsor relationships built over successive credit cycles. Key dependencies include CLO warehouse financing, tri-party repo clearing, and securitization conduit access. Single-source vulnerability sits with tri-party repo infrastructure dependence on two US clearing banks. Distribution runs through placement agent networks and direct institutional relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shadow banking competition is becoming a vertical-integration race, with balance sheet deployment capabilities and captive origination networks serving as the decisive downstream levers separating scale players from fee-compressed boutiques.
For Market Incumbents: Deploy balance sheet anchoring to defend specialty financing mandates against independent asset managers building direct lending franchises. Incumbents should deepen captive origination networks in Dallas and Chicago middle-market corridors while investing in SEC examination-ready custody technology controls. The threat vector emanates from technology-enabled loan origination platforms compressing underwriting timelines and eroding information advantages. For New Entrants and Emerging Players: Capture infrastructure debt opportunities through National Investment and Infrastructure Fund structures in India, where rupee-denominated origination capabilities remain scarce among foreign sponsors. Green private debt strategies under EU Green Deal taxonomy offer second white-space target with preferential regulatory treatment. Go-to-market positioning should emphasize climate data vendor partnerships enabling granular carbon footprint reporting compliance. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent asset managers with proven net IRR through multiple credit cycles in the United States, where consolidation pressure concentrates single-product boutiques. Long-term viability over a multi-cycle horizon requires integrated multi-strategy capabilities spanning private credit, real assets, and specialty finance. Watch FSB leverage limit framework finalization as the signal for capital structure planning clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Balance Sheet Anchoring | Goldman Sachs leverages scale to capture large-scale specialty financing mandates from retreating banks. |
| Captive Origination Network Expansion | Ares Management sustains dominant private debt positioning through sponsor relationships built across credit cycles. |
| Technology-Enabled Underwriting | Machine learning credit scoring platforms compress timelines for middle-market borrowers and expand deal flow. |
| Climate Data Infrastructure Investment | European fund administrators partner with climate data vendors to meet AIFMD sustainability disclosure requirements. |
| Multi-Strategy Platform Consolidation | US public pension plans negotiate cross-vehicle economic arrangements with integrated asset managers. |
Methodological Framework
Multi-period observation of capital commitment flows, fee compression trends, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with fund formation attorneys, institutional allocator due diligence officers, private credit portfolio managers, and securitization structurers. Secondary validation drew from SEC private fund adviser rule filings, FSB non-bank financial intermediation monitoring reports, EU AIFMD regulatory guidance, and Federal Reserve systemically important non-bank designations. Bottom-up triangulation across manager-reported AUM and top-down allocator survey data ensured consistency.
Segment-weighting approaches distributed value projections across service type, client archetype, investment stage, and offering structure dimensions. CAGRs derived from regression analysis of historical capital commitment growth rates applied across the projection horizon, with inputs including Basel III bank retreat velocity, pension fund liability-driven investment mandate expansion, and technology-enabled loan origination adoption curves.
The model holds under stable prudential regulatory frameworks and sustained institutional yield compression; deviation in FSB leverage limit finalization or SEC examination intensity escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Armenia Stock Market