
 High-Yield Bonds Market | 2026-2036
High-Yield Bonds Market Size, Share, and Industry Trends Forecast 2026-2036
High-Yield Bonds Market Analysis
Collateralized loan obligation bundling is hardening as the dominant packaging format for institutional high-yield exposure. BlackRock leverages its scale in active credit selection to anchor CLO equity tranche demand. JP Morgan sustains dealer dominance in secondary market liquidity provision. VanEck competes through specialized ETFs targeting fallen-angel credit transitions.
High-yield bonds are debt securities issued by entities with sub-investment-grade credit ratings, typically paying coupons between 150 and 600 basis points above comparable-maturity Treasuries to compensate for elevated default probability. These instruments finance leveraged buyouts, capital restructuring, and growth capex for companies excluded from investment-grade markets. Corporate bonds occupy the deepest liquidity pools, while distressed bonds command the widest bid-ask spreads and attract event-driven capital. Active management approaches capture alpha from credit migration, though index investing has eroded fee structures across retail channels.
The SEC enforces liquidity risk management programs under Rule 22e-4, forcing fund managers to classify holdings across four liquidity buckets and maintain minimum unencumbered cash positions. The Financial Industry Regulatory Authority monitors mark-up disclosure in retail bond transactions, compressing opaque pricing practices. The European Securities and Markets Authority's stress-testing frameworks for UCITS funds create parallel compliance architecture for cross-border offerings. Stakeholders must monitor central bank rate trajectories and covenant-lite issuance volumes as early indicators of cycle turning points.
Market Dynamics
The SEC's Rule 22e-4 liquidity classification mandate is forcing fund managers to restructure portfolio construction, compressing holdings into four liquidity buckets and elevating cash reserve requirements. This regulatory pressure is reshaping how institutional capital accesses below-investment-grade credit exposure.
Growth Catalysts
- Institutional Pension Reallocation:US public pension funds are expanding alternative credit sleeves to meet yield targets absent from traditional fixed-income portfolios.
- Rule 22e-4 Compliance Infrastructure:The SEC's liquidity risk management framework is standardizing classification methodologies across registered investment companies.
- Collateralized Loan Obligation Market Deepening:CLO equity tranche demand is absorbing leveraged loan supply that previously strained high-yield bond issuance windows.
Market Restraints
- Secondary Market Liquidity Concentration:Dealer balance sheet capacity remains concentrated among five primary market-makers, amplifying spread volatility during stress periods.
- Covenant-Lite Documentation Proliferation:Weak creditor protections in leveraged loan structures are eroding recovery rates and compressing risk-adjusted returns across the capital structure.
- Central Bank Rate Trajectory Uncertainty:Federal Reserve policy path ambiguity is extending duration risk premia and depressing new issue appetite among rate-sensitive buyers.
Strategic Opportunities
- Fallen-Angel Credit Migration:Investment-grade downgrades into high-yield indices are creating technical buying pressure and mispriced entry points for active managers.
- Private Credit Convergence:Direct lending platforms are converging with liquid credit strategies, enabling hybrid structures that blend illiquid yield with periodic liquidity windows.
- Environmental, Social, and Governance Screening:European UCITS sustainability disclosure requirements are creating differentiated demand for ESG-tilted high-yield portfolios.
Industry Challenges
- Credit Analyst Talent Scarcity:Specialized distressed debt and covenant analysis expertise remains concentrated among aging practitioner cohorts at major asset managers.
- Legacy System Integration Friction:Portfolio management platforms built for equity-centric workflows require costly reconfiguration to handle fixed-income cash flow modeling and liquidity bucketing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Yield Bonds Market |
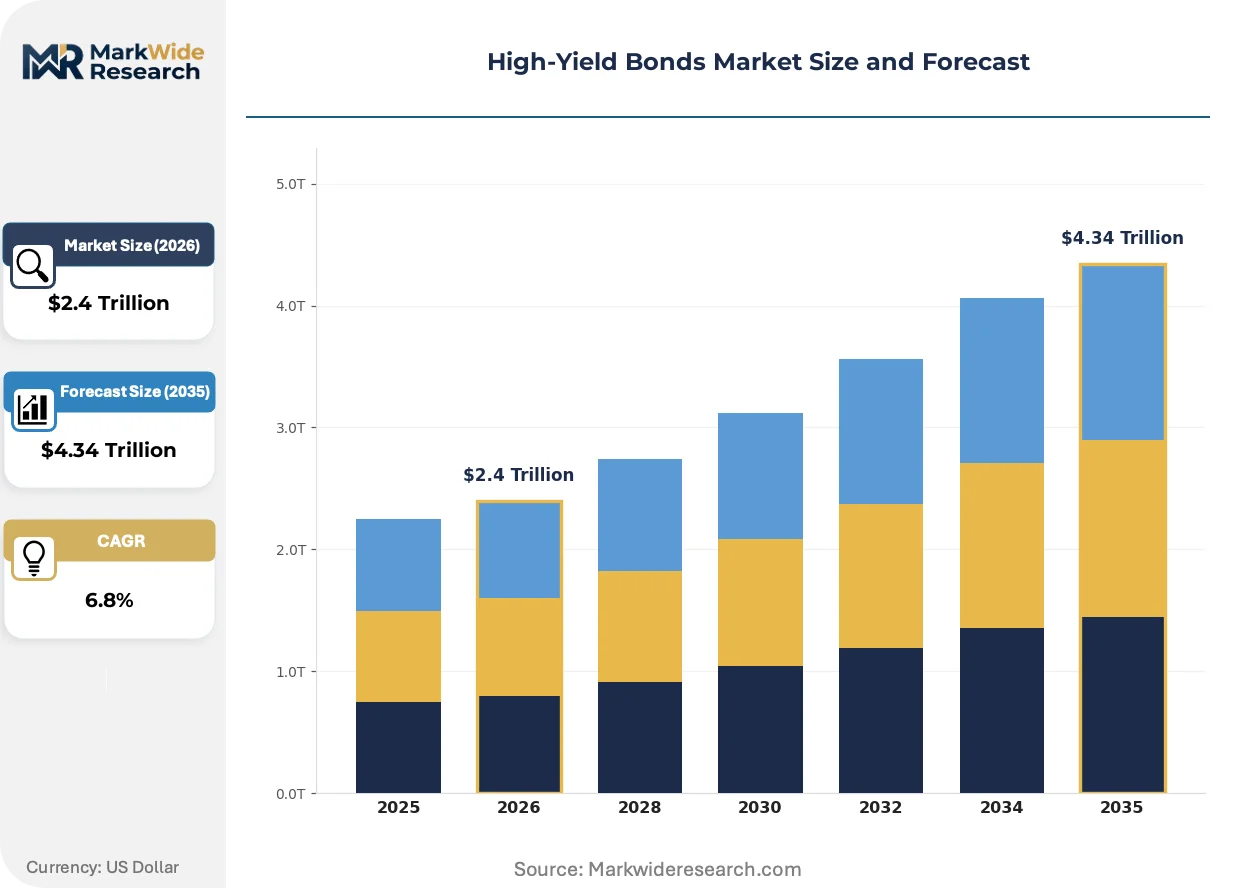
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $4.34 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Corporate Bonds, Convertible Bonds, Municipal Bonds, Distressed Bonds Issuer Type: Private Companies, Non-Profit Entities, Government Units, Special Purpose Vehicles Credit Rating: B rated, CCC rated, CC rated, C rated Market Approach: Active Management, Passive Management, Index Investing, Tactical Strategy |
| Companies Covered | BlackRock, State Street, Invesco, DWS, First Trust, VanEck, JP Morgan, AllianceBernstein, Franklin Templeton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Yield Bonds Market Emerging Trajectories
Artificial intelligence is penetrating credit selection workflows, rewiring how portfolio managers process issuer financials and market signals. Three developments are compressing traditional analytical advantages and redistributing alpha capture across the value chain.
Machine learning models trained on alternative data sources are rewriting the speed and scale of issuer surveillance. Asset managers at BlackRock and JP Morgan are deploying natural language processing on earnings call transcripts and supply chain disclosures to flag deterioration signals months ahead of rating agency actions. This compression of information asymmetry is eroding the edge previously held by specialized credit research boutiques.
The European Securities and Markets Authority's stress-testing frameworks for UCITS funds are mandating parallel liquidity compliance architecture for cross-border offerings. Fund managers must now maintain dual classification systems satisfying both SEC Rule 22e-4 and ESMA liquidity stress scenarios. European-domiciled funds accessing US high-yield markets face the most complex overlay of competing regulatory requirements.
Institutional buyers are unbundling alpha generation from beta exposure through separately managed accounts and custom credit sleeves. Pension funds and insurance company portfolios are demanding direct security selection authority while outsourcing execution and operational infrastructure to platform managers. This disintermediation of commingled fund structures is most visible among US public pension systems with internal credit research capabilities.
High-Yield Bonds Market Segmentation
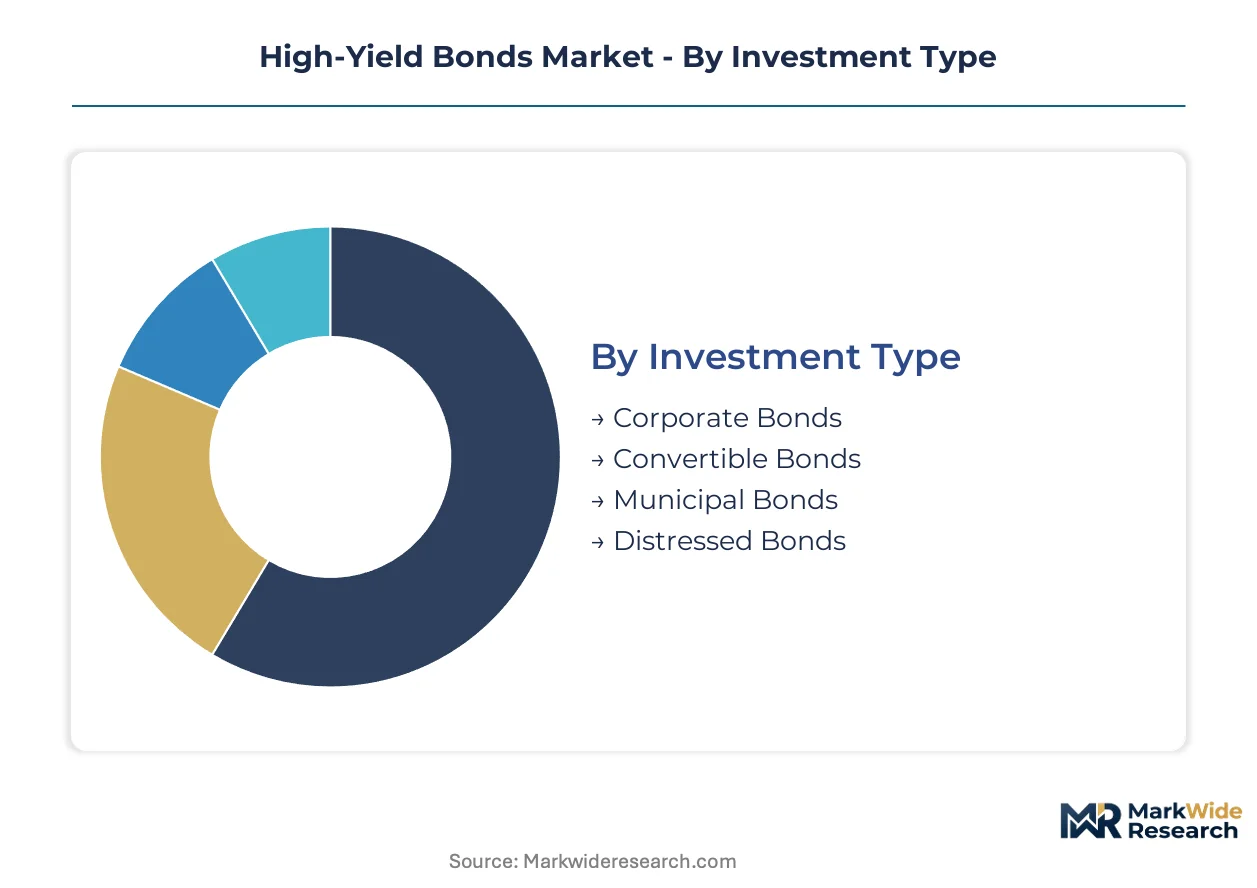
High-yield bond segmentation governs liquidity profiles, regulatory treatment, and investor eligibility across institutional portfolios. Structural distinctions between issuer types and credit tiers determine covenant protections, recovery rates, and secondary market depth.
Investment Type:
Standardized cash-pay instruments dominate institutional mandates while specialized structures serve niche risk-return objectives.
- Corporate Bonds:Unsecured obligations of sub-investment-grade issuers paying fixed coupons with bullet maturities. Demand concentrates among US insurance company general accounts seeking yield pickup over investment-grade corporates, constrained by SEC liquidity bucketing requirements for registered funds.
- Distressed Bonds:Securities trading below 80 cents on the dollar where issuers face imminent default or restructuring. Event-driven hedge funds in Connecticut and London deploy activist strategies to extract value through covenant enforcement or debt-for-equity swaps.
- Convertible Bonds:Hybrid instruments embedding equity conversion options with lower cash coupons.
- Municipal Bonds:Tax-exempt obligations of sub-investment-grade state and local issuers.
Leading the category by volume: Corporate Bonds. Expanding most quickly: Distressed Bonds.
Issuer Type:
Originator sophistication shapes disclosure quality, covenant negotiation leverage, and restructuring complexity.
- Private Companies:Leveraged buyout sponsors and mid-cap operating companies accessing capital for acquisitions, dividends, and refinancings. Sponsor-backed issuers in Texas and California drive new issue calendars, though covenant-lite documentation erodes creditor protections.
- Special Purpose Vehicles:Bankruptcy-remote entities issuing asset-backed securities with ring-fenced collateral pools. CLO warehouses in Delaware and Cayman Islands structure leveraged loan and bond collateral to satisfy rating agency enhancement requirements.
- Government Units:Sovereign and sub-sovereign entities below investment-grade.
- Non-Profit Entities:Hospitals, universities, and cultural institutions with volatile revenue bases.
Private Companies anchor issuance volume. Special Purpose Vehicles gain share fastest through securitization demand.
Credit Rating:
Rating tier determines index eligibility, regulatory capital treatment, and institutional investment mandate compliance.
- B rated:Securities carrying moderate default risk with generally adequate debt service coverage. US pension fund core allocations concentrate here, balancing yield against volatility constraints under ERISA prudent investor standards.
- CCC rated:Speculative obligations with substantial default risk and vulnerable business profiles. Distressed specialists and CLO equity tranche buyers absorb this supply, extracting returns from credit migration or restructuring outcomes.
- CC rated:Highly speculative securities with imminent default probability.
- C rated:Lowest-rated obligations typically in payment default.
B rated securities dominate index composition. CCC rated issuance shows steepest expansion trajectory as fallen-angel migration accelerates.
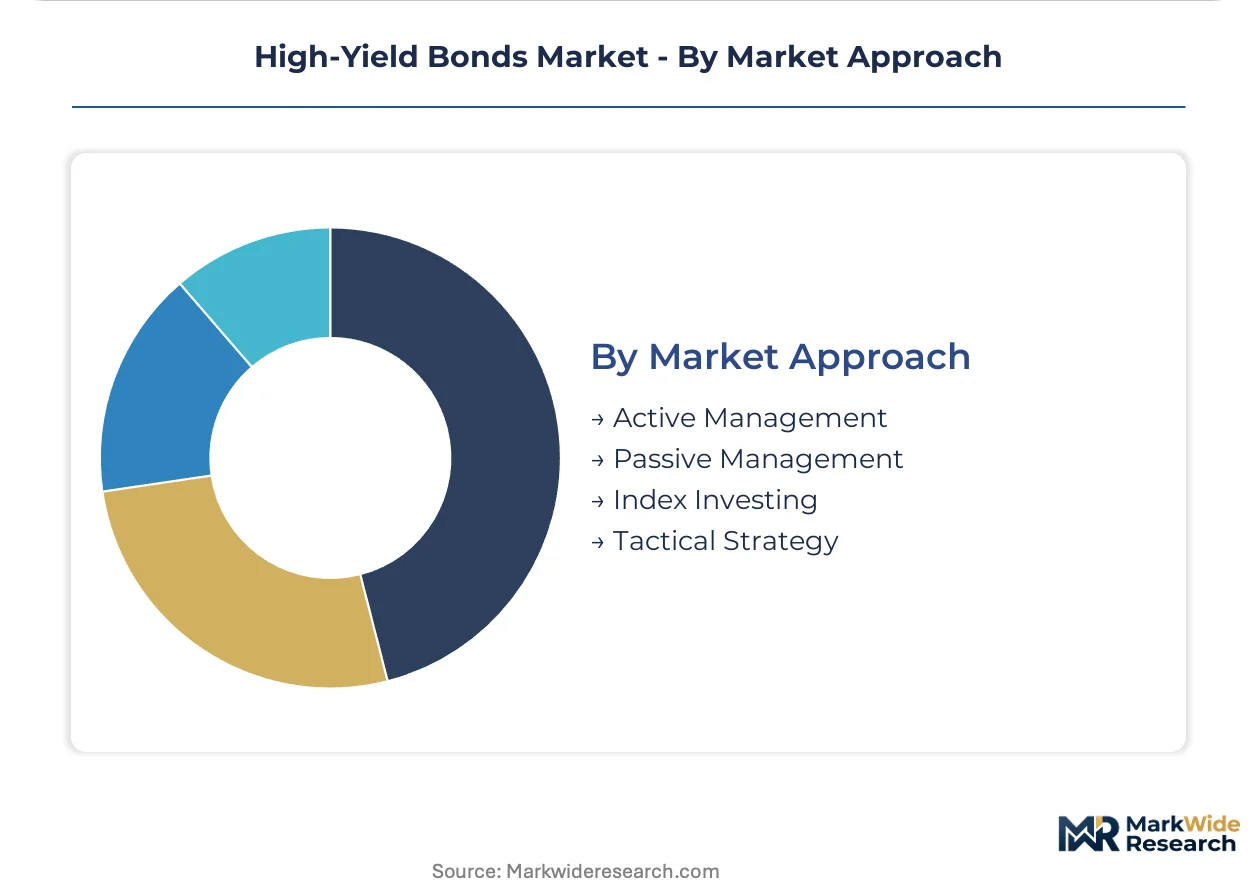
Market Approach:
Fee structures and alpha capture mechanisms diverge sharply across implementation styles.
- Active Management:Discretionary security selection exploiting credit research, relative value, and event-driven positioning. BlackRock and Pacific Investment Management Company deploy fundamental analysts to identify rating migration opportunities ahead of index rebalancing.
- Passive Management:Rules-based replication of high-yield indices with minimal tracking error tolerance. Vanguard and State Street Global Advisors compress fees to basis points, capturing beta exposure for cost-sensitive defined contribution plans.
- Index Investing:Strict benchmark replication without active deviation.
- Tactical Strategy:Duration and credit quality timing based on macro signals.
Passive Management leads by assets under management. Active Management retains pricing power in institutional separate accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary issuance concentrates in the United States while European institutional buyers absorb cross-border supply. Demand fragmentation across regulatory jurisdictions creates arbitrage opportunities for structured credit vehicles.
United States
US public pension funds in California and New York drive institutional allocation to alternative credit sleeves. SEC Rule 22e-4 mandates liquidity bucketing for registered investment companies, elevating compliance costs for fund managers. Dealer balance sheets in New York and Chicago anchor secondary market liquidity provision, though concentration among five primary market-makers amplifies spread volatility.
Germany
Insurance company general accounts in Frankfurt and Munich seek yield pickup through UCITS-eligible high-yield exposure. ESMA stress-testing frameworks for UCITS funds create parallel compliance architecture alongside SEC requirements. Asset managers in the Frankfurt financial cluster structure euro-denominated CLO liabilities to access German institutional capital.
United Kingdom
London-based event-driven hedge funds deploy activist strategies in distressed bond restructurings. The Financial Conduct Authority monitors conduct in wholesale debt markets, complementing EU regulatory oversight for cross-border offerings. The City of London maintains specialized trading desks for fallen-angel credit transitions and covenant-lite loan documentation analysis.
Japan
Japanese institutional investors channel capital into dollar-denominated high-yield through Tokyo-based asset managers. METI guidelines on foreign investment influence portfolio construction for domestic insurers. The Tokyo financial district houses specialized credit research boutiques serving regional bank trust departments.
Switzerland
Swiss private banks in Geneva and Zurich structure high-yield exposure through Luxembourg-domiciled fund vehicles. FINMA liquidity requirements for collective investment schemes add a third regulatory layer for cross-border offerings. The Zurich insurance cluster maintains dedicated credit analyst teams for leveraged loan and distressed debt evaluation.
High-Yield Bonds Market Vendor Landscape
The competitive structure tilts toward scale-driven asset managers with active credit selection capabilities. Consolidation among the top ten players captures the majority of institutional mandate flows, while specialized boutiques retain pricing power in distressed and event-driven niches. Three archetypes dominate: integrated platform managers with CLO structuring capabilities, index replication specialists compressing fees to basis points, and credit research boutiques exploiting information asymmetry. Dominant competitive moves include strategic partnerships between asset managers and dealer balance sheets, plus portfolio diversification into private credit convergence structures.
Within the integrated platform tier, BlackRock leverages scale in active credit selection to anchor CLO equity tranche demand. JP Morgan sustains dealer dominance in secondary market liquidity provision through its balance sheet infrastructure. VanEck competes through specialized ETF vehicles targeting fallen-angel credit transitions, exemplifying the index-replication-with-tilt archetype that has eroded fee structures across retail distribution channels.
| Leading Market Players |
|---|
| BlackRock |
| State Street |
| Invesco |
| DWS |
| First Trust |
| VanEck |
| JP Morgan |
| AllianceBernstein |
| Franklin Templeton |
| Others |
Supply Flow & Price Mechanics
Horizontal integration across dealer balance sheets in New York and Chicago anchors both secondary market liquidity provision and the bid-ask spread pricing power that concentrated market-makers extract during stress periods. This structural choice ties pricing power directly to balance sheet capacity rather than to issuer fundamentals, creating feedback loops where supply scarcity amplifies spread volatility.
Pricing Analysis
Margin tightening in CCC-rated tranches reflects covenant-lite documentation proliferation eroding recovery rate assumptions. Three-tier pricing structure across CLO equity, mezzanine, and senior debt levels segments buyer risk appetite, with institutional pension funds in California and New York showing lowest price sensitivity for B-rated core allocations while event-driven hedge funds in Connecticut demand steepest discounts for distressed paper. Cost-down pressure on retail ETF shares accelerates because Vanguard and State Street fee compression has reset baseline expectations across defined contribution channels.
Supply Chain Analysis
Workforce availability constraints in Delaware and Cayman Islands special purpose vehicle structuring operations limit CLO warehouse expansion velocity. Geographic supply concentrates in the United States, United Kingdom, and Germany, with leveraged loan collateral drawing from Texas and California sponsor-backed issuers and European UCITS distribution feeding from Frankfurt and Luxembourg fund domiciles. Single-source vulnerability to SEC Rule 22e-4 liquidity reclassification creates structural risk for cross-border offerings. Distribution runs through dealer balance sheet intermediation rather than direct issuer-investor matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning credit selection is displacing legacy fundamental analyst workflows, compressing the information asymmetry that previously sustained boutique research premiums.
For Market Incumbents: Anticipate continued fee compression in retail ETF channels as BlackRock and JP Morgan scale NLP-driven surveillance tools. Defensive moves center on anchoring CLO equity tranche demand through balance sheet commitments and building captive distressed debt analyst teams to offset aging practitioner cohort attrition. Vertical integration into private credit convergence structures offers margin protection against liquid credit fee erosion. For New Entrants and Emerging Players: ESMA stress-testing frameworks for UCITS funds in Europe open a window for Luxembourg-domiciled fund administrators specializing in dual SEC-ESMA compliance architecture. White-space targets include fallen-angel transition mandates for mid-size US pension funds and ESG-tilted high-yield sleeves for German insurance general accounts. Go-to-market angle emphasizes outsourced liquidity bucketing infrastructure for asset managers lacking fixed-income workflow reconfiguration capital. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated platform managers seeking CLO structuring capabilities. Long-term viability hinges on sustained institutional pension reallocation to alternative credit sleeves and the depth of secondary market liquidity provision. Acquisition target archetype: credit research boutiques with distressed debt and covenant analysis expertise. Signal to watch: central bank rate trajectory clarity as inflection indicator for new issue appetite recovery.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Credit Surveillance Deployment | BlackRock and JP Morgan NLP models on earnings transcripts compress rating agency information advantage. |
| CLO Equity Tranche Anchoring | Balance sheet commitments from New York dealers stabilize leveraged loan absorption capacity. |
| Dual Regulatory Compliance Infrastructure | Luxembourg fund administrators capture UCITS-SEC overlay demand from cross-border managers. |
| Private Credit Convergence Structuring | Hybrid illiquid-yield vehicles with periodic liquidity windows attract US public pension capital. |
| Fallen-Angel Transition Mandate Targeting | Active managers exploit technical buying pressure from investment-grade downgrade index rebalancing. |
Methodological Framework
Independent corroboration across portfolio managers at BlackRock and AllianceBernstein, CLO structuring specialists in Delaware and Cayman Islands, and SEC regulatory affairs counsel underwrites the qualitative findings in this study. Primary interviews with pension fund investment officers, insurance company credit analysts, dealer balance sheet traders, and UCITS compliance consultants combined with secondary validation from SEC Rule 22e-4 filings, ESMA stress-testing documentation, CLO trustee reports, and Federal Reserve senior loan officer surveys. Bottom-up security-level cash flow modeling and top-down institutional flow analysis provided triangulation.
Rate-of-change decomposition across credit migration velocity, institutional allocation shift magnitude, and regulatory compliance cost escalation shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include investment type, issuer type, credit rating tier, market approach, and regional regulatory cluster. CAGRs derived from historical issuance volume trajectories, institutional mandate growth rates, and cross-asset class yield spread dynamics. Industry-specific forecast inputs incorporated covenant-lite documentation penetration rates and artificial intelligence adoption curves in credit surveillance workflows.
The model assumes a particular technology adoption path; alternative pathways for natural language processing deployment would alter the outlook if regulatory latency or data quality constraints slow implementation. Forecasts reflect assumptions about central bank rate trajectory resolution, pension fund liability-driven investment mandate persistence, and dealer balance sheet capacity stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Europe ETF Market