
 Special Purpose Vehicle Market | 2026-2036
Special Purpose Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Special Purpose Vehicle Market Analytics
Certified commercial vehicle technician availability is collapsing across major manufacturing hubs, forcing OEMs to restructure assembly footprints and training pipelines. Volvo Group leverages its Gothenburg engineering base to sustain integrated chassis-body development for emergency and defense applications. Oshkosh Corporation anchors North American military and airport ground support demand through its Wisconsin manufacturing complex. Rosenbauer International AG specializes in aerial ladder and pumping platform configurations that dominate European fire apparatus procurement.
Special purpose vehicles are commercial automotive products engineered on modified or dedicated chassis architectures, incorporating purpose-built bodies, auxiliary power systems, and mission-specific equipment mounts for functions beyond standard cargo or passenger transport. Construction-grade concrete mixer drums require hardened steel formulations and hydraulic rotation drives rated for continuous duty cycles exceeding eight hours. Emergency services applications lead order volumes due to non-discretionary municipal replacement schedules and NFPA equipment life mandates. Electric fuel type variants are expanding fastest where total cost of ownership calculations incorporate carbon credit monetization and low-emission zone access privileges. Diesel configurations retain margin density in heavy-duty off-road construction and military segments where charging infrastructure remains undeveloped.
FAA certification requirements govern airport rescue and firefighting vehicle performance standards, while EPA Phase 3 rules constrain powertrain emissions across vocational weight classes. NFPA 1901 and NFPA 1906 establish minimum pump flow rates, aerial reach capabilities, and stability testing protocols that structure product development investments for North American fire apparatus manufacturers. ECHA REACH chemical restrictions and EU F-Gas Regulation phase-down schedules are reshaping foam suppression system formulations and refrigerant selections in European-built units. Stakeholders must monitor evolving battery thermal management standards and determine chassis electrification timing against residual value risk in vocational asset pools.
Market Dynamics
Electrification of chassis architectures is compressing development cycles while fragmenting supplier ecosystems, as battery thermal management requirements collide with legacy body-builder integration protocols established over decades of diesel-dominant production.
Growth Catalysts
- EPA Phase 3 Standards:Stringent greenhouse gas mandates for vocational weight classes are forcing fleet operators to accelerate zero-emission procurement timelines.
- NFPA Equipment Life Mandates:Non-discretionary replacement schedules for fire apparatus create predictable order flow regardless of economic cycles.
- Municipal Fleet Electrification:German cities are bundling ambulance and refuse truck conversions into consolidated decarbonization tenders.
Market Restraints
- Battery Cell Supply Concentration:Asian cathode material processing bottlenecks constrain European OEM production ramp rates.
- Charging Infrastructure Gaps:Rural construction and military operating zones lack high-power depot charging, preserving diesel dependence.
- REACH Chemical Restrictions:ECHA foam suppression formulation rules are forcing reformulation of legacy firefighting agent chemistries.
Strategic Opportunities
- Airport Ground Support Electrification:FAA-certified electric ARFF vehicle categories remain underdeveloped relative to apron equipment.
- EU Green Deal Transport Decarbonization:Dedicated funding streams for municipal fleet conversion create captive demand pools.
- Modular Battery Swapping:Standardized pack interfaces would enable 24-hour continuous duty cycles for emergency services.
Industry Challenges
- Certified Technician Scarcity:High-voltage chassis diagnostics training pipelines have collapsed across major manufacturing hubs.
- Dual-Certification Complexity:Simultaneous EPA powertrain and NFPA apparatus compliance extends validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Purpose Vehicle Market |
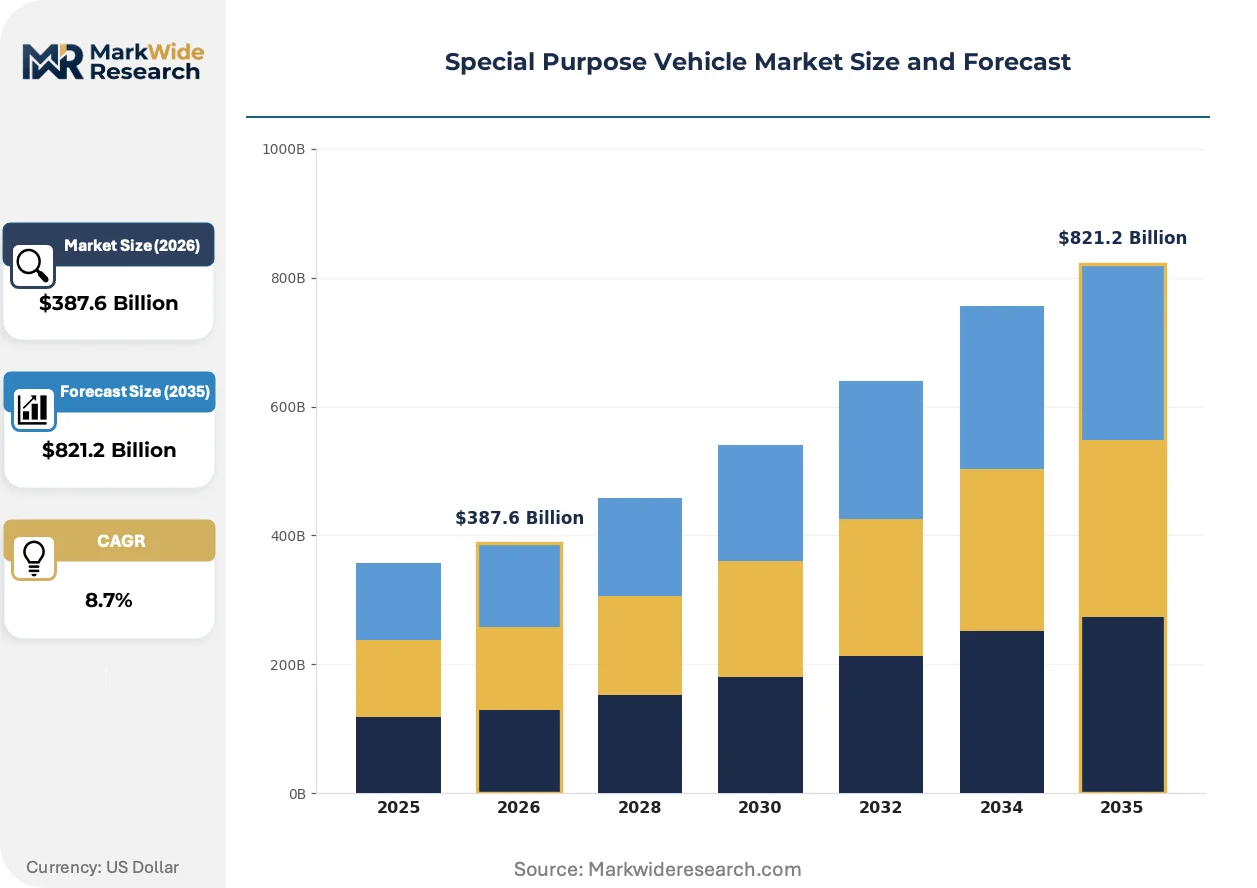
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Bus, Scooter, Trailer, Trolley Application: Construction, Military, Emergency Services, Entertainment Fuel Type: Electric, Diesel, Gasoline, Hybrid End User: Aerospace, Retail, Agriculture, Utilities |
| Companies Covered | Volvo Group, General Motors, REV Group, Iveco Group N.V., Rosenbauer International AG, Oshkosh Corporation, Shyft Group, Force Motors Ltd., Daimler Truck AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Purpose Vehicle Market Evolving Landscape
Powertrain architecture decisions are now decoupling from body fabrication timelines, enabling parallel development streams that compress total program duration while introducing new interface standardization requirements.
Silicon carbide inverter modules are replacing silicon IGBTs in heavy-duty electric drivetrains, cutting switching losses and enabling higher motor speeds. Municipal bus and refuse truck operators in California are specifying SiC-based systems for routes exceeding 150 miles daily. The technology is bifurcating procurement specifications between premium efficiency tiers and cost-optimized legacy architectures.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions in mobile climate control and battery thermal management systems. European fire apparatus OEMs are redesigning HVAC circuits to accommodate lower-GWP alternatives before 2027 compliance deadlines. Aerial platform and pumping configurations face the most severe packaging constraints from larger heat exchanger requirements.
Lifecycle service contracting is displacing transactional parts-and-labor arrangements for municipal fleet operators. Integrated telematics platforms enable predictive maintenance scheduling that unbundles traditional dealer service networks. German and Dutch municipal procurement authorities are piloting ten-year total cost of ownership models that internalize residual value risk with OEMs.
Special Purpose Vehicle Market Segmentation
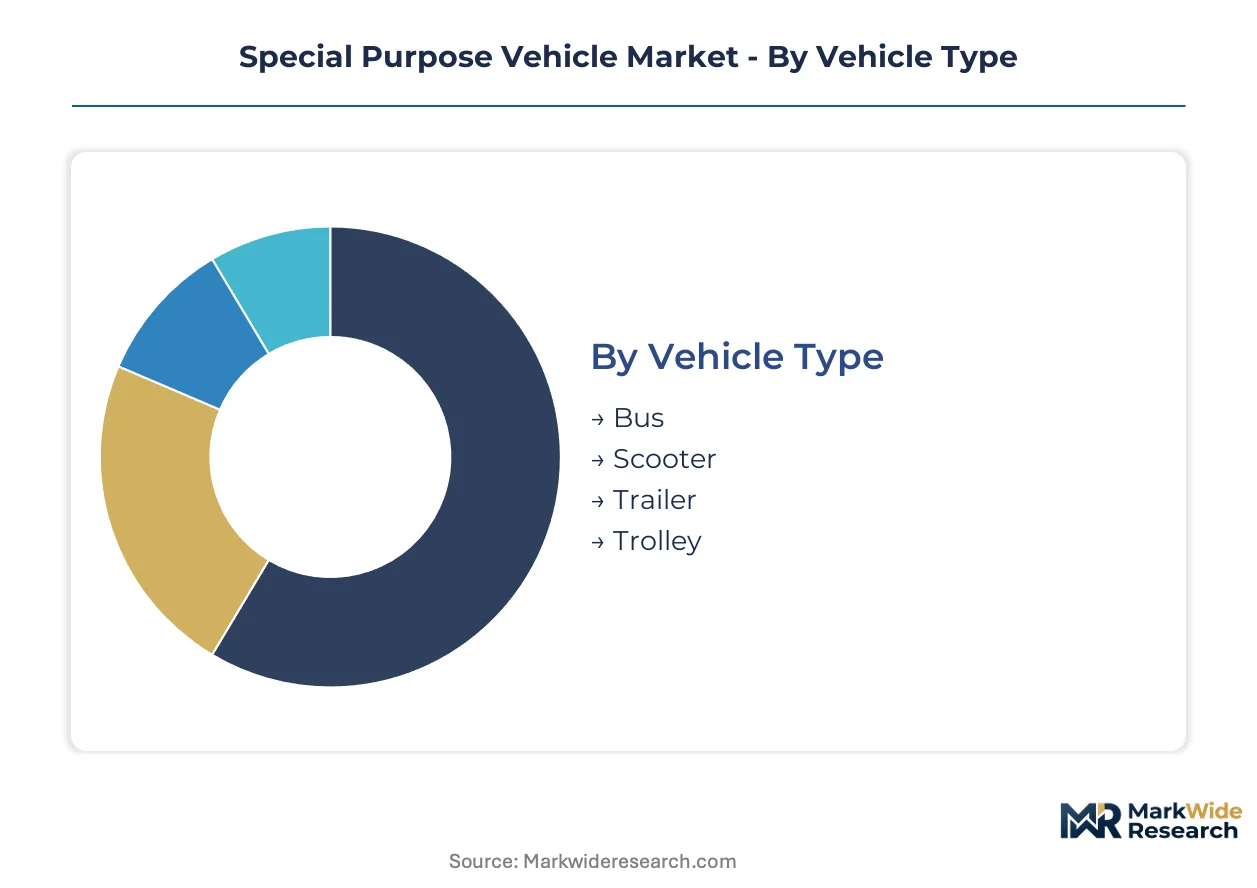
Segmentation in special purpose vehicles reveals how chassis electrification, mission-specific body fabrication, and regulatory compliance requirements fragment procurement patterns across vocational fleets. Understanding these dimensions exposes where substitution pressures from adjacent vehicle categories threaten incumbent suppliers.
Vehicle Type:
Bus and trailer configurations face the most acute substitution threat from standardized commercial platforms, while trolley and scooter variants retain structural differentiation through dedicated infrastructure dependencies.
- Bus:Low-floor and articulated configurations dominate municipal transit electrification tenders, with battery thermal management systems integrated into floor pans. German cities are bundling bus procurement with charging depot infrastructure, compressing supplier margins through consolidated tendering.
- Trailer:Refrigerated and curtain-sided variants incorporate telematics-enabled cargo monitoring for pharmaceutical and perishable supply chains. Dutch logistics operators are specifying trailer-mounted battery packs for electric tractor compatibility, extending range without chassis modification.
- Scooter:Last-mile delivery fleets in dense urban cores favor compact electric scooters for parking efficiency and low-emission zone compliance.
- Trolley:Overhead catenary dependence limits deployment to fixed-route applications with established electrical infrastructure, preserving niche procurement.
Bus retains volume leadership; scooter holds the steepest expansion curve.
Application:
Cost tier stratification separates emergency services from construction and military segments, with entertainment applications occupying a volatile mid-tier dependent on capital expenditure cycles.
- Emergency Services:Fire apparatus and ambulance configurations must satisfy NFPA pump flow and aerial reach mandates alongside EPA powertrain emissions rules. Municipal replacement schedules create non-discretionary demand regardless of economic cycles.
- Construction:Concrete mixer and dump body variants require hardened steel formulations and hydraulic drives rated for continuous duty cycles exceeding eight hours. Diesel configurations retain margin density where charging infrastructure remains undeveloped.
- Military:Tactical wheeled vehicles prioritize mobility and survivability specifications over fuel efficiency, preserving diesel dependence in expeditionary operating zones.
- Entertainment:Mobile stage and broadcast unit configurations face discretionary procurement patterns tied to event industry capital cycles.
Emergency services command the premium pricing tier; construction absorbs the highest absolute unit volumes.
Fuel Type:
Application geography determines fuel type viability, with urban low-emission zones accelerating electric penetration and rural operating environments preserving liquid fuel dependence.
- Electric:Battery-electric chassis architectures are expanding fastest where total cost of ownership calculations incorporate carbon credit monetization and zone access privileges. Silicon carbide inverter modules are replacing silicon IGBTs in heavy-duty drivetrains for routes exceeding 150 miles daily.
- Diesel:Compression-ignition engines retain dominance in heavy-duty off-road construction and military segments where depot charging infrastructure is absent. EPA Phase 3 standards are forcing exhaust aftertreatment complexity that erodes residual value.
- Gasoline:Spark-ignition configurations persist in light-duty emergency services and entertainment applications where payload requirements permit lower power density.
- Hybrid:Parallel and series-hybrid architectures serve as transitional platforms for operators hedging against charging infrastructure uncertainty.
Diesel retains installed base dominance; electric is climbing the fastest on new order intake.
End User:
Customer procurement sophistication separates aerospace and utilities from agriculture and retail, with regulated industries demanding integrated lifecycle service contracts.
- Aerospace:Airport rescue and firefighting vehicles must satisfy FAA certification requirements for acceleration, gradient, and water/foam discharge rates. Electric ARFF categories remain underdeveloped relative to apron ground support equipment.
- Utilities:Bucket truck and digger derrick configurations for electrical grid maintenance require insulated boom ratings and hydraulic tool circuits. Lifecycle service contracting is displacing transactional parts arrangements.
- Agriculture:Seasonal utilization patterns favor diesel configurations with proven field service networks over electrification experiments.
- Retail:Mobile retail and promotional vehicle procurement tracks consumer discretionary spending with minimal technical specification rigor.
Utilities anchor the most predictable replacement demand; aerospace concentrates the highest unit value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering clusters while North American procurement cycles favor volume-driven suppliers. Municipal electrification mandates in Stuttgart and Mannheim create captive demand pools for custom chassis-body integration. Asian manufacturing hubs compete on unit economics but lack the certification depth for premium emergency apparatus.
United States
Airport rescue and firefighting procurement anchors high-value order flow under FAA certification requirements. EPA Phase 3 standards compress powertrain development timelines for vocational weight classes. Oshkosh Corporation's Wisconsin manufacturing complex dominates military and airport ground support segments.
Germany
Baden-Württemberg's specialized vehicle engineering clusters concentrate order flow for custom body-on-chassis applications. EU Green Deal transport decarbonization mandates accelerate municipal fleet electrification programs. Stuttgart-based engineering centers sustain integrated chassis-body development for emergency services.
China
MIIT dual carbon goals reshape domestic procurement specifications for municipal and construction fleets. GB standards govern battery thermal management in heavy-duty electric chassis architectures. Yangtze River Delta manufacturing bases scale silicon carbide inverter production for 150-mile daily route applications.
Japan
METI industrial policy directs battery supply chain localization for vocational electrification. JIS standards structure fire apparatus stability testing protocols alongside NFPA-equivalent benchmarks. Kanto region engineering centers develop modular battery swapping interfaces for continuous emergency duty cycles.
India
PLI scheme incentives attract chassis electrification investment for municipal bus and refuse truck segments. BIS certification requirements govern auxiliary power system integration in tropical operating conditions. Maharashtra and Gujarat industrial corridors concentrate body-builder fabrication capacity for cost-optimized configurations.
Special Purpose Vehicle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with European engineering specialists commanding premium positioning against Asian volume manufacturers. The vendor base separates into three tiers: integrated chassis-body developers, dedicated body fabricators, and regional assembly specialists. Archetypes include engineering-intensive specialists with proprietary aerial platform designs, diversified automotive groups leveraging shared powertrain architectures, and contract manufacturers serving price-sensitive municipal tenders. Competitive moves center on strategic partnerships for battery cell supply security and geographic expansion into electrification-mandate jurisdictions.
Within the integrated chassis-body tier, Volvo Group and Rosenbauer International AG exemplify divergent specialization strategies. Gothenburg-based Volvo Group leverages captive powertrain development for emergency and defense applications requiring chassis-body co-design. Rosenbauer International AG, an Austrian AG-structured specialist, occupies the premium fire apparatus segment through aerial ladder and pumping platform configurations. Oshkosh Corporation anchors North American military and airport ground support demand through its Wisconsin manufacturing footprint, representing the defense-aerospace convergence archetype.
| Leading Market Players |
|---|
| Volvo Group |
| General Motors |
| REV Group |
| Iveco Group N.V. |
| Rosenbauer International AG |
| Oshkosh Corporation |
| Shyft Group |
| Force Motors Ltd. |
| Daimler Truck AG |
| Others |
Value Network & Pricing Analysis
Chassis-body integration lead times stretching 14-18 months for custom emergency apparatus concentrate pricing power with German and Swedish engineering clusters capable of parallel development streams, while Asian volume manufacturers compete on unit economics through standardized platform derivatives.
Pricing Analysis
German-built aerial ladder platforms command 35-45% premiums over Polish-assembled equivalents due to NFPA 1901 certification depth and integrated lifecycle service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Stuttgart-engineered integrated chassis-body systems from Czech body-builder fabrications and Chinese knock-down kit assemblies. Cost compression in the standard tier is intensifying because municipal procurement authorities are consolidating tenders across ambulance and refuse truck categories. Retail and promotional vehicle buyers exhibit highest price sensitivity; airport rescue and firefighting operators show lowest sensitivity due to FAA certification non-negotiability.
Supply Chain Analysis
Steel inventory cycles averaging 90-120 days for hardened drum formulations expose concrete mixer manufacturers to commodity volatility that chassis OEMs hedge through captive foundry relationships. Battery cell supply concentrates in China, South Korea, and Japan, with cathode material processing bottlenecks constraining European OEM production ramp rates. Silicon carbide wafers, high-voltage inverters, and hardened hydraulic drives constitute critical component dependencies. Single-source vulnerability in Asian cathode processing creates procurement risk for European electrification timelines. Distribution runs through municipal tendering authorities, defense procurement offices, and commercial fleet lessors rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where NFPA equipment life mandates and EPA Phase 3 compliance timelines create structural barriers to displacement regardless of economic cycles.
For Market Incumbents: Consolidate chassis-body integration capabilities through captive engineering centers in Baden-Württemberg and Gothenburg to defend against Asian platform standardization threats. Deepen backward integration into battery thermal management systems to capture margin erosion from silicon carbide inverter commoditization. Prioritize dual-certification capacity for simultaneous EPA powertrain and NFPA apparatus validation.
For New Entrants and Emerging Players: Anchor in underdeveloped electric airport rescue and firefighting categories where FAA certification gaps persist against established diesel incumbents. Target Dutch and German municipal fleet electrification tenders bundling ambulance and refuse truck conversions. Pursue modular battery swapping interfaces as a go-to-market wedge for 24-hour emergency duty cycle applications.
For Investors and Strategic Acquirers: Long-term, this sits as a replacement-demand annuity play because non-discretionary municipal replacement schedules and carbon credit monetization create predictable cash flow visibility. Acquisition focus should center on mid-cap body fabricators with NFPA 1901 certification depth and established municipal service networks. Monitor battery cell supply contract renegotiation cycles as inflection signals for margin compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode material allocation from Korean suppliers for European chassis electrification programs. |
| Platform Standardization | Enables parallel chassis-body development streams that compress NFPA validation timelines. |
| Charging Infrastructure Partnership | Addresses rural depot gaps preserving diesel dependence in construction and military segments. |
| Software-Defined Vehicle Investment | Supports predictive maintenance telematics displacing traditional dealer service networks. |
| Geographic Manufacturing Footprint | Locates assembly near Stuttgart engineering clusters for EU Green Deal tender access. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and municipal procurement database records anchors the qualitative findings in observable tender patterns. Primary interviews with chassis development directors, body-builder procurement leads, municipal fleet managers, and FAA certification engineers combined with secondary validation through EPA Phase 3 regulatory filings, NFPA equipment replacement databases, and EU Green Deal funding disbursement records. Bottom-up unit shipment tallies triangulate against top-down addressable fleet calculations across the analysis window.
Sensitivity analysis around battery cost decline curves and charging infrastructure deployment rates tests forecast robustness. Segmentation dimensions span vehicle type, application category, fuel architecture, and end-user industry, with additional modeling of certification tier and lifecycle service bundling. CAGRs derive from regression against historical replacement cycles and regulatory mandate acceleration effects. Key inputs include silicon carbide adoption rates in heavy-duty drivetrains and municipal electrification budget allocations.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Phase 3 enforcement and EU Green Deal transport decarbonization funding continuity; material deviation in battery cell supply concentration or NFPA equipment life mandate amendments would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
US Securities Brokerage Market