
 Stockbroking Market | 2026-2036
Stockbroking Market Size, Share, and Industry Trends Forecast 2026-2036
Stockbroking Market Analysis
EU CSRD disclosure mandates is rebalancing how brokerage platforms report sustainability-linked investment products to retail clients. Charles Schwab leverages its banking-brokerage integration to sustain deposit-funded client acquisition economics. Interactive Brokers anchors its competitive position through global multi-currency account infrastructure and margin lending scale.
Stockbroking encompasses the execution, clearing, and custody of equity, fixed-income, and derivative securities on behalf of clients, typically operating through centralized order management systems with sub-second latency requirements and real-time risk monitoring protocols. The primary commercial purpose is to facilitate capital market access while generating transaction-based revenue and asset-based fees. Full-service brokerage retains concentrated margin pools among high-net-worth relationship managers, while robo-advisors represent the fastest-scaling segment through automated portfolio construction at fractional cost bases. Discount brokerage occupies the volume-intensive core, competing on execution price and platform usability rather than advisory depth.
SEC Regulation Best Interest, FINRA suitability rules, and EU MiFID II conduct standards collectively elevate compliance infrastructure spending while restricting revenue from proprietary product placement. These frameworks reshape demand toward transparent fee structures and documented investment rationales. Stakeholders must monitor evolving fiduciary interpretations across jurisdictions to anticipate product distribution constraints and platform architecture requirements.
Market Dynamics
Commission compression is restructuring revenue architecture across the stockbroking sector, forcing platforms to pivot toward asset-based fees and banking integration to preserve margin profiles.
Growth Catalysts
- SEC Regulation Best Interest:The standard elevates documented advice protocols, creating demand for compliance-integrated platforms that automate rationale capture and fee transparency.
- Mobile-first onboarding infrastructure:Frictionless account opening and fractional share access is pulling first-time retail investors into equity markets at unprecedented velocity.
- Retirement account inflows:Employer-sponsored 401(k) rollovers and IRA consolidations are concentrating custody relationships among integrated brokerage-banking providers.
Market Restraints
- Proprietary trading restrictions:Volcker Rule constraints and EU MiFID II inducement prohibitions eliminate a historical revenue pool for broker-dealers holding inventory positions.
- Clearing concentration:Dependence on DTCC and Euroclear for settlement finality creates systemic vulnerability to operational outages or cyber incidents.
- Interest rate sensitivity:Net interest margin on client cash sweeps compresses when central bank policy rates decline, directly impairing deposit-funded economics.
Strategic Opportunities
- EU CSRD-aligned ESG product shelves:Sustainability disclosure mandates are opening advisory revenue streams through taxonomy-compliant portfolio construction tools.
- Multi-currency margin lending:Cross-border investors seek unified collateral pools across equity, fixed-income, and derivative positions in single-account structures.
- Embedded finance distribution:Neobank and fintech partnerships offer white-labeled brokerage APIs to non-financial platforms with captive user bases.
Industry Challenges
- FINRA licensing throughput:Series 7 and Series 66 examination backlogs constrain registered representative hiring velocity during client acquisition surges.
- Legacy core system interoperability:Mainframe-based custody records resist real-time API integration with modern front-end trading interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stockbroking Market |
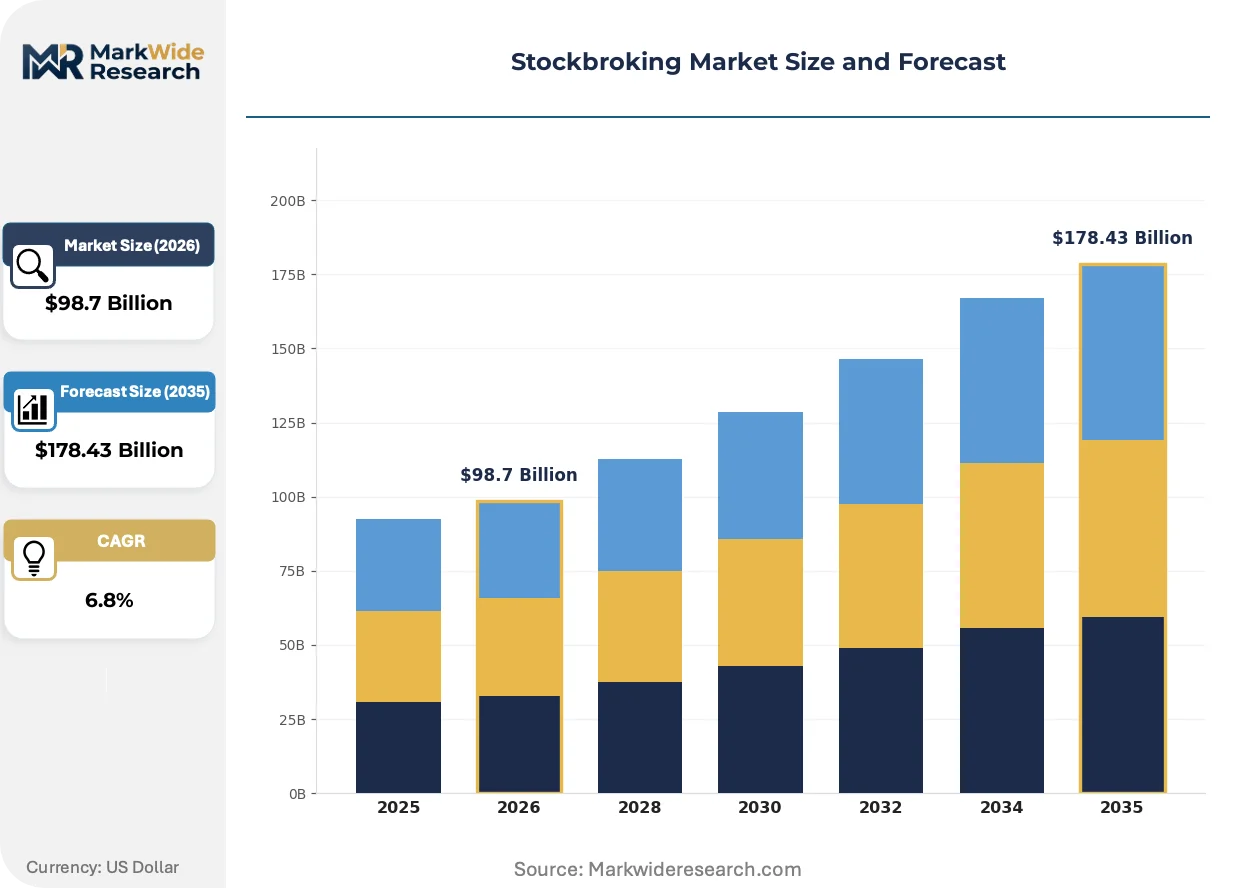
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Brokerage, Discount Brokerage, Robo-Advisors, Online Trading Platforms Client Type: Retail Investors, Institutional Investors, High-Net-Worth Individuals, Corporations Investment Strategy: Value Investing, Growth Investing, Day Trading, Passive Investing Transaction Size: Small Orders, Medium Orders, Large Orders, Institutional Trades |
| Companies Covered | E*TRADE, Robinhood, Charles Schwab, Webull, Merrill Edge, Fidelity Investments, Vanguard, Ally Invest, Interactive Brokers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stockbroking Market Emerging Trajectories
Algorithmic execution infrastructure is compressing latency thresholds while regulatory technology spend redirects engineering resources away from proprietary product development.
Artificial intelligence-driven order routing is consolidating market fragmentation by intelligently parsing liquidity across dark pools, lit exchanges, and internalization engines. Institutional desks at asset managers and hedge funds are adopting these systems to minimize market impact on large-block transactions. The technology is consolidating the competitive advantage of broker-dealers with superior data infrastructure over those relying on static smart-order-routing configurations.
EU MiFID II best execution reporting obligations are mandating granular transaction cost analysis and venue performance disclosure. Asset managers must now document routing decisions and demonstrate price improvement relative to benchmark quotes. European-domiciled funds are responding by consolidating broker relationships toward providers with transparent TCA dashboards and independent transaction reporting.
Self-directed investors are migrating toward unified financial dashboards that aggregate brokerage, banking, credit, and tax-optimized accounts within single interfaces. Traditional standalone trading platforms are losing engagement to integrated wealth management portals offered by deposit-rich institutions. This behavioral pivot is most pronounced in the United States, where Charles Schwab and Fidelity have conditioned users to expect seamless cash management alongside securities execution.
Stockbroking Market Segmentation
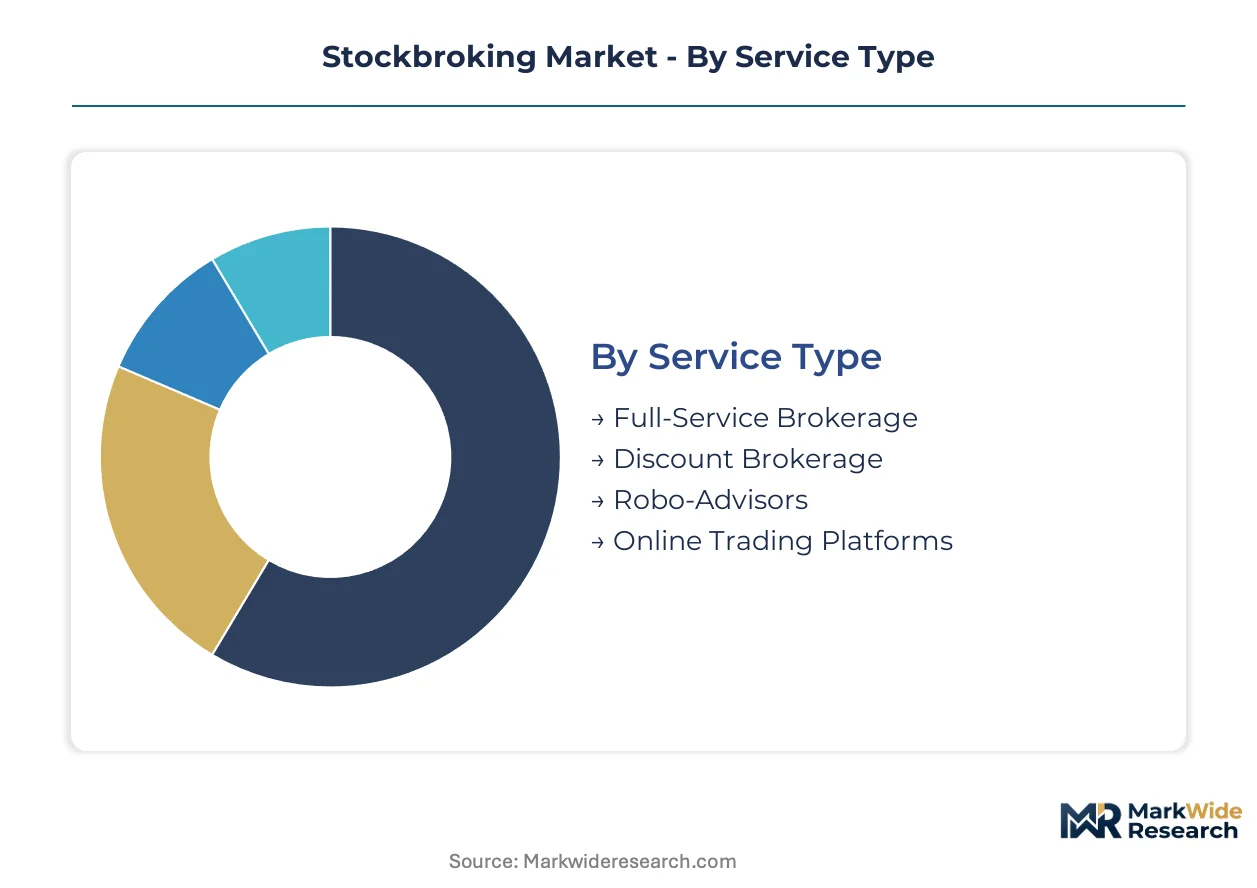
Stockbroking platforms architect their service tiers around client sophistication and transaction economics rather than uniform product distribution. Segmentation determines clearing infrastructure requirements, regulatory licensing obligations, and margin lending protocols. Each category reflects distinct operational cost structures and compliance footprints.
Service Type:
Supply concentration in custody and clearing infrastructure favors platforms with integrated banking arms and proprietary technology stacks over standalone execution venues.
- Full-Service Brokerage:Relationship-driven advisory models combine securities execution with tax planning, estate structuring, and dedicated representative access. Demand clusters among high-net-worth households in the United States seeking consolidated wealth management, constrained by FINRA licensing throughput for registered representatives.
- Discount Brokerage:Commission-free execution platforms monetize through payment for order flow and cash sweep interest spreads. Volume concentration in the United States reflects mobile-first onboarding infrastructure pulling first-time retail investors at unprecedented velocity.
- Robo-Advisors:Algorithmic portfolio construction at fractional advisory fees.
- Online Trading Platforms:Self-directed execution interfaces with real-time market data and options chains.
Today's leader: Discount Brokerage. Tomorrow's challenger: Robo-Advisors.
Client Type:
Cost tier stratification separates bespoke advisory relationships from automated, low-touch account structures with minimal human intervention.
- Retail Investors:Self-directed individuals executing trades through mobile applications and web portals. Demand is expanding fastest in the United States as fractional share access and commission compression democratize market participation.
- Institutional Investors:Asset managers and hedge funds requiring algorithmic execution infrastructure and transaction cost analysis reporting. Regulatory mandates from SEC and EU MiFID II best execution obligations are consolidating broker relationships toward providers with transparent TCA dashboards.
- High-Net-Worth Individuals:Households with concentrated equity positions requiring margin lending and concentrated risk management.
- Corporations:Treasury departments managing share repurchase programs and employee stock plan administration.
Institutional Investors command premium economics. Retail Investors are climbing the fastest.
Investment Strategy:
Application-specific platform features range from real-time derivatives chains for active traders to automated rebalancing for systematic allocators.
- Value Investing:Fundamental research platforms with screening tools and dividend reinvestment infrastructure. Demand concentrates among retirement account holders in the United States executing 401(k) rollovers and IRA consolidations.
- Growth Investing:Access to IPO allocations and secondary offerings with research coverage.
- Day Trading:Sub-second execution latency and advanced options analytics.
- Passive Investing:Commission-free ETF access and automated dividend reinvestment.
Value Investing anchors custody relationships. Passive Investing is gaining share fastest.
Transaction Size:
Volume thresholds determine routing protocols, with large blocks requiring algorithmic execution to minimize market impact.
- Small Orders:Retail-sized transactions typically internalized or routed to wholesale market makers. Demand concentrates in the United States through mobile-first platforms offering fractional share access.
- Institutional Trades:Large-block transactions requiring smart order routing across dark pools and lit exchanges. AI-driven order routing is consolidating competitive advantage among broker-dealers with superior data infrastructure.
- Medium Orders:Transactions requiring price improvement but not full algorithmic execution.
- Large Orders:Block trades necessitating market impact analysis and venue selection.
Institutional Trades drive margin concentration. Small Orders show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockbroking traces its modern origins to London coffee houses and the Buttonwood Agreement of 1792 in New York, where organized equity trading first institutionalized. Today's market structure reflects that Anglo-American lineage while expanding through regulatory export and technology diffusion.
United States
Employer-sponsored retirement rollovers and IRA consolidations concentrate custody relationships among integrated brokerage-banking providers. SEC Regulation Best Interest mandates documented advice protocols and fee transparency, reshaping broker-dealer conduct obligations. New York and Chicago anchor institutional trading infrastructure, with Jersey City hosting critical clearing and custody operations.
Germany
Retail participation in equity markets accelerates through neobank-integrated brokerage APIs and commission-free mobile platforms. BaFin supervision enforces MiFID II best execution standards and inducement prohibitions, elevating compliance infrastructure requirements. Frankfurt's trading infrastructure supports both Xetra electronic execution and Eurex derivatives clearing for cross-border institutional flows.
United Kingdom
Self-directed investors migrate toward unified financial dashboards aggregating brokerage, banking, and tax-optimized accounts. FCA conduct rules and consumer duty standards mandate fair value assessments and vulnerable customer protections. The City of London retains institutional execution concentration, while fintech clusters in Shoreditch and Manchester drive retail platform innovation.
Japan
Household financial asset reallocation from savings deposits toward equity investment sustains platform expansion. FSA stewardship codes and corporate governance reforms pressure asset managers toward active ownership and transparent proxy voting. Tokyo's Kabutocho district anchors securities firm headquarters, with Osaka supporting regional trading infrastructure and commodity derivatives.
Australia
Superannuation fund inflows and self-managed super fund establishment create persistent demand for execution and custody services. ASIC design and distribution obligations require target market determinations and product intervention powers. Sydney concentrates major bank-owned brokerage operations, while Melbourne supports fintech platform development and retail advisory networks.
Stockbroking Market Vendor Landscape
Premium-margin players sit above commodity-margin players across advisory depth and balance sheet integration. The market exhibits tiered concentration: integrated wealth managers capture high-net-worth relationships through dedicated representatives, while discount platforms compete on execution price and mobile usability. Three archetypes dominate: banking-integrated full-service brokers, technology-native zero-commission platforms, and global multi-currency specialists. Consolidation accelerates through deposit-funded acquisition economics and API-based embedded finance distribution.
Among banking-integrated providers, Charles Schwab and Fidelity Investments exemplify the custody-relationship archetype through deposit-funded client acquisition and retirement account concentration. Interactive Brokers occupies the global specialist tier, serving cross-border investors through unified multi-currency margin infrastructure. Robinhood represents the mobile-native archetype, pulling first-time retail investors through fractional share access and frictionless onboarding.
| Leading Market Players |
|---|
| E*TRADE |
| Robinhood |
| Charles Schwab |
| Webull |
| Merrill Edge |
| Fidelity Investments |
| Vanguard |
| Ally Invest |
| Interactive Brokers |
| Others |
Supply Flow & Price Mechanics
Algorithmic execution infrastructure is compressing latency thresholds while simultaneously elevating fixed-cost requirements for order management systems and co-location facilities. This technology shift concentrates pricing power among platforms with proprietary matching engines and direct market access agreements, while forcing smaller venues toward white-label API distribution or consolidation.
Pricing Analysis
Three-tier pricing structure across premium advisory, standard execution, and economy self-service levels dominates revenue architecture. Price differentiation rests on advisory depth, custody integration, and margin lending scale rather than pure execution quality. Pricing pressure stems from commission compression and payment-for-order-flow scrutiny, with retail investors exhibiting highest price sensitivity while institutional desks prioritize transaction cost analysis transparency over headline rates.
Supply Chain Analysis
FINRA Series 7/66 licensing and SEC net capital requirements create qualification gating that constrains registered representative supply and clearing firm authorization. Technology infrastructure concentrates among United States, United Kingdom, and Germany vendors for order management systems and risk monitoring protocols. Raw material dependencies include co-location data center capacity, sub-second market data feeds, and cybersecurity certification. Single-source vulnerability sits with DTCC and Euroclear for settlement finality. Distribution runs through direct-to-consumer mobile applications, institutional sales desks, and embedded finance API partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by accelerating demand for fiduciary-grade advisory documentation and consolidated wealth management dashboards over transactional execution.
For Market Incumbents: Anticipate regulatory technology spend escalation by automating SEC Regulation Best Interest rationale capture and EU MiFID II best execution reporting. Prioritize backward integration into banking deposits to defend margin profiles against commission compression. Threat concentration sits with mobile-native platforms pulling first-time investors through fractional share access.
For New Entrants and Emerging Players: Begin with white-labeled embedded finance distribution through neobank partnerships targeting EU CSRD-aligned ESG advisory tools. Most penetrable white space sits in multi-currency margin lending for cross-border retail investors underserved by legacy custody networks. Go-to-market angle should emphasize unified collateral pools across equity, fixed-income, and derivative positions.
For Investors and Strategic Acquirers: Valuations sit cheapest among discount brokerage platforms with deposit-funded economics but lagging advisory depth. Long-term viability favors integrated wealth managers with retirement account concentration and proprietary technology stacks. Acquisition target archetype: regional platforms with FINRA licensing infrastructure and scalable custody operations. Signal to watch: employer-sponsored 401(k) rollover velocity as custody relationship concentration indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Automation | SEC and EU MiFID II compliance mandates elevate documented advice protocol spending across advisory platforms. |
| Banking-Brokerage Integration | Deposit-funded client acquisition economics sustain margin profiles amid commission compression pressures. |
| Multi-Currency Margin Infrastructure | Cross-border investors demand unified collateral pools reducing currency conversion friction and capital fragmentation. |
| Embedded Finance API Distribution | Neobank partnerships extend brokerage access to non-financial platforms with captive user bases. |
| ESG Product Shelf Development | EU CSRD taxonomy compliance opens advisory revenue streams through sustainability-linked portfolio construction. |
Methodological Framework
Bottom-up client-type modeling reconciled against top-down clearing volume tracking forms the analytical core of this study. Primary interviews with brokerage platform CTOs, FINRA compliance officers, institutional trading desk heads, and retail investor experience designers combined with secondary validation from SEC 10-K filings, FINRA regulatory notices, DTCC volume reports, and EU ESMA transaction data. Triangulation across these sources ensures segmentation integrity and revenue attribution accuracy.
Input-output matrices map transaction velocity, asset-based fee generation, and net interest margin contributions across service tiers and client segments throughout the forecast period. Segmentation dimensions include service type, client sophistication level, investment strategy orientation, and transaction size threshold. CAGRs derive from regression analysis against retirement account inflow trends, mobile onboarding velocity, and regulatory technology adoption curves.
Several conditions sit outside the modeled scope, including discrete geopolitical events affecting cross-border capital flows, abrupt central bank policy rate shifts altering deposit sweep economics, and systemic clearing infrastructure outages. A model refresh is warranted upon material change in SEC fiduciary rule interpretation or EU inducement prohibition enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market