
 Europe ETF Market | 2026-2036
Europe ETF Market Size, Share, and Industry Trends Forecast 2026-2036
Europe ETF Market Insights
Algorithmic portfolio construction is rewriting how European asset managers assemble multi-asset exposures. iShares leverages its scale in equity index tracking to dominate core beta positioning. Amundi sustains competitive pressure through its Paris-based active quantitative franchise. Xtrackers anchors its presence in Germany with deep liquidity on DAX-linked products.
An exchange-traded fund is a pooled investment vehicle that trades on stock exchanges like individual securities, typically holding a basket of assets with an expense ratio below 0.20% for passive variants and daily portfolio transparency requirements. Its primary commercial purpose is to deliver diversified market exposure with intraday liquidity and tax efficiency. Passive strategies lead by assets under management, though smart beta is capturing margin pools as investors seek factor tilts beyond cap-weighted indices. Institutional distribution channels control the largest flows, while online platforms represent the fastest-growing access point for retail participation.
ESMA oversees product governance and risk disclosure standards, while the EU Green Deal and Sustainable Finance Disclosure Regulation shape demand by mandating ESG transparency across fund documentation. The F-Gas Regulation indirectly affects commodity ETFs tracking carbon-intensive materials. Stakeholders must monitor how the EU AI Act reshapes algorithmic fund management and index construction methodologies.
Market Dynamics
The EU's Sustainable Finance Disclosure Regulation is compressing the competitive window for non-ESG-compliant products while institutional capital rotation accelerates toward transparent, low-cost index vehicles.
Growth Catalysts
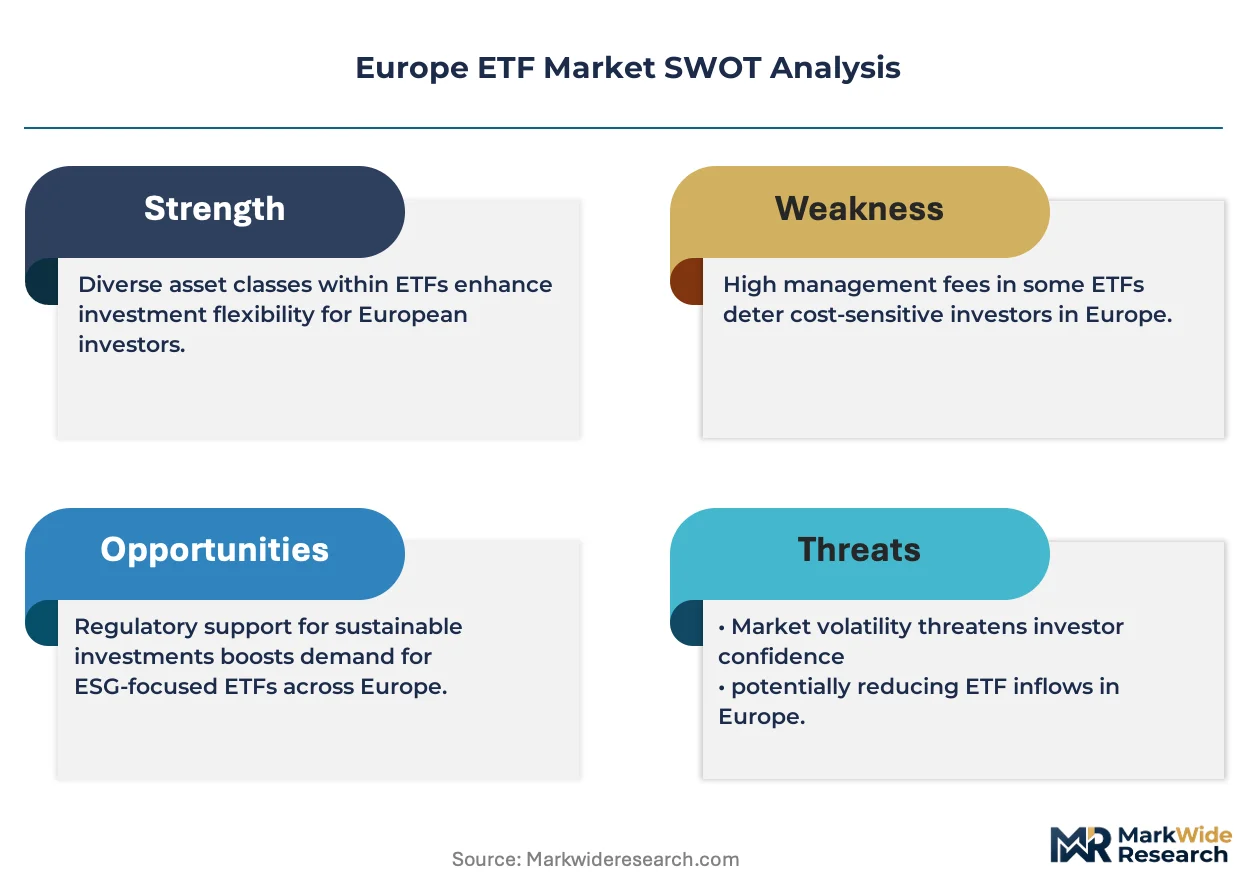
- SFDR Article 8 and 9 frameworks:Mandatory ESG disclosure requirements redirect pension fund mandates toward Article 8-compliant ETFs, creating structural demand for sustainability-labelled products.
- Algorithmic rebalancing engines:Quantitative portfolio construction tools enable real-time factor tilt adjustments, attracting insurer allocations previously held in active mutual funds.
- Netherlands pension consolidation:Mega-funds such as APG and PGGM are streamlining external manager panels, concentrating flows into liquid, low-fee index trackers.
Market Restraints
- Securities lending opacity:Revenue-sharing arrangements between ETF issuers and authorized participants create fee leakage concerns for fiduciary investors scrutinizing total cost of ownership.
- Central counterparty concentration:Euroclear and Clearstream dominate European post-trade infrastructure, creating single-point-of-failure risk during liquidity stress events.
- MiFID II research unbundling:Restrictions on soft dollar arrangements compress distribution economics for smaller asset managers lacking scale to self-fund analyst coverage.
Strategic Opportunities
- Polish and Romanian retail channels:Underdeveloped online brokerage penetration in Eastern European markets offers first-mover positioning for direct-to-investor platform partnerships.
- Carbon futures integration:EU Emissions Trading System exposure products align with corporate net-zero hedging programs and CSRD-mandated climate risk disclosure.
- Tokenized settlement infrastructure:Distributed ledger technology convergence with traditional fund administration promises T+0 creation-redemption cycles and reduced counterparty exposure.
Industry Challenges
- Quantitative risk modeling talent:Shortage of portfolio engineers capable of constructing multi-factor smart beta indices with controlled tracking error budgets.
- SFDR taxonomy alignment verification:Complex sustainable investment definitions require specialized compliance functions to avoid greenwashing litigation exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe ETF Market |
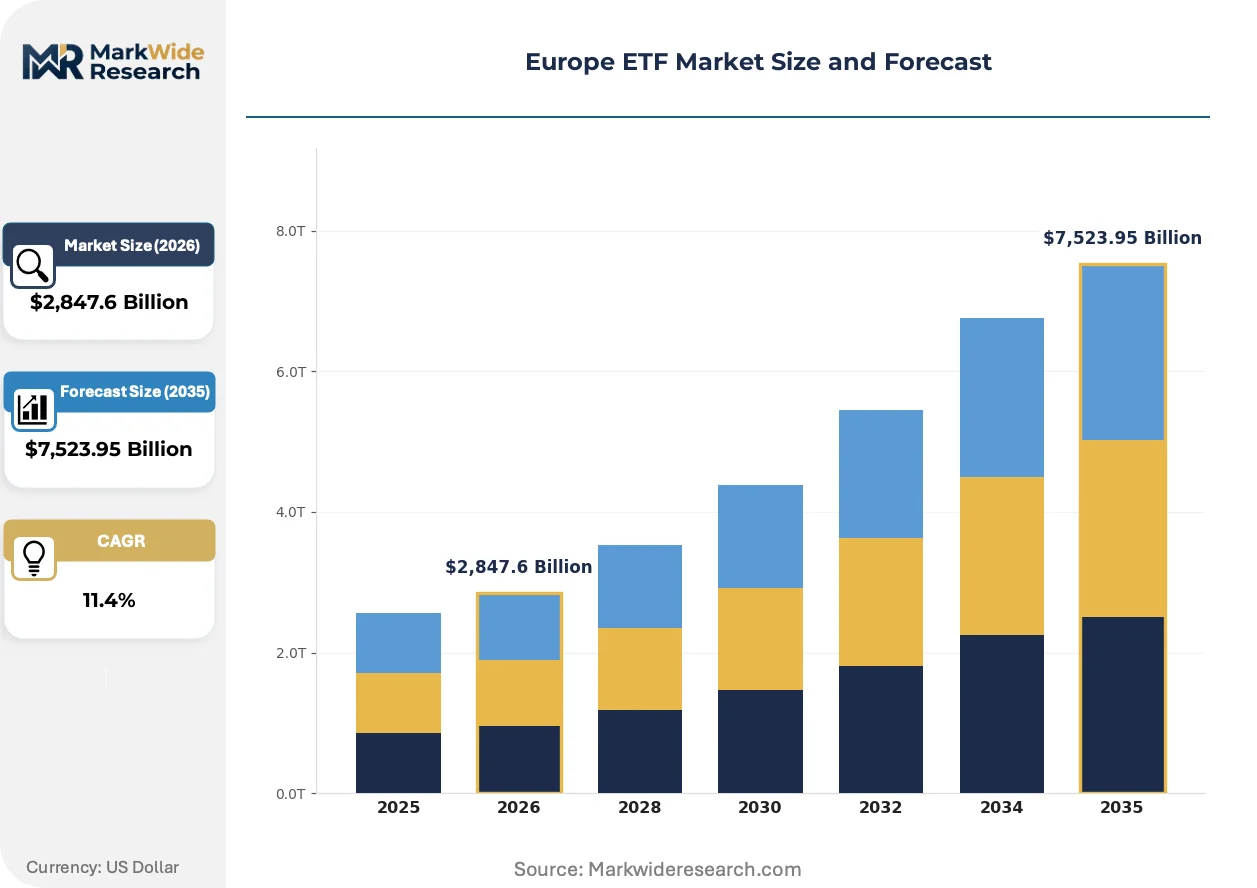
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $7,523.95 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Passive, Active, Smart Beta, Enhanced Indexing Asset Class: Equities, Bonds, Commodities, Real Estate Distribution Channel: Direct Investors, Financial Advisors, Institutional Investors, Online Platforms Fund Size: Small-Cap, Mid-Cap, Large-Cap, Ultra-Large-Cap |
| Companies Covered | iShares, Amundi, Xtrackers, Vanguard, UBS, Invesco, SPDR, HSBC, WisdomTree, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe ETF Market Trends and Innovations
Active ETF wrappers are eroding the passive-active boundary as European regulators clarify permissible portfolio management techniques within exchange-traded structures.
Direct indexing technology is collapsing the minimum threshold for customized portfolio construction. Wealth managers at UBS and Credit Suisse are deploying fractional share engines to replicate index exposures with client-specific exclusions. This capability is compressing demand for off-the-shelf sector ETFs among ultra-high-net-worth segments.
CSRD implementation timelines are tightening ESG data infrastructure requirements. Corporate sustainability reporting obligations now extend to investee companies, forcing index providers to integrate verified Scope 3 emissions estimates. Asset managers in France and Germany are accelerating vendor contracts with climate data specialists to maintain index eligibility.
Consolidation among online brokers is reshaping retail distribution economics. Platforms such as Trade Republic and Scalable Capital are unbundling research and execution, compressing commission revenues available for product placement fees. This channel shift is forcing ETF issuers to prioritize direct marketing and educational content over traditional wholesale relationships.
Europe ETF Market Segmentation
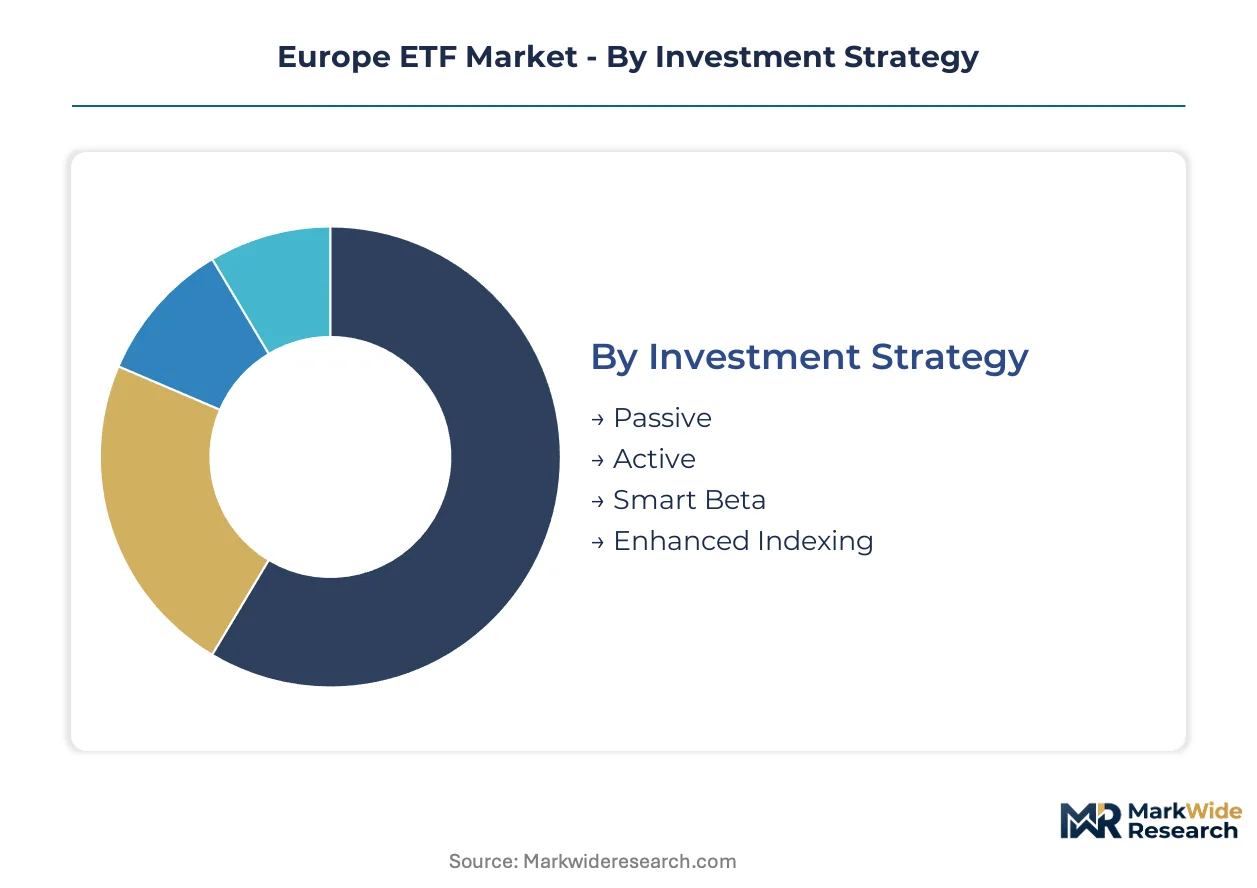
Segmentation in the Europe ETF market reveals how structural shifts in regulation, distribution economics, and investor sophistication are fragmenting demand across multiple dimensions. Understanding these divisions exposes where capital is concentrating and which product architectures command sustainable fee margins.
Investment Strategy:
After-sales service intensity varies sharply across strategy types, with active and smart beta wrappers requiring ongoing factor calibration support while passive vehicles demand minimal post-launch intervention.
- Passive:Cap-weighted index replication with expense ratios typically below 0.20% dominates core institutional allocations. Dutch pension mega-funds APG and PGGM concentrate mandates here for liquid, low-fee beta exposure.
- Active:Discretionary portfolio management within exchange-traded structures permits real-time tactical adjustments. ESMA's clarification of permissible techniques is accelerating insurer adoption previously blocked by fiduciary uncertainty.
- Smart Beta:Factor-tilted indices targeting value, momentum, or quality premia. Demand concentrates among French and German asset managers seeking controlled tracking error budgets.
- Enhanced Indexing:Rules-based optimization around benchmark constraints with modest active risk. The Netherlands and Scandinavian institutions favor this for core-satellite construction.
By volume, Passive leads. By growth pace, Smart Beta is ahead.
Asset Class:
Cost tier differentiation separates institutional-grade fixed income vehicles from retail-accessible equity products, with commodity and real estate wrappers occupying specialized fee bands.
- Equities:Broad market and sector-specific exposures constitute the foundational ETF architecture. German and French distribution channels concentrate flows into DAX and CAC 40 trackers.
- Bonds:Sovereign and corporate credit index replication serves liability-driven investment strategies. Insurers across the Netherlands and Belgium prioritize euro-denominated investment grade vehicles.
- Commodities:Futures-based and physically-backed structures track energy, metals, and agricultural baskets. The F-Gas Regulation indirectly constrains carbon-intensive material exposure products.
- Real Estate:REIT index tracking delivers property market beta without direct asset ownership. French and German institutional investors use these for inflation-sensitive allocation sleeves.
Equities commands the largest asset base, though Bond ETFs are expanding most quickly as rates stabilize.
Distribution Channel:
Customer type fragmentation is concentrating power in institutional gatekeepers while online platforms disintermediate traditional advisory relationships.
- Direct Investors:Self-directed retail participants executing through bank brokerage accounts. Polish and Romanian markets show underdeveloped penetration, offering first-mover positioning.
- Financial Advisors:Independent and bank-affiliated wealth managers constructing model portfolios. MiFID II research unbundling has compressed soft-dollar economics for smaller managers.
- Institutional Investors:Pension funds, insurers, and sovereign wealth vehicles deploying block liquidity. Netherlands consolidation into mega-funds is streamlining external manager panels toward scale players.
- Online Platforms:Mobile-first brokers such as Trade Republic and Scalable Capital unbundling research and execution. Commission compression is forcing issuers toward direct marketing over wholesale placement.
Institutional Investors control the deepest flows. Online Platforms are gaining share fastest.
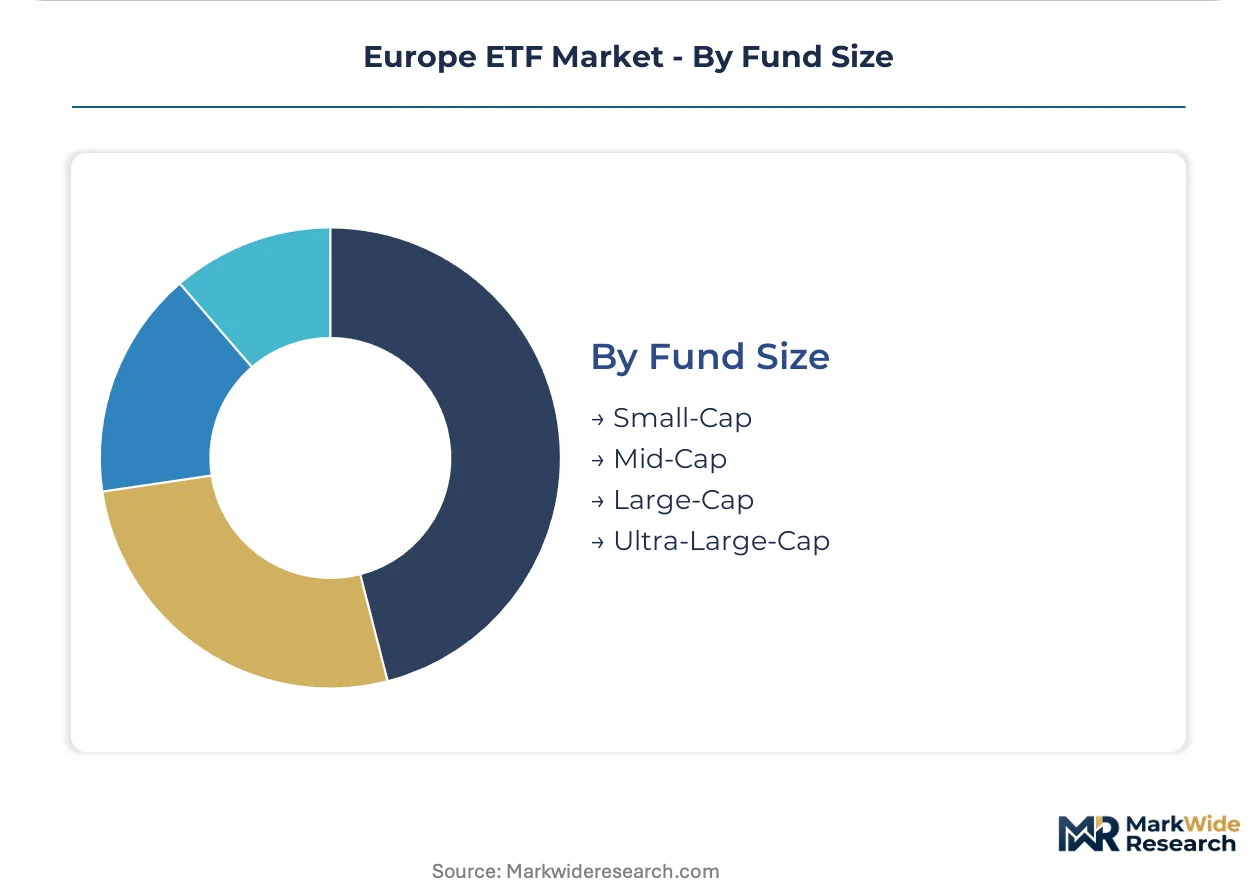
Fund Size:
Maturity stratification separates established liquidity leaders from emerging products struggling to achieve viable creation-redemption economics.
- Small-Cap:Niche exposures and recently launched vehicles below €100 million in assets. Specialist thematic products targeting CSRD-aligned sustainability themes populate this tier.
- Mid-Cap:Established regional or sector funds with sufficient liquidity for institutional consideration. French and German smart beta offerings cluster here.
- Large-Cap:Broad market benchmarks with deep secondary market liquidity and tight bid-ask spreads. Core equity and bond index trackers dominate this category.
- Ultra-Large-Cap:Flagship products exceeding €10 billion with creation-redemption infrastructure serving as market reference points. iShares and Amundi maintain multiple vehicles in this tier.
Ultra-Large-Cap products anchor trading infrastructure. Small-Cap vehicles are climbing the fastest as thematic and ESG-labelled launches multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-domiciled ETF products command substantial cross-border distribution into French and Dutch institutional portfolios, with Luxembourg serving as the primary UCITS structuring hub for pan-European fund passports.
Germany
Asset managers in Frankfurt and Munich are scaling DAX-linked product liquidity to capture insurer rebalancing flows. BaFin's implementation of MiFID II suitability requirements shapes retail distribution compliance costs. The Eurex exchange in Frankfurt anchors derivatives-based hedging activity for institutional ETF positions.
France
Paris-based quantitative teams are engineering smart beta indices for pension fund core-satellite mandates. The Autorité des Marchés Financiers enforces SFDR disclosure standards that filter product shelf access. La Défense financial district houses Amundi's active ETF research infrastructure.
Netherlands
APG and PGGM mega-funds are consolidating external manager panels toward ultra-low-fee index trackers. DNB prudential guidelines influence insurer capital treatment of exchange-traded vehicles. Amsterdam's trading infrastructure supports creation-redemption activity for euro-denominated bond ETFs.
United Kingdom
Post-Brexit regulatory divergence is fragmenting UCITS passporting arrangements for London-based issuers. The Financial Conduct Authority's sustainability disclosure requirements run parallel to EU SFDR frameworks. The City of London retains specialized market-making capacity for sterling-denominated equity products.
Switzerland
Wealth managers in Zurich and Geneva are deploying direct indexing technology that displaces standardized sector ETF demand. FINMA's fintech licensing framework accommodates algorithmic portfolio construction tools. Zürcher Kantonalbank's institutional desk channels cross-border flows into ESG-screened equity trackers.
Europe ETF Market Competitive Landscape
On the supply side, the industry is consolidating around scale-driven index providers with deep authorized participant networks and proprietary data licensing arrangements. Three strategic archetypes dominate: diversified asset managers with multi-asset platform breadth, specialist quantitative houses with factor research depth, and banking-affiliated issuers leveraging captive distribution. Competitive moves center on fee compression through securities lending revenue optimization and strategic partnerships with online brokerage platforms.
Among banking-affiliated issuers, UBS and HSBC occupy positions that exemplify the integration of wealth management distribution with proprietary product manufacturing. iShares represents the scale-driven archetype with creation-redemption infrastructure serving as market reference points across core equity and fixed income categories.
| Leading Market Players |
|---|
| iShares |
| Amundi |
| Xtrackers |
| Vanguard |
| UBS |
| Invesco |
| SPDR |
| HSBC |
| WisdomTree |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in passive equity tracking products across German and French markets is compressing management fee floors while concentrating pricing power among ultra-large-cap issuers with securities lending scale. This utilization dynamic forces smaller asset managers toward active wrappers or thematic niches where differentiation commands premium pricing.
Pricing Analysis
The pricing gap between first-generation cap-weighted trackers, second-generation smart beta factor tilts, and emerging direct-indexing alternatives defines competitive positioning. Three-tier pricing structure across premium active, standard smart beta, and economy passive levels stratifies by liquidity depth and after-sales service intensity. Pricing pressure stems from online brokerage commission compression and unbundled research economics, with Dutch pension mega-funds exhibiting acute fee sensitivity while Swiss private banking clients tolerate premium tiers for customization.
Supply Chain Analysis
Upstream index licensing feeds from concentrated intellectual property holders in the United States and United Kingdom, with S&P Dow Jones and FTSE Russell commanding dominant share. Authorized participant networks, creation-redemption infrastructure, and securities lending programs constitute critical operational inputs. Single-source vulnerability sits with Euroclear and Clearstream's post-trade duopoly, while distribution runs through institutional gatekeepers, independent advisory platforms, and mobile-first retail brokers in varying combinations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Netherlands pension consolidation and online platform aggregation, fragmenting issuer negotiating leverage across channels.
For Market Incumbents: Entrench liquidity leadership in core equity and fixed income benchmarks where creation-reduction infrastructure creates switching costs. Deepen securities lending revenue optimization to offset fee compression, while accelerating SFDR Article 9 product development to preempt regulatory displacement of non-compliant wrappers. For New Entrants and Emerging Players: Pursue underdeveloped retail channels in Poland and Romania where online brokerage penetration lags Western European saturation. Carbon futures-integrated products and tokenized settlement infrastructure represent penetrable white-space segments with limited incumbent positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among quantitative index providers with sticky pension fund mandates and proprietary factor research libraries. Long-term viability favors acquisition targets with demonstrated SFDR compliance infrastructure and direct platform distribution relationships, with the signal to watch being regulatory clarity on active ETF permissible techniques under ESMA guidance.| Strategic Initiative | Industry Significance |
|---|---|
| SFDR Article 9 Product Development | Mandatory ESG disclosure frameworks redirect Dutch and French institutional flows toward sustainability-labelled vehicles. |
| Securities Lending Revenue Optimization | Fee compression in passive tiers demands ancillary income streams from authorized participant arrangements. |
| Direct Platform Distribution Partnerships | Trade Republic and Scalable Capital's commission unbundling forces issuer migration from wholesale to direct marketing. |
| Smart Beta Factor Research Investment | French quantitative teams at Amundi demonstrate sustained margin pools in value and momentum tilt products. |
| Tokenized Settlement Infrastructure Development | Distributed ledger convergence promises T+0 creation-reduction cycles reducing Euroclear counterparty exposure. |
Research Methodology
Cross-validation between regulatory filing analysis and authorized participant network interviews anchors the qualitative findings. Primary fieldwork encompassed portfolio construction officers at Dutch pension mega-funds, quantitative research heads at Paris-based asset managers, distribution strategists at German banking groups, and compliance leads navigating SFDR implementation. Secondary sources included ESMA product governance circulars, ECB statistical warehouse data on fund flows, BaFin and AMF disclosure repositories, and UCITS regulatory databases. Bottom-up demand modeling triangulated against top-down asset allocation surveys.
Calibration against historical flow patterns and expense ratio trajectories informed the projection framework. Segmentation dimensions encompassed investment strategy archetype, underlying asset class, distribution channel structure, and fund size tier across the analysis window. CAGRs derived from regression of institutional mandate growth rates against retail platform adoption curves, with inputs from insurer capital treatment guidelines under DNB and EIOPA prudential frameworks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by fintech platform entrants or regulatory acceleration of tokenized settlement standards would shift outcomes. Cross-checking against ECB investment fund statistics and EFAMA industry reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Middle East and Africa ETF Market