
 North America ETF Market | 2026-2036
North America ETF Market Size, Share, and Industry Trends Forecast 2026-2036
North America ETF Market Insights
US asset manager capacity is hardening around scale infrastructure and distribution reach. BlackRock leverages its iShares platform to dominate equity ETF flows. Vanguard sustains its mutual-to-ETF conversion engine, capturing cost-sensitive retail assets. State Street Global Advisors competes through institutional liquidity provision and custom basket optimization.
An exchange-traded fund is a pooled investment vehicle that trades on stock exchanges with intraday pricing transparency, typically tracking an index through either physical replication or synthetic swap-based structures, and serves primarily as a low-cost, liquid tool for diversified market exposure. Equity ETFs anchor the majority of assets under management, reflecting sustained demand for broad-market beta at minimal expense ratios. Bond ETFs represent the fastest-growing product type as institutional investors seek transparent fixed-income execution alternatives to over-the-counter trading. Institutional platforms command the deepest margin pools within distribution channels, given the concentration of large-ticket flows and associated securities lending revenue.
The SEC governs ETF creation and redemption mechanics through the Investment Company Act of 1940 and modernized exemptive relief frameworks, while FINRA oversees sales practice standards and suitability requirements for broker-distributed products. The IRS shapes demand through tax treatment distinctions between in-kind redemption mechanisms and traditional mutual fund capital gains distributions. Stakeholders must monitor how the SEC's ongoing scrutiny of semi-transparent and non-transparent active ETF structures alters the competitive boundary between mutual funds and exchange-traded products.
Market Dynamics
The SEC's ETF Rule modernization compresses product approval timelines, accelerating the shift from mutual fund wrappers to exchange-traded structures across US and Canadian distribution channels.
Growth Catalysts
- SEC exemptive relief frameworks:Streamlined creation-redemption mechanics reduce time-to-market for novel structures, enabling asset managers to launch active and thematic products faster than traditional 1940 Act registration permits.
- Institutional fixed-income execution:Bond ETFs displace over-the-counter trading for pension funds and insurers seeking transparent, T+1 settlement in US Treasury and investment-grade credit markets.
- Canadian retail brokerage platforms:Commission-free trading expansion at major Canadian banks funnels self-directed investors toward low-cost equity beta products.
Market Restraints
- Swap counterparty concentration:Synthetic replication structures depend on a limited pool of US and European dealer banks, creating single-name exposure during stress periods.
- Tax-loss harvesting complexity:IRS wash-sale rules constrain retail investors from maintaining continuous exposure while realizing losses, complicating year-end portfolio management.
- Authorized participant capacity:Creation unit economics require minimum block sizes that exclude smaller US registered investment advisors from direct primary market access.
Strategic Opportunities
- Defined outcome strategies:Buffered and structured protection ETFs target risk-averse US pre-retirees seeking equity participation with explicit downside limits.
- Environmental attribute indexing:ISSB-aligned disclosure standards enable differentiated products for Canadian institutional mandates subject to OSFI climate risk guidelines.
- Direct indexing-to-ETF conversion:Separately managed account platforms automate tax-loss harvesting at scale, compressing fees below traditional SMA minimums.
Industry Challenges
- Portfolio management system integration:Legacy custody platforms at US broker-dealers require middleware upgrades to handle intraday NAV calculations and custom basket optimization.
- Securities lending operational risk:Revenue-sharing disputes between ETF issuers and lending agents demand enhanced collateral management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America ETF Market |
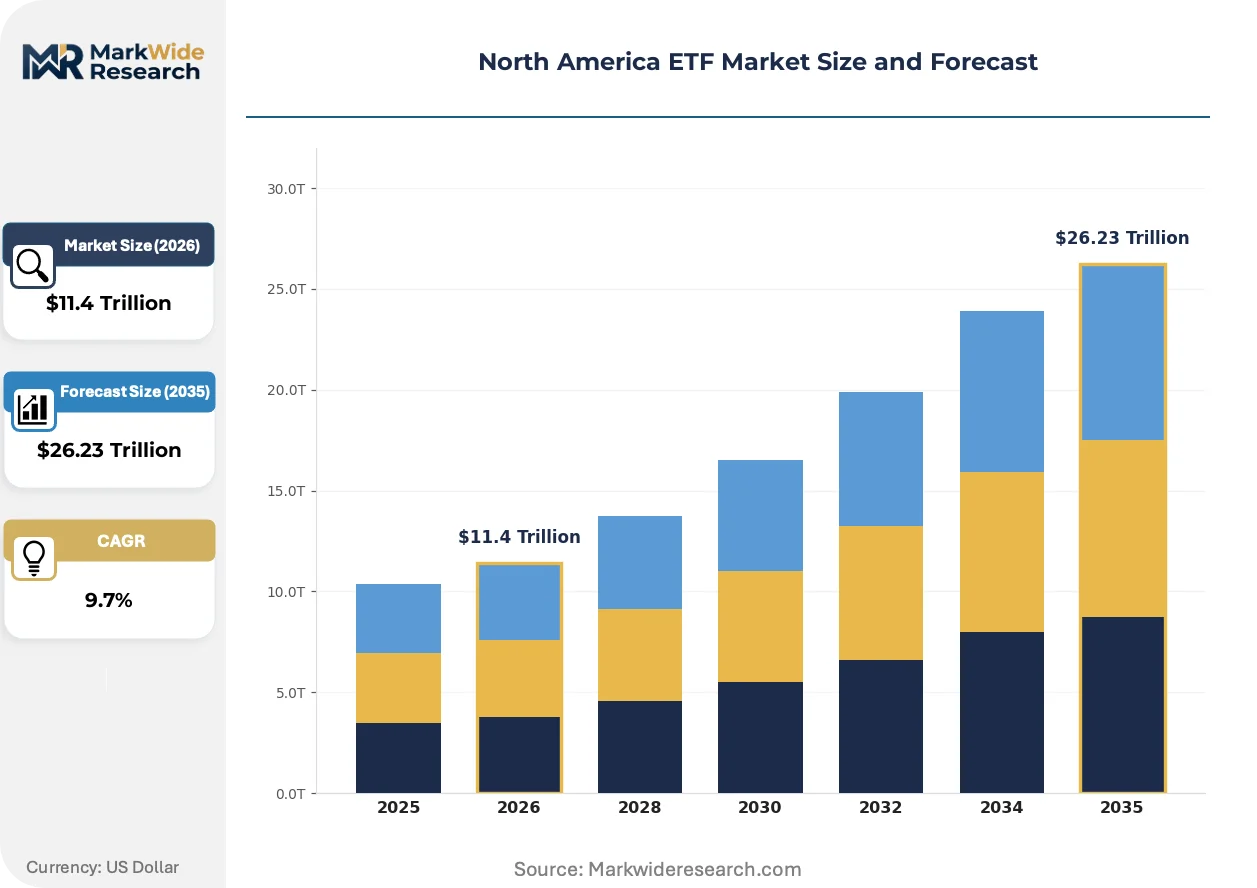
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $26.23 Trillion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity ETFs, Bond ETFs, Commodity ETFs, Currency ETFs Investor Type: Retail Investors, Institutional Investors, Wealth Managers, Hedge Funds Distribution Channel: Online Brokers, Financial Advisors, Direct Market Access, Institutional Platforms Trading Volume: High Volume, Medium Volume, Low Volume, Block Trading |
| Companies Covered | BlackRock, Inc., Vanguard Group, Inc., State Street Global Advisors, Invesco Ltd., Charles Schwab Investment Management, Inc., First Trust Advisors L.P., WisdomTree Investments, Inc., JPMorgan Asset Management, Goldman Sachs Asset Management, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America ETF Market Trends and Innovations
Active management is migrating into exchange-traded wrappers through semi-transparent structures, blurring the historical boundary between mutual fund opacity and ETF tax efficiency.
Custom basket optimization technology is converging with institutional liquidity provision. State Street Global Advisors and other large-scale US managers deploy proprietary algorithms to minimize tracking error while accommodating restricted securities in creation baskets. Pension consultants now mandate this capability for core equity mandates, compressing fees for plain-vanilla replication strategies.
FINRA suitability requirements for complex products tighten distribution standards for leveraged and inverse ETFs. The self-regulatory organization mandates enhanced disclosure protocols and holding-period documentation for retail accounts, elevating compliance costs for US broker-dealers. Wirehouse platforms respond by restricting access to options-approved accounts with minimum net worth thresholds.
Wealth management platforms unbundle portfolio construction from product manufacturing. US registered investment advisors increasingly outsource sleeve-level implementation to zero-commission ETF strategists, retaining client relationships while delegating security selection. This disintermediation concentrates flows among scale infrastructure providers and compresses expense ratios for tactical allocation products.
North America ETF Market Segmentation
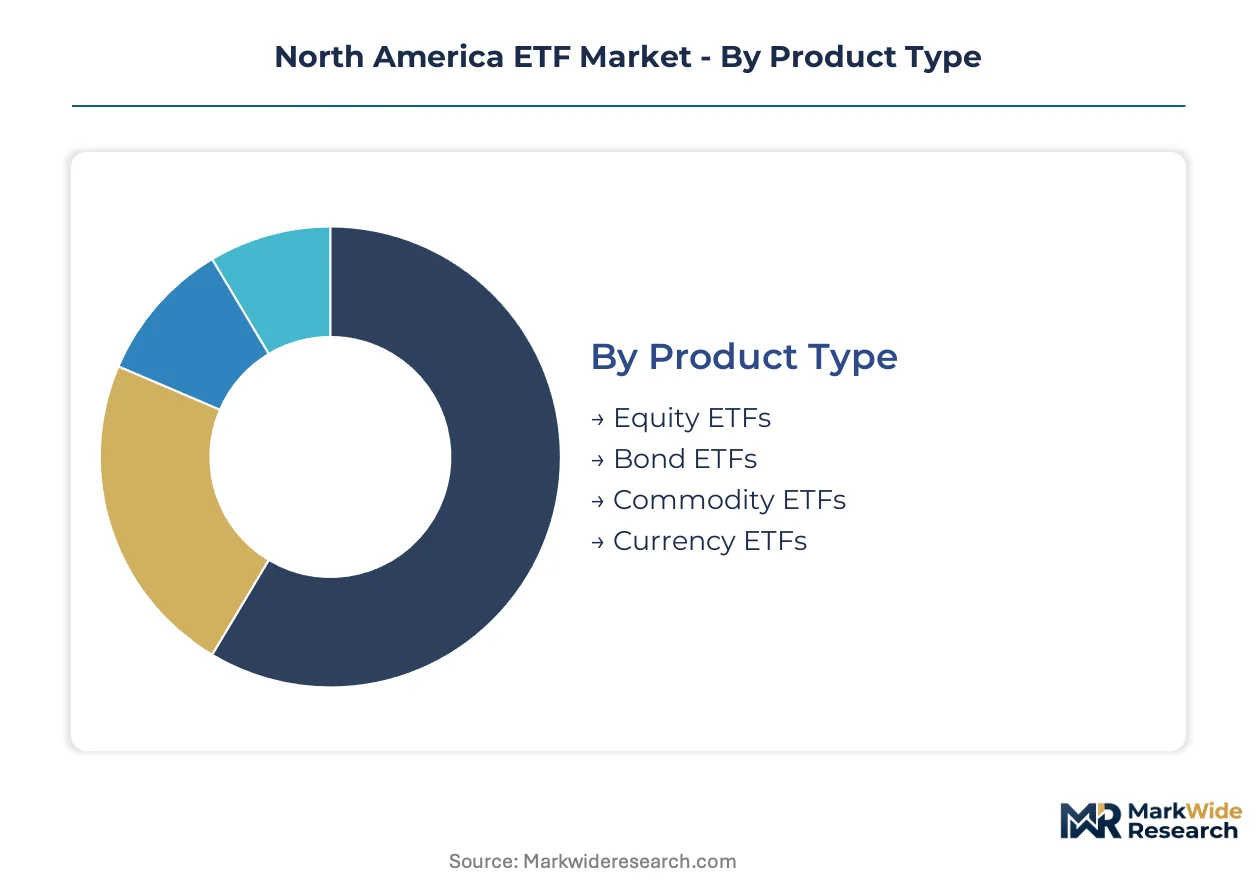
Product architecture and distribution pathways determine fee capture and asset flow velocity in the North America ETF market. Segmentation reveals how passive vehicle demand concentrates across investor sophistication tiers and execution channels.
Product Type:
Expense ratio sensitivity and liquidity requirements drive product selection across US and Canadian investor segments.
- Equity ETFs:Physical replication vehicles tracking S&P 500, Russell 2000, and TSX Composite indices dominate asset-weighted flows. US retirement platforms and Canadian defined contribution plans anchor demand for broad domestic beta at sub-10 basis point cost structures.
- Bond ETFs:Transparent fixed-income execution vehicles displace over-the-counter trading for US pension funds and Canadian insurers seeking T+1 settlement in Treasury and investment-grade credit markets. Demand concentrates among liability-driven investors requiring daily NAV visibility.
- Commodity ETFs:Futures-based structures provide exposure to energy and precious metals without physical storage logistics.
- Currency ETFs:Dollar-denominated pairs and emerging market proxies serve tactical overlay strategies for US hedge funds.
Volume sits with Equity ETFs; growth tilts toward Bond ETFs.
Investor Type:
Ticket size and holding period differentiate service requirements and revenue contribution across the North America ETF market.
- Institutional Investors:Pension funds, endowments, and sovereign wealth vehicles deploy block-sized creation units through authorized participants. These accounts generate securities lending revenue and demand custom basket optimization for restricted security handling.
- Wealth Managers:US registered investment advisors and Canadian portfolio managers construct multi-asset sleeves using zero-commission platforms. Fee compression pressures drive preference for lowest-cost providers with model portfolio infrastructure.
- Retail Investors:Self-directed accounts at US discount brokers and Canadian bank platforms gravitate toward commission-free equity beta products.
- Hedge Funds:Leveraged and inverse structures support tactical positioning and risk overlay strategies.
Revenue concentrates with Institutional Investors; expansion accelerates fastest among Wealth Managers.
Distribution Channel:
Access economics and advisory relationships shape product placement and flow concentration across North American markets.
- Online Brokers:US firms and Canadian bank-owned platforms eliminated trading commissions on ETFs, funneling self-directed flows toward broad equity indices. These channels prioritize low expense ratios and high average daily volume for liquidity assurance.
- Institutional Platforms:Custody banks and prime brokerage services handle creation-redemption mechanics for large-ticket US asset managers. Securities lending programs and collateral management infrastructure deepen relationships.
- Financial Advisors:Wirehouse and independent channels face FINRA suitability requirements for complex product distribution.
- Direct Market Access:Algorithmic traders and proprietary desks execute intraday strategies using ETF liquidity.
Flow volume anchors to Online Brokers; margin expansion concentrates within Institutional Platforms.
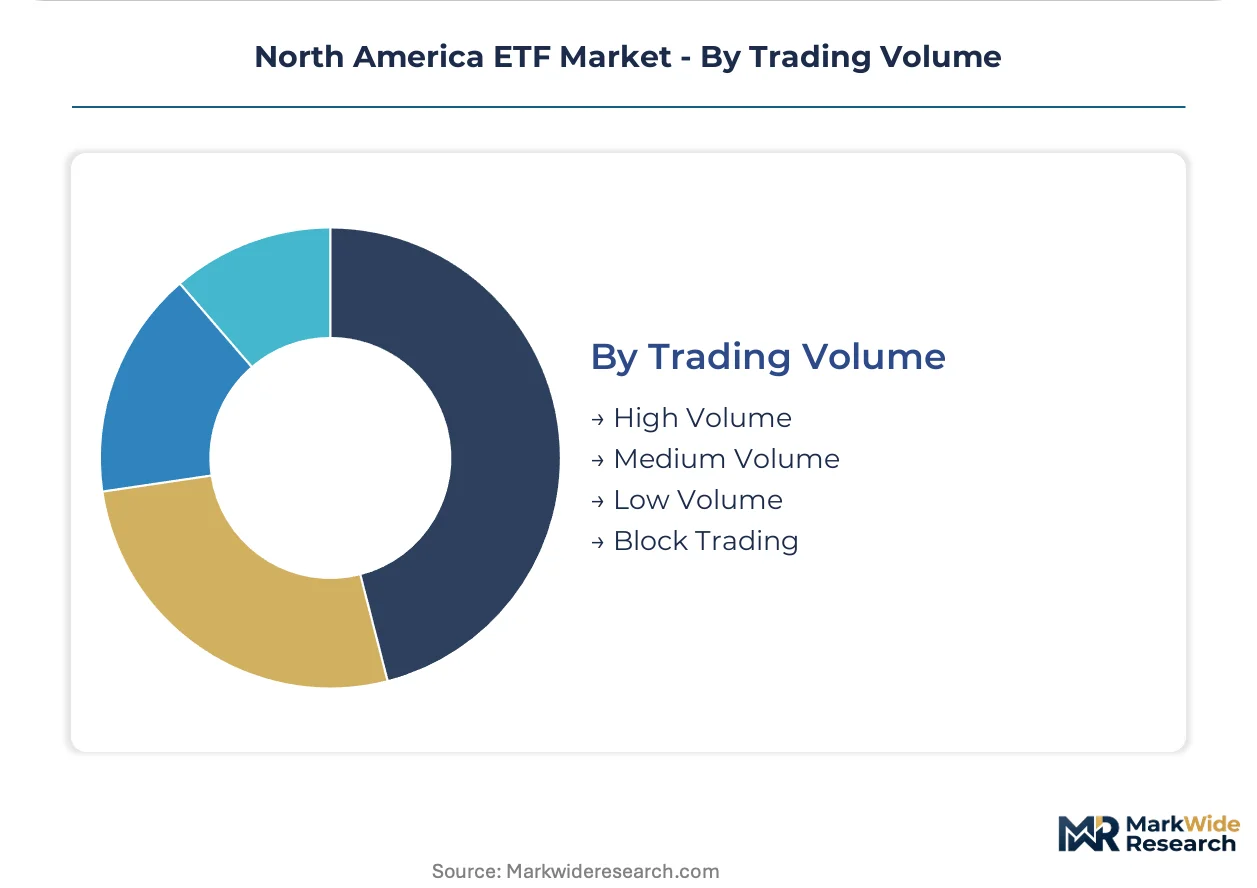
Trading Volume:
Liquidity profiles and spread characteristics determine execution cost and investor suitability across product tiers.
- High Volume:S&P 500 and broad Treasury ETFs trade at penny-wide spreads with deep order book depth. US market makers and Canadian designated brokers commit capital to these vehicles, supporting institutional block execution without market impact.
- Block Trading:Creation unit-sized transactions bypass secondary market liquidity constraints through authorized participant facilitation. Minimum 50,000-share blocks enable US pension funds and Canadian insurers to deploy capital efficiently.
- Medium Volume:Sector and thematic products require careful execution timing to minimize slippage.
- Low Volume:Narrowly focused or recently launched vehicles exhibit wider bid-ask spreads.
Transaction activity clusters in High Volume vehicles; infrastructure investment prioritizes Block Trading capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York and Toronto anchor North American ETF infrastructure through concentrated exchange listings and authorized participant networks.
United States
US pension funds and endowments drive block-sized creation unit demand through institutional platforms. The SEC's ETF Rule modernization streamlines exemptive relief frameworks for novel product structures. Manhattan houses the headquarters of BlackRock, Vanguard, and State Street Global Advisors, where proprietary custom basket algorithms minimize tracking error for core equity mandates.
Canada
Canadian insurers and defined contribution plans seek transparent fixed-income execution alternatives to over-the-counter trading. OSFI climate risk guidelines shape institutional demand for ISSB-aligned environmental attribute indexing products. Toronto's bank-owned brokerage platforms eliminated ETF trading commissions, funneling self-directed retail flows toward TSX Composite-tracking vehicles.
Mexico
Mexican pension funds (Afores) expand cross-border allocation to US-listed equity beta products for diversification. CNBV regulatory frameworks govern securities lending and custody arrangements for foreign-registered ETFs. Mexico City anchors domestic asset manager operations seeking to launch local-currency bond ETFs for liability-driven institutional investors.
North America ETF Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized factor and thematic exposures. The vendor base concentrates around three scale infrastructure providers commanding creation-redemption network effects. Strategic archetypes include: universal platform operators with securities lending ecosystems, cost-engineered beta specialists, and institutional liquidity providers with custom basket capabilities. Dominant competitive moves encompass mutual-to-ETF conversion engines and direct indexing platform acquisitions.
Within the universal platform tier, BlackRock, Inc. and Vanguard Group, Inc. exemplify divergent paths to scale dominance. BlackRock occupies a position anchored by iShares distribution reach and institutional securities lending revenue pools. Vanguard represents the cost-engineered archetype through mutual fund conversion infrastructure and advisor-aligned share classes. State Street Global Advisors sits within the institutional liquidity specialist tier, emphasizing custom creation baskets and pension consultant relationships.
| Leading Market Players |
|---|
| BlackRock, Inc. |
| Vanguard Group, Inc. |
| State Street Global Advisors |
| Invesco Ltd. |
| Charles Schwab Investment Management, Inc. |
| First Trust Advisors L.P. |
| WisdomTree Investments, Inc. |
| JPMorgan Asset Management |
| Goldman Sachs Asset Management |
| Others |
Pricing and Supply Chain Analysis
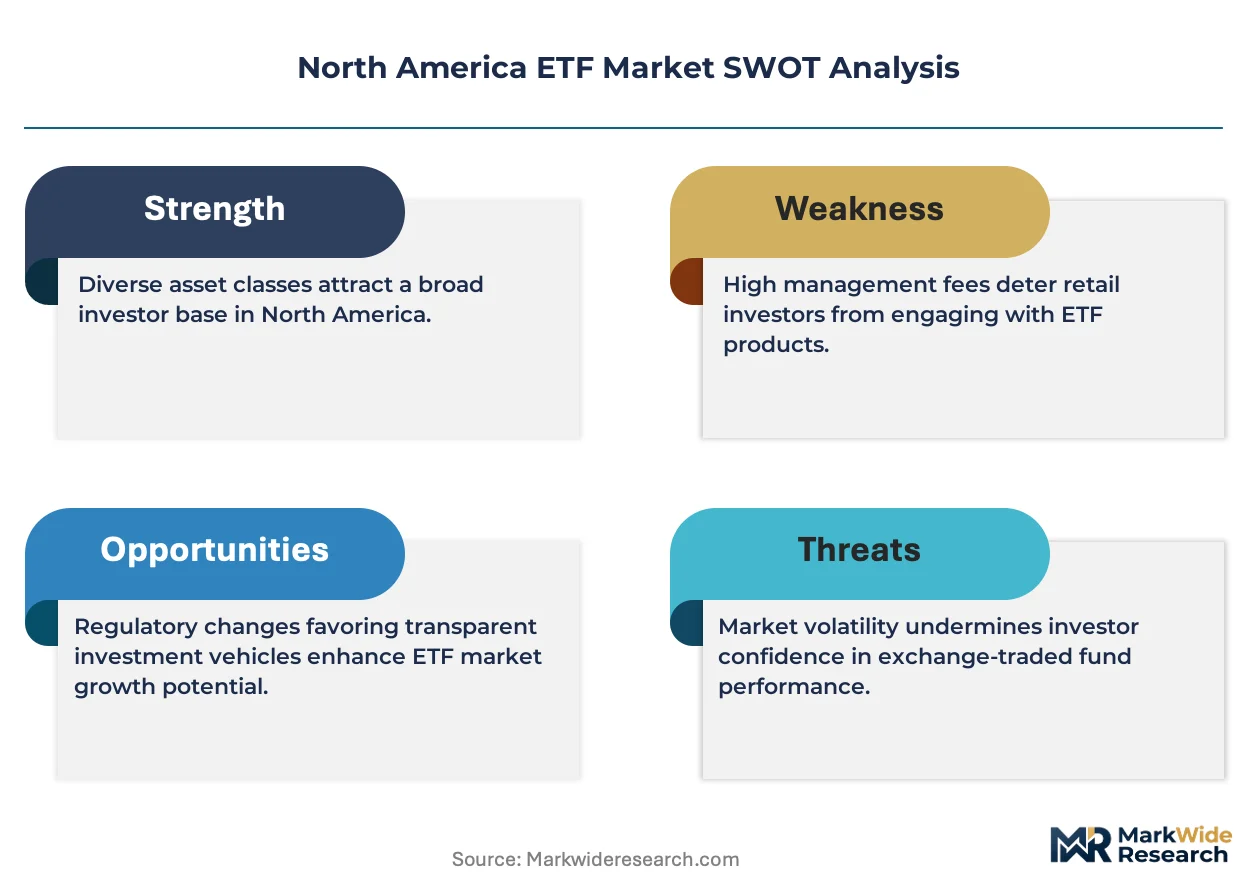
OSFI climate risk guidelines gate qualified supply for Canadian institutional mandates and prop premium-tier pricing access for ISSB-aligned environmental attribute indexing products. Asset managers lacking ESG data infrastructure face exclusion from fee-rich defined benefit flows.
Pricing Analysis
Service-bundling separates pure beta vehicles from value-added offerings, with securities lending revenue sharing and custom basket optimization unbundled at the institutional tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by creation-redemption infrastructure access and tax-loss harvesting automation. Cost compression in standard equity beta intensifies because Vanguard and Schwab compete on expense ratio alone. Retail investors through Canadian bank platforms exhibit highest price sensitivity; pension funds paying for custom creation baskets show least.
Supply Chain Analysis
Warehouse-distribution layer concentration in New Jersey and Toronto anchors authorized participant networks for creation unit settlement. Primary custody infrastructure draws from the United States, Canada, and Ireland-domiciled fund structures. Dependency on US Treasury securities, investment-grade corporate bonds, and equity index futures contracts creates input concentration. Single-source vulnerability sits with clearing banks handling T+1 fixed-income settlement. Distribution runs through institutional platforms for block-sized flows and online brokers for retail fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authorized participant capacity constraints prop pricing power for scale infrastructure providers, as minimum creation unit economics exclude smaller advisors from direct primary market access.
For Market Incumbents: Deploy securities lending ecosystem expansion to capture revenue pools from pension fund block flows. Consolidate around custom basket optimization capabilities before semi-transparent active structures commoditize institutional liquidity provision. BlackRock's iShares platform and State Street's proprietary algorithms represent the consolidation archetype to emulate. Threat from direct indexing platforms automating tax-loss harvesting demands middleware investment. For New Entrants and Emerging Players: Begin with defined outcome strategy white space targeting US pre-retirees seeking buffered equity participation. Mexican Afore cross-border allocation to US-listed products offers the most penetrable geography. Canadian retail brokerage commission elimination creates self-directed investor acquisition opportunity. Go-to-market angle: zero-commission thematic products through bank-owned platforms. For Investors and Strategic Acquirers: SEC scrutiny of semi-transparent active ETF structures is the leading indicator that mutual fund conversion velocity will accelerate. Long-term viability favors universal platform operators with securities lending revenue and institutional consultant relationships. Acquisition target archetype: direct indexing platforms with tax-loss harvesting automation capability. Signal to watch: FINRA suitability enforcement tightening on leveraged product distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Mutual Fund Conversion Engine | Vanguard's infrastructure captures cost-sensitive retail assets through share class unification. |
| Custom Basket Optimization | State Street's proprietary algorithms minimize tracking error for pension core mandates. |
| Direct Indexing Platform Acquisition | SMA automation compresses fees below traditional minimums for tax-loss harvesting. |
| Securities Lending Ecosystem Expansion | Revenue-sharing arrangements with custodian banks deepen institutional relationships. |
| Semi-Transparent Active Structure Launch | SEC exemptive relief enables mutual fund opacity migration into ETF tax efficiency. |
Research Methodology
Document review covered SEC exemptive relief filings, FINRA regulatory notices, and Canadian Securities Administrators rulemaking, complemented by interviews with ETF portfolio managers, authorized participant trading desks, pension consultant advisors, and custody bank operations leads. Secondary validation drew from Investment Company Institute flow reports, ETF.com product databases, and OSFI climate risk disclosure guidelines. Bottom-up asset flow modeling triangulated against top-down market size estimates from exchange listing data.
Segmentation outputs across product type, investor tier, and distribution channel dimensions anchored the analytical framework over the projection horizon. CAGRs derived from historical flow velocity analysis adjusted for regulatory modernization impacts. Forecast inputs incorporated SEC rulemaking timelines and Canadian retail brokerage platform expansion trajectories.
Underlying measurement precision varies by segment; institutional platform flows carry tighter precision than self-directed retail estimates due to disclosure requirements. Forecasts reflect assumptions around regulatory approval continuity and authorized participant capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market