
 Foreign Exchange Market | 2026-2036
Foreign Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Foreign Exchange Market Intelligence
Quantitative analyst talent pools across major dealing rooms is rotating toward Python-based algorithmic execution and machine learning model governance, tightening headroom for traditional voice-broker operations. Deutsche Bank AG leverages its Frankfurt-London-Singapore triangle to sustain 24-hour flow coverage across G10 and emerging market currency pairs. JPMorgan Chase & Co. anchors its dominance through the eXecute platform, which competes directly with multi-dealer portals on price discovery speed. Citigroup Inc. differentiates via its WorldLink payments network, extending foreign exchange execution into integrated treasury workflows for multinational corporations.
Foreign exchange denotes the decentralized global marketplace for trading national currencies against one another, with spot transactions settling within two business days at prevailing interbank rates and forward contracts locking in future exchange rates through bilateral agreements. The primary commercial purpose centers on enabling international trade settlement, hedging currency risk exposure, and facilitating speculative position-taking across macroeconomic cycles. Spot contracts occupy the deepest liquidity tier, processing the highest notional volumes but compressing margin capture per unit traded. Options and swaps generate superior margin pools, particularly among institutional investors and hedge funds seeking tailored risk-reward structures. Retail trader participation through MetaTrader 4 and MetaTrader 5 platforms represents the fastest-growing client channel, though individual ticket sizes remain orders of magnitude below corporate or institutional flows.
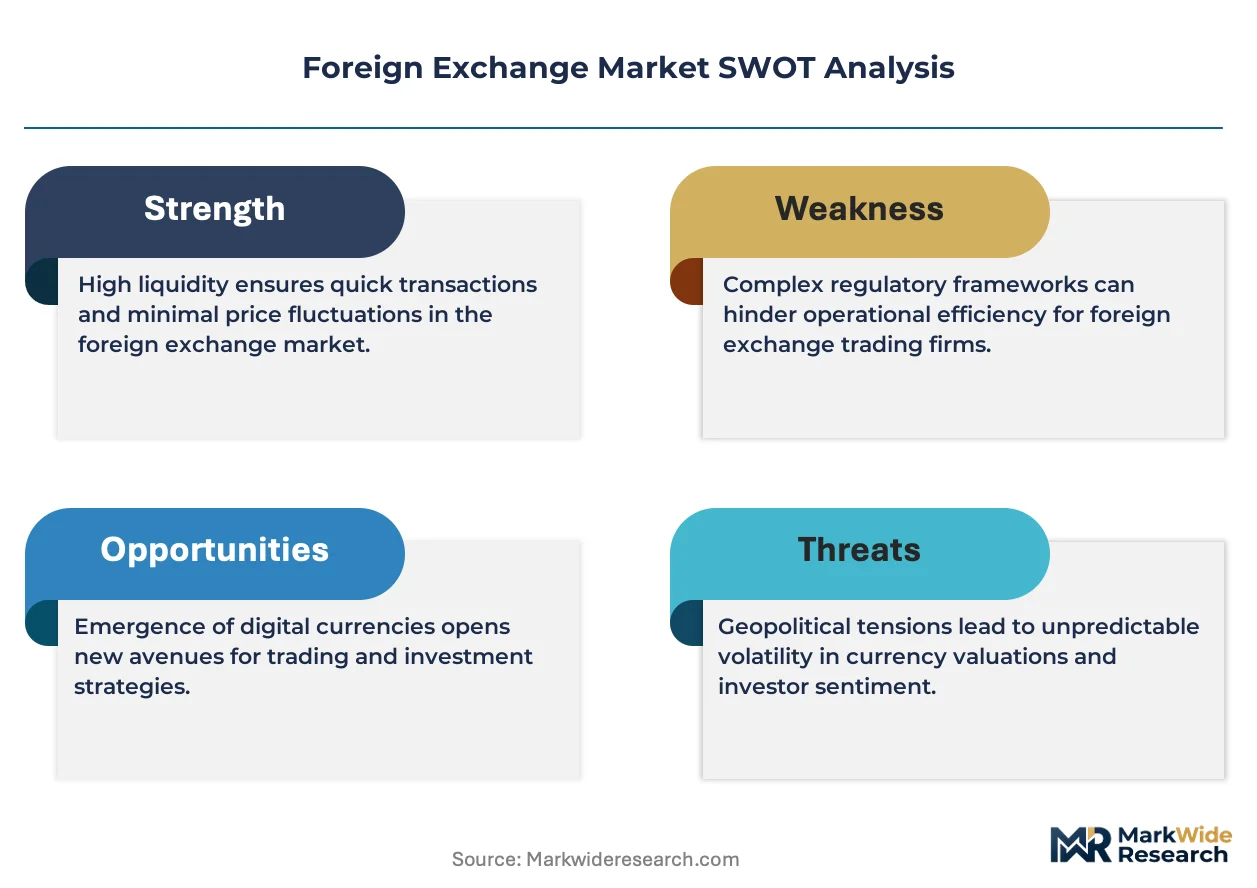
The US Commodity Futures Trading Commission oversees retail forex dealer registration and capital adequacy, while the UK Financial Conduct Authority enforces conduct standards through its Senior Managers and Certification Regime. The Basel Committee on Banking Supervision shapes prudential requirements for market-making capital allocation, directly influencing how dealers price liquidity provision across volatile currency pairs. Stakeholders must monitor whether fragmented national digital asset regulations create parallel settlement rails that either compete with or integrate into traditional foreign exchange infrastructure.
Market Dynamics
Algorithmic execution engines are compressing bid-ask spreads across G10 currency pairs while fragmenting liquidity provision across non-bank market makers, fundamentally restructuring how price discovery occurs in institutional spot markets.
Growth Catalysts
- MiFID II transparency mandates:European regulators force pre- and post-trade reporting, accelerating electronification of formerly voice-brokered flows and opening data-rich execution venues.
- Python-based quantitative talent migration:Dealing rooms in Singapore and London recruit machine learning engineers for alpha-generating models, expanding automated market-making capacity.
- Southeast Asian e-commerce corridors:Cross-border merchant settlement volumes surge through Bangkok and Jakarta hubs, deepening local currency liquidity pools for regional FX pairs.
Market Restraints
- Basel III market risk capital charges:The Basel Committee's standardized approach raises cost of warehousing volatile emerging market positions, constraining dealer willingness to provide deep liquidity in TRY, ZAR, and BRL pairs.
- Cloud infrastructure concentration:Critical execution infrastructure clusters within AWS and Azure data centers in Virginia and Dublin, creating single-point vulnerability for latency-sensitive algorithmic strategies.
- Voice-broker cost structures:Traditional interdealer brokerage maintains fixed personnel overhead that cannot scale down with compressed spreads, eroding profitability of relationship-driven flow.
Strategic Opportunities
- India's rupee internationalization:RBI's progressive current account liberalization permits broader offshore INR trading, opening previously restricted NDF markets to global liquidity providers.
- Embedded FX in treasury workflows:API-first execution layers integrate directly into corporate ERP systems, capturing payment flows before they reach standalone trading platforms.
- Regulatory technology convergence:Real-time transaction reporting tools merge with execution management systems, turning compliance burden into competitive data advantage for early adopters.
Industry Challenges
- Model governance expertise scarcity:Senior staff capable of validating machine learning execution algorithms command premium compensation, creating recruitment bottlenecks for mid-tier dealers.
- Legacy system integration friction:Cobol-based settlement infrastructure at correspondent banks resists real-time API connectivity, delaying straight-through-processing for next-generation trading platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foreign Exchange Market |
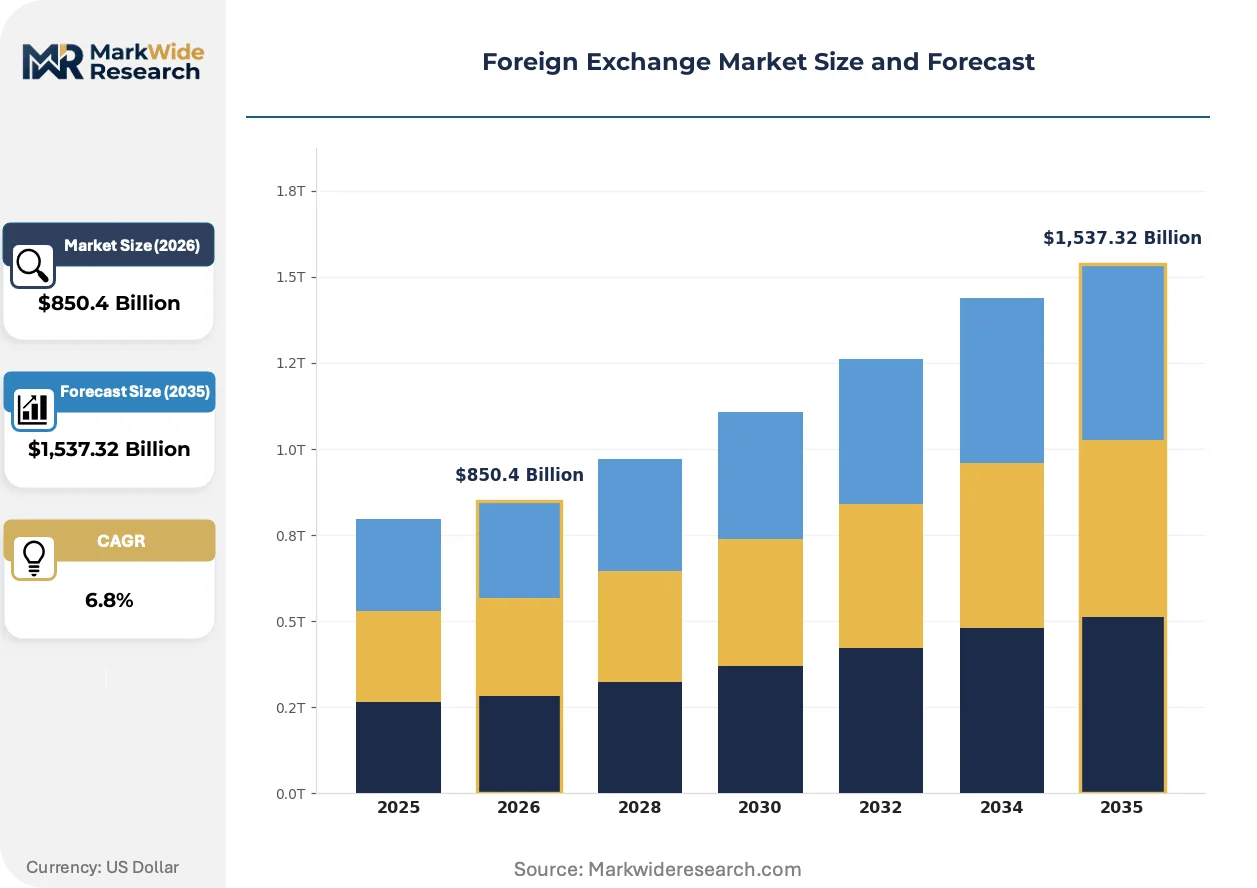
| Market Size in 2026 | $850.4 Billion |
| Market Size in 2035 | $1,537.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spot Contracts, Forward Contracts, Options, Swaps Client Type: Retail Traders, Institutional Investors, Corporations, Hedge Funds Transaction Size: Micro Lots, Mini Lots, Standard Lots, Jumbo Lots Trading Platform: MetaTrader 4, MetaTrader 5, cTrader, Proprietary Platforms |
| Companies Covered | Deutsche Bank AG, Bank of America Corp., JPMorgan Chase & Co., HSBC Holdings PLC, Barclays PLC, Citigroup Inc., XTX Markets Ltd., BNP Paribas SA, UBS Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foreign Exchange Market Strategic Shifts & Innovations
Execution technology is fragmenting liquidity across specialized venues while regulatory data requirements transform compliance infrastructure into strategic assets. Three developments dominate current market evolution.
Smart order routing technology is miniaturizing execution decisions into microsecond-level optimization across fragmented liquidity pools. High-frequency trading firms and institutional asset managers deploy these engines to capture price improvement invisible to human traders. The compression is eliminating traditional dealer intermediation in liquid G10 pairs.
EU's Digital Operational Resilience Act imposes strict continuity requirements on critical financial infrastructure. Trading venues must demonstrate 99.999% uptime with geographic redundancy across Frankfurt and Amsterdam data centers. European banks accelerate cloud migration investments to meet these binding operational standards ahead of enforcement deadlines.
Corporate treasury departments unbundle execution from relationship banking, selecting liquidity providers through open-architecture platforms. Multinational corporations in the manufacturing vertical lead this disintermediation, routing flows directly to multi-dealer portals rather than bilateral credit lines. German automotive exporters demonstrate the strongest adoption velocity in this channel shift.
Foreign Exchange Market Segmentation
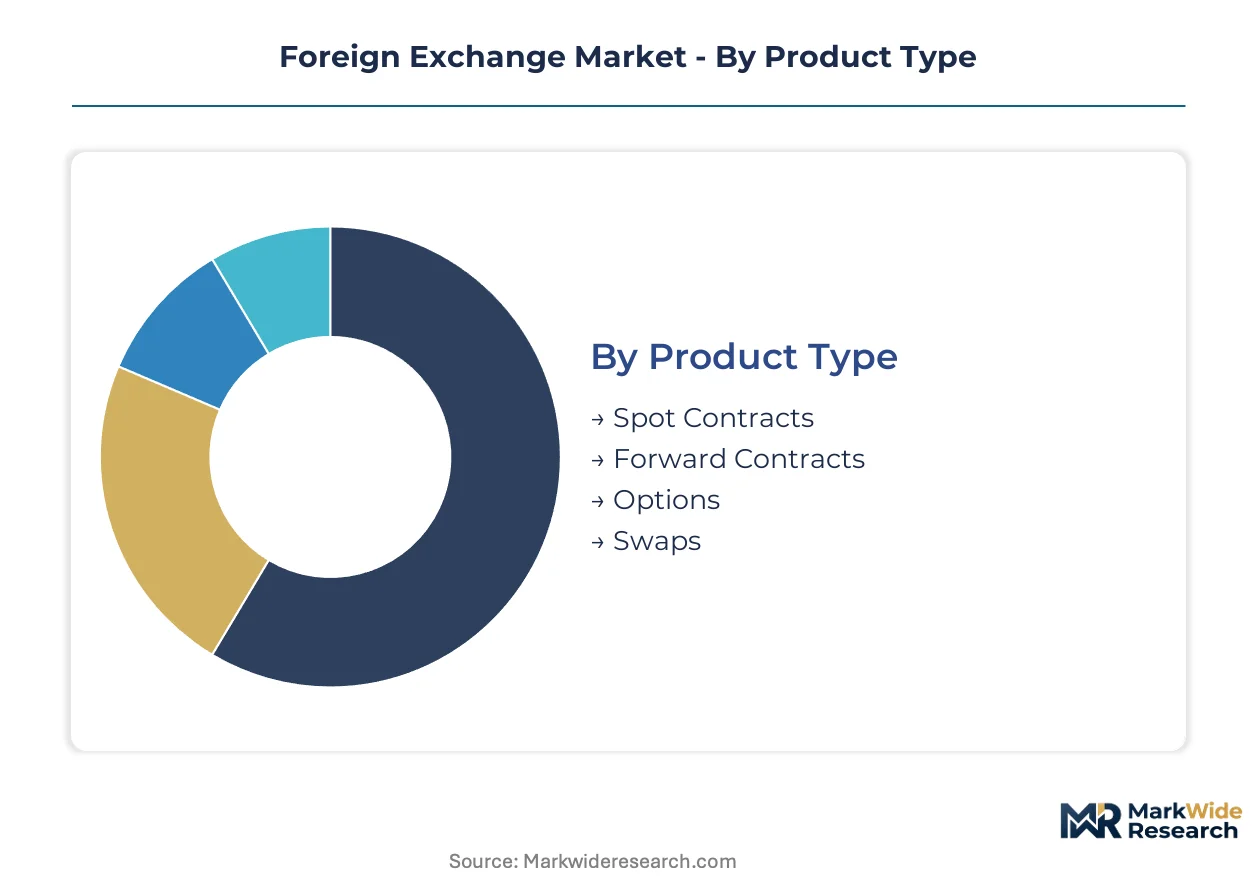
Foreign exchange market segmentation reveals how execution technology, client sophistication, and transaction scale reshape liquidity provision across distinct commercial tiers. Product complexity and platform infrastructure create divergent margin profiles that separate high-volume institutional flows from retail-accessible micro-lots.
Product Type:
Spot contracts anchor domestic settlement volumes across European and Asian financial centers, while derivatives concentrate in export-led hedging demand from multinational corporations managing cross-border receivables.
- Spot Contracts:Immediate settlement at prevailing interbank rates within two business days. Demand concentrates across Singapore and London dealing rooms where algorithmic execution compresses spreads on EUR/USD and USD/JPY pairs. The electronification of spot markets displaces traditional voice-brokered flows.
- Forward Contracts:Bilateral agreements locking future exchange rates for predetermined dates. Corporate treasury departments in Germany and Japan deploy forwards to hedge trade settlement exposure, with contract tenors extending from one week to twelve months. Regulatory margin requirements under EMIR reshape collateral posting practices.
- Options:Asymmetric payoff structures granting right but not obligation to exchange currencies. Institutional investors structure tailored risk-reward profiles through vanilla and exotic strikes.
- Swaps:Simultaneous purchase and sale of identical notional amounts for different value dates. Banks deploy currency swaps to manage overnight funding positions across G10 pairs.
Spot contracts command the established base. The steepest expansion runs through options as hedge funds seek convexity exposure.
Client Type:
Cost-tier stratification separates relationship-driven corporate banking from self-directed retail platforms, with institutional investors occupying the premium execution tier.
- Retail Traders:Individual participants accessing markets through leveraged margin accounts with ticket sizes below $100,000 notional. Bangkok and Jakarta hubs experience surging retail account openings as Southeast Asian financial literacy expands. MetaTrader platform accessibility lowers entry barriers.
- Institutional Investors:Pension funds, asset managers, and sovereign wealth vehicles executing block trades through prime brokerage relationships. Singapore-based asset managers demand direct market access with sub-millisecond latency. MiFID II best execution mandates reshape counterparty selection protocols.
- Corporations:Non-financial enterprises hedging trade receivables and payables through bilateral bank relationships. German automotive exporters demonstrate strongest adoption of API-integrated treasury workflows.
- Hedge Funds:Speculative vehicles deploying leveraged directional and relative-value strategies across G10 and emerging market pairs.
Corporations command the established base. The steepest expansion runs through retail traders as mobile platform penetration deepens.
Transaction Size:
Volume-based tiering aligns with distinct liquidity pools, where standard lots access interbank pricing while micro-lots route through retail aggregators.
- Standard Lots:100,000 base currency units representing the institutional benchmark. Interbank dealers provide executable streaming prices to asset managers and corporate treasuries. Frankfurt and London matching engines process standard lot flows with minimal market impact.
- Jumbo Lots:Positions exceeding $10 million notional requiring specialized handling to minimize information leakage. Block trading desks at major dealers negotiate bespoke execution for sovereign wealth funds.
- Mini Lots:10,000 base currency units serving smaller institutional accounts and high-net-worth individuals.
- Micro Lots:1,000 base currency units enabling precise position sizing for algorithmic strategies and retail risk management.
Standard lots command the established base. The steepest expansion runs through micro lots as quantitative retail strategies proliferate.
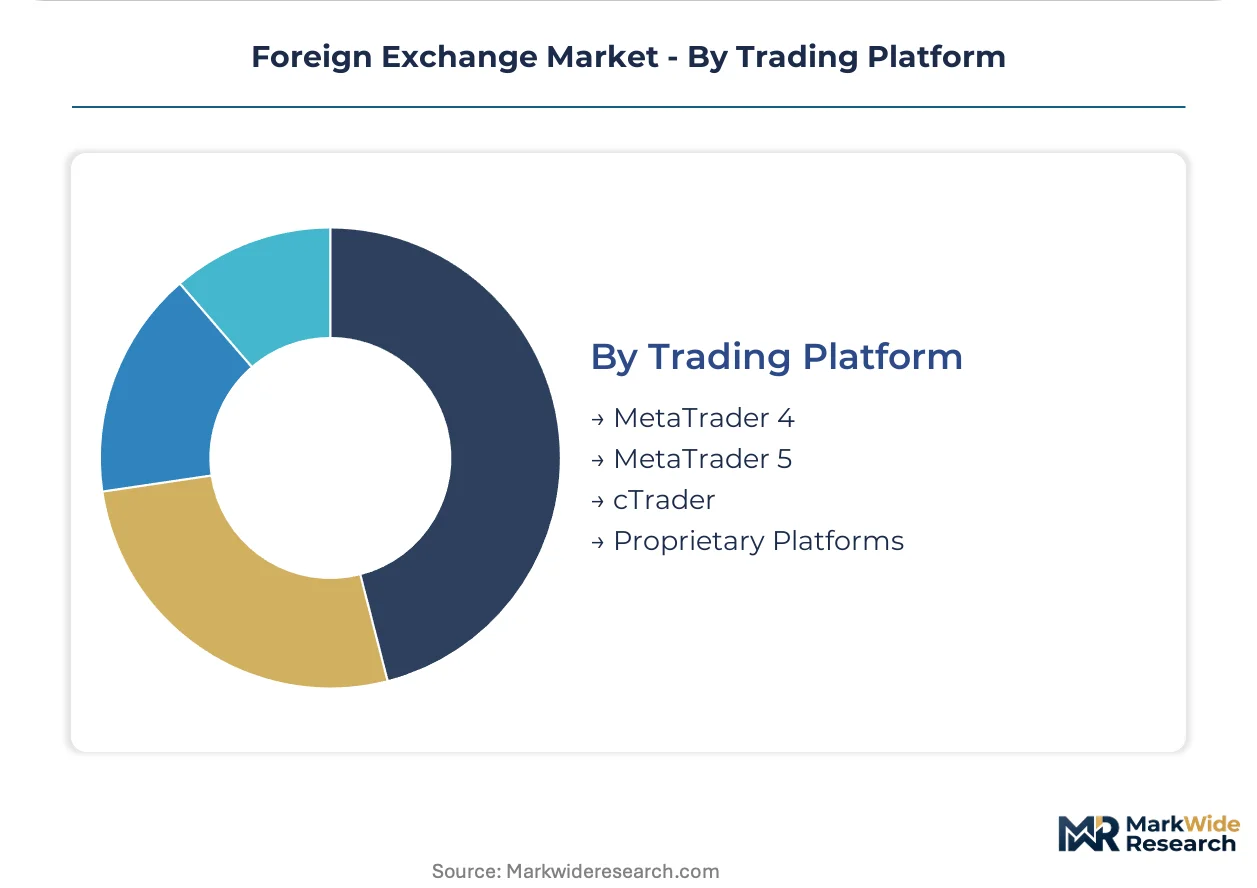
Trading Platform:
Maturity-stage differentiation separates legacy infrastructure from next-generation execution layers, with proprietary systems capturing premium corporate relationships.
- Proprietary Platforms:Dealer-developed execution environments offering integrated research, analytics, and post-trade services. JPMorgan's eXecute and comparable systems compete on price discovery speed and credit line management. Corporate clients value straight-through-processing into treasury management systems.
- MetaTrader 5:Successor platform supporting expanded asset classes and improved execution architecture. Brokers in Cyprus and Australia migrate retail order flow to MT5 for enhanced back-testing capabilities.
- MetaTrader 4:Dominant retail infrastructure with extensive third-party algorithmic library and copy-trading functionality.
- cTrader:Electronic communication network architecture providing direct market access without dealer intervention.
MetaTrader 4 commands the established base. The steepest expansion runs through proprietary platforms as corporate treasury departments unbundle execution from relationship banking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Commodity Futures Trading Commission anchors the regulatory framework for North American foreign exchange operations, while the UK Financial Conduct Authority and the European Securities and Markets Authority shape conduct standards across Atlantic dealing rooms.
United States
Corporate treasury departments in New York and Chicago drive institutional hedging demand through API-integrated execution platforms. The CFTC enforces retail forex dealer registration and capital adequacy requirements that filter market access. Dallas and Miami data centers host critical matching engine infrastructure for latency-sensitive algorithmic strategies.
United Kingdom
Asset managers and hedge funds in London generate block trade flows through prime brokerage relationships with sub-millisecond latency requirements. The FCA's Senior Managers and Certification Regime imposes individual accountability for execution quality. The City of London remains the dominant European venue for G10 spot and forward contract liquidity.
Singapore
Quantitative talent migration from traditional voice-broker operations to Python-based algorithmic execution accelerates automated market-making capacity. The Monetary Authority of Singapore supervises payment system stability and foreign exchange settlement risk. The Marina Bay financial district hosts regional headquarters for dealers covering Southeast Asian currency pairs.
Germany
Automotive exporters in Stuttgart and Munich demonstrate the strongest adoption velocity of unbundled execution through open-architecture treasury platforms. BaFin enforces MiFID II transparency mandates across pre- and post-trade reporting obligations. Frankfurt anchors continental European liquidity provision with 24-hour flow coverage extending into Asian trading hours.
Japan
Corporate treasury departments in Tokyo deploy forward contracts to hedge trade settlement exposure across export-led manufacturing operations. The Financial Services Agency oversees conduct standards for retail forex margin trading. Osaka's financial district complements Tokyo's dealing rooms in yen-denominated derivatives liquidity provision.
Foreign Exchange Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in foreign exchange market-making, with global systemically important banks maintaining 24-hour flow coverage across G10 and emerging market pairs while non-bank electronic market makers capture fragmented liquidity in standardized instruments. The competitive terrain separates full-service dealers with integrated payments networks from algorithmic specialists optimizing microsecond execution. Strategic moves center on API-first treasury workflow integration and geographic redundancy investments to meet operational resilience mandates.
Among integrated global dealers, Deutsche Bank AG anchors European liquidity provision through its Frankfurt-London-Singapore operational triangle, while JPMorgan Chase & Co. occupies a position on the premium-tier vector through proprietary execution platform development. Citigroup Inc. exemplifies the payments-integrated archetype by extending foreign exchange execution into corporate treasury workflows. XTX Markets Ltd. represents the non-bank algorithmic specialist tier that has displaced traditional dealer intermediation in liquid G10 pairs through smart order routing technology.
| Leading Market Players |
|---|
| Deutsche Bank AG |
| Bank of America Corp. |
| JPMorgan Chase & Co. |
| HSBC Holdings PLC |
| Barclays PLC |
| Citigroup Inc. |
| XTX Markets Ltd. |
| BNP Paribas SA |
| UBS Group AG |
| Others |
Cost & Logistics Intelligence
Two-day settlement cycles in spot foreign exchange markets concentrate pricing power within tier-1 dealers in London, New York, and Singapore, where inventory velocity and credit line depth determine quote competitiveness across G10 pairs. This temporal compression of settlement risk amplifies the advantage of banks with real-time nostro account visibility and deep local currency liquidity pools.
Pricing Analysis
Bid-ask spreads on EUR/USD and USD/JPY in London and New York dealing rooms compress tighter than equivalent quotes in secondary Asian hubs, reflecting electronification density and algorithmic market-maker participation. Price differentiation rests on execution speed tiers and credit line availability, with prime brokerage clients accessing sub-millisecond fills while retail aggregators face wider spreads. Pricing pressure stems from non-bank algorithmic specialists displacing traditional voice-brokered flows in liquid pairs. Corporate treasury departments demonstrate lowest price sensitivity, prioritizing straight-through-processing integration over spread capture.
Supply Chain Analysis
Swift messaging infrastructure chokepoints in Brussels and Culpeper, Virginia, tether global settlement velocity to concentrated network nodes. Liquidity provision concentrates in the United States, United Kingdom, and Singapore, where matching engine infrastructure and regulatory clarity attract order flow. Raw material dependencies include cloud compute capacity from hyperscalers, co-location space in financial districts, and specialized network hardware. Single-source vulnerability runs through AWS and Azure data center concentration for latency-sensitive execution. Distribution runs through bilateral credit lines and multi-dealer portals reaching corporate and institutional end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foreign exchange markets present a service-attach opportunity as API integration and post-trade analytics expand faster than standalone execution revenues, with treasury workflow embedding capturing recurring fee streams beyond transactional spreads.
For Market Incumbents: Fortify defensible positions by deepening vertical integration into cloud infrastructure and co-location services, reducing dependency on AWS and Azure concentration. Invest in machine learning model governance capabilities to meet EU Digital Operational Resilience Act validation requirements. Consolidate regional liquidity pools through targeted hiring of Python-based quantitative talent in Singapore and London.
For New Entrants and Emerging Players: Differentiate on embedded execution within corporate ERP systems, targeting German automotive exporters and Southeast Asian e-commerce merchants with API-first treasury workflows. Penetrate India's progressively liberalized rupee NDF markets ahead of full internationalization. Pursue regulatory technology partnerships that transform real-time transaction reporting into competitive data advantages.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified banking groups spinning non-core electronic market-making units under Basel III capital pressure. Long-term viability favors specialists with geographic redundancy across Frankfurt, London, and Singapore data centers. Monitor MiFID II enforcement intensity as signal for electronification acceleration and voice-broker displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Treasury Integration | Captures payment flows before they reach standalone trading platforms at German automotive exporters. |
| Geographic Data Center Redundancy | Meets EU Digital Operational Resilience Act uptime mandates across Frankfurt and Amsterdam clusters. |
| Machine Learning Model Governance Investment | Addresses recruitment bottlenecks for validating algorithmic execution under ECB supervisory scrutiny. |
| Offshore INR Market Entry | Positions liquidity providers for RBI current account liberalization expanding NDF access. |
| Regulatory Technology Convergence | Merges real-time transaction reporting with execution management for MiFID II compliance advantage. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with FX dealing room heads, quantitative strategists, corporate treasury managers, and regulatory technology vendors, combined with secondary validation through BIS triennial surveys, CLS Bank settlement data, and central bank foreign exchange committee disclosures. Bottom-up order flow estimates from regional financial centers triangulated against top-down market size assessments derived from dealer revenue disclosures and platform transaction reporting.
Across the analysis window, forecasts employed segmented modeling across product type, client sophistication tier, transaction size band, and trading platform architecture, with CAGRs derived from historical electronification trends and regulatory mandate implementation schedules. Industry-specific inputs incorporated MiFID II transaction reporting volumes, cloud infrastructure capex disclosures from hyperscalers, and cross-border e-commerce settlement velocity through Southeast Asian financial hubs.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory electronification pressure and stable cloud infrastructure availability; material deviation in Basel III implementation intensity or geopolitical fragmentation of settlement rails would warrant model refresh. Practitioners should keep alternative scenarios live as central bank digital currency interoperability and tokenized settlement experiments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
Securities Trading Software Market