
 Asia Pacific ETF Market | 2026-2036
Asia Pacific ETF Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific ETF Market Insights
The bifurcation between institutional-grade and retail-accessible ETF tiers is hardening across Asia Pacific. BlackRock iShares leverages its global indexing infrastructure to dominate cross-border equity products. Nomura Asset Management anchors its position in Japan through specialized fixed-income vehicles. Samsung Asset Management competes aggressively in thematic and sector-specific Korean listings.
Exchange-traded funds are pooled investment securities tracking indices, commodities, or baskets of assets while trading intraday on exchanges like ordinary shares, with creation-redemption mechanisms employing authorized participants to maintain price convergence with net asset value. Equity ETFs command the deepest liquidity pools across Tokyo, Shanghai, and Sydney bourses, while bond ETFs attract duration-sensitive institutional flows as regional rate cycles diverge. Retail investor segments expand fastest through mobile brokerage integration, though sovereign wealth funds concentrate margin-rich block trades in direct platform channels.
Japan's Financial Services Agency, the Securities and Exchange Board of India, and Australia's Australian Securities and Investments Commission each enforce distinct disclosure and liquidity standards that shape product registration timelines and cross-border distribution eligibility. China's National Association of Financial Market Institutional Investors and the CSRC coordinate quota frameworks governing offshore ETF access for mainland investors. Stakeholders must monitor how divergent settlement cycles and tax withholding regimes across these jurisdictions alter total cost of ownership calculations.
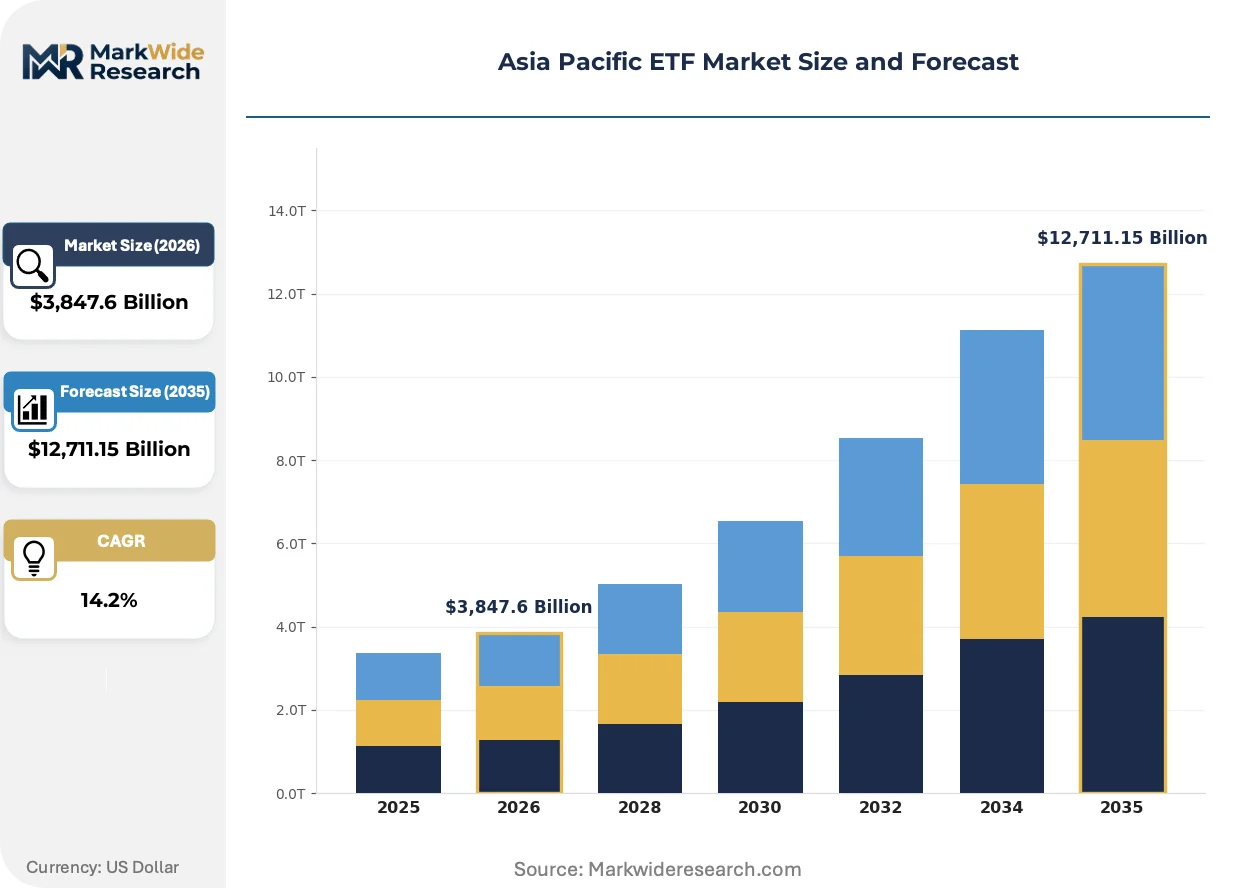
Market Dynamics
Passive investment mandates from Japan's Government Pension Investment Fund and Australia's sovereign wealth vehicles are compressing active management fee structures while concentrating liquidity in benchmark-tracking instruments.
Growth Catalysts
- Japan's FSA Stewardship Code:Institutional asset owners must disclose voting policies and engagement strategies, channeling capital toward transparent, low-cost ETF vehicles that satisfy governance reporting requirements.
- India's SEBI FPI Framework:Simplified registration for foreign portfolio investors has expanded eligible participant pools for domestic equity ETFs, deepening secondary market liquidity in NSE-listed products.
- Carbon Credit-Linked Products:Exchange-traded vehicles tracking regional emissions allowances are capturing capital rotation from conventional fixed-income as investors seek compliance-grade exposure to decarbonization pathways.
Market Restraints
- USD-HKD Basis Volatility:Hong Kong dollar peg mechanics create synthetic hedging costs for offshore RMB-denominated products, compressing net returns for cross-border equity strategies.
- Authorized Participant Concentration:Primary market creation-redemption functions depend on a narrow tier of global investment banks with balance sheet capacity, creating single-point fragility during stress periods.
- Settlement Cycle Fragmentation:T+2 cycles in Tokyo, T+1 in Shanghai, and T+0 in Sydney generate cash drag and FX mismatch risks for multi-market arbitrage strategies.
Strategic Opportunities
- Vietnam's Ho Chi Minh Stock Exchange:Frontier market status and MSCI watchlist progression create first-mover advantages for index-licensing agreements ahead of potential reclassification.
- Tokenized Fund Units:Singapore's MAS Project Guardian pilots are validating distributed ledger infrastructure for fractionalized ETF ownership, potentially collapsing minimum investment thresholds for retail segments.
- Transition Finance Taxonomy:ASEAN sustainable finance classification standards will channel mandatory institutional allocations toward green bond ETFs and climate-aligned equity baskets.
Industry Challenges
- Quantitative Index Engineering Talent:Systematic factor construction and smart beta methodology development require specialized skill sets concentrated in North American and European financial centers, constraining regional product innovation pipelines.
- Cross-Border Tax Reclaim Complexity:Withholding tax recovery procedures across 14 Asia Pacific jurisdictions demand dedicated operational infrastructure, elevating total expense ratios for internationally distributed share classes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific ETF Market |
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $12,711.15 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity ETFs, Bond ETFs, Commodity ETFs, Currency ETFs Investor Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Sovereign Wealth Funds Asset Class: Large Cap, Mid Cap, Small Cap, International Distribution Channel: Online Brokerage, Wealth Management Firms, Direct Investment Platforms, Advisors |
| Companies Covered | BlackRock iShares, State Street Global Advisors, Nikko Asset Management, Samsung Asset Management, Mirae Asset Global Investments, Nomura Asset Management, Daiwa Asset Management, China Asset Management, Vanguard, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific ETF Market Trends and Innovations
Blockchain-enabled fund administration and artificial intelligence-driven portfolio construction are compressing product development cycles while fragmenting distribution control away from traditional intermediary channels.
Distributed ledger technology for fund registry and settlement is decentralizing custody and transfer agency functions that historically concentrated with bank-owned infrastructure providers. Asset managers in Singapore and Hong Kong are piloting tokenized creation units that bypass conventional authorized participant networks. This architecture collapse threatens incumbent service provider margins while enabling real-time NAV publication and intraday creation-redemption cycles.
China's CSRC has tightened disclosure requirements for thematic ETFs, mandating granular holdings reporting and concentration risk warnings for sector-specific products. The regulation compresses marketing flexibility for fund sponsors while elevating compliance documentation burdens. Korean asset managers have responded by pivoting toward broad-based equity indices that avoid single-industry concentration thresholds.
Direct indexing platforms and separately managed account technology are fragmenting traditional ETF distribution through brokerage-integrated fractional share construction. Retail investors in Australia and Japan increasingly bypass pooled vehicles to replicate benchmark exposures through custom baskets with tax-loss harvesting overlays. This behavioral shift pressures management fee sustainability for conventional fund structures while concentrating platform economics with technology-enabled custodians.
Asia Pacific ETF Market Segmentation
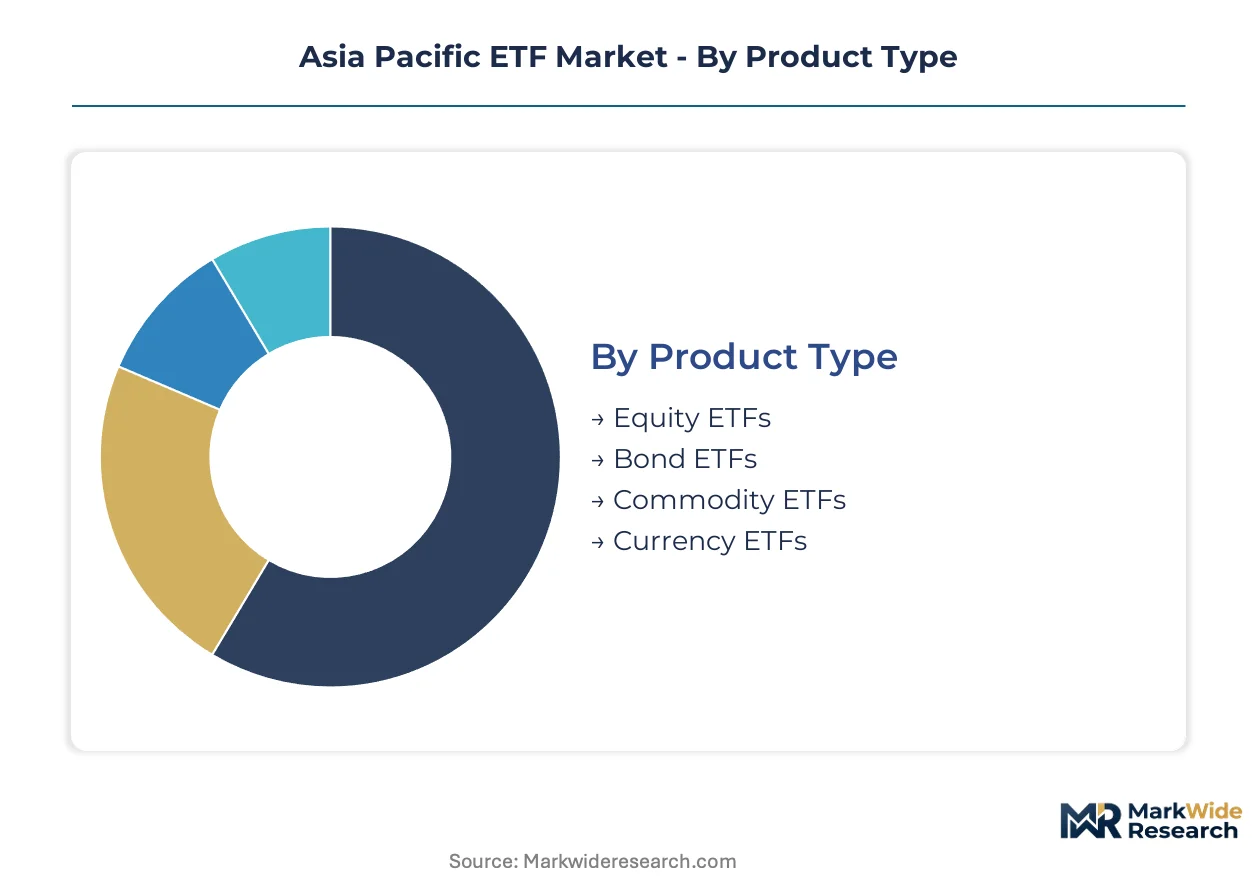
Segmentation in the Asia Pacific ETF market reveals how investor sophistication, regulatory frameworks, and distribution infrastructure shape product development. Each dimension exposes distinct margin profiles and operational requirements that fund sponsors must navigate.
Product Type:
Investor risk tolerance and duration requirements determine product selection across institutional and retail channels.
- Equity ETFs:These vehicles track benchmark indices across Tokyo, Shanghai, and Sydney exchanges, offering intraday liquidity and transparent pricing. Japan's Government Pension Investment Fund channels substantial flows into broad-market equity products, compressing expense ratios while concentrating liquidity in core benchmark vehicles.
- Bond ETFs:Fixed-income vehicles provide duration exposure across diverging regional rate cycles, with institutional investors seeking yield pickup in Australian and Korean sovereign debt. Settlement cycle fragmentation between T+2 Tokyo and T+1 Shanghai markets generates cash drag that constrains arbitrage efficiency.
- Commodity ETFs:Physical and synthetic structures track precious metals and energy futures, attracting inflation-hedge demand from Australian superannuation funds.
- Currency ETFs:RMB and yen-denominated vehicles facilitate FX exposure management for cross-border equity strategies, though USD-HKD basis volatility elevates hedging costs.
Volume sits with Equity ETFs; growth tilts toward Bond ETFs as rate cycle divergence deepens duration-sensitive institutional allocations.
Investor Type:
Capital deployment scale and governance requirements fragment service models across the distribution landscape.
- Retail Investors:Mobile brokerage integration in Japan and Australia drives fastest expansion through fractional share access and tax-loss harvesting overlays.
- Institutional Investors:Pension funds and insurance mandates concentrate liquidity in benchmark-tracking instruments, with Japan's FSA Stewardship Code compelling governance reporting that favors transparent ETF structures.
- High Net Worth Individuals:Family offices seek customized factor exposures through direct indexing platforms that bypass conventional pooled vehicles.
- Sovereign Wealth Funds:Australia's Future Fund and comparable state vehicles execute margin-rich block trades through direct platform channels, bypassing intermediary economics.
Institutional Investors command current volume; Retail Investors are expanding most quickly through technology-enabled access.
Asset Class:
Market capitalization thresholds and geographic scope determine liquidity depth and tracking error profiles.
- Large Cap:Blue-chip indices across Nikkei and ASX benchmarks offer tight bid-ask spreads and minimal tracking variance.
- Mid Cap:Secondary listings in Korea and Taiwan provide factor exposure with elevated volatility premiums.
- Small Cap:Frontier market access through Vietnam and Philippines listings attracts specialist mandates with liquidity constraints.
- International:Cross-border developed market exposure satisfies diversification requirements within single-vehicle structures.
Large Cap dominates transaction volume; Small Cap captures steepest expansion trajectory on frontier market reclassification potential.
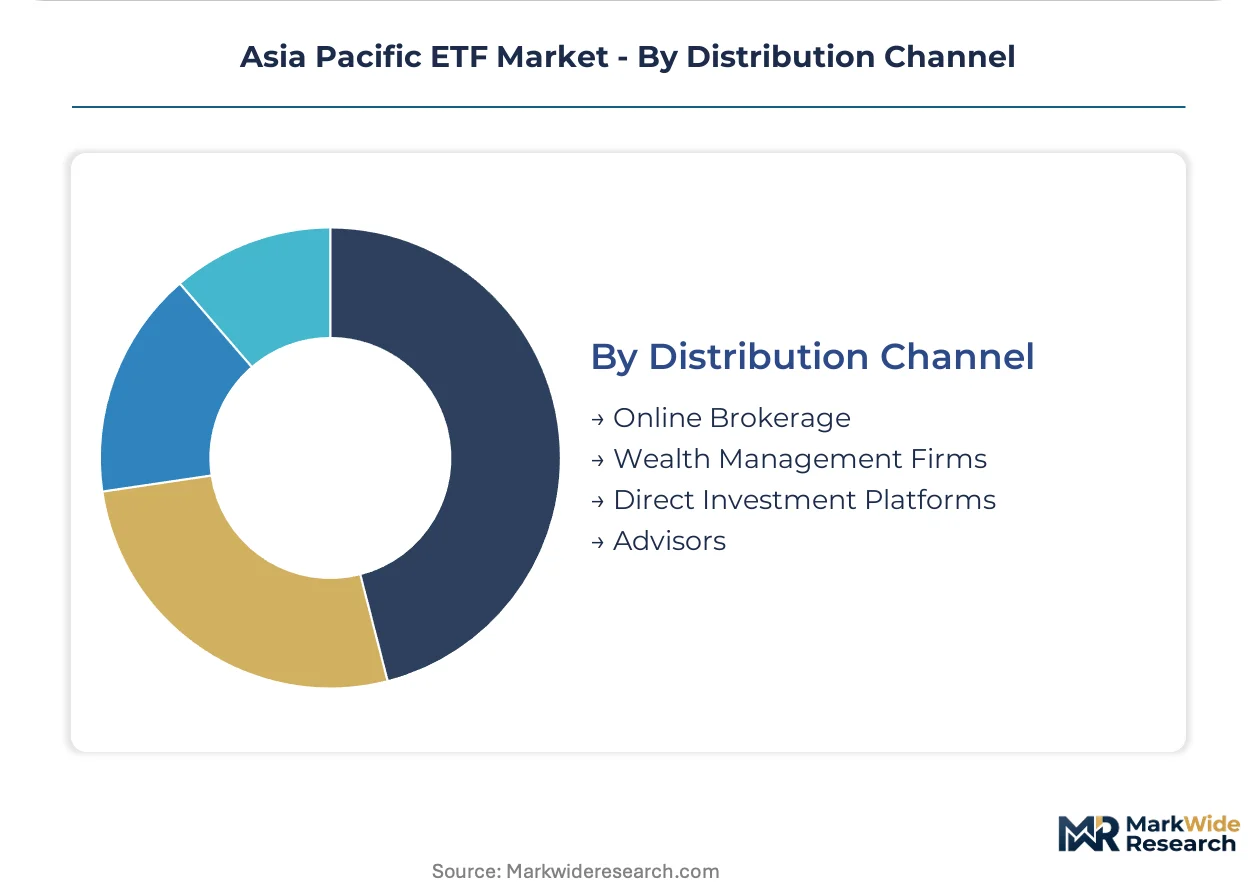
Distribution Channel:
Technology infrastructure and advisory relationships determine client acquisition economics and retention rates.
- Online Brokerage:Rakuten Securities and Australian neobrokers fragment traditional distribution through zero-commission models and mobile-first interfaces.
- Wealth Management Firms:Full-service advisors in Singapore and Hong Kong construct model portfolios using ETF sleeves, capturing ongoing advisory fees.
- Direct Investment Platforms:Institutional-only channels serve sovereign wealth funds with customized creation-redemption terms and dedicated liquidity provision.
- Advisors:Independent practitioners leverage ETF strategists for outsourced portfolio construction, concentrating platform economics with technology-enabled custodians.
Online Brokerage holds current volume leadership; Direct Investment Platforms gain share fastest on institutional mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors the Asia Pacific ETF ecosystem, housing the Monetary Authority of Singapore's regulatory sandbox and regional headquarters for major asset managers. Tokyo, Shanghai, and Sydney bourses concentrate liquidity pools and product innovation pipelines.
Japan
The Government Pension Investment Fund channels substantial passive mandates into benchmark-tracking equity vehicles. Japan's Financial Services Agency enforces Stewardship Code disclosure requirements that favor transparent ETF structures for institutional asset owners. Tokyo Stock Exchange listings dominate regional equity ETF liquidity, with specialized fixed-income products gaining traction among insurance mandates.
China
Onshore ETF demand concentrates in CSI 300 and STAR Market index vehicles as retail brokerage penetration deepens. The China Securities Regulatory Commission coordinates quota frameworks governing offshore ETF access through Stock Connect mechanisms. Shanghai's Pudong financial zone houses the headquarters of domestic asset managers expanding product shelves into carbon credit-linked and thematic strategies.
Australia
Superannuation fund allocations drive fixed-income and commodity ETF expansion as duration-sensitive institutions seek yield pickup. The Australian Securities and Investments Commission enforces distinct liquidity and disclosure standards shaping product registration timelines. Sydney's central business district clusters the headquarters of major wealth management platforms integrating ETF sleeves into model portfolios.
South Korea
Retail brokerage integration accelerates thematic and sector-specific ETF adoption through mobile-first distribution channels. The Financial Services Commission regulates product concentration limits that Korean asset managers navigate through broad-based equity index pivots. Seoul's Yeouido financial district anchors Samsung Asset Management and competing domestic sponsors in aggressive product development cycles.
India
Simplified foreign portfolio investor registration under SEBI frameworks expands eligible participant pools for domestic equity ETFs. The National Stock Exchange of India deepens secondary market liquidity through institutional block trading infrastructure. Mumbai's Bandra-Kurla Complex concentrates asset management headquarters and index-licensing negotiations ahead of potential MSCI weight increases.
Asia Pacific ETF Market Competitive Landscape
Capital-heavy asset managers with proprietary indexing infrastructure compete with asset-light sponsors licensing third-party benchmarks. The market structure concentrates around three tiers: global index giants with cross-border distribution networks, regional specialists with localized regulatory expertise, and domestic champions leveraging home-market custody relationships. Strategic archetypes include scale-driven fee compressors, factor-innovation specialists, and distribution-integrated platform builders. Competitive moves center on index-licensing exclusivity arrangements and direct-to-institutional platform channel development.
Within the global-scale tier, BlackRock iShares and State Street Global Advisors anchor positions through cross-border equity product dominance and authorized participant network density. Among Asia-headquartered specialists, Nomura Asset Management exemplifies fixed-income vehicle specialization, while Samsung Asset Management occupies a position in Korean thematic and sector-specific listings. Nikko Asset Management and Daiwa Asset Management represent Japan-focused regulatory navigation capabilities, and China Asset Management anchors onshore RMB-denominated product shelves.
| Leading Market Players |
|---|
| BlackRock iShares |
| State Street Global Advisors |
| Nikko Asset Management |
| Samsung Asset Management |
| Mirae Asset Global Investments |
| Nomura Asset Management |
| Daiwa Asset Management |
| China Asset Management |
| Vanguard |
| Others |
Pricing and Supply Chain Analysis
Japan's FSA Stewardship Code disclosure mandates gate qualified supply relationships for authorized participants while restricting premium-tier pricing access to sponsors demonstrating full governance transparency. Fund sponsors lacking Stewardship-compliant operational infrastructure face exclusion from institutional mandates that concentrate liquidity in lowest-expense-ratio vehicles.
Pricing Analysis
Expense ratio compression anchors value-based pricing for institutional block trades, where basis-point fees scale inversely with creation unit size. Price differentiation separates ultra-low-cost core equity products from specialized fixed-income vehicles carrying duration management premiums. Pricing pressure intensifies in retail-accessible share classes as mobile brokerage zero-commission models eliminate distribution margin recovery. Sovereign wealth funds exhibit lowest price sensitivity, while self-directed retail investors concentrate demand in sub-ten-basis-point equity trackers.
Supply Chain Analysis
Single-source vulnerability sits with global investment banks providing authorized participant balance sheet capacity for primary market creation-redemption functions. Authorized participant networks concentrate in the United States, the United Kingdom, and Japan, with regional Asian banks lacking scale to backstop stress-period liquidity. The supply chain draws from proprietary index licensing agreements, fund administration platforms, and custody infrastructure. Tariff exposure on cross-border data transmission elevates operational risk for cloud-dependent NAV calculation services. Distribution runs through direct platform channels for institutional mandates and mobile-integrated brokerages for retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as fee compression eliminates sub-scale sponsors lacking proprietary indexing infrastructure or direct institutional relationships.
For Market Incumbents: Cement index-licensing exclusivity arrangements with benchmark providers ahead of MSCI reclassifications, particularly for Vietnam frontier market exposure. Acquire specialized fixed-income vehicle capabilities to capture insurance mandate rotations as regional rate cycles diverge. Authorized participant network density serves as the critical defensive moat against asset-light entrants. For New Entrants and Emerging Players: The mid-basis-point pricing gap between premium-tier BlackRock iShares products and economy-tier domestic sponsors creates white-space opportunity for factor-innovation specialists. Target carbon credit-linked thematic vehicles ahead of ASEAN sustainable finance taxonomy implementation. Deploy direct-to-institutional platform channels bypassing conventional wealth management intermediaries. For Investors and Strategic Acquirers: Regulatory sandbox approvals from Singapore's MAS Project Guardian serve as the leading indicator that tokenized fund infrastructure is reaching commercial viability. Position for acquisition of asset managers with established onshore China CSRC relationships and RMB-denominated product shelves. Watch for authorized participant concentration stress events as inflection signals for platform consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Index-Licensing Exclusivity Agreement | Secures benchmark access ahead of Vietnam MSCI reclassification, locking out competing sponsors. |
| Tokenized Creation Unit Pilot | Validates distributed ledger infrastructure through Singapore MAS Project Guardian regulatory sandbox. |
| Carbon Credit-Linked Product Launch | Captures institutional capital rotation toward ASEAN sustainable finance taxonomy compliance exposure. |
| Direct Institutional Platform Channel | Bypasses wealth management intermediary economics to capture sovereign wealth fund block trade margins. |
| Authorized Participant Network Expansion | Reduces single-source fragility by diversifying primary market creation-redemption balance sheet providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia Pacific ETF market analysis. Primary interviews with fund development executives, authorized participant trading desks, index licensing specialists, and institutional portfolio managers combined with secondary validation from Japan FSA disclosure databases, SEBI FPI registration records, and CSRC product approval filings. Bottom-up asset flow tracking and top-down macro allocation surveys underwent triangulation to reconcile volume estimates.
Data-stream reconciliation across exchange-reported creation unit volumes, fund sponsor AUM disclosures, and broker-dealer transaction records informed the analytical framework. Segmentation modeling covered product type, investor category, asset class capitalization tier, and distribution channel complexity. CAGRs derived from historical flow trajectories and projected mandate shift assumptions across the analysis window. Forecast inputs incorporated regulatory sandbox progression timelines and MSCI index reclassification watchlist status.
Underlying measurement precision varies by segment; large-cap equity ETF flows carry tighter precision than frontier market small-cap estimates due to disclosure granularity differences. Forecasts reflect assumptions regarding Stewardship Code adoption velocity and Stock Connect quota expansion that could materially revise trajectory if regulatory priorities shift. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market
Capital Markets and Securities
US Capital Exchange Ecosystem Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Global Algorithm Trading Market