
 Stock Trading and Investing Applications Market | 2026-2036
Stock Trading and Investing Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Stock Trading and Investing Applications Market Analytics
Unbundling of research, execution, and advisory services is rebalancing how investors assemble their toolkits. Charles Schwab leverages its branch network and scale to anchor full-service relationships. Robinhood competes through zero-commission mechanics that attract first-time equity buyers.
Stock trading and investing applications are software platforms that facilitate order routing, portfolio analytics, and real-time market data delivery through APIs and cloud infrastructure, serving both self-directed and advised wealth management workflows. Commission-free service models now dominate retail onboarding flows, while robo-advisory segments capture automated allocation demand from younger accumulators. Mobile app platform types command the highest session frequency, though desktop applications retain dominance among active day traders requiring multi-monitor execution layouts.
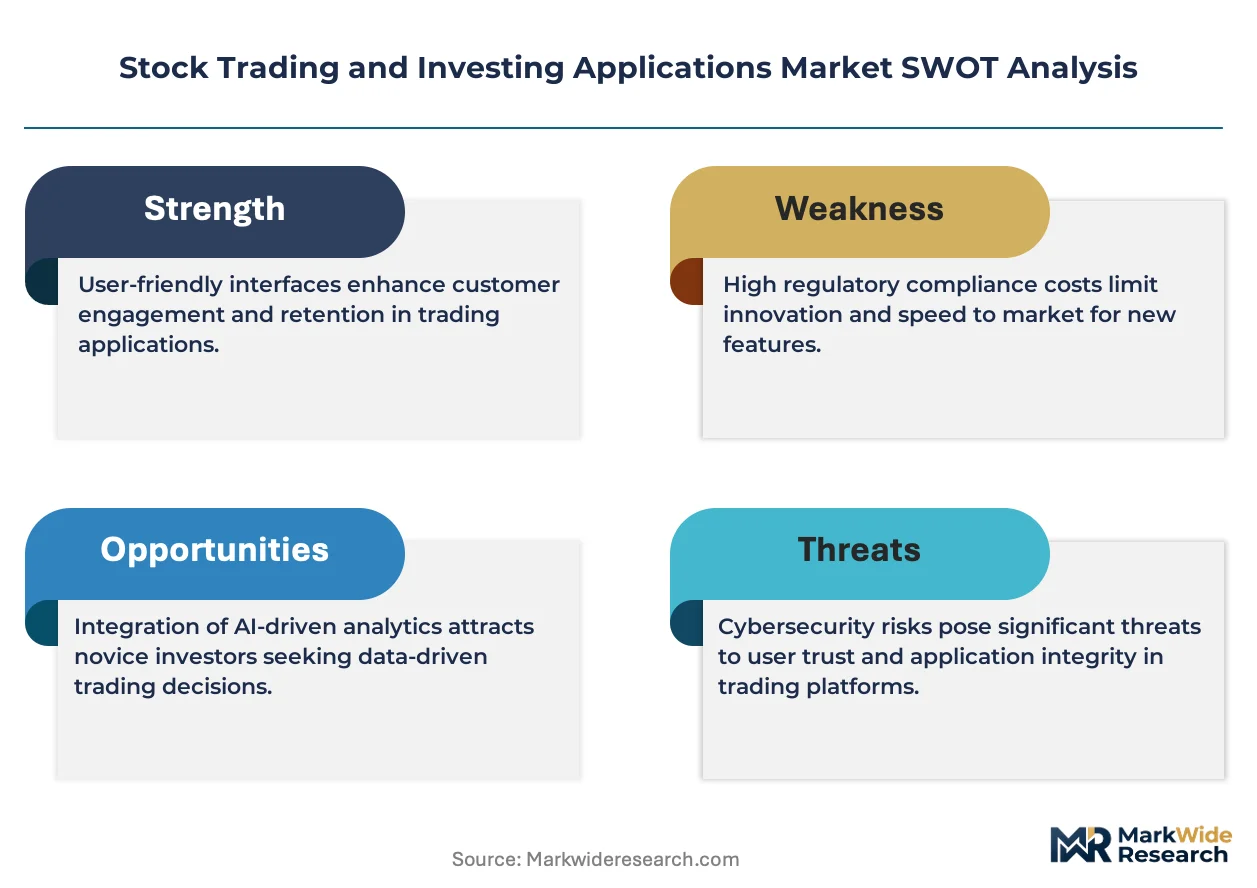
The SEC enforces disclosure standards around order routing and best execution, while FINRA supervises broker-dealer conduct and advertising claims, collectively elevating compliance costs for platform operators. The EU AI Act and GDPR impose parallel constraints on European-deployed algorithmic recommendation engines and client data handling. Stakeholders must monitor how jurisdictional fragmentation in digital asset classification reshapes product roadmaps and licensing requirements.
Market Dynamics
Payment for order flow economics faces structural pressure as SEC disclosure mandates intensify scrutiny of retail execution quality, forcing platforms to rebuild revenue architectures around subscription tiers and securities lending.
Growth Catalysts
- Zero-commission mechanics:Commission-free entry points pull first-time equity buyers into self-directed workflows, expanding the retail participant base beyond traditional brokerage demographics.
- API infrastructure:Open banking interfaces and real-time data feeds enable third-party developers to embed trading functionality into personal finance and wealth management ecosystems.
- GDPR-aligned data portability:European regulatory frameworks for client data control accelerate platform investments in cross-border account aggregation and unified portfolio views.
Market Restraints
- Cloud compute concentration:AWS, Google Cloud, and Microsoft Azure dominate platform infrastructure, creating single-provider vulnerability for latency-sensitive order routing systems.
- FINRA advertising scrutiny:Enhanced supervision of performance claims and risk disclosures extends compliance review cycles and raises legal overhead for customer acquisition campaigns.
- Crypto-asset substitution:Digital asset platforms siphon speculative trading volume from traditional equity applications among cohorts under 35.
Strategic Opportunities
- India's demat account expansion:SEBI's simplified KYC protocols and mobile-first onboarding protocols open access to 140 million new retail investors in secondary markets.
- AI-actuarial convergence:Machine learning-driven risk scoring merges with automated portfolio rebalancing to serve mass-affluent segments previously requiring human advisor relationships.
- Embedded finance channels:Neobanks and payroll platforms integrate fractional share purchasing at point-of-salary, capturing systematic investment behavior before traditional brokerage consideration.
Industry Challenges
- Quantitative developer scarcity:Platforms compete for talent capable of building low-latency matching engines and real-time risk systems, compressing engineering compensation bands.
- Multi-jurisdiction licensing:Fragmented digital asset classifications across EU member states, UK FCA, and US state-level money transmitter rules delay product launches by 12-18 months.
- Core banking integration:Legacy custodian APIs lack standardization, forcing bilateral technical builds for each clearing relationship and inflating operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stock Trading and Investing Applications Market |
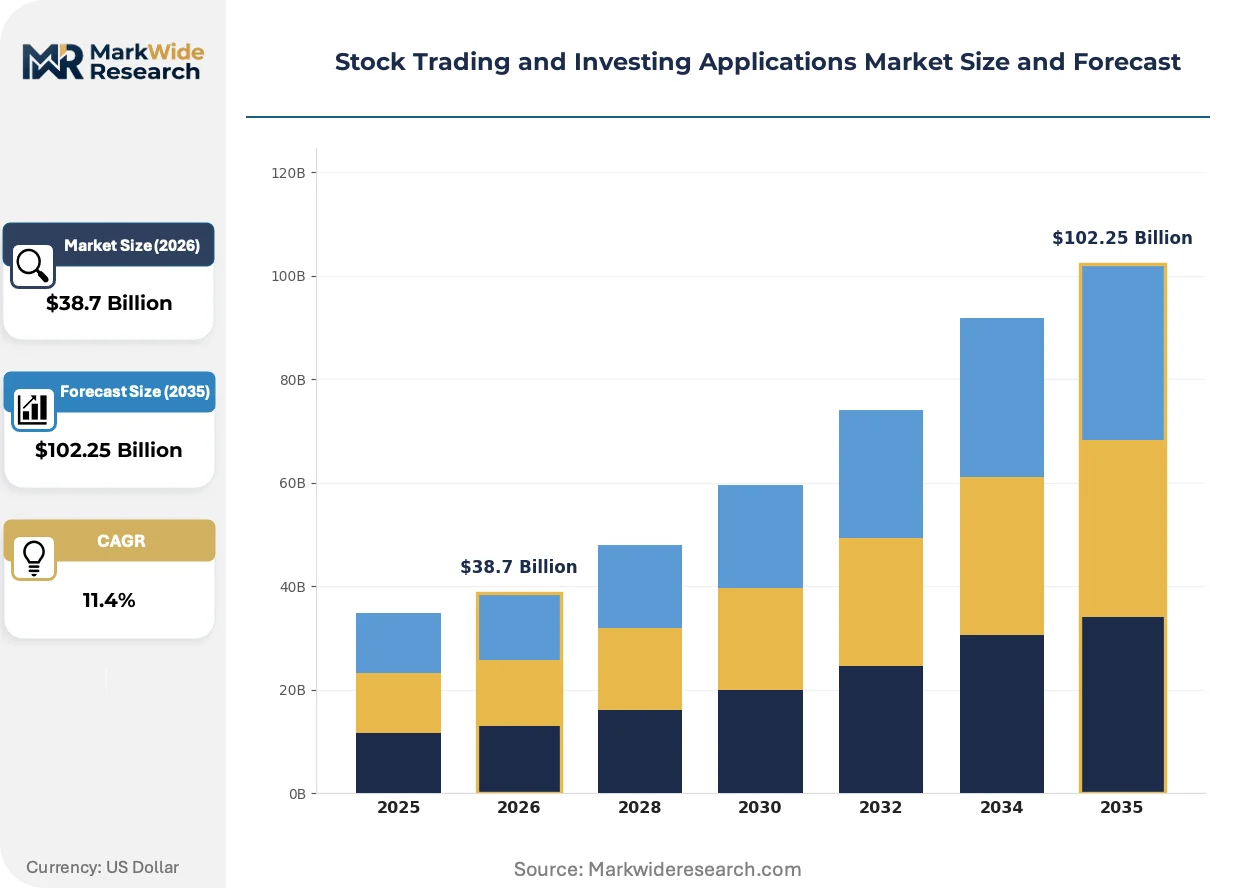
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Equities, ETFs, Mutual Funds, Options Platform Type: Web-Based, Mobile App, Desktop Application, Trading Software User Category: Retail Investors, Institutional Investors, Day Traders, Swing Traders Service Model: Commission-Free, Full-Service Brokerage, Robo-Advisors, Managed Accounts |
| Companies Covered | Charles Schwab, Fidelity Investments, Robinhood, E*TRADE, Interactive Brokers, eToro, Morgan Stanley, Webull, Vanguard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stock Trading and Investing Applications Market Evolving Landscape
Real-time payment rails and fractional share mechanics are dissolving minimum balance barriers, while regulatory technology investments automate compliance workflows previously handled through manual oversight.
Embedded trading interfaces are expanding into neobank and payroll applications, allowing salary-linked micro-investing at point-of-credit. Younger accumulators adopt these channels faster than traditional brokerage onboarding flows. This convergence is compressing customer acquisition costs and redirecting platform development resources toward white-label API architectures.
SEC best-execution disclosure amendments now require granular reporting of order routing economics and price improvement metrics. Broker-dealers restructure internalization arrangements and enhance transaction cost analysis tooling. Active traders in the United States demand this transparency as a selection criterion, shifting competitive emphasis from headline commissions to execution quality verification.
Self-directed investors increasingly unbundle research from execution, subscribing to independent analyst channels and social sentiment platforms while maintaining transactional relationships with low-cost clearing venues. This behavior fragments revenue per user across multiple providers. Platform operators in North America and Western Europe respond by acquiring content assets or building proprietary research marketplaces to recapture wallet share.
Stock Trading and Investing Applications Market Segmentation
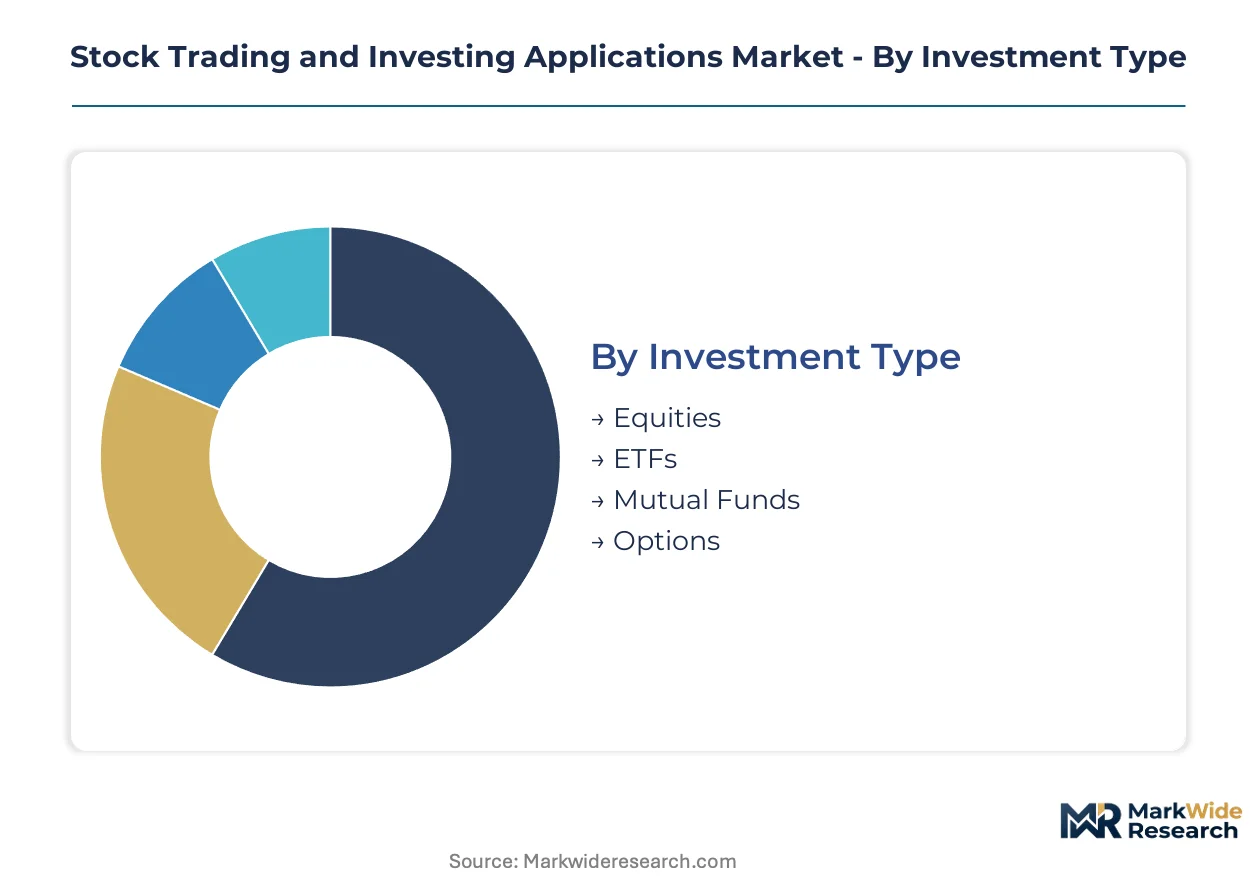
Segmentation in stock trading applications reveals how platform operators architect revenue streams and user experiences around distinct behavioral profiles. Each dimension—asset class, interface modality, investor sophistication, and service tier—commands different infrastructure investments and compliance postures.
Investment Type:
Customization intensity spans from standardized equity execution to complex multi-leg derivatives workflows, with each asset class demanding specialized clearing relationships and risk frameworks.
- Equities:Direct share ownership through common and preferred stock transactions forms the foundational liquidity layer for retail onboarding. Demand concentrates among first-time investors in the United States seeking fractional share access, constrained by SEC best-execution disclosure requirements that elevate platform transparency investments.
- ETFs:Exchange-traded funds bundle diversified exposure with intraday liquidity, appealing to cost-sensitive accumulators pursuing passive strategies. Demand concentrates in tax-advantaged retirement accounts, driven by fee compression that pushes platforms toward securities lending and payment-for-order-flow economics.
- Mutual Funds:NAV-based pooled vehicles retain dominance in advised wealth management workflows through 401(k) and IRA channels.
- Options:Multi-leg derivatives strategies require specialized approval workflows and margin infrastructure, serving experienced traders with elevated risk tolerance.
Most installed capacity flows through Equities. Expansion is steepest in ETFs.
Platform Type:
Interface modality determines session frequency, feature depth, and monetization architecture across the customer lifecycle.
- Mobile App:Touch-optimized interfaces dominate daily check-in behavior and push-notification engagement, with biometric authentication and simplified order entry reducing friction. Demand concentrates among investors under 35, driven by commission-free mechanics that eliminate account minimum barriers and embed social features.
- Desktop Application:Multi-monitor layouts with Level II quotes and advanced charting serve active intraday participants requiring sub-second execution. Demand concentrates among pattern day traders in the United States, constrained by FINRA margin rule compliance and pattern day trader minimum equity requirements.
- Web-Based:Browser-accessible platforms balance accessibility with moderate analytical depth for intermittent users.
- Trading Software:API-first terminals and algorithmic execution engines cater to quantitative developers and institutional connectivity.
User engagement peaks through Mobile App interfaces. Feature monetization concentrates in Trading Software.
User Category:
Investor sophistication stratifies across holding periods, order complexity, and advisory dependency.
- Retail Investors:Self-directed individuals executing personal financial decisions through taxable and tax-advantaged accounts, typically with smaller position sizes and longer holding periods. Demand concentrates in the United States through commission-free platforms, driven by simplified KYC flows and educational content libraries that reduce onboarding friction.
- Institutional Investors:Asset managers, pension funds, and hedge funds executing block trades with customized algorithms and direct market access. Demand concentrates among quantitative strategies requiring colocated infrastructure, constrained by MiFID II transaction cost analysis mandates in European deployment.
- Day Traders:Intraday position holders exploiting volatility with leveraged accounts and technical analysis tools.
- Swing Traders:Multi-day position holders balancing momentum capture with reduced screen-time requirements.
Account volume skews toward Retail Investors. Revenue per user peaks with Institutional Investors.
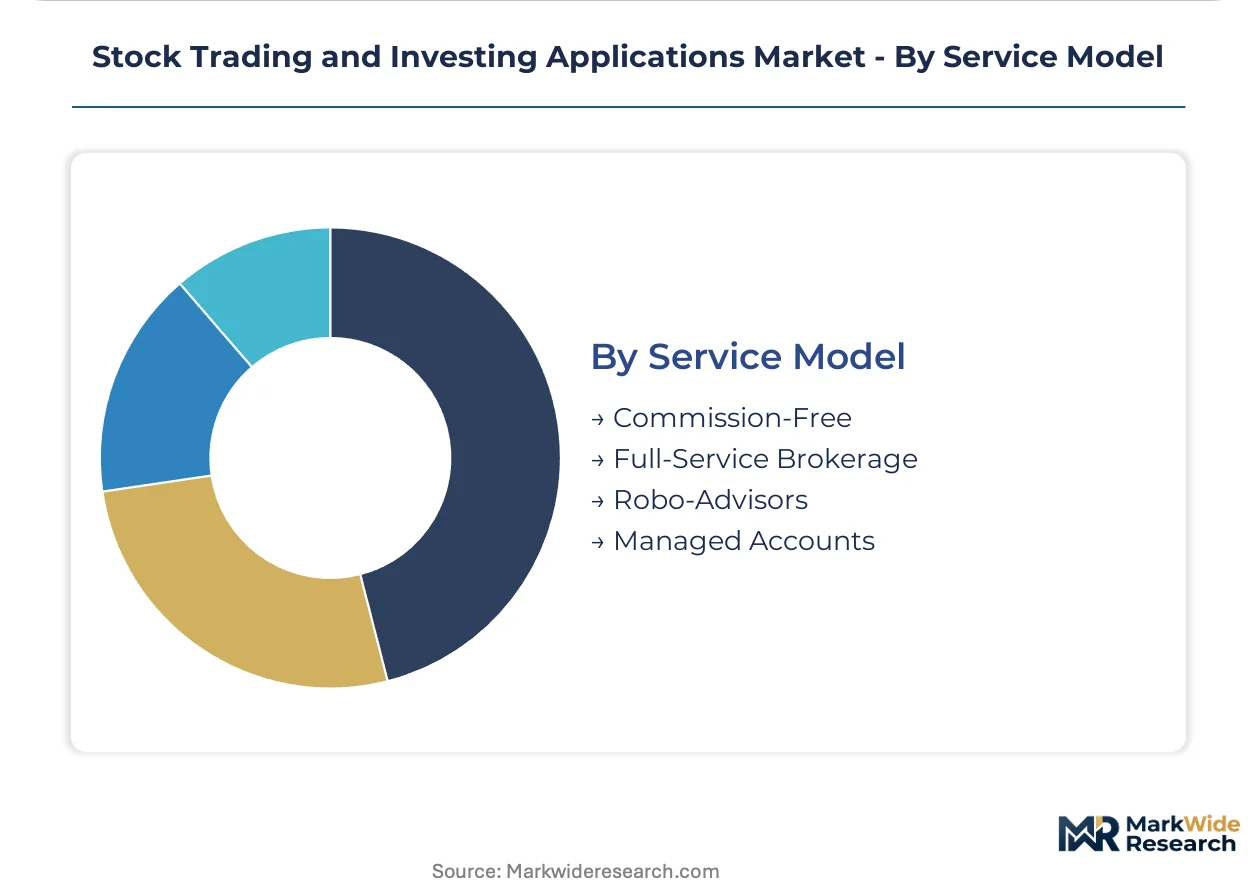
Service Model:
Economics range from zero-commission user acquisition to high-touch advisory relationships with layered fee structures.
- Commission-Free:Zero-transaction-cost entry points monetized through payment for order flow, securities lending, and premium subscription tiers. Demand concentrates among first-time equity buyers, driven by mobile-first onboarding that compresses account opening to under ten minutes.
- Robo-Advisors:Automated allocation engines using questionnaire-driven risk profiling and systematic rebalancing. Demand concentrates among mass-affluent accumulators seeking tax-loss harvesting, constrained by SEC investment adviser registration and fiduciary duty obligations.
- Full-Service Brokerage:Human advisor relationships with research access and financial planning integration.
- Managed Accounts:Discretionary portfolio management with personalized investment policy statements and performance reporting.
Customer acquisition flows through Commission-Free models. Advisory margin concentrates in Managed Accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The stock trading application industry traces its modern lineage to the United States, where electronic communication networks displaced floor-based trading in the 1990s and mobile-first brokerage later democratized market access. Platform economics and regulatory frameworks established there subsequently diffused to other developed and emerging markets. Today, demand concentrates in jurisdictions with deep capital markets, favorable fintech policy, and rising retail participation.
United States
Mobile-first brokerage penetration remains deepest among developed economies, with commission-free platforms capturing first-time equity buyers. SEC best-execution disclosure amendments now require granular reporting of order routing economics and price improvement metrics. New York and San Francisco anchor the fintech cluster, housing headquarters for platforms that set industry-wide user experience standards.
United Kingdom
Retail investor adoption surges through neobank-integrated trading interfaces and fractional share mechanics. FCA supervision of crypto-asset promotions and investment platform conduct elevates compliance architecture requirements. London's Square Mile and Canary Wharf concentrate institutional connectivity providers and regulatory technology vendors serving European-deployed platforms.
India
Demat account expansion accelerates through SEBI's simplified KYC protocols and mobile-first onboarding reaching 140 million new retail investors. RBI oversight of payment aggregation and digital lending creates licensing complexity for salary-linked micro-investing products. Mumbai and Bangalore host the dominant fintech development centers building low-latency matching engines for domestic exchanges.
Germany
Neo-broker adoption concentrates among accumulators seeking ETF-based passive strategies through tax-advantaged wrappers. BaFin enforcement of MiFID II transaction cost analysis mandates shapes platform disclosure requirements. Frankfurt's financial district and Berlin's startup ecosystem bifurcate between institutional infrastructure providers and consumer-facing application developers.
Japan
Retail participation in equities recovers through government-promoted NISA tax-exempt accounts and simplified mobile interfaces. FSA guidelines on suitability and complex product sales constrain options and leveraged product onboarding flows. Tokyo's Nihonbashi district and Osaka's financial center house incumbent brokerage technology divisions modernizing legacy core banking integrations.
Stock Trading and Investing Applications Market Competitive Landscape
The competitive structure tilts toward diversified financial conglomerates with captive brokerage technology. Tier-one operators leverage balance sheet scale to subsidize zero-commission user acquisition, while specialized platforms compete through execution quality differentiation and API-first architectures. Three archetypes dominate: full-service incumbents with branch networks, mobile-native disruptors with viral onboarding mechanics, and institutional-focused specialists with direct market access infrastructure. Competitive moves concentrate on M&A for content assets and strategic partnerships for embedded finance distribution.
Within the full-service incumbent tier, Charles Schwab and Fidelity Investments anchor positions through scale advantages in custody and advisory relationships. Robinhood occupies a defining position among mobile-native platforms that restructured retail onboarding economics. Interactive Brokers exemplifies the institutional-specialist archetype with multi-currency margin infrastructure and algorithmic execution tooling.
| Leading Market Players |
|---|
| Charles Schwab |
| Fidelity Investments |
| Robinhood |
| E*TRADE |
| Interactive Brokers |
| eToro |
| Morgan Stanley |
| Webull |
| Vanguard |
| Others |
Value Network & Pricing Analysis
Retail investor demand for commission-free execution has forced platform operators to dismantle traditional fee architectures and reconstruct monetization around payment-for-order-flow arrangements and securities lending programs. This buyer-driven compression cascades backward through clearing relationships, compressing per-transaction economics for custodians and reshaping infrastructure investment priorities toward volume-scaled automation.
Pricing Analysis
Zero-commission entry with tiered subscription upsells now dominates platform economics, separating basic execution from premium analytics and margin capabilities. Price differentiation rests on execution speed tiers and research access levels. Cost compression in retail onboarding is intensifying because customer acquisition spend concentrates on viral referral mechanics rather than traditional advertising. First-time equity buyers exhibit highest price sensitivity; active day traders demonstrate lowest sensitivity to subscription fees.
Supply Chain Analysis
Reverse-logistics flows for decommissioned trading terminals and refurbished server hardware circulate through certified electronics recyclers in the United States, Singapore, and Ireland. Cloud infrastructure draws from hyperscaler facilities concentrated in Virginia, Frankfurt, and Mumbai. Single-source vulnerability pervades matching engine colocation, where AWS Outposts and Azure Edge Zones dominate latency-sensitive deployments. Distribution runs through API-first brokerage platforms and white-label embedded finance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by structural retail participation growth in mobile-first brokerage, with regulatory technology spend creating durable recurring revenue streams for compliance-automation vendors.
For Market Incumbents: Anchor defensive positioning through captive custody infrastructure and advisory relationship density. Consolidate clearing relationships to capture securities lending economics that offset compressed transaction revenue. Threat from crypto-native platforms demands API-first architecture investment to retain speculative trading volume. Vertical integration into proprietary research marketplaces recaptures wallet share fragmented across independent analyst channels. For New Entrants and Emerging Players: Embedded finance partnerships with neobanks and payroll platforms offer the most penetrable route for systematic micro-investing capture. White-label API distribution to European neobanks exploits MiFID II disclosure gaps that disadvantage incumbent marketing. Target India's SEBI-simplified KYC corridor through mobile-native onboarding flows under ten minutes. For Investors and Strategic Acquirers: Asymmetric upside sits with regulatory technology vendors automating SEC and FINRA compliance workflows for mid-tier broker-dealers. Long-term viability favors platforms with diversified revenue beyond payment-for-order-flow, spanning subscription tiers and advisory fees. Monitor FINRA advertising scrutiny intensity as inflection indicator for customer acquisition cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Architecture | Enables embedded finance distribution through neobank and payroll partnerships. |
| Regulatory Technology Automation | Reduces SEC best-execution disclosure compliance costs for broker-dealers. |
| Fractional Share Infrastructure | Captures systematic investment behavior from accumulators with limited capital. |
| Securities Lending Program Expansion | Offsets compressed transaction revenue through inventory monetization. |
| Cross-Border Licensing Investment | Accelerates product launch timelines amid fragmented EU-UK-US regulatory divergence. |
Research Methodology
Direct dialogue with brokerage technology executives, clearing operations directors, regulatory compliance officers, and retail platform product managers grounded qualitative findings. Secondary validation drew from SEC disclosure filings, FINRA regulatory notices, SEBI circulars, and European Securities and Markets Authority technical standards. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Market size outputs and growth trajectories were derived through multi-dimensional segmentation incorporating platform type, user sophistication tier, service model economics, and regional regulatory cluster variations. CAGRs were computed from annualized progression rates across the projection horizon. Forecast inputs included retail account opening velocity, payment-for-order-flow revenue per user, and cloud infrastructure capex disclosures from hyperscaler partners.
The model assumes a particular technology adoption path; alternative pathways for decentralized finance infrastructure would alter the outlook for traditional platform intermediation. Forecasts reflect assumptions around regulatory stability and retail participation trends. Practitioners should monitor SEC disclosure mandate amendments and crypto-asset classification rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
Europe ETF Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market