
 UK Capital Exchange Ecosystem Market | 2026-2036
UK Capital Exchange Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
UK Capital Exchange Ecosystem Market Insights
Asset-light exchange infrastructure and third-party clearing models are fragmenting competitive barriers in UK capital markets. London Stock Exchange Group leverages its vertically integrated clearing and data franchise to sustain margin capture across the trade lifecycle. Globacap Limited specializes in blockchain-native primary issuance, positioning for regulatory acceptance of distributed ledger settlement. Intercontinental Exchange competes through its energy and commodity derivatives heritage, extending that infrastructure into European carbon and emissions contracts.
The UK Capital Exchange Ecosystem encompasses the integrated infrastructure of trading venues, clearinghouses, settlement systems, and regulatory technology that enables capital formation and secondary market liquidity across equity, debt, and derivative instruments, operating on sub-millisecond matching engines with throughput exceeding 100,000 messages per second. Its primary commercial purpose is to reduce counterparty risk, price discovery latency, and transaction costs for issuers and investors. Equity Trading anchors the revenue pool through persistent volatility and retail participation, while Blockchain infrastructure represents the fastest-growing segment as the Financial Conduct Authority advances its digital securities sandbox. Algorithmic Trading dominates order flow volume but faces margin compression from cloud-based execution services.
The Financial Conduct Authority's operational resilience framework and the Bank of England's CCP recovery and resolution regime are tightening system availability standards and liquidity provisioning requirements for UK trading infrastructure. The Prudential Regulation Authority's Basel III implementation shapes capital treatment of exchange-traded versus bilaterally cleared derivatives, redirecting flow toward central counterparties. Stakeholders must monitor how the UK Treasury's Edinburgh Reforms recalibrate the ring-fencing regime and whether HM Treasury's stablecoin legislation opens settlement architecture to non-bank tokenization providers.
Market Dynamics
The Bank of England's operational resilience framework is forcing trading infrastructure providers to reengineer system availability architectures, while pension fund allocations into alternative venues are fragmenting traditional liquidity concentration.
Growth Catalysts
- Tokenized Settlement Infrastructure:The Financial Conduct Authority's digital securities sandbox is accelerating regulatory acceptance of distributed ledger settlement for gilts and corporate bonds. Asset managers are piloting atomic settlement to compress counterparty risk windows.
- Carbon Derivatives Expansion:Intercontinental Exchange's European carbon futures complex is drawing liquidity from compliance buyers and speculative capital. The UK Emissions Trading Scheme is creating new hedging demand among energy-intensive industrials.
- Cloud-Native Matching Engines:Fintech clusters in London's Shoreditch and Canary Wharf are deploying sub-millisecond infrastructure without captive data center capex. This is lowering barriers for specialized trading venue launches.
Market Restraints
- CCP Capital Intensity:The Prudential Regulation Authority's Basel III implementation demands higher default fund contributions from clearing members. This is concentrating clearing participation among tier-one banks with balance sheet depth.
- Single-Point Infrastructure Risk:LCH SwapClear dominates sterling interest rate derivatives clearing. A service disruption would cascade through UK pension liability hedging programs.
- Substitute Venue Competition:European Union trading venues are capturing order flow that previously executed in London. The share of euro-denominated instruments cleared in UK CCPs has compressed since Brexit implementation.
Strategic Opportunities
- Scotland's Fintech Corridor:Edinburgh and Glasgow are developing custody and fund administration clusters with lower operational cost bases than London. HM Treasury's Edinburgh Reforms may relax ring-fencing constraints for regional headquarters.
- Stablecoin Settlement Rails:Pending legislation on fiat-referenced stablecoins could open non-bank tokenization providers to compete with traditional settlement banks. This would disintermediate correspondent banking layers.
- AI-Regtech Convergence:Natural language processing and machine learning are converging to automate trade surveillance and market abuse detection. This addresses the FCA's expanding transaction reporting mandates.
Industry Challenges
- Distributed Systems Engineering Talent:Building resilient matching engines requires specialists in low-latency C++ and kernel-bypass networking. Competition from high-frequency trading firms and hyperscale cloud providers constrains recruitment pipelines.
- Legacy Integration Complexity:Incumbent settlement infrastructure runs on COBOL-based core banking systems. Migration to API-native architectures demands parallel operation periods that strain operational risk budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Capital Exchange Ecosystem Market |
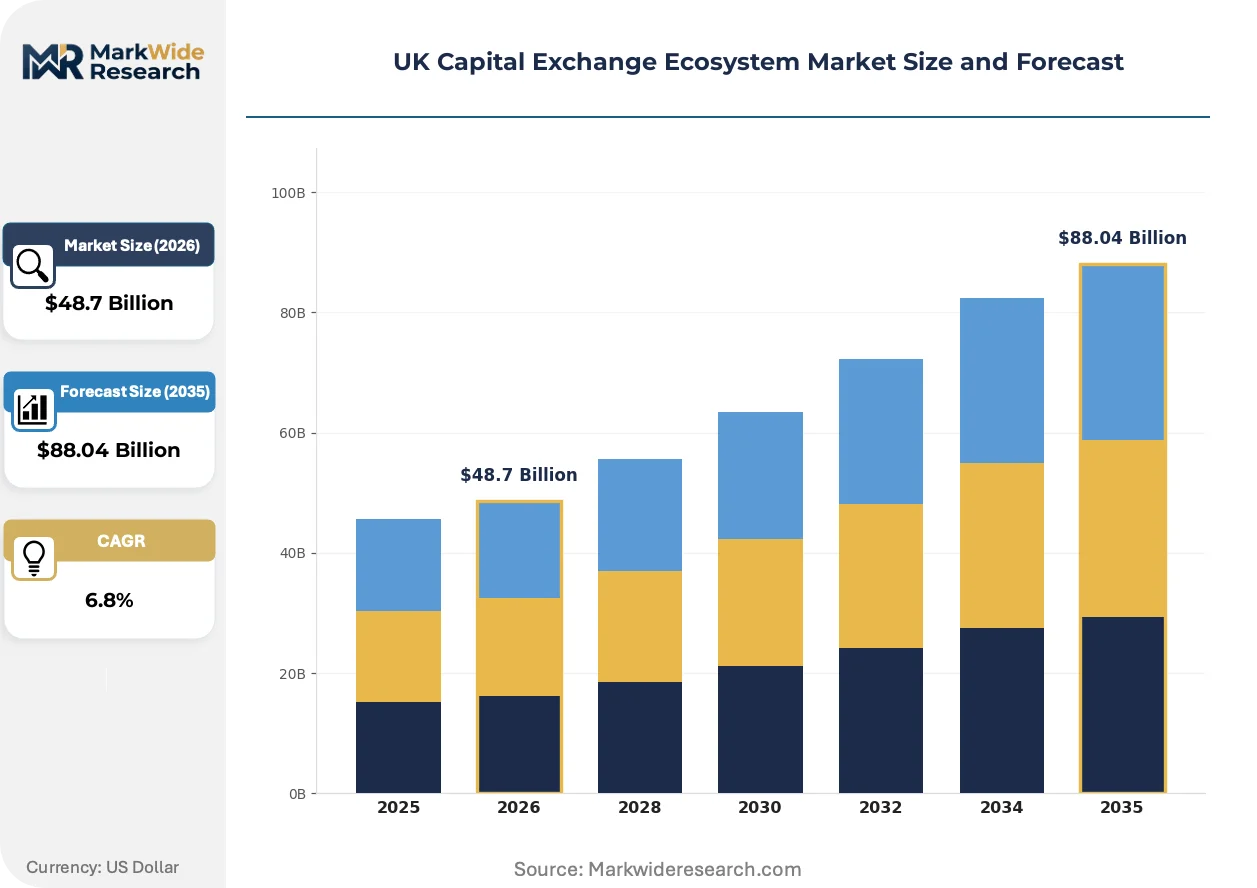
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Equity Trading, Debt Issuance, Asset Management, Market Making Investor Type: Institutional Investors, Retail Investors, Hedge Funds, Private Equity Technology: Blockchain, High-Frequency Trading, Algorithmic Trading, Cloud Computing Client Type: Corporates, Government Agencies, Financial Institutions, Individual Traders |
| Companies Covered | London Stock Exchange Group, Intercontinental Exchange, Euronext Group, Nasdaq, Globacap Limited, BSE Ltd., Japan Exchange Group, Hong Kong Exchanges and Clearing, Shanghai Stock Exchange, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Capital Exchange Ecosystem Market Trends and Innovations
Distributed ledger infrastructure is migrating from experimental pilots to production settlement layers, while regulatory sandboxes are compressing approval timelines for novel trading mechanisms.
Tokenized securities infrastructure is migrating from permissioned consortium networks to public-permissioned hybrid architectures. Primary issuance platforms are adopting this stack to enable atomic settlement and 24/7 trading cycles. The structural consequence is that custody and settlement functions are migrating from traditional bank intermediaries to specialized digital asset infrastructure providers.
The Bank of England's CCP recovery and resolution regime is mandating pre-funded default waterfall structures and binding liquidity provision commitments. Clearinghouses must now maintain resolution plans that specify how critical services continue through member default. Sterling interest rate derivatives clearing is most affected, with LCH enhancing its skin-in-the-game requirements and committed liquidity facilities.
Buy-side execution is fragmenting across specialized algorithmic providers rather than consolidating through single-broker relationships. Asset managers are unbundling research payments from execution commissions under MiFID II pressure. This pattern is most visible among UK pension funds and insurance asset managers, who are building direct connectivity to alternative trading venues to capture price improvement.
UK Capital Exchange Ecosystem Market Segmentation
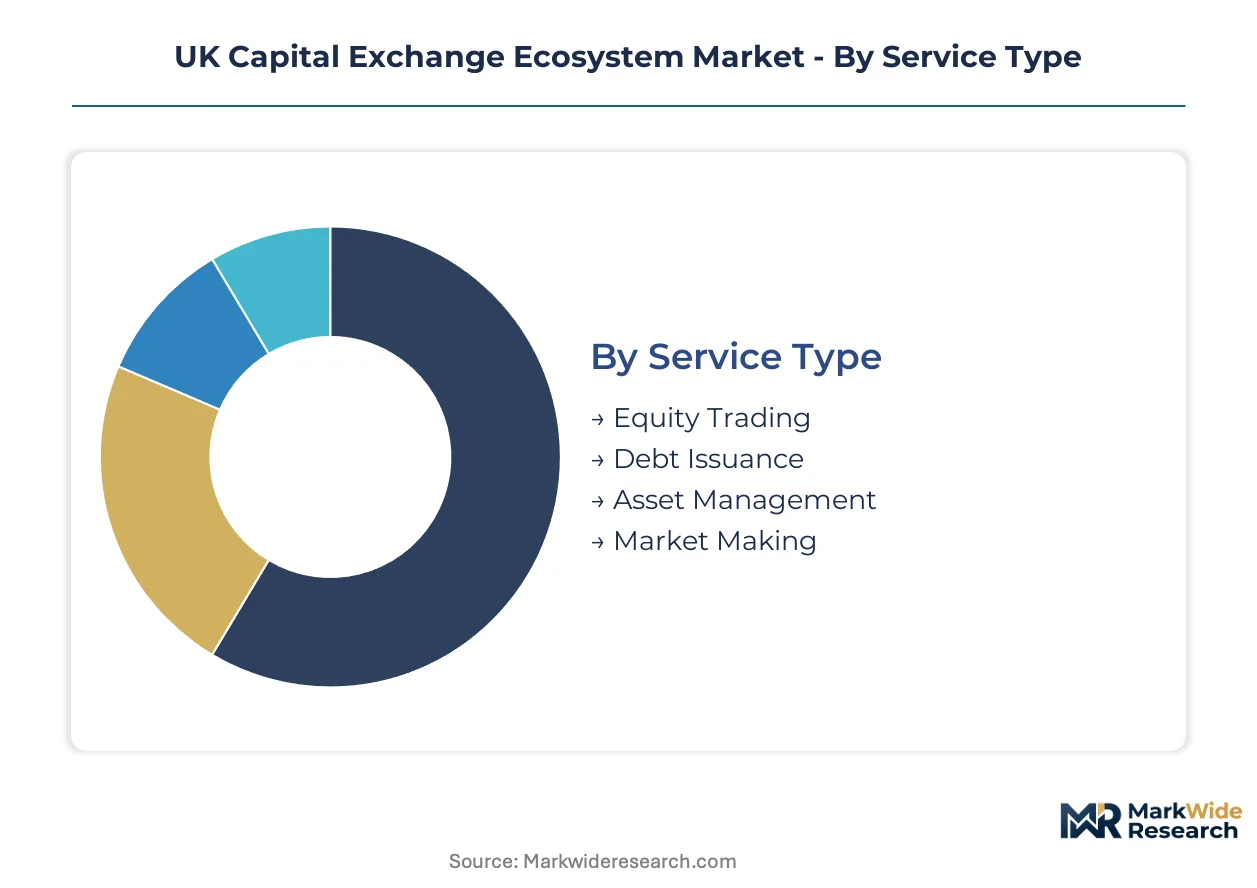
The UK Capital Exchange Ecosystem fragments across service models, investor sophistication, technology stacks, and client relationships. Each dimension shapes capital allocation patterns and infrastructure requirements differently across London's trading corridors.
Service Type:
Mature execution services anchor revenue stability while emerging issuance platforms capture regulatory tailwinds.
- Equity Trading:Electronic order matching across primary and secondary listings generates persistent transaction velocity. Demand concentrates among UK pension funds executing block trades through London Stock Exchange order books, driven by persistent volatility and retail participation expansion.
- Debt Issuance:Primary market origination for gilts and corporate bonds includes syndicated bookrunning and auction infrastructure. The Bank of England's gilt issuance program and ESG-linked corporate bond supply are concentrating demand in digital primary issuance platforms.
- Asset Management:Portfolio construction and fund administration services span active and passive strategies.
- Market Making:Continuous two-sided liquidity provision absorbs order flow imbalances across fragmented venues.
Equity Trading handles the majority of throughput; Debt Issuance is expanding most quickly on regulatory sandbox momentum.
Investor Type:
Institutional capital pools dominate absolute flow volumes while retail participation reshapes venue economics.
- Institutional Investors:Pension funds, insurance companies, and sovereign wealth vehicles deploy long-horizon capital through segregated mandates. UK defined-benefit pension schemes are concentrating allocations into alternative trading venues to capture price improvement outside traditional broker relationships.
- Hedge Funds:Absolute-return strategies employ leverage and derivatives across multi-asset class portfolios. London-based systematic funds are demanding co-location proximity and kernel-bypass networking to minimize execution latency.
- Retail Investors:Individual account holders access markets through execution-only platforms and mobile applications.
- Private Equity:Long-dated capital commitments fund buyout and growth equity transactions outside public market infrastructure.
Institutional Investors command the deepest order flow; Hedge Funds are gaining share fastest through systematic strategy proliferation.
Technology:
Legacy execution infrastructure coexists with experimental settlement architectures across divergent maturity curves.
- Algorithmic Trading:Rule-based and machine-learning order execution systems fragment large parent orders across time and venues. Asset managers unbundling research from execution under MiFID II pressure are concentrating demand in specialized algorithmic providers with direct venue connectivity.
- Blockchain:Distributed ledger infrastructure enables atomic settlement and 24/7 trading cycles for digital securities. The Financial Conduct Authority's digital securities sandbox is accelerating regulatory acceptance for gilt and corporate bond tokenization pilots.
- High-Frequency Trading:Sub-millisecond latency strategies exploit microstructural price dislocations.
- Cloud Computing:Elastic compute resources reduce captive data center capital requirements for venue operators.
Algorithmic Trading processes the dominant share of message traffic; Blockchain exhibits the steepest expansion trajectory as settlement infrastructure migrates to production deployment.
Client Type:
Corporate and government relationships anchor primary market activity while individual trader volumes drive retail platform economics.
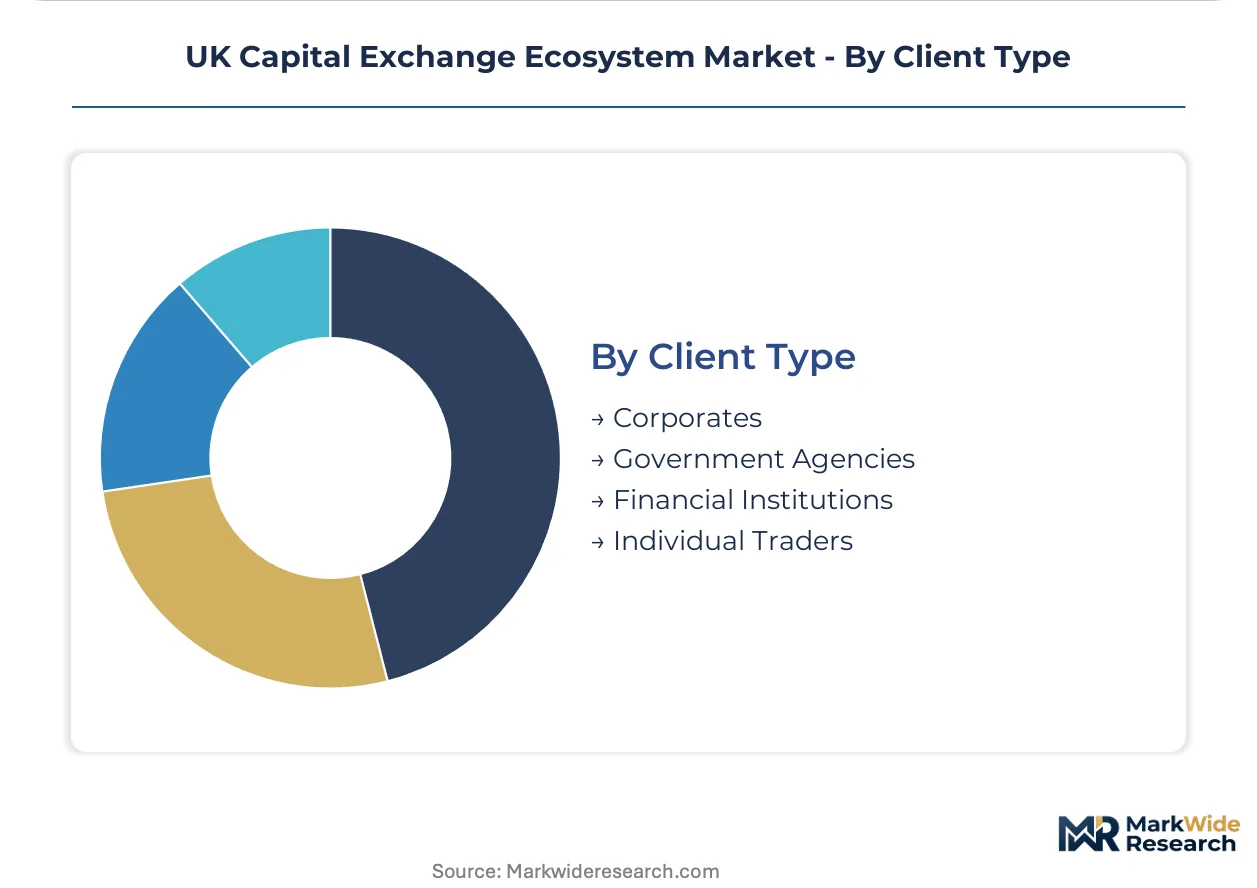
- Financial Institutions:Banks, broker-dealers, and asset managers intermediate capital flows across the trade lifecycle. Tier-one UK clearing banks are consolidating their roles as clearing members under Prudential Regulation Authority capital intensity requirements.
- Corporates:Non-financial issuers access equity and debt capital markets for strategic funding and liability management. UK-listed multinational corporations are piloting tokenized securities for shareholder registry modernization.
- Government Agencies:Sovereign and municipal borrowers raise funding through auction and syndication mechanisms.
- Individual Traders:Self-directed investors execute through direct market access and mobile brokerage applications.
Financial Institutions generate the highest revenue per relationship; Corporates are climbing the fastest on digital issuance platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK Capital Exchange Ecosystem generates substantial cross-border service exports through clearing and settlement infrastructure, while importing technology components and specialized engineering talent from international markets. This trade dynamic shapes regional clustering patterns across British financial centers.
London and the Southeast
Pension fund managers and asset-light fintech ventures drive demand for alternative trading venues and cloud-native matching engines. The Financial Conduct Authority's digital securities sandbox accelerates regulatory approval timelines for tokenized settlement pilots. Canary Wharf and Shoreditch clusters concentrate blockchain-native custody providers and sub-millisecond infrastructure deployments.
Scotland
Edinburgh and Glasgow develop custody and fund administration capabilities at lower operational cost bases than London competitors. HM Treasury's Edinburgh Reforms propose relaxing ring-fencing constraints for regional headquarters of financial institutions. The Scottish fintech corridor attracts digital asset infrastructure providers seeking regulatory arbitrage opportunities.
The Midlands
Legacy settlement system operators and COBOL-based core banking maintenance specialists concentrate in Birmingham and Nottingham. The Bank of England's operational resilience framework forces these incumbents to reengineer system availability architectures. Regional technology parks host parallel operation facilities for migration to API-native settlement stacks.
North England
Manchester and Leeds clusters specialize in retail brokerage platform development and mobile execution applications. The Prudential Regulation Authority's Basel III implementation redirects derivatives flow toward central counterparties with regional clearing member presence. Northern hubs capture back-office functions displaced from London cost pressures.
Wales and Northern Ireland
Cardiff and Belfast develop regulatory technology and trade surveillance automation capabilities. Natural language processing and machine learning specialists cluster here to address the FCA's expanding transaction reporting mandates. These regions compete on AI-regtech convergence talent at discount to London compensation benchmarks.
UK Capital Exchange Ecosystem Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in clearing, data, and custody layers. Vertically integrated exchange groups sustain margin capture across trade lifecycle stages while fragmented fintech clusters erode traditional barriers through cloud-native infrastructure. Three archetypes dominate: legacy exchange conglomerates with captive clearing franchises, blockchain-native issuance platforms, and specialized algorithmic execution providers. Competitive moves concentrate on M&A for data assets and strategic partnerships for distributed ledger settlement capabilities.
Among UK-based infrastructure operators, London Stock Exchange Group anchors the vertically integrated archetype through its clearing and data franchises. Intercontinental Exchange exemplifies the commodity-derivatives heritage model extending into carbon and emissions contracts. Globacap Limited occupies a position within the blockchain-native issuance tier, positioning for regulatory acceptance of distributed ledger settlement. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| London Stock Exchange Group |
| Intercontinental Exchange |
| Euronext Group |
| Nasdaq |
| Globacap Limited |
| BSE Ltd. |
| Japan Exchange Group |
| Hong Kong Exchanges and Clearing |
| Shanghai Stock Exchange |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on LCH SwapClear for sterling interest rate derivatives clearing determines both pricing tier compression across execution services and supply chain resilience investments by infrastructure operators. The Bank of England's CCP recovery regime is forcing clearing members to pre-fund default waterfalls, which concentrates pricing power among tier-one banks with balance sheet depth while fragmenting competitive supply alternatives.
Pricing Analysis
Institutional investors anchor execution pricing through volume-tiered transaction fees that compress as order flow concentrates in alternative trading venues. Price differentiation separates premium co-location proximity services from standard electronic access and economy retail brokerage tiers. Pricing pressure stems from cloud-native matching engines lowering barriers for venue launches. Retail platforms exhibit highest price sensitivity due to commission-free competition, while pension funds prioritize execution quality over marginal cost.
Supply Chain Analysis
Contract manufacturing concentration in UK-based data center operators and Irish cloud hyperscale facilities holds capacity for matching engine deployments. Geographic supply draws from Estonia for blockchain infrastructure talent, Singapore for regulatory technology components, and the United States for low-latency networking hardware. Raw material dependencies include specialized semiconductors for kernel-bypass networking, fiber optic cable for co-location connectivity, and cobalt for data center power backup systems. Supply chain risk centers on single-point infrastructure concentration at LCH SwapClear. Distribution runs through direct sales to financial institutions and API integrations with broker-dealer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Capital Exchange Ecosystem sits at a cyclical recovery phase driven by pension fund reallocation into alternative trading venues following volatility compression in traditional liquidity pools.
For Market Incumbents: Insulate clearing franchise margins by deepening default fund skin-in-the-game requirements that raise barriers for prospective entrants. Accelerate backward integration into proprietary data center infrastructure to reduce hyperscale cloud dependency and capture latency arbitrage premiums. The Prudential Regulation Authority's Basel III capital intensity rules favor incumbents with pre-positioned balance sheet capacity. For New Entrants and Emerging Players: Pursue Scotland's fintech corridor as the most penetrable geography given Edinburgh Reforms momentum and lower operational cost bases than London. Target tokenized settlement infrastructure as the whitespace application where regulatory sandbox approvals compress time-to-market versus traditional clearing authorization. Position through partnerships with pension fund administrators seeking price improvement outside established broker relationships. For Investors and Strategic Acquirers: The market sits at an infrastructure consolidation phase that favors vertically integrated exchange groups with captive clearing and data assets. Long-term viability hinges on regulatory capture of distributed ledger settlement standards before protocol ossification. Acquisition target archetypes include blockchain-native custody providers with FCA sandbox approvals. Monitor the UK Treasury's stablecoin legislation timeline as the inflection signal for settlement architecture disintermediation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Entry | FCA digital securities sandbox accelerates tokenized settlement approval timelines for gilt pilots. |
| Cloud Infrastructure Migration | Elastic compute deployment reduces captive data center capex for sub-millisecond matching engines. |
| Clearing Member Consolidation | Tier-one banks deepen default fund contributions under Prudential Regulation Authority Basel III rules. |
| Regional Headquarters Relocation | HM Treasury Edinburgh Reforms relax ring-fencing constraints for Scotland-based custody operations. |
| AI-Regtech Capability Build | Natural language processing automation addresses FCA transaction reporting mandate expansion. |
Research Methodology
Initial hypotheses were tested against primary input from exchange infrastructure executives, clearinghouse risk officers, pension fund portfolio managers, and fintech platform engineers and refined through secondary validation against Bank of England financial stability reports, FCA regulatory sandbox disclosures, LSEG and ICE exchange filings, and European securities settlement statistics. Bottom-up triangulation across venue throughput data and top-down reconciliation against UK financial services output metrics anchored value estimates.
Demand-supply balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, investor sophistication tier, technology stack maturity, and client relationship depth alongside geographic regulatory cluster differentiation. CAGRs were derived from trend extrapolation of pension fund allocation shifts and infrastructure investment cycles. Forecast inputs incorporated the Bank of England's operational resilience timeline and HM Treasury's legislative pipeline for stablecoin settlement.
Sensitivities concentrate around Brexit-related euro-denominated instrument migration, Edinburgh Reforms implementation pace, and distributed ledger protocol standardization outcomes. Forecasts reflect assumptions about regulatory sandbox graduation rates and clearing member default fund participation. Quarterly review of FCA authorization statistics and LCH SwapClear volume trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
Europe Mutual Fund Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Shadow Banking Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
Algorithmic Trading Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Stockbroking Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market