
 US Capital Exchange Ecosystem Market | 2026-2036
US Capital Exchange Ecosystem Market Size, Share, and Industry Trends Forecast 2026-2036
US Capital Exchange Ecosystem Market Insights
The direct listing channel is narrowing as alternative pathways to public markets gain institutional credibility. Nasdaq, Inc. leverages its technology stack to dominate cloud-based exchange infrastructure. CME Group Inc. anchors derivatives clearing through its captive clearinghouse network. Intercontinental Exchange (ICE) competes across asset classes with vertically integrated data and execution services.
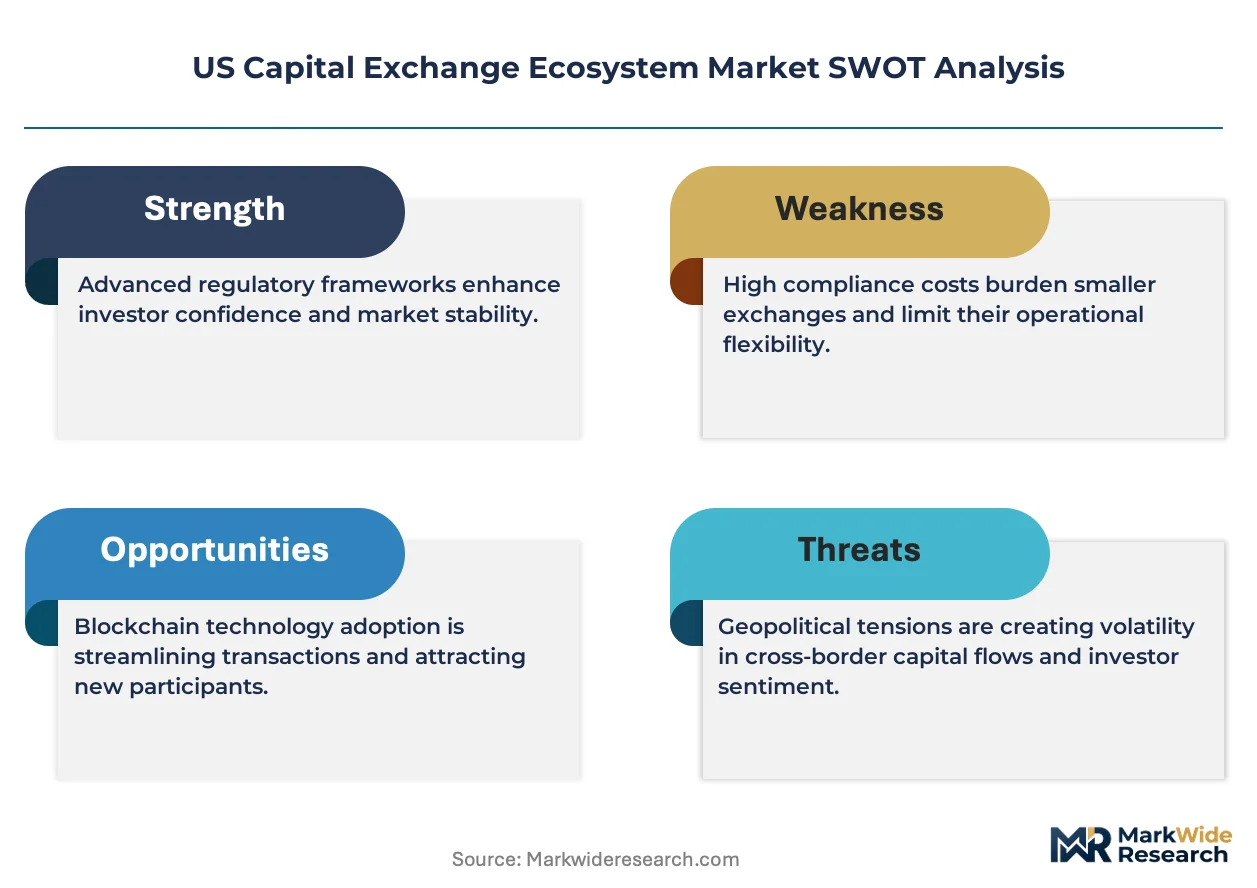
The US Capital Exchange Ecosystem encompasses regulated venues, alternative trading systems, and supporting infrastructure that facilitate price discovery, liquidity provision, and settlement for securities transactions across equity, debt, and derivatives instruments. These systems operate with sub-millisecond matching engines and T+1 settlement cycles to reduce counterparty risk. Brokerage and trading platforms capture the largest margin pools as commission compression shifts revenue toward data monetization and order flow arrangements. Derivatives and hybrid securities represent the fastest-growing product categories as institutional hedging demand expands.
The SEC, FINRA, and the Commodity Futures Trading Commission enforce market structure rules that determine venue access, best execution obligations, and capital reserve requirements for exchange operators. The SEC's proposed order competition rule would reshape retail order routing economics. Stakeholders must monitor regulatory divergence between Washington's reform agenda and state-level blue sky compliance burdens.
Market Dynamics
The SEC's order competition rule is compressing payment-for-order-flow economics while T+1 settlement mandates force infrastructure overhauls across clearing and custody operations. These dual pressures are restructuring how broker-dealers route retail orders and manage intraday liquidity.
Growth Catalysts
- Institutional derivatives hedging:Pension funds and asset managers are expanding notional exposure through CME Group's interest rate and equity index complexes. This demand pulls volume into centrally cleared instruments with standardized margining.
- SEC market structure reforms:Proposed best execution enhancements are accelerating venue competition for retail order flow. Broker-dealers are upgrading smart order routers to capture price improvement opportunities.
- Cloud-based matching engines:Exchange operators are deploying elastic compute infrastructure to handle volatility spikes without fixed capital overhead. This technology shift lowers barriers for new ATS entrants.
Market Restraints
- Clearing capital intensity:Depository Trust & Clearing Corporation's margin requirements for T+1 settlement compress broker-dealer balance sheet capacity. Firms must prefund settlement obligations earlier in the trading cycle.
- Concentrated data vendor dependence:Consolidated tape infrastructure relies on a narrow set of authorized processors. Pricing power asymmetries raise costs for downstream algorithmic trading firms.
- Regulatory fragmentation:State-level blue sky compliance obligations create friction for national order routing networks. Multi-state registration burdens favor incumbents with established legal infrastructure.
Strategic Opportunities
- Tokenized settlement infrastructure:Distributed ledger pilots at DTCC and private consortia are testing atomic settlement for equities and fixed income. Successful deployment would compress counterparty risk windows further.
- Retail direct indexing:Separately managed account platforms are disintermediating mutual fund wrappers. This channel creates demand for fractional share execution and tax-loss harvesting automation.
- Carbon derivatives expansion:CFTC-registered venues are listing voluntary carbon credit futures. Speculative and hedging interest from corporate sustainability desks is building liquidity in these contracts.
Industry Challenges
- Real-time risk system integration:T+1 settlement demands intraday margin monitoring across fragmented clearing relationships. Legacy batch-processing architectures at smaller broker-dealers require expensive replacement.
- Cross-venue surveillance coordination:FINRA's Consolidated Audit Trail mandates uniform order event reporting across 24 exchanges and 50+ ATS platforms. Data normalization across incompatible proprietary formats strains compliance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Capital Exchange Ecosystem Market |
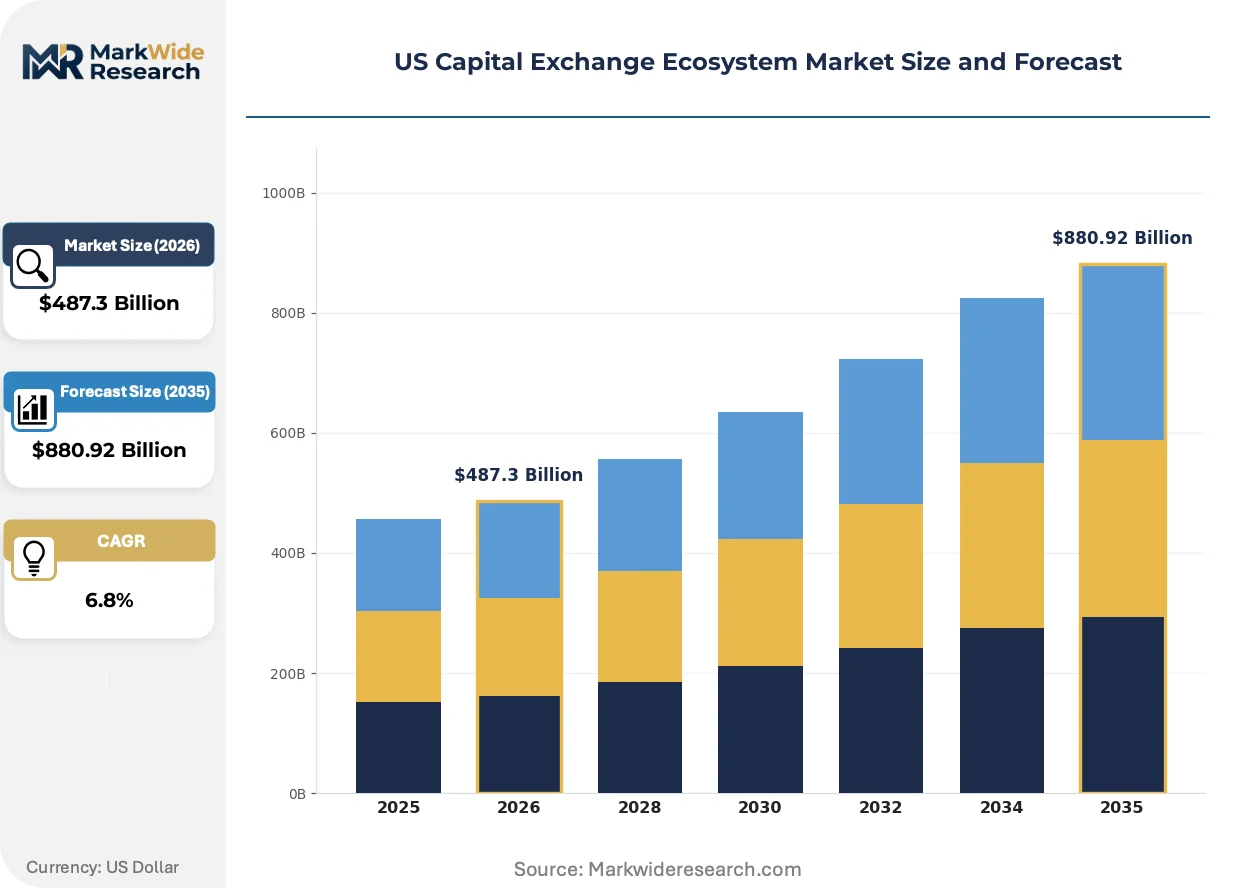
| Market Size in 2026 | $487.3 Billion |
| Market Size in 2035 | $880.92 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equity, Debt, Hybrid Securities, Derivatives Service Type: Brokerage, Trading Platforms, Custodial Services, Clearing Services Client Type: Institutional Investors, Retail Investors, Hedge Funds, Venture Capitalists Investment Stage: Seed Stage, Growth Stage, Mature Stage, Distressed Assets |
| Companies Covered | Intercontinental Exchange (ICE), Investors Exchange (IEX), New York Stock Exchange (NYSE), Long-Term Stock Exchange (LTSE), MEMX LLC, Nasdaq, Inc., CME Group Inc., OTC Markets Group, Cboe Global Markets, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Capital Exchange Ecosystem Market Trends and Innovations
Matching engine architecture is decoupling from physical data center footprints as exchange operators pursue latency arbitrage through geographic distribution and cloud proximity. This infrastructure shift is redrawing competitive boundaries between incumbent venues and technology-native entrants.
Exchange matching technology is migrating from co-located bare-metal deployments to containerized cloud instances with dynamic scaling. Tier-two broker-dealers and proprietary trading firms are adopting these elastic platforms to reduce fixed infrastructure commitments. The shift is compressing the historical advantage of incumbents with captive data center real estate.
The SEC's proposed order competition rule would mandate auction mechanisms for retail marketable orders. This regulatory push is forcing broker-dealers to rebuild order routing logic around price improvement rather than payment-for-order-flow economics. Retail-focused firms are most exposed, with some accelerating investments in alternative liquidity venues.
Institutional hedging desks are unbundling execution from research and compressing commission budgets toward explicit execution-only pricing. Asset managers are consolidating broker relationships around multi-asset platforms with integrated analytics. This consolidation is most visible among mid-sized RIAs in the Northeast corridor seeking operational leverage through vendor consolidation.
US Capital Exchange Ecosystem Market Segmentation
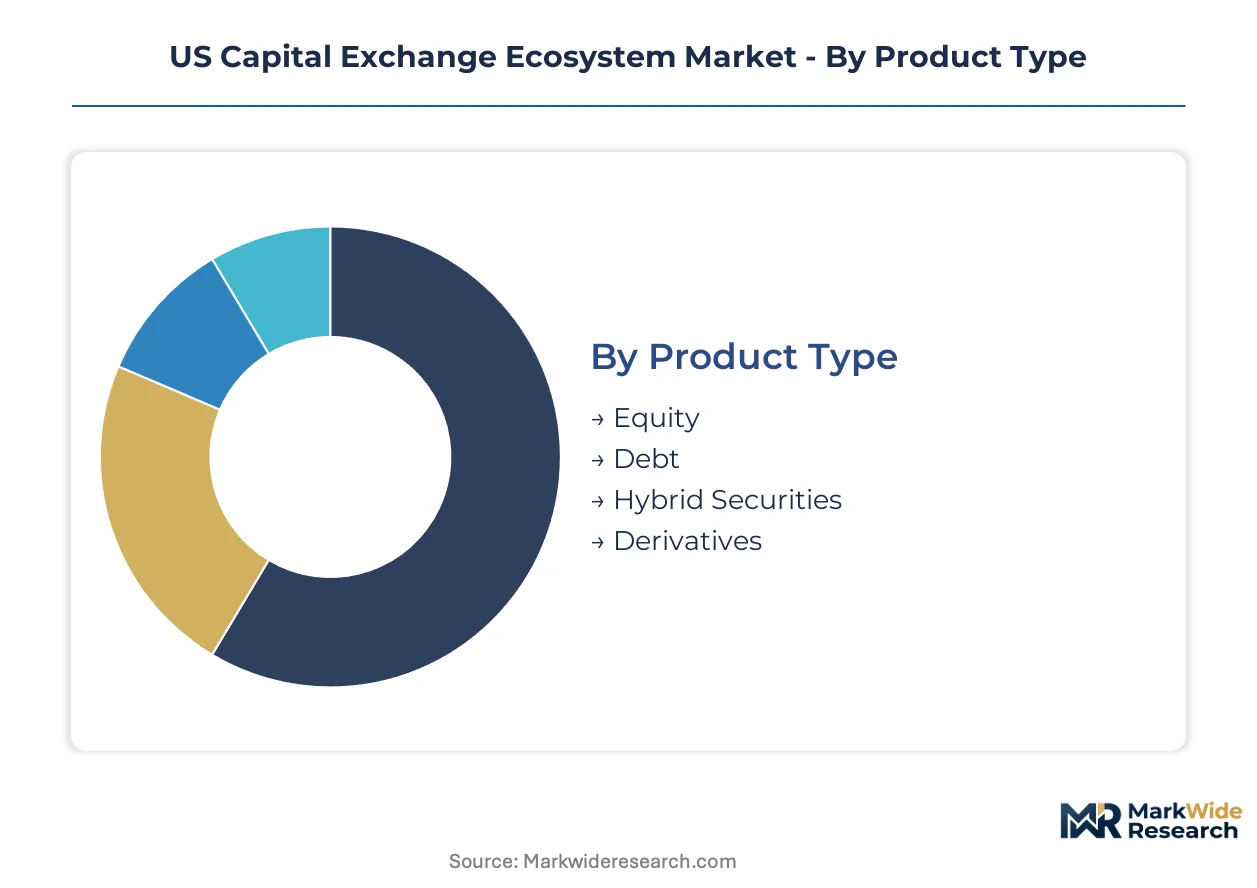
The US Capital Exchange Ecosystem fragments across instrument type, infrastructure service, client sophistication, and company maturity. Each dimension carries distinct velocity profiles and margin structures that determine competitive positioning.
Product Type:
Derivatives contracts turn over intraday while debt instruments sit in buy-and-hold portfolios for quarters or years.
- Equity:Common and preferred shares trade across 16 national securities exchanges and 50+ alternative trading systems. New York's financial district concentrates liquidity for large-cap listings, though retail order flow is fragmenting toward off-exchange venues under SEC market structure reforms.
- Derivatives:Futures and options contracts on interest rates, equity indexes, and commodities clear through CME Group's captive clearinghouse. Chicago's derivatives corridor anchors notional volume as pension funds expand hedging programs.
- Debt:Corporate bonds and municipal securities trade in dealer-intermediated markets with periodic electronic auction protocols.
- Hybrid Securities:Convertible bonds and preferred equity blend fixed income characteristics with equity optionality.
Equity anchors the volume base while derivatives gains share at the steepest rate.
Service Type:
Cost tier separates premium integrated platforms from execution-only utilities.
- Brokerage:Full-service and discount broker-dealers route orders across fragmented venues while managing best execution obligations. Commission compression is shifting revenue toward payment-for-order-flow arrangements and securities lending.
- Clearing Services:Central counterparty infrastructure at DTCC and OCC manages novation and margin collection for T+1 settlement cycles. Balance sheet intensity is rising as prefunding requirements compress intraday liquidity.
- Trading Platforms:Exchange matching engines and alternative trading systems compete on latency and market data feeds.
- Custodial Services:Bank and non-bank custodians safekeep assets and process corporate actions across fragmented account structures.
Brokerage captures the widest revenue pool while clearing services face the steepest margin pressure.
Client Type:
Volume concentrates with institutional accounts though retail participation is climbing fastest.
- Institutional Investors:Pension funds, mutual funds, and insurance companies execute block trades through specialized broker-dealers with customized analytics. Northeast corridor asset managers are consolidating vendor relationships around multi-asset platforms.
- Hedge Funds:Leveraged strategies demand prime brokerage services, securities lending, and delta-one synthetic exposure.
- Retail Investors:Direct indexing platforms and fractional share programs are disintermediating traditional mutual fund wrappers.
- Venture Capitalists:Private market participants access secondary liquidity through specialized ATS platforms and tender offer mechanisms.
Institutional investors anchor the volume base while retail investors gain share at the steepest rate.
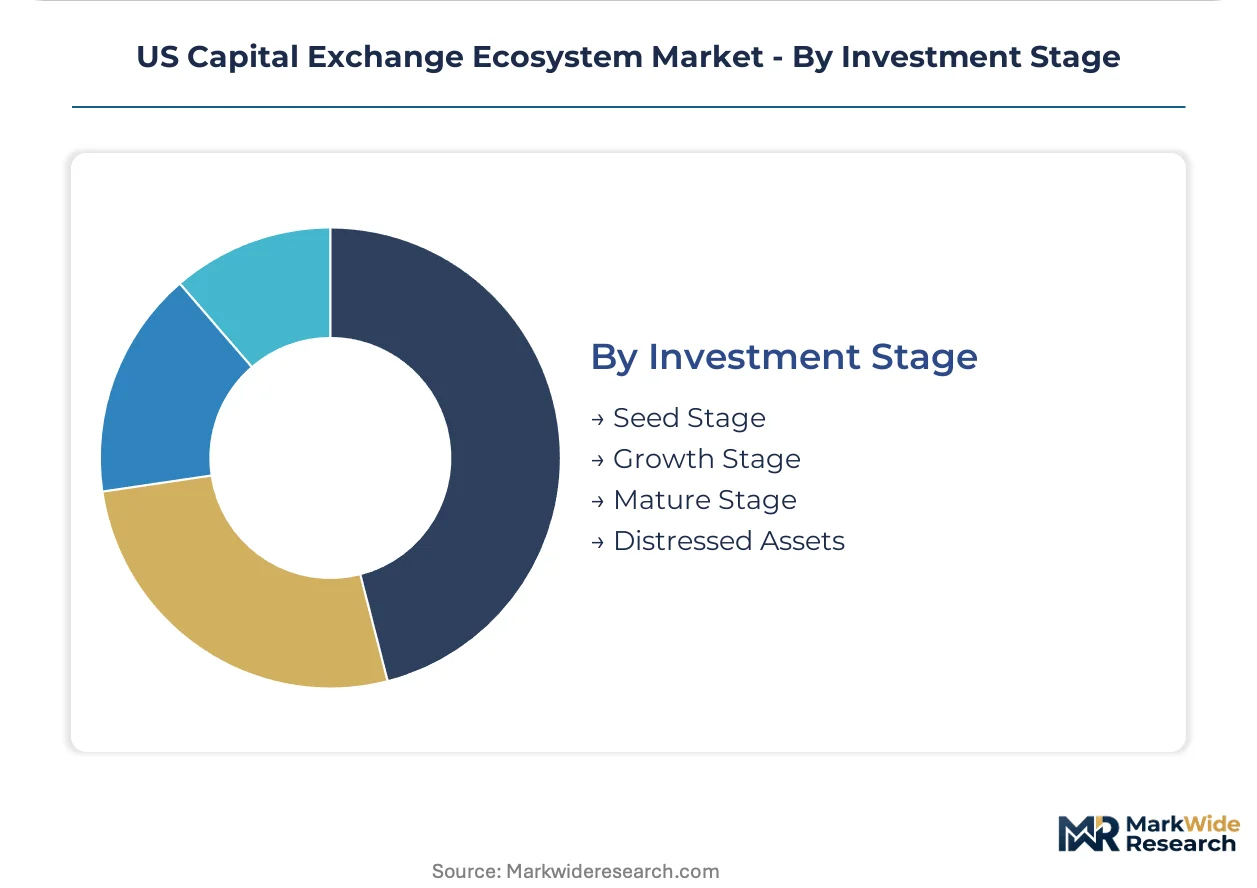
Investment Stage:
Maturity determines information asymmetry and liquidity access.
- Mature Stage:Public issuers with established trading histories access deep liquidity pools and standardized derivatives markets. Continuous disclosure requirements reduce due diligence friction for new capital formation.
- Growth Stage:Late-stage private companies navigate secondary trading platforms and pre-IPO tender programs.
- Seed Stage:Early venture financing operates through private placement frameworks with limited secondary liquidity.
- Distressed Assets:Bankruptcy claims and restructuring securities trade in specialized dealer networks with negotiated settlement terms.
Mature stage anchors the volume base while growth stage gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago Mercantile Exchange's fiber network anchors derivatives liquidity infrastructure, while the DTCC's Jersey City data centers underwrite settlement velocity. These physical assets concentrate trading gravity in specific metropolitan corridors.
New York Metro
Pension fund rebalancing and hedge fund prime brokerage sustain equity volume density. SEC best execution rules force broker-dealers to upgrade smart order routers for price improvement capture. Manhattan's financial district hosts Intercontinental Exchange and Nasdaq data centers where sub-millisecond matching engines process institutional block flows.
Chicago
Interest rate hedging by insurance companies and asset managers drives derivatives notional growth. CFTC margin requirements for futures clearing compress intraday liquidity windows. The Loop corridor anchors CME Group's captive clearinghouse network and proprietary trading firm co-location facilities.
Jersey City/Newark
DTCC's depository and clearing operations demand geographic proximity to Manhattan for latency-sensitive settlement. FINRA audit trail mandates force data normalization investments across fragmented venue feeds. The Hudson waterfront concentrates custody banks and securities lending infrastructure.
Boston
Asset manager consolidation around multi-asset platforms creates execution-only pricing pressure. State-level fiduciary rules for RIAs accelerate vendor relationship rationalization. The Seaport District anchors fintech infrastructure providers serving Northeast corridor wealth management platforms.
Dallas
Energy derivatives hedging by corporate treasuries builds liquidity in commodity futures complexes. CFTC swap dealer registration requirements raise compliance barriers for regional broker-dealers. The Uptown corridor hosts exchange data center expansions serving southwestern institutional accounts.
US Capital Exchange Ecosystem Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated exchange operators with captive clearing infrastructure. Tier-one venues leverage technology stacks to dominate cloud-based matching engine deployment. Three archetypes define competitive positioning: incumbent exchange operators with data center real estate, technology-native alternative trading systems, and specialized derivatives clearinghouses. Dominant competitive moves include strategic data center expansions and regulatory technology partnerships.
Within the incumbent exchange tier, Intercontinental Exchange and Nasdaq occupy positions defined by multi-asset data and execution integration. CME Group exemplifies the derivatives clearinghouse archetype through its captive infrastructure model. These operators represent the supply-side concentration that new ATS entrants must navigate through elastic cloud deployments.
| Leading Market Players |
|---|
| Intercontinental Exchange (ICE) |
| Investors Exchange (IEX) |
| New York Stock Exchange (NYSE) |
| Long-Term Stock Exchange (LTSE) |
| MEMX LLC |
| Nasdaq, Inc. |
| CME Group Inc. |
| OTC Markets Group |
| Cboe Global Markets |
| Others |
Pricing and Supply Chain Analysis
Manhattan's financial district concentrates matching engine capacity and co-location services, creating pricing power asymmetries that favor incumbent exchanges with captive data center real estate over cloud-native entrants seeking elastic compute.
Pricing Analysis
Volume-discount tiering structures dominate execution fees, with institutional block trades commanding lower per-share rates than fragmented retail flow. Price differentiation rests on latency proximity and market data feed quality, with premium tiers offering direct fiber access to matching engines. Pricing pressure stems from commission compression as broker-dealers shift revenue toward payment-for-order-flow arrangements and securities lending. Retail-focused platforms exhibit highest price sensitivity, while pension funds and hedge funds prioritize execution quality over marginal cost savings.
Supply Chain Analysis
Equinix and NYI hold concentrated contract-manufacturing capacity for exchange data center infrastructure, with CME Group and Intercontinental Exchange operating captive facilities. Geographic supply concentration centers on New Jersey, Illinois, and Texas for derivatives clearing and custody operations. Raw material dependencies include fiber optic cable, specialized semiconductors for matching engines, and redundant power systems. Single-source vulnerability runs through DTCC's centralized settlement infrastructure. Distribution runs through broker-dealer networks and direct market access platforms to end investors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across alternative trading systems and cloud-based matching engines creates white-space opportunities as SEC market structure reforms displace incumbent routing economics and open niches for technology-native entrants.
For Market Incumbents: Harden data center real estate advantages through geographic expansion into secondary liquidity corridors. Consolidate clearing infrastructure to capture T+1 settlement volume as balance sheet intensity rises. Defend against cloud-native ATS entrants by embedding regulatory technology partnerships that raise compliance barriers for elastic compute competitors.
For New Entrants and Emerging Players: Build out retail direct indexing platforms that disintermediate traditional mutual fund wrappers through fractional share execution and tax-loss harvesting automation. Target mid-sized RIAs in the Northeast corridor seeking vendor consolidation around multi-asset platforms. Lead with explicit execution-only pricing that unbundles research from commission budgets.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory capture play because SEC order competition rules and T+1 settlement mandates favor operators with established compliance infrastructure and captive clearing networks. Acquisition targets include specialized derivatives clearing technology and tokenized settlement pilots. Monitor CFTC carbon derivatives registration activity as speculative liquidity build indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Matching Engine Deployment | Elastic compute infrastructure lowers fixed capital barriers for new ATS entrants competing with incumbent exchanges. |
| Regulatory Technology Partnership | FINRA audit trail compliance and CAT data normalization investments strain smaller broker-dealer budgets. |
| Tokenized Settlement Infrastructure | DTCC distributed ledger pilots test atomic settlement compression for equities and fixed income instruments. |
| Retail Direct Indexing Platform | Separately managed account automation disintermediates mutual fund wrappers through fractional execution. |
| Carbon Derivatives Exchange Launch | CFTC-registered voluntary carbon credit futures attract corporate sustainability desk hedging demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with exchange technology executives, broker-dealer routing specialists, pension fund trading desk heads, clearing operations managers, and regulatory affairs counsel at FINRA and SEC. Secondary validation drew from SEC market structure rulemaking dockets, CFTC swap data repository filings, DTCC settlement volume statistics, and exchange operator SEC 10-K disclosures. Bottom-up venue volume aggregation and top-down ecosystem value triangulation were cross-referenced for consistency.
Calibration against historical T+1 adoption curves and derivatives notional growth patterns anchored the projection framework across the analysis window. Segmentation dimensions modeled include instrument type, infrastructure service tier, client sophistication level, and company maturity stage. CAGRs were derived from regression analysis of exchange participation rates and technology deployment cycles. Forecast inputs incorporated cloud infrastructure capex trajectories and regulatory implementation timelines for order competition rules.
Sensitivities concentrate around SEC rulemaking finalization schedules, DTCC margin requirement adjustments, and cloud service provider pricing volatility. Forecasts reflect documented assumptions regarding institutional hedging demand elasticity and retail platform adoption curves. Quarterly review of CFTC carbon derivatives contract registrations and tokenized settlement pilot outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
North America ETF Market
Capital Markets and Securities
Exchange Traded Fund Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
GCC Mutual Fund Market
Capital Markets and Securities
High-Yield Bonds Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
South America ETF Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
Securities Trading Software Market
Capital Markets and Securities
Armenia Stock Market
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Europe ETF Market