
 Europe Mutual Fund Market | 2026-2036
Europe Mutual Fund Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mutual Fund Market Insights
Institutional capital is rotating from traditional balanced mandates toward specialized fixed income and equity sleeves. Amundi leverages its pan-European distribution platform to capture this shift. BlackRock sustains dominance in passive vehicles through scale advantages in index replication. Schroders competes on active emerging market debt capabilities.
A mutual fund constitutes a pooled investment vehicle regulated under UCITS or AIFM frameworks, combining capital from multiple investors to purchase diversified portfolios of securities with daily net asset value calculation and redemption rights. Its primary commercial purpose is to provide regulated, liquid exposure to asset classes for investors lacking scale for direct portfolio construction. Equity funds occupy the largest share of European assets under management, reflecting persistent demand for long-term capital appreciation. Fixed income funds attract inflows during rate volatility as investors seek yield with defined duration exposure. Passive management strategies are gaining share against active mandates as fee compression intensifies across the retail channel.
The European Securities and Markets Authority enforces UCITS eligibility criteria and liquidity stress-testing requirements that shape product design and redemption mechanics. The EU Sustainable Finance Disclosure Regulation and taxonomy framework mandate classification of ESG integration levels, altering fund marketing and distributor due diligence. The Markets in Financial Instruments Directive II governs payment for order flow and best execution standards, affecting platform economics and fund selection processes. Stakeholders must monitor how the EU Retail Investment Strategy reforms alter cost disclosure rules and inducement structures across national distribution networks.
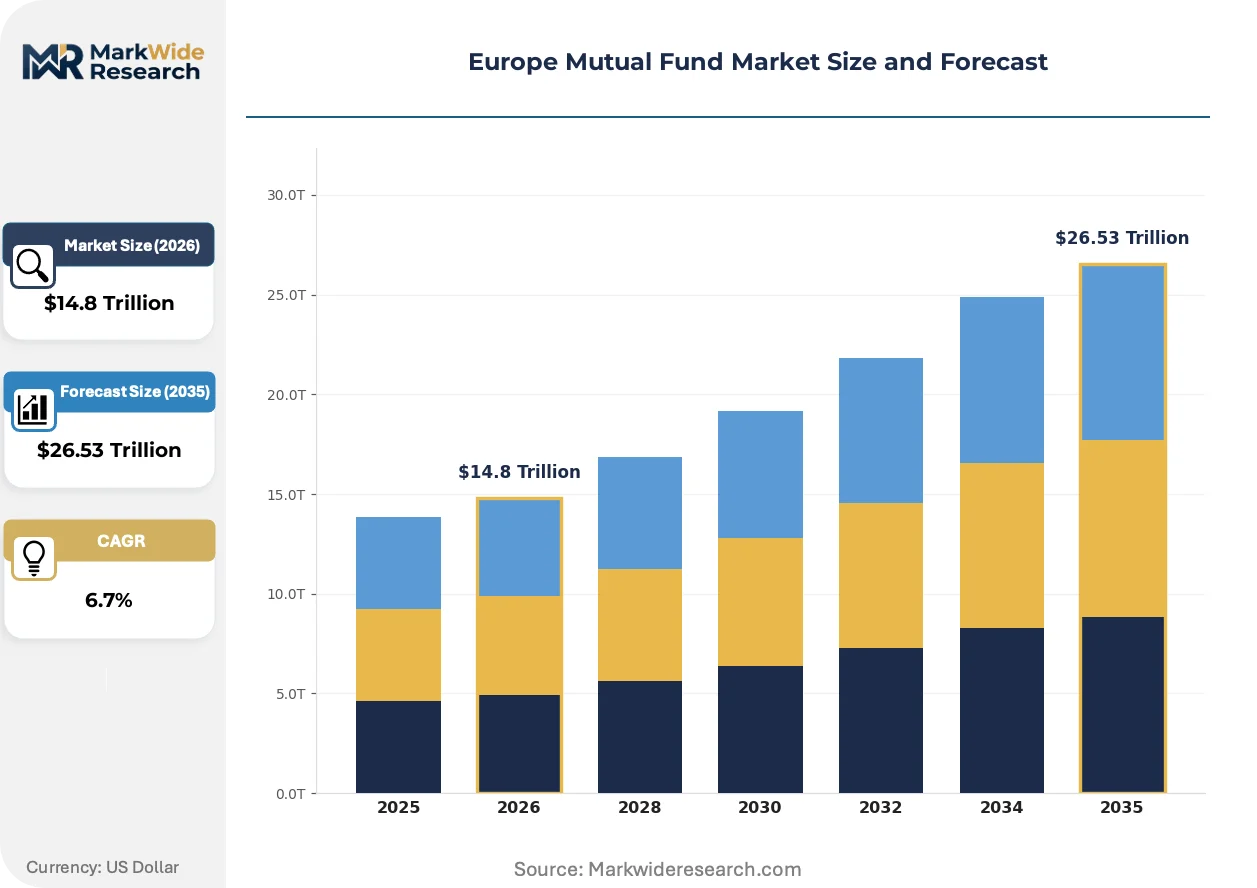
Market Dynamics
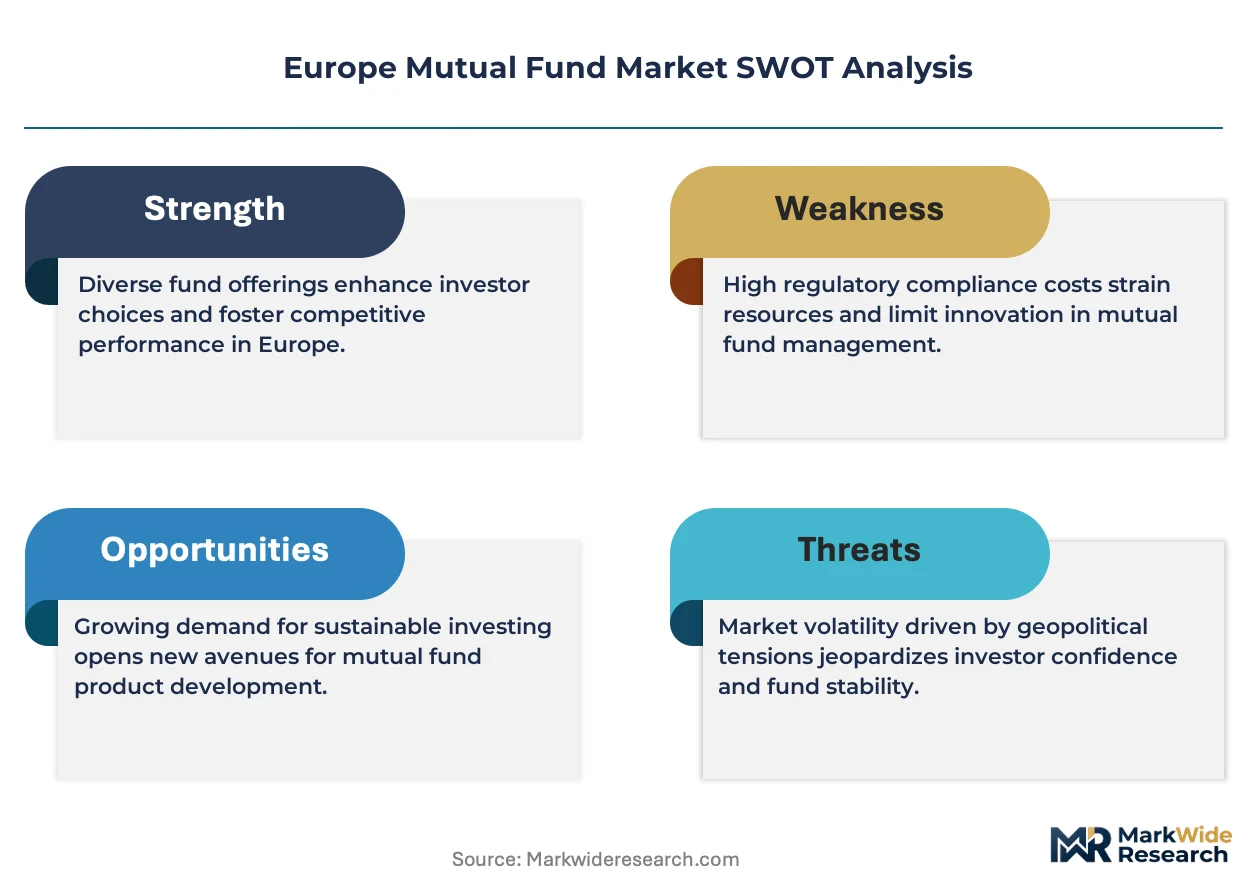
The European mutual fund sector is restructuring around the Sustainable Finance Disclosure Regulation's classification tiers, which mandate granular ESG transparency and redirect distributor due diligence toward Article 8 and 9 products. This regulatory architecture is compressing legacy fund architectures while elevating taxonomy-aligned vehicles.
Growth Catalysts
- SFDR Article 8/9 Mandates:The EU Sustainable Finance Disclosure Regulation's disclosure tiers compel asset managers to reclassify products, creating standardized ESG signaling that accelerates retail and institutional capital rotation into compliant vehicles.
- Pension Fund Reallocation:Dutch and German occupational pension schemes are expanding dedicated sleeves for actively managed European equity strategies, channeling defined-benefit liabilities into UCITS-structured vehicles with daily liquidity.
- Netherlands Distribution Hub Concentration:Amsterdam's fund platform infrastructure and favorable withholding tax treaties position the country as a cross-border distribution nexus for UCITS targeting Benelux and Nordic investors.
Market Restraints
- Fee Compression Mechanics:The EU Retail Investment Strategy's cost disclosure reforms expose total expense ratios with standardized granularity, pressuring active managers to defend basis-point structures against passive replication alternatives.
- Central Counterparty Concentration:Euroclear and Clearstream's dominance in European fund settlement creates single-point-of-failure exposure for cross-border redemption processing during liquidity stress events.
- Tax Fragmentation:Divergent national withholding tax regimes across France, Germany, and Italy fragment net return calculations and complicate pan-European product standardization.
Strategic Opportunities
- Poland Retail Penetration:Poland's underdeveloped mutual fund culture relative to GDP per capita presents white-space potential for UCITS distributors building local custody and adviser networks.
- MiFID II Inducement Reform:The prohibition of retrocession fees in multiple EU jurisdictions is forcing distribution innovation through fee-based advisory models that favor transparent, low-cost fund structures.
- Blockchain-Native NAV Calculation:Distributed ledger infrastructure for real-time net asset value verification is converging with tokenized fund units, enabling atomic settlement and intraday liquidity for institutional feeders.
Industry Challenges
- SFDR Taxonomy Alignment Verification:Asset managers face operational complexity in substantiating "do no significant harm" criteria across sovereign and corporate bond portfolios, requiring enhanced data vendor relationships and forensic screening capabilities.
- Legacy System Integration:Established European asset servicers are encountering friction in retrofitting decades-old transfer agency platforms to accommodate same-day redemption processing and real-time ESG scoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mutual Fund Market |
| Market Size in 2026 | $14.8 Trillion |
| Market Size in 2035 | $26.53 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Active Management, Passive Management, Tactical Asset Allocation, Strategic Asset Allocation Asset Class: Equity Funds, Fixed Income Funds, Money Market Funds, Balanced Funds Fund Size: Small Cap, Mid Cap, Large Cap, Multi-Cap Investor Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Pension Funds |
| Companies Covered | BlackRock, Amundi, DWS Group, Schroders, Allianz Global Investors, UBS, Vanguard, Janus Henderson Investors, M&G Investments, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mutual Fund Market Trends and Innovations
European fund architecture is fragmenting into specialized liquidity tiers and ESG-verification layers, with technology and regulation jointly compressing the operational assumptions that sustained traditional active management economics.
Tokenized fund units operating on permissioned distributed ledger infrastructure are decomposing the two-day settlement cycle that has defined European UCITS since the 1980s. Institutional feeders in Luxembourg and Ireland are piloting atomic settlement for institutional share classes. This compression is eliminating counterparty exposure windows and enabling intraday liquidity for pension fund liability matching.
The EU Green Deal's taxonomy technical screening criteria are forcing asset managers to restructure fixed income portfolios around climate-aligned benchmarks. Funds failing to meet substantial contribution thresholds face marketing restrictions and distributor exclusion. French and German regulators are conducting enhanced scrutiny of "greenwashing" claims in retail-facing prospectuses.
Advisory platforms in the Netherlands and Belgium are unbundling fund selection from custody and reporting services, with independent fee-only advisers displacing bank-owned distribution channels. This channel rotation favors fund families with transparent cost structures and direct-to-platform data feeds. The shift is most visible in Dutch second-pillar pension transitions, where participants exercise individual choice through regulated investment supermarkets.
Europe Mutual Fund Market Segmentation
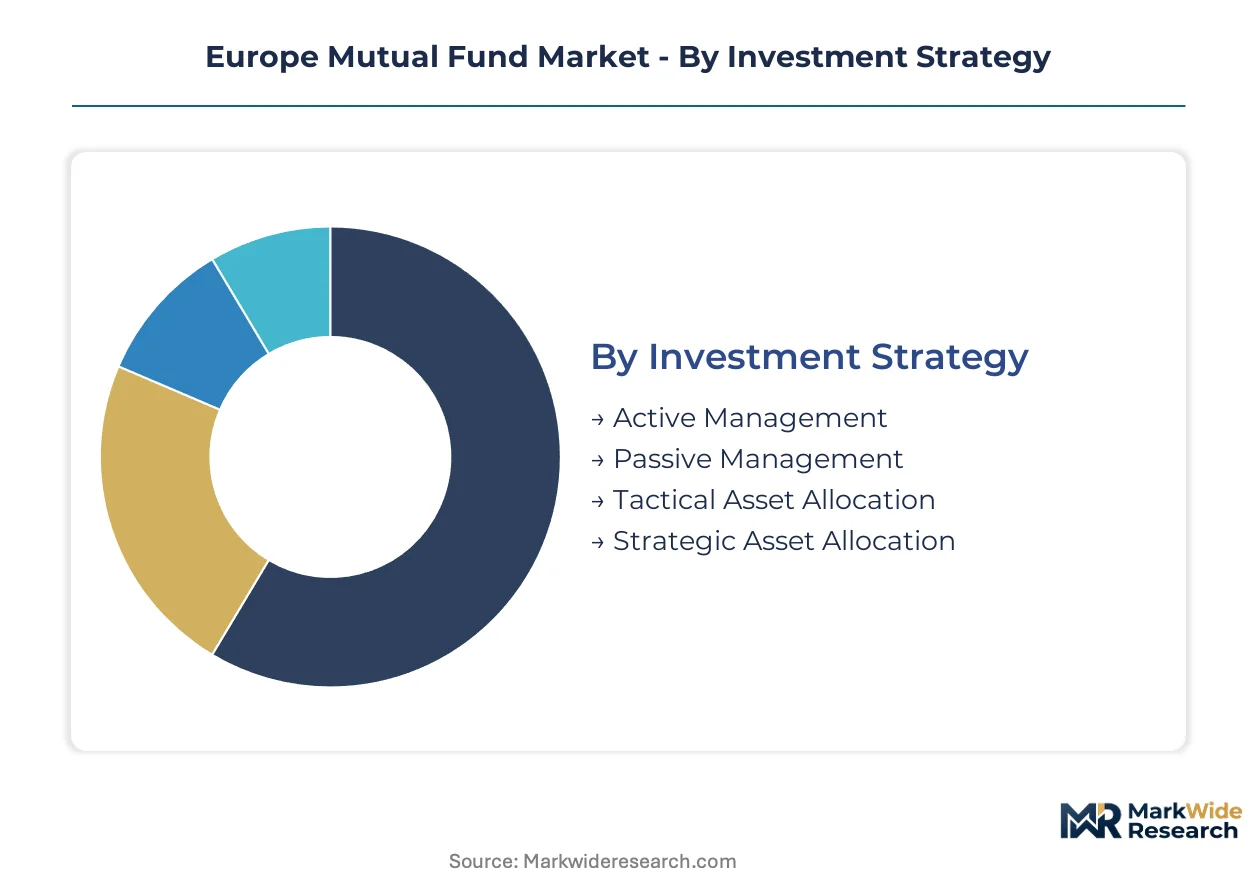
European mutual fund distribution channels exhibit distinct product-mix preferences, with institutional platforms favoring scale-driven vehicles while retail networks prioritize accessibility and transparency. Understanding these segment-channel pairings reveals where asset managers must configure differentiated share classes and fee structures to capture flow concentration.
Investment Strategy:
Channel economics determine which strategies dominate platform shelf space, with fee-based advisers rotating toward transparent vehicles and bank networks defending legacy active products.
- Active Management:Portfolio managers deploy discretionary security selection to outperform benchmarks, charging premium fees for alpha generation. Dutch and German pension consultants are expanding dedicated active equity sleeves for liability-matching purposes, though SFDR disclosure requirements now demand substantiated ESG integration for shelf access.
- Passive Management:Rules-based index replication minimizes tracking error through full or sampled portfolio construction. French retail platforms and Dutch investment supermarkets are channeling flow into UCITS ETFs and index-tracking mutual funds as MiFID II inducement reforms compress distribution economics.
- Tactical Asset Allocation:Dynamic shifts between asset classes based on macroeconomic signals and valuation metrics. Luxembourg-domiciled institutional feeders employ these strategies for pension fund liability hedging.
- Strategic Asset Allocation:Long-term target mixes rebalanced periodically to maintain risk-return profiles. German insurance-owned distribution networks favor these for retail retirement products.
By volume, Passive Management leads. By growth pace, Active Management is ahead as ESG-integrated mandates attract reallocated institutional capital.
Asset Class:
Cost tier differentiation separates premium-priced alternatives from commoditized core exposures, with fee compression most severe in liquid developed-market categories.
- Equity Funds:Diversified portfolios of listed stocks targeting capital appreciation through regional, sectoral, or thematic concentration. Benelux and Nordic institutional investors are expanding European equity allocations as home bias moderates, with Article 8 and 9 classifications now mandatory for distributor due diligence.
- Fixed Income Funds:Sovereign, corporate, and structured debt instruments with defined duration and credit quality parameters. French and Italian retail networks are absorbing inflows during rate volatility as investors seek yield with explicit maturity structures.
- Money Market Funds:Short-term debt instruments maintaining stable net asset values through amortized cost accounting. Irish and Luxembourg domiciled vehicles serve euro liquidity management for corporate treasuries.
- Balanced Funds:Static or dynamic mixes of equity and fixed income exposures packaged as single-ticket solutions. German Sparkassen distribution channels defend these for conservative retail investors.
By volume, Equity Funds dominate. By expansion trajectory, Fixed Income Funds are climbing the fastest as rate uncertainty sustains demand for duration-managed products.
Fund Size:
Customer type segmentation separates institutional scale requirements from retail accessibility preferences, with minimum investment thresholds determining platform eligibility.
- Large Cap:Funds exceeding institutional liquidity thresholds with established track records and operational infrastructure. Pension fund consultants in the Netherlands and Germany mandate these for fiduciary mandates requiring daily dealing capacity.
- Multi-Cap:Flexible capitalization ranges allowing managers to deploy capital across market segments. Independent fee-only advisers in Belgium are channeling retail flow into these as they displace bank-owned distribution.
- Mid Cap:Focused exposure to medium-sized issuers with growth characteristics and acquisition potential.
- Small Cap:Concentrated positions in emerging companies with higher volatility and liquidity constraints.
By volume, Large Cap leads. By growth pace, Multi-Cap is gaining share fastest as platform unbundling favors flexible vehicles.
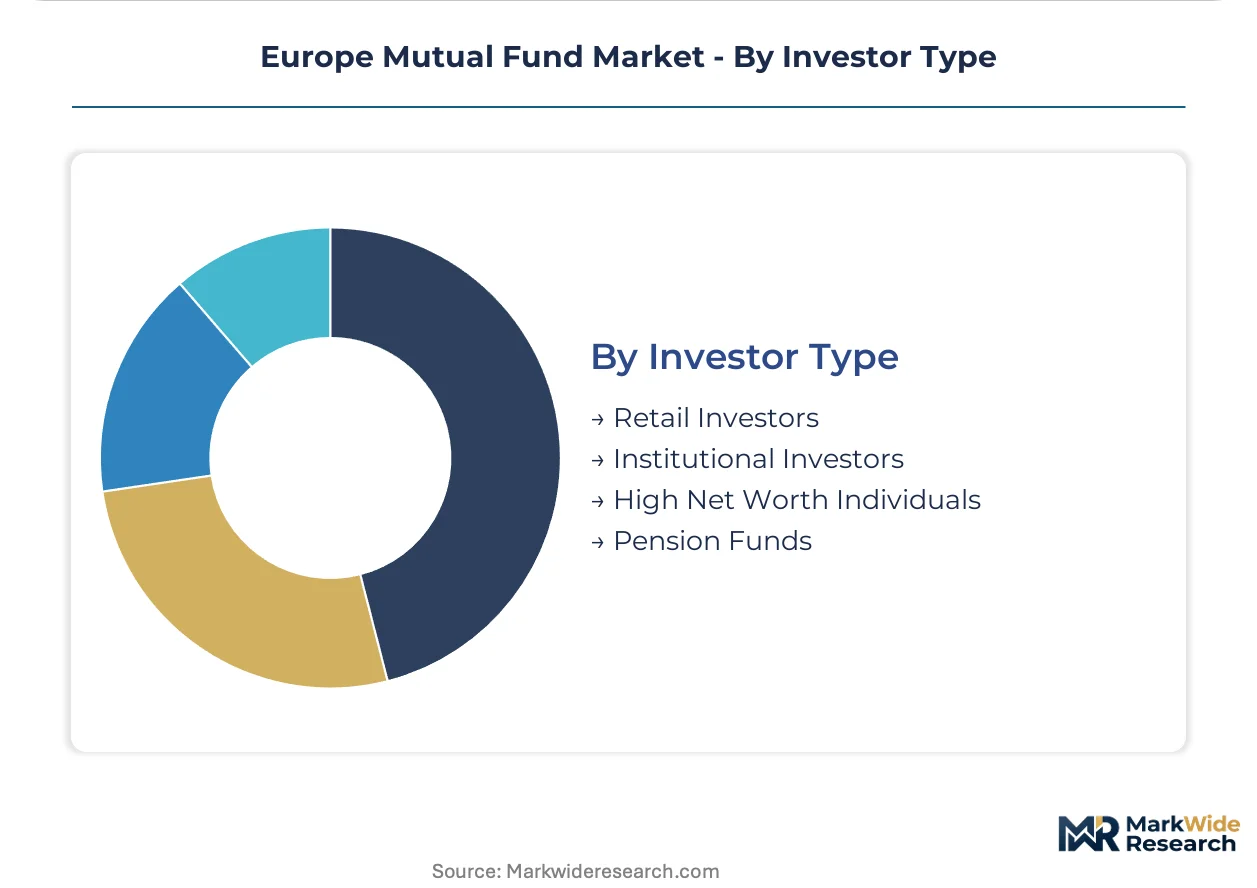
Investor Type:
Maturity gradients separate established institutional relationships from developing retail penetration, with regulatory reform accelerating channel rotation.
- Pension Funds:Occupational and supplementary schemes managing defined-benefit and defined-contribution liabilities. Dutch second-pillar transitions and German Betriebsrente reforms are channeling structural flow into UCITS-structured vehicles with daily liquidity.
- Retail Investors:Individual savers accessing funds through advised, execution-only, or platform-direct channels. Polish and Romanian markets present white-space potential as mutual fund penetration lags GDP per capita trends.
- Institutional Investors:Insurance companies, foundations, and corporate treasuries with customized mandate requirements.
- High Net Worth Individuals:Private banking clients accessing specialized share classes with tailored liquidity terms.
By volume, Retail Investors lead. By expansion trajectory, Pension Funds are ahead as occupational scheme reforms accelerate institutional reallocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxembourg's UCITS fund platform infrastructure anchors European cross-border distribution, processing daily net asset value calculations for vehicles domiciled across the continent. The Clearstream and Euroclear settlement networks interconnect national markets through this hub.
Germany
Betriebsrente pension reforms channel occupational scheme assets into UCITS-structured equity vehicles with daily liquidity. BaFin enforces SFDR disclosure standards that reclassify ESG-integrated products for distributor access. Frankfurt's fund management cluster hosts DWS Group and Allianz Global Investors operations serving institutional mandates.
France
Retail platforms absorb fixed income inflows during rate volatility as investors seek yield with defined duration exposure. Autorité des Marchés Financiers scrutinizes greenwashing claims in retail prospectuses under EU Green Deal taxonomy criteria. Paris-based Amundi leverages pan-European distribution infrastructure to capture institutional rotation into ESG-compliant sleeves.
Netherlands
Dutch second-pillar pension transitions exercise individual choice through regulated investment supermarkets, expanding UCITS allocations. De Nederlandsche Bank supervises liquidity stress-testing for fund platforms operating under UCITS frameworks. Amsterdam's fund infrastructure and favorable withholding tax treaties position the city as a Benelux-Nordic distribution nexus.
United Kingdom
Post-Brexit regulatory divergence creates parallel fund authorization tracks, with some managers maintaining dual UCITS and UK OEIC structures. The Financial Conduct Authority governs cost disclosure under Consumer Duty rules that parallel EU Retail Investment Strategy reforms. London retains concentration in emerging market debt and alternative UCITS capabilities through Schroders and Janus Henderson Investors operations.
Europe Mutual Fund Market Competitive Landscape
Listed leaders compete with private specialists across distribution reach and ESG integration depth. The European mutual fund sector exhibits tiered concentration, with scale-driven passive providers commanding retail platform shelf space while active boutiques defend institutional relationships. Strategic archetypes include pan-European distributors leveraging cross-border UCITS passports, ESG-specialized boutiques substantiating taxonomy alignment, and index replication specialists compressing fee structures. Dominant competitive moves encompass M&A-driven platform consolidation and strategic partnerships with pension fund consultants for fiduciary mandate access.
Within the scale-driven tier, BlackRock and Vanguard exemplify passive replication dominance through index-tracking vehicle proliferation. Amundi occupies a position bridging active and passive capabilities with pan-European distribution infrastructure. Among UK-based active managers, Schroders sits within the emerging market debt specialization archetype that attracts institutional reallocation.
| Leading Market Players |
|---|
| BlackRock |
| Amundi |
| DWS Group |
| Schroders |
| Allianz Global Investors |
| UBS |
| Vanguard |
| Janus Henderson Investors |
| M&G Investments |
| Others |
Pricing and Supply Chain Analysis
UCITS regulatory compliance gates both fund manufacturer qualification and fee tier differentiation, compressing active management economics while elevating standardized index replication vehicles. Asset servicers in Luxembourg and Ireland face simultaneous pressure to absorb compliance costs and defend basis-point structures against platform unbundling.
Pricing Analysis
Volume-discount tiering structures dominate institutional share classes, with pension fund consultants negotiating reduced management fees for commitments exceeding defined thresholds. Pricing stratifies across premium active mandates, standard index-tracking vehicles, and economy money market products based on complexity of ESG integration and liquidity terms. Cost compression runs through the retail channel as MiFID II inducement reforms expose total expense ratios with standardized granularity. Independent fee-only advisers exhibit highest price sensitivity, while Dutch second-pillar pension schemes prioritize liability-matching precision over basis-point minimization.
Supply Chain Analysis
Euroclear and Clearstream settlement infrastructure constitutes a chokepoint for cross-border redemption processing, concentrating operational risk in Brussels and Luxembourg nodes. Fund manufacturing draws from transfer agency platforms in Ireland, custody networks in Luxembourg, and distribution technology vendors in the Netherlands. Single-point-of-failure exposure intensifies during liquidity stress events when redemption volumes spike across UCITS-structured vehicles. Distribution runs through bank-owned platforms, independent advisory networks, and regulated investment supermarkets with divergent fee-sharing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European mutual fund architecture is approaching a platform-economics inflection as blockchain-native NAV infrastructure and open-banking APIs dismantle legacy custody monopolies. Interoperability between fund units and central bank digital currency settlement rails is redefining liquidity provisioning.
For Market Incumbents: Shield active management franchises by deepening ESG data vendor relationships and securing Article 9 taxonomy alignment ahead of distributor due diligence tightening. Acquire specialized fixed income boutiques in Dublin or Luxembourg to defend yield-focused mandates against passive replication. Prioritize transfer agency platform modernization to accommodate same-day redemption processing demanded by Dutch pension transitions. For New Entrants and Emerging Players: SFDR Article 8 fast-track certification opens shelf-space access for boutique managers with forensic climate-screening capabilities. Target Polish retail penetration where mutual fund culture lags GDP per capita advancement and local custody infrastructure remains underdeveloped. Deploy direct-to-platform data feeds that bypass bank-owned distribution chokepoints through API-first integration with Belgian and Dutch investment supermarkets. For Investors and Strategic Acquirers: EU Retail Investment Strategy implementation reshapes the acquisition landscape by compressing retrocession-dependent distribution models and elevating transparent fee structures. Long-term viability favors asset servicers with scalable ESG verification infrastructure and atomic settlement pilot programs. Monitor blockchain-NAV regulatory clarity as the decisive signal for infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SFDR Article 9 Reclassification | Taxonomy alignment unlocks distributor shelf space across Benelux and Nordic platforms. |
| Blockchain-NAV Infrastructure Deployment | Atomic settlement eliminates counterparty exposure for Irish-domiciled institutional feeders. |
| Polish Custody Network Expansion | Local infrastructure captures white-space retail penetration as GDP per capita advances. |
| MiFID II Inducement Reform Adaptation | Fee-based advisory rotation favors transparent cost structures in Dutch supermarkets. |
| Pension Fund Consultant Partnership | Fiduciary mandate access channels defined-benefit liabilities into UCITS vehicles. |
Research Methodology
Desk research of UCITS regulatory filings, ESMA stress-test disclosures, and national pension fund annual reports preceded structured interviews with fund platform executives, transfer agency operations heads, Dutch pension consultants, and Belgian fee-only advisers. Secondary validation drew from ECB statistical data releases, EFAMA industry factbooks, and Luxembourg financial regulator circulars. Bottom-up flow data triangulated against top-down asset under management estimates across the projection horizon.
Variance-decomposition framing separated volume effects from mix-shift and pricing components across investment strategy, asset class, and investor type dimensions. Modeling incorporated fund domicile concentration patterns, ESG classification migration trajectories, and platform economics evolution. CAGRs were derived from historical flow velocity adjusted for regulatory reform implementation timelines and pension fund reallocation schedules.
Decision-makers should treat outputs as directional under sustained SFDR enforcement intensity and stable eurozone rate environments; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU Retail Investment Strategy cost disclosure rules and central bank digital currency settlement pilots evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Capital Markets and Securities
Foreign Exchange Market
Capital Markets and Securities
Gold Derivatives and Futures Market
Capital Markets and Securities
UK Capital Exchange Ecosystem Market
Capital Markets and Securities
Asia Pacific Capital Exchange Ecosystem Market
Capital Markets and Securities
Stock Trading Affiliate Programs Market
Capital Markets and Securities
Asia Pacific ETF Market
Capital Markets and Securities
India Capital Exchange Ecosystem Market
Capital Markets and Securities
Stock Trading and Investing Applications Market
Capital Markets and Securities
Hong Kong Capital Exchange Ecosystem Market
Capital Markets and Securities
Europe Capital Exchange Ecosystem Market
Capital Markets and Securities
Global Algorithm Trading Market
Capital Markets and Securities
US Securities Brokerage Market
Capital Markets and Securities
Middle East and Africa ETF Market
Capital Markets and Securities
Special Purpose Vehicle Market
Capital Markets and Securities
North America Mutual Fund Market
Capital Markets and Securities
China Capital Exchange Ecosystem Market