
 AI Consulting Services Market | 2026-2036
AI Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
AI Consulting Services Market Analysis
Modular service packaging is pivoting how enterprises purchase AI expertise, shifting from monolithic transformation contracts toward discrete, outcome-based modules. Accenture leverages its global delivery network to anchor large-scale implementation engagements across multiple industry verticals. IBM Consulting sustains technology leadership through deep hybrid cloud and generative AI integration capabilities. Kanerika specializes in mid-market AI adoption, competing on agility against larger consultancies.
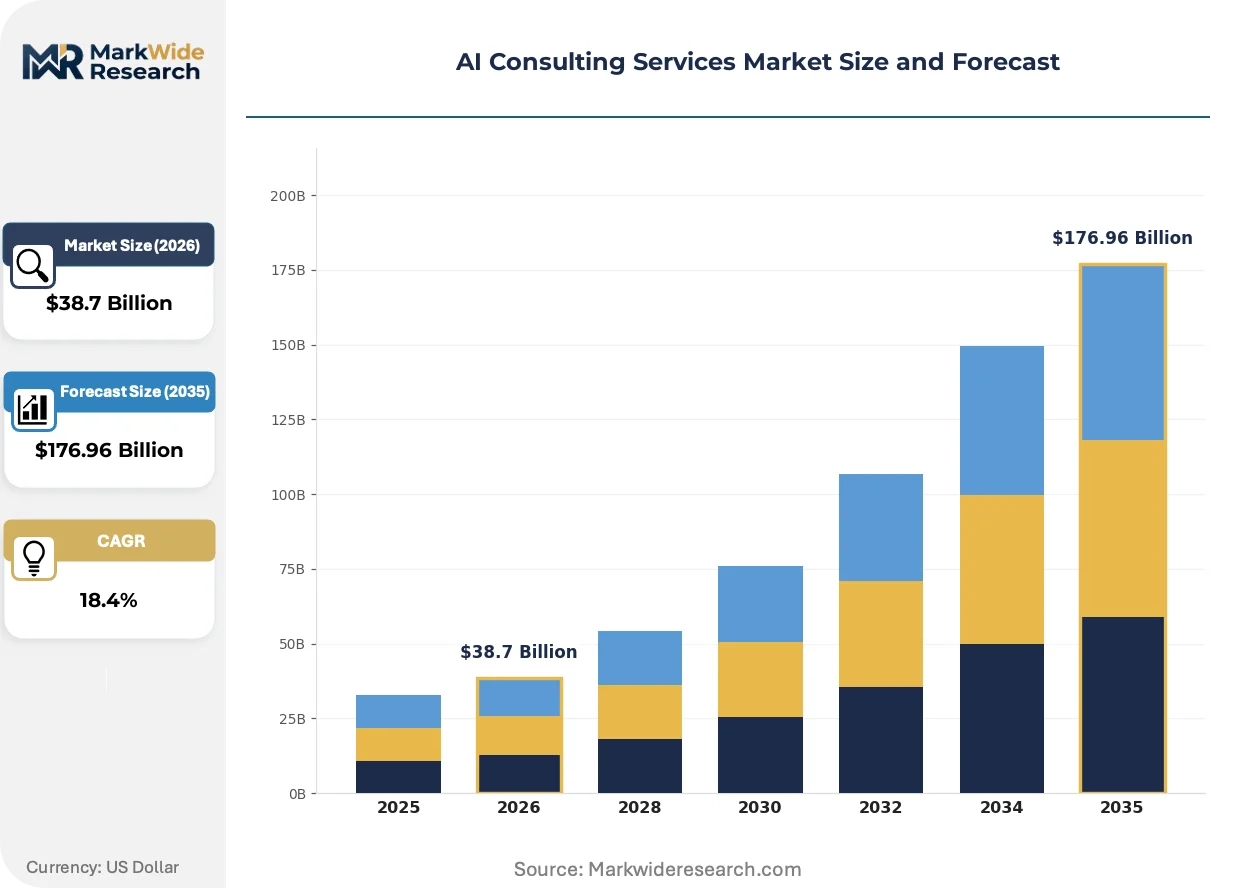
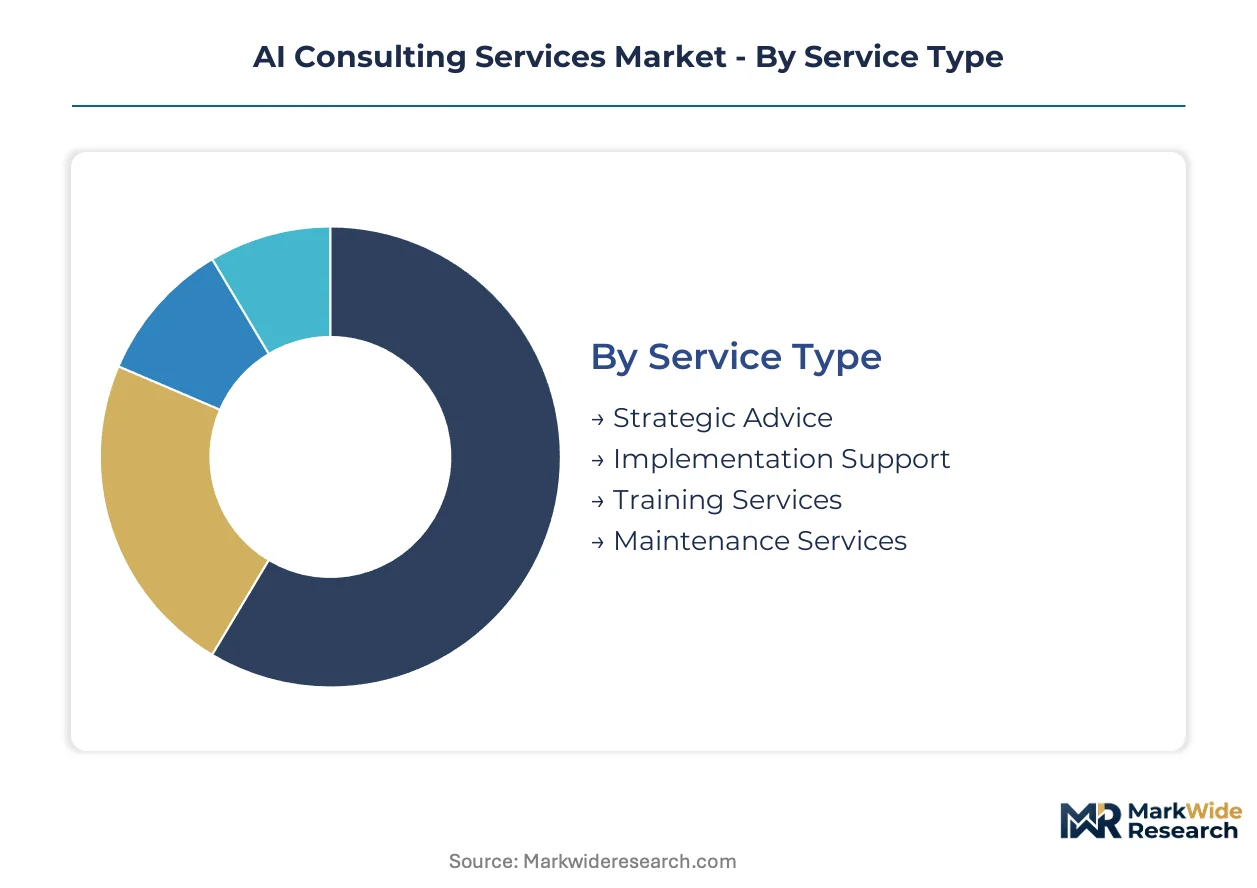
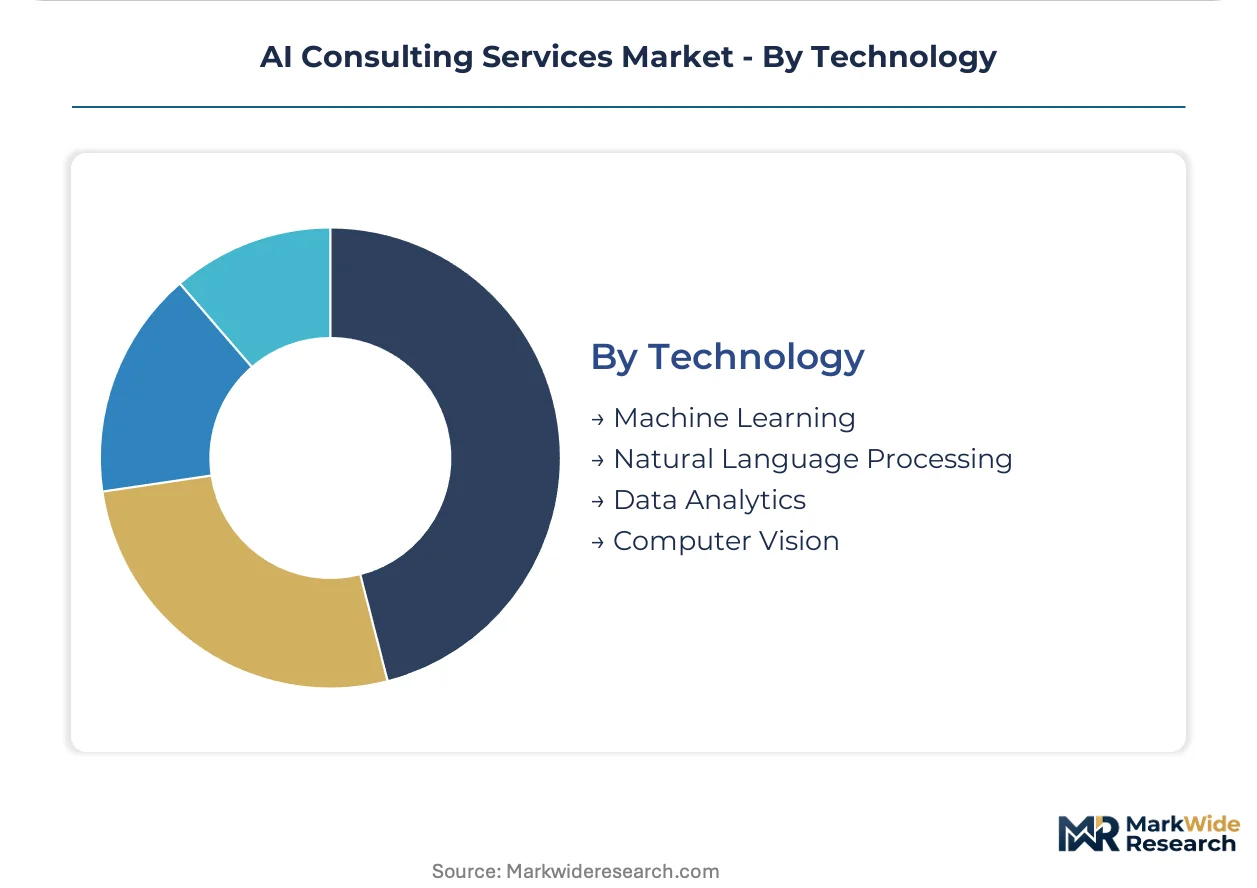
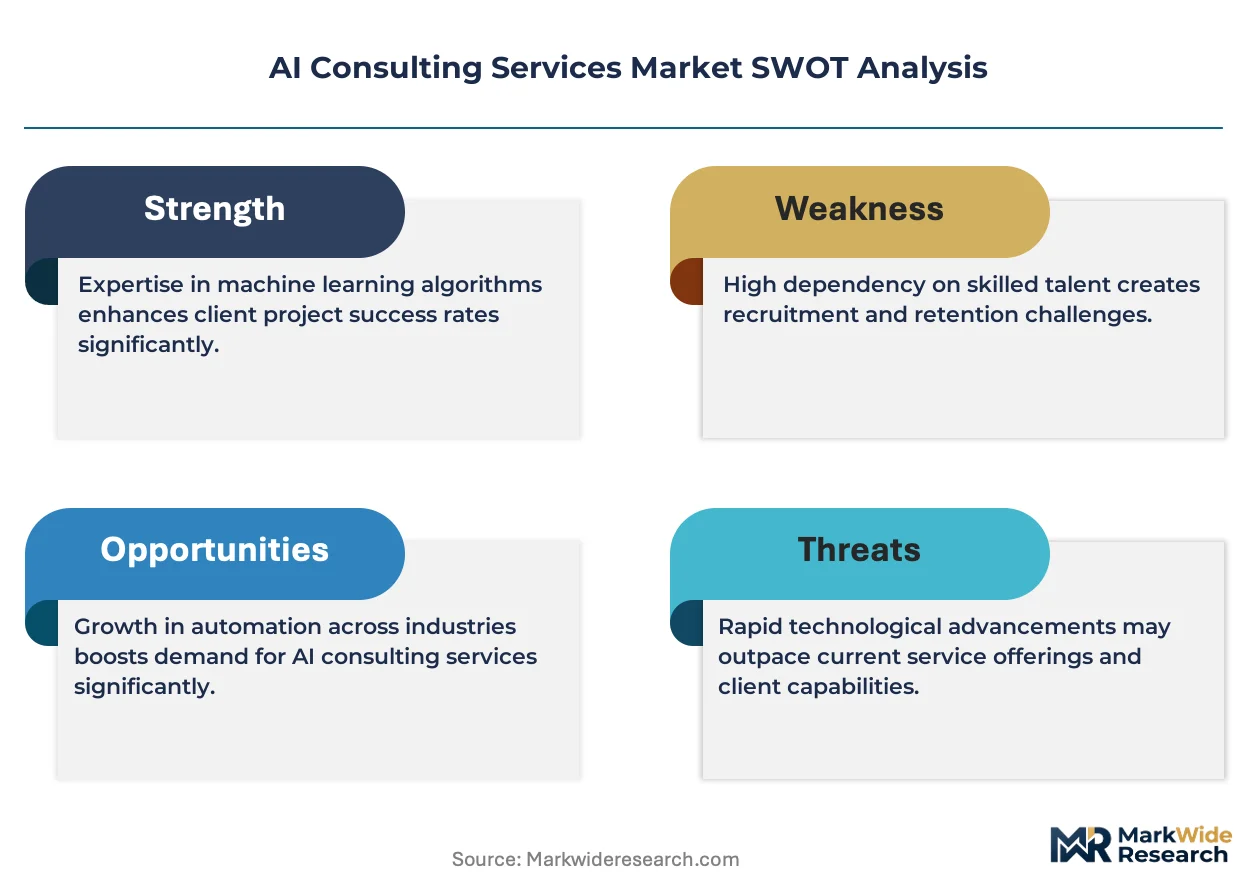
AI consulting services encompass advisory and technical execution engagements that design, deploy, and optimize artificial intelligence systems within enterprise environments. These services integrate machine learning model development, data pipeline architecture, and governance frameworks to automate decision processes and extract predictive insights from structured and unstructured data. Strategic Advice and Implementation Support command the largest share of service type revenue, while Natural Language Processing and Computer Vision represent the fastest-expanding technology segments as enterprises prioritize conversational AI and visual automation. Maintenance Services remains a mature, lower-margin pool, whereas Training Services is gaining traction amid acute talent shortages.
The EU AI Act, FDA guidance on AI-enabled medical devices, and HIPAA requirements for algorithmic patient data processing are reshaping compliance obligations for healthcare and cross-border deployments. Enterprises must now embed risk management, transparency documentation, and human oversight into every AI consulting engagement before production deployment. Stakeholders should monitor how regulatory divergence between jurisdictions affects service standardization and delivery economics.
Market Dynamics
Modular service packaging is fragmenting traditional AI consulting engagements as enterprises reject monolithic transformation contracts in favor of discrete, outcome-based modules that tie fees to measurable automation outcomes.
Growth Catalysts
- EU AI Act compliance mandates:Enterprises across Germany, France, and Italy must embed risk management and human oversight into automated decision systems before production deployment, creating sustained advisory demand.
- Healthcare diagnostic automation:FDA guidance on AI-enabled medical devices is accelerating validation and deployment engagements for algorithmic patient data processing tools.
- Fortune 500 enterprise-scale transformation:Concentrated demand from United States-based conglomerates is anchoring large-scale implementation contracts across financial services, manufacturing, and retail verticals.
Market Restraints
- Specialized talent scarcity:Acute shortages of machine learning engineers and AI governance specialists are inflating project costs and extending delivery timelines.
- Regulatory fragmentation:Divergent compliance requirements between EU AI Act risk classifications, FDA device pathways, and HIPAA algorithmic privacy rules are forcing redundant documentation and localization costs.
- Legacy system integration complexity:Enterprises with entrenched ERP and data warehouse architectures face prohibitive reconfiguration expenses to enable real-time AI inference pipelines.
Strategic Opportunities
- Mid-market penetration gaps:Manufacturing and professional services firms with $500M-$2B revenue represent underserved segments where agile consultancies can compete against tier-one incumbents.
- Natural Language Processing and Computer Vision convergence:Multimodal AI systems that process voice, text, and visual inputs simultaneously are opening new automation categories in customer service and quality inspection.
- Maintenance Services monetization:Post-deployment model monitoring, drift detection, and retraining contracts offer recurring revenue streams that offset project-based volatility.
Industry Challenges
- Explainability and transparency documentation:Consultants must produce technical records satisfying EU AI Act audit requirements and FDA premarket submission standards simultaneously.
- Data pipeline architecture debt:Enterprises with fragmented data lakes and inconsistent governance frameworks require expensive remediation before model deployment can proceed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Consulting Services Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategic Advice, Implementation Support, Training Services, Maintenance Services Industry Vertical: Healthcare, Finance, Retail, Manufacturing Client Type: Corporates, Startups, Government Agencies, Nonprofits Technology: Machine Learning, Natural Language Processing, Data Analytics, Computer Vision |
| Companies Covered | Slalom, Coherent Solutions, Accenture, Zfort Group, Kanerika, IBM Consulting, DataRobot, BotsCrew, RTS Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Consulting Services Market Emerging Trajectories
Generative AI capabilities are compressing development cycles and reshaping how advisory firms structure delivery teams and client value propositions.
Retrieval-augmented generation architectures are absorbing unstructured enterprise knowledge bases into conversational interfaces that surface proprietary insights without retraining foundation models. Financial services and legal departments are deploying these systems to accelerate contract analysis and regulatory research. This absorption of domain expertise into queryable interfaces is compressing the traditional knowledge-transfer phase of consulting engagements.
The EU AI Act's risk-based classification system is mandating conformity assessments and CE marking for high-risk AI applications including credit scoring and recruitment automation. Deployment timelines for affected systems have extended by three to six months to accommodate documentation and third-party auditing requirements. Healthcare and financial services verticals are absorbing these compliance costs into project budgets while smaller consultancies struggle to maintain certification capabilities.
Outcome-based contracting is displacing time-and-materials arrangements as procurement teams demand fixed fees tied to automation rate improvements or cost reduction targets. Manufacturing and logistics buyers are leading this shift, with contracts specifying penalty clauses for missed KPIs. Germany and the United States exhibit the most advanced adoption of performance-guarantee structures in AI consulting procurement.
AI Consulting Services Market Segmentation
Segmentation in AI consulting services reveals how procurement patterns fragment across engagement models and client capabilities. Buyers select service tiers based on internal technical maturity and regulatory exposure. Technology specialization and vertical expertise determine competitive positioning among providers.
Service Type:
Standalone advisory engagements dominate initial client relationships, while embedded implementation contracts anchor long-term revenue. The integration depth varies sharply across these categories.
- Strategic Advice:Front-end diagnostic and roadmap development engagements assess organizational AI readiness, data asset quality, and governance maturity. Demand concentrates among Fortune 500 conglomerates in the United States seeking board-level alignment before capital allocation. EU AI Act risk classification requirements are extending these engagements to include compliance architecture planning.
- Implementation Support:Technical deployment services spanning model development, pipeline construction, and production integration. Healthcare providers in Germany and France are absorbing the largest share as FDA and EMA validation pathways lengthen deployment timelines. Talent scarcity is inflating delivery costs and forcing hybrid onshore-nearshore team structures.
- Training Services:Capability-building programs addressing acute shortages of machine learning engineers and AI governance specialists. Financial services firms in London and Singapore are prioritizing upskilling over external hiring.
- Maintenance Services:Post-deployment monitoring, drift detection, and model retraining contracts. Manufacturing buyers in the United States Midwest are pioneering multi-year service agreements with performance guarantees.
Implementation Support leads volumes today; Training Services is gaining share fastest.
Industry Vertical:
Cost tier differentiation separates verticals with heavy compliance burdens from those prioritizing operational efficiency. Premium pricing attaches to regulated sectors requiring audit trails and human oversight documentation.
- Healthcare:Diagnostic automation, clinical decision support, and operational optimization engagements. FDA guidance on AI-enabled medical devices and HIPAA algorithmic privacy rules mandate extensive validation documentation. United States hospital systems and European university medical centers are absorbing these compliance costs into capital budgets.
- Finance:Credit scoring automation, fraud detection, and algorithmic trading infrastructure. EU AI Act high-risk classification for credit decisions is mandating conformity assessments and CE marking. Frankfurt and Paris-based institutions are extending procurement timelines to accommodate third-party auditing.
- Retail:Demand forecasting, inventory optimization, and customer personalization systems. Lower regulatory friction enables faster deployment cycles and outcome-based contracting structures.
- Manufacturing:Predictive maintenance, quality inspection, and supply chain optimization. Computer Vision convergence with sensor data is opening multimodal automation categories in German automotive and Japanese electronics clusters.
Finance commands premium pricing today; Healthcare is expanding most quickly.
Client Type:
Customer type determines engagement scale and sales cycle complexity. Enterprise procurement teams demand outcome-based modules while smaller buyers accept standardized packages.
- Corporates:Large enterprises with $1B+ revenue seeking enterprise-scale transformation. United States-based conglomerates are anchoring the largest implementation contracts across multiple verticals simultaneously.
- Startups:Venture-backed firms requiring rapid AI capability insertion without internal build-out. Agility-focused consultancies compete here against tier-one incumbents on speed and cost.
- Government Agencies:Public sector buyers with extended procurement cycles and stringent transparency requirements. EU member state administrations are embedding EU AI Act compliance into RFP specifications.
- Nonprofits:Mission-driven organizations prioritizing cost efficiency over technical sophistication. Limited budgets constrain engagement scope to advisory and training tiers.
Corporates anchor revenue today; Government Agencies are climbing the fastest.
Technology:
Application maturity separates foundational capabilities from frontier expansion areas. Established technologies anchor project economics while emerging domains command premium rates.
- Machine Learning:Predictive modeling, classification systems, and optimization algorithms forming the technical backbone of most engagements. Mature tooling and talent pools enable standardized delivery.
- Natural Language Processing:Conversational AI, document analysis, and retrieval-augmented generation systems. Financial services legal departments and United States healthcare administrators are deploying these for contract analysis and clinical documentation.
- Data Analytics:Descriptive and diagnostic analytics preceding AI model development. Often bundled with implementation support as pipeline preparation.
- Computer Vision:Visual inspection, medical imaging analysis, and autonomous system perception. Manufacturing quality control and radiology departments in Germany and Japan are driving adoption.
Machine Learning leads deployment volume today; Natural Language Processing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI consulting services first achieved scale in the United States through early enterprise adoption of machine learning platforms. The industry subsequently expanded across Europe and Asia-Pacific as regulatory frameworks matured and cloud infrastructure penetrated mid-market segments.
United States
Fortune 500 conglomerates in financial services and healthcare anchor the largest implementation contracts. FDA guidance on AI-enabled medical devices mandates extensive validation documentation for diagnostic automation deployments. Hospital systems in the Boston-Cambridge cluster and financial institutions in New York Metro absorb these compliance costs into capital budgets.
Germany
Automotive and industrial manufacturing firms drive demand for predictive maintenance and quality inspection systems. EU AI Act risk classifications require conformity assessments and CE marking for high-risk applications including credit scoring automation. The Stuttgart automotive cluster and Munich industrial technology corridor host the densest concentration of deployment engagements.
United Kingdom
Financial services legal departments and insurance underwriters prioritize natural language processing for contract analysis and regulatory research. FCA expectations for algorithmic transparency in credit decisions extend procurement timelines. London's Square Mile and Canary Wharf financial districts concentrate advisory engagements for governance framework development.
France
Healthcare providers and luxury goods manufacturers represent distinct demand poles for operational optimization. ANSM oversight of clinical decision support tools requires extensive documentation for hospital system deployments. The Paris-Saclay research cluster and Lyon healthcare technology corridor anchor validation and implementation activity.
Japan
Electronics manufacturers and automotive suppliers deploy computer vision for quality control and supply chain optimization. METI guidelines for AI governance influence enterprise procurement specifications for human oversight documentation. The Nagoya automotive cluster and Osaka-Kobe manufacturing corridor concentrate multimodal automation deployments.
AI Consulting Services Market Vendor Landscape
Premium-margin players sit above commodity-margin players across implementation complexity and regulatory certification depth. The vendor base organizes into three tiers: global systems integrators with multi-vertical delivery networks, specialized boutiques competing on agility and sector focus, and technology-native firms bundling advisory with proprietary platforms. Strategic moves concentrate on outcome-based contracting structures and post-deployment maintenance service expansion.
Within the global systems integrator tier, Accenture and IBM Consulting occupy positions defined by scale and hybrid cloud integration depth. Kanerika exemplifies the mid-market specialist archetype competing against larger consultancies on deployment velocity. These named entities anchor industry-level commentary without specific claims about individual strategic actions or financial performance.
| Leading Market Players |
|---|
| Slalom |
| Coherent Solutions |
| Accenture |
| Zfort Group |
| Kanerika |
| IBM Consulting |
| DataRobot |
| BotsCrew |
| RTS Labs |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialist consultancies anchor supply-side concentration across the United States and United Kingdom, compressing mid-market pricing discipline while tier-one incumbents defend premium positioning through certification depth and outcome-based contracting structures.
Pricing Analysis
Outcome-based contracting structures dominate procurement for Fortune 500 engagements, with fees tied to measurable automation rate improvements or cost reduction targets rather than time-and-materials billing. Price differentiation stems from EU AI Act certification capabilities and vertical-specific validation documentation depth, with healthcare and finance buyers absorbing premium tiers for FDA and EMA pathway expertise. Cost compression runs through mid-market advisory tiers as talent scarcity inflates delivery costs and agile competitors undercut tier-one rates. Startups and government agencies exhibit divergent sensitivity, with venture-backed firms prioritizing speed over cost and public sector buyers accepting extended timelines for transparency compliance.
Supply Chain Analysis
Single-source vulnerability sits with machine learning engineering talent concentrated in the United States, United Kingdom, and Germany, where acute shortages of AI governance specialists and MLOps practitioners constrain delivery capacity. The talent pipeline draws from elite computer science programs at Stanford, MIT, and ETH Zurich, with nearshore delivery networks in Poland and India providing partial relief. Regulatory fragmentation between EU AI Act risk classifications and FDA device pathways forces redundant documentation and localization costs across engagements. Distribution runs through direct enterprise sales teams for large contracts and platform partnerships with hyperscalers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI consulting services represent a late-cycle quality story as procurement teams shift demand toward premium specifications mandating EU AI Act conformity assessments and FDA validation documentation.
For Market Incumbents: Acquire specialized boutiques with deep healthcare or finance vertical expertise to defend against agile mid-market competitors. Consolidate maintenance services capabilities to capture recurring revenue streams offsetting project-based volatility. Reinforce certification depth for EU AI Act high-risk system auditing and FDA premarket submission standards. For New Entrants and Emerging Players: Begin with manufacturing firms in the United States Midwest and German automotive clusters where outcome-based contracting acceptance lags tier-one penetration. Target predictive maintenance and quality inspection applications where Computer Vision convergence creates whitespace. Lead with rapid deployment velocity and transparent pricing against incumbent complexity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market specialists with healthcare compliance depth but limited brand recognition. Long-term viability hinges on recurring maintenance services revenue share and vertical certification moats. Watch FDA guidance expansion into clinical decision support tools as an inflection signal for diagnostic automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | CE marking capabilities for high-risk credit scoring and recruitment automation systems unlock German and French financial services procurement. |
| Maintenance Services Monetization | Post-deployment model monitoring and drift detection contracts generate recurring revenue streams with manufacturing buyers in the United States Midwest. |
| Healthcare Validation Partnership | FDA submission pathway expertise for AI-enabled medical devices accelerates hospital system engagements in Boston-Cambridge and Paris-Saclay clusters. |
| Natural Language Processing Platform Integration | Retrieval-augmented generation architectures for contract analysis absorb financial services legal department budgets in London and New York Metro. |
| Mid-Market Geographic Expansion | Agile delivery networks in Poland and India capture manufacturing and professional services firms with $500M-$2B revenue underserved by tier-one incumbents. |
Methodological Framework
Bottom-up enterprise procurement modeling reconciled against top-down consultancy capacity tracking forms the analytical core of this study. Primary interviews with AI consulting engagement directors, healthcare CIOs, financial services procurement leads, and FDA regulatory affairs specialists were cross-validated against secondary sources including SEC 10-K filings, EU AI Act implementation guidance, FDA premarket submission databases, and hyperscaler partnership announcements. Triangulation between demand-side budget allocation patterns and supply-side talent pipeline data ensures segmentation integrity.
Historical trendline analysis of service type revenue mix and technology deployment patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, industry vertical, client size tier, and technology specialization, with CAGRs derived from weighted average growth rates across these categories. Forecast inputs incorporate EU AI Act compliance timeline assumptions and FDA guidance evolution for AI-enabled medical devices.
Several conditions sit outside the modeled scope, including potential regulatory divergence between EU member state implementations and unanticipated FDA pathway revisions for clinical decision support tools. Forecasts reflect documented assumptions about talent scarcity persistence and cloud infrastructure cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
Global Voice Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Global Federated Learning Solutions Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Global Enterprise Artificial Intelligence Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market