
 Europe Spice and Herb Extracts Market | 2026-2036
Europe Spice and Herb Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Spice and Herb Extracts Market Foresight
Mediterranean herb cultivation zones in Spain and southern France is broadening raw material availability for European extractors. Kerry Group plc leverages integrated botanical sourcing networks to secure year-round supply consistency. Symrise AG anchors its position through deep R&D partnerships with regional agricultural cooperatives. Kalsec Inc. competes on specialized oleoresin extraction technologies that preserve heat-sensitive volatile compounds.
Europe spice and herb extracts comprise concentrated bioactive compounds—essential oils, oleoresins, and standardized phytochemical fractions—typically extracted via supercritical CO2, solvent, or steam distillation methods at specified purity thresholds between 5% and 95% active marker content. These extracts serve primarily as natural flavoring, coloring, and functional ingredients across formulated consumer goods. Liquid extracts command the largest volume share due to ease of incorporation into beverage and sauce matrices, while powder extracts represent the fastest-expanding format as dry-blend convenience products gain shelf space. Within applications, food and beverages absorbs the dominant share of extract volume, though nutraceuticals generates disproportionate margin contribution as branded supplement makers pay premiums for certified-organic and traceable botanical provenance.
EMA guidelines on herbal medicinal products, EFSA Novel Food regulations, and REACH chemical safety protocols collectively govern extract purity, labeling claims, and new ingredient market access across European jurisdictions. Compliance with these frameworks raises formulation costs but simultaneously erects barriers against unstandardized imports from non-EU suppliers. Stakeholders must monitor evolving EU AI Act traceability requirements that will soon mandate digital supply chain documentation for botanical ingredient batches.
Market Dynamics
EU Green Deal mandates on solvent emissions and the F-Gas Regulation are forcing European extractors to abandon conventional chemical processes. This regulatory compression is accelerating capital redeployment toward supercritical CO2 and aqueous extraction systems, reshaping competitive economics across the value chain.
Growth Catalysts
- Clean-label procurement:German food manufacturers are expanding long-term contracts for certified-organic extracts to meet retailer sustainability scorecards.
- Supercritical CO2 technology:This extraction method eliminates residual solvent concerns while preserving heat-sensitive volatile compounds in oleoresin production.
- Nutraceutical premiumization:Branded supplement makers in France and Italy pay traceability premiums for batch-documented botanical provenance under EFSA Novel Food frameworks.
Market Restraints
- Raw material concentration:Mediterranean herb cultivation clusters in Spain and southern France create weather-dependent supply vulnerability for regional extractors.
- REACH compliance costs:Chemical safety documentation requirements for novel extract fractions raise formulation barriers against smaller ingredient suppliers.
- Natural flavor substitution:Synthetic biotechnology-derived flavor compounds threaten price positioning in mass-market beverage applications.
Strategic Opportunities
- Polish processing expansion:Underdeveloped extraction capacity in Central Europe offers first-mover positioning for EU-funded greenfield facilities.
- EU AI Act traceability:Mandatory digital supply chain documentation creates service revenue streams for compliance-software providers serving botanical suppliers.
- Dry-blend convenience formats:Powder extract demand from ready-meal manufacturers in the Netherlands outpaces current specialist production capacity.
Industry Challenges
- Phytochemical standardization expertise:Shortage of analytical chemists capable of validating active marker content between 5% and 95% purity thresholds slows product development cycles.
- Legacy equipment retrofitting:Converting solvent-based extraction lines to supercritical CO2 systems requires extended downtime and specialized engineering procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Spice and Herb Extracts Market |
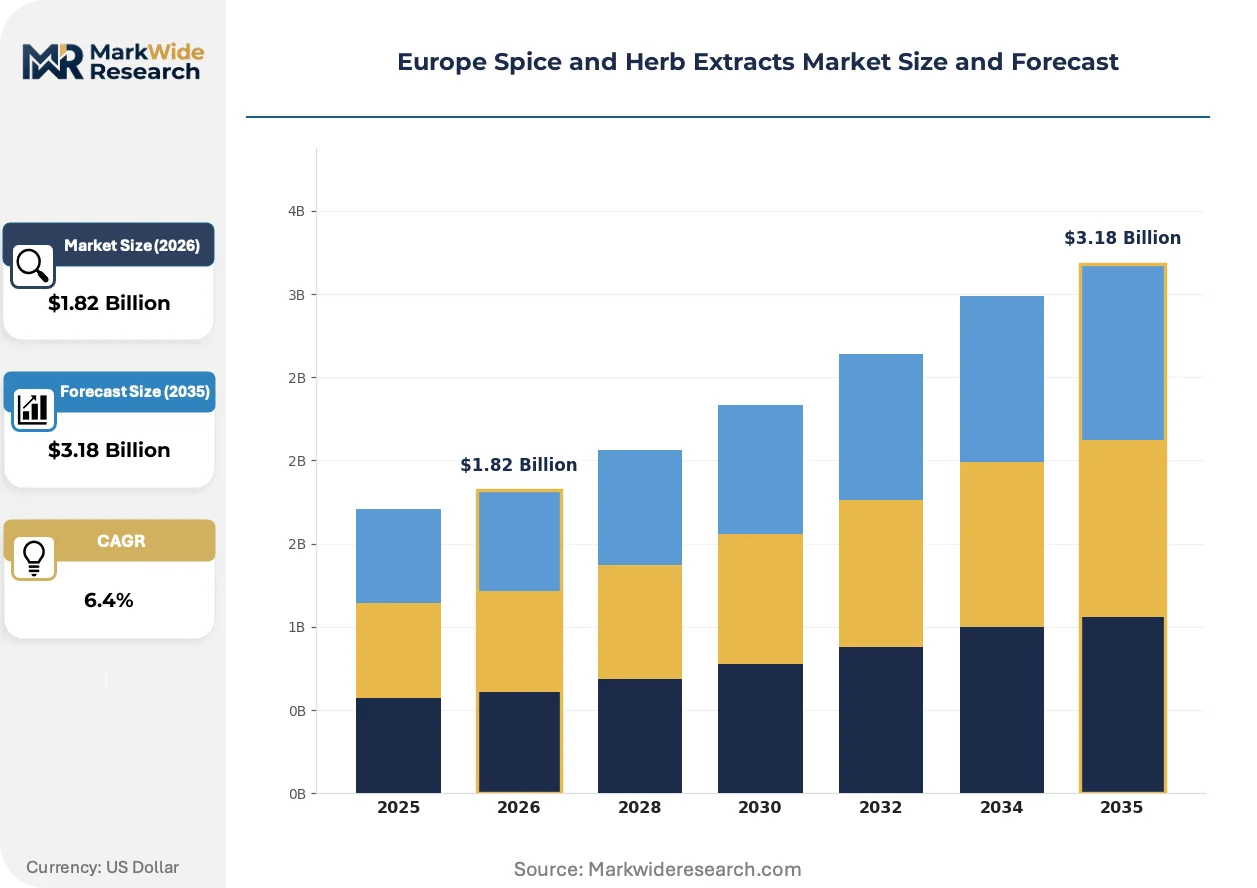
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extracts, Powder Extracts, Granular Extracts, Resin Extracts Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals End User: Food Manufacturers, Herbal Product Companies, Cosmetic Producers, Pharmaceutical Firms Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Kerry Group plc, Kalsec Inc., Döhler GmbH, Olam International, Sensient Technologies Corporation, Givaudan, Symrise AG, McCormick & Company, Frutarom Industries Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Spice and Herb Extracts Market Shifts & Advancements
Extraction technology convergence with digital traceability systems is redefining operational requirements for European botanical suppliers. These developments compress process development timelines while elevating compliance burdens.
Supercritical CO2 extraction is integrating with inline spectroscopic monitoring to enable real-time purity adjustment during oleoresin production. Mid-sized German flavor houses are adopting these hybrid systems fastest, typically completing technology transitions within 18-month windows. This convergence is compressing batch-to-batch variability and reducing post-process laboratory testing overhead.
REACH chemical safety protocols are tightening disclosure requirements for residual solvent thresholds in imported extract fractions. The regulation forces reformulation of legacy product lines and disqualifies several non-EU suppliers from tender participation. Nutraceutical contract manufacturers in Switzerland and Austria are responding by consolidating supplier panels to pre-audited European sources.
Long-term offtake agreements are displacing spot-market purchasing among major food manufacturers seeking supply security for certified-organic inputs. This contractual shift concentrates procurement leverage with integrated botanical processors capable of year-round raw material sourcing. The pattern is most visible in German sauerkraut and condiment production clusters, where three-year supply contracts now dominate volume planning.
Europe Spice and Herb Extracts Market Segmentation
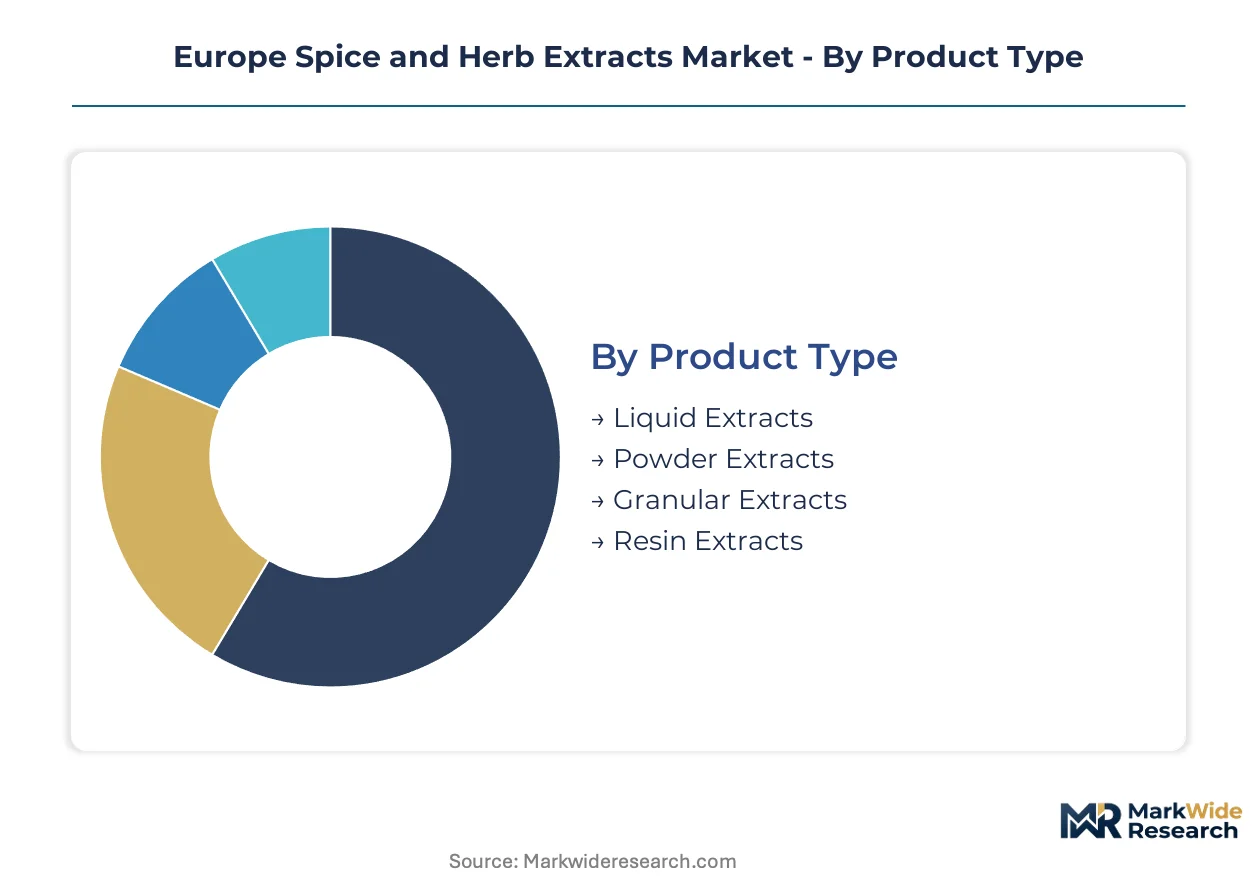
Extraction format selection drives formulation compatibility and shelf-life performance across European processed food and nutraceutical lines. Product type choices determine solvent residue profiles and EFSA Novel Food compliance pathways. Application segmentation reveals margin concentration in pharmaceutical-grade fractions versus volume scale in beverage flavoring systems.
Product Type:
Equipment upgrade cycles favor formats that reduce reformulation costs when switching between solvent-based and supercritical CO2 extraction systems.
- Liquid Extracts:Alcohol or glycerin-based solutions with 5-40% active marker concentration dissolve readily into beverage emulsions and sauce matrices. German condiment manufacturers specify liquid formats for seamless integration into existing production lines without dry-blend equipment retrofitting.
- Powder Extracts:Spray-dried or carrier-bound formulations achieve 95% purity thresholds through encapsulated volatile stabilization. Ready-meal producers in the Netherlands source powder extracts for dry seasoning sachets, though EFSA Novel Food documentation requirements extend qualification timelines for new suppliers.
- Granular Extracts:Agglomerated particles balance dispersibility with flow characteristics for industrial-scale dry blending.
- Resin Extracts:Highly concentrated oleoresin fractions serve specialized pharmaceutical and flavor compounding applications.
Liquid extracts sit at the top of the volume ranking, with powder extracts climbing the fastest.
Application:
Margin structure varies sharply across end-use segments, with certification requirements determining viable supplier pools.
- Food & Beverages:Natural flavoring and coloring applications in processed sauces, baked goods, and alcoholic beverages absorb the majority of extract volume. French and Italian beverage compounders drive demand for heat-stable color fractions from paprika and turmeric sources.
- Pharmaceuticals:Standardized phytochemical fractions meeting EMA herbal medicinal product guidelines command premium positioning. Swiss contract manufacturers consolidate procurement to pre-audited European extractors capable of batch-level traceability documentation.
- Cosmetics:Antioxidant and antimicrobial botanical actives enter dermal formulation supply chains under REACH cosmetic ingredient protocols.
- Nutraceuticals:Branded supplement makers pay traceability premiums for certified-organic provenance certified under EU organic regulation.
Food and beverages generates the largest absolute volume, while nutraceuticals delivers the steepest expansion trajectory.
End User:
Procurement sophistication separates large-scale manufacturers from specialty compounders in supplier qualification requirements.
- Food Manufacturers:Industrial processors in German sauerkraut and condiment clusters negotiate three-year offtake contracts for supply security. These buyers prioritize year-round raw material consistency over spot-market price optimization.
- Herbal Product Companies:Traditional medicine and wellness product makers require EMA-compliant documentation for botanical ingredient batches.
- Cosmetic Producers:Formulators seek REACH-registered extracts with defined dermal safety profiles for premium skincare lines.
- Pharmaceutical Firms:Drug manufacturers impose the strictest purity validation protocols, typically sourcing from GMP-certified extraction facilities.
Food manufacturers dominate procurement volume, with pharmaceutical firms expanding contract value fastest.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and documentation complexity for regulatory compliance.
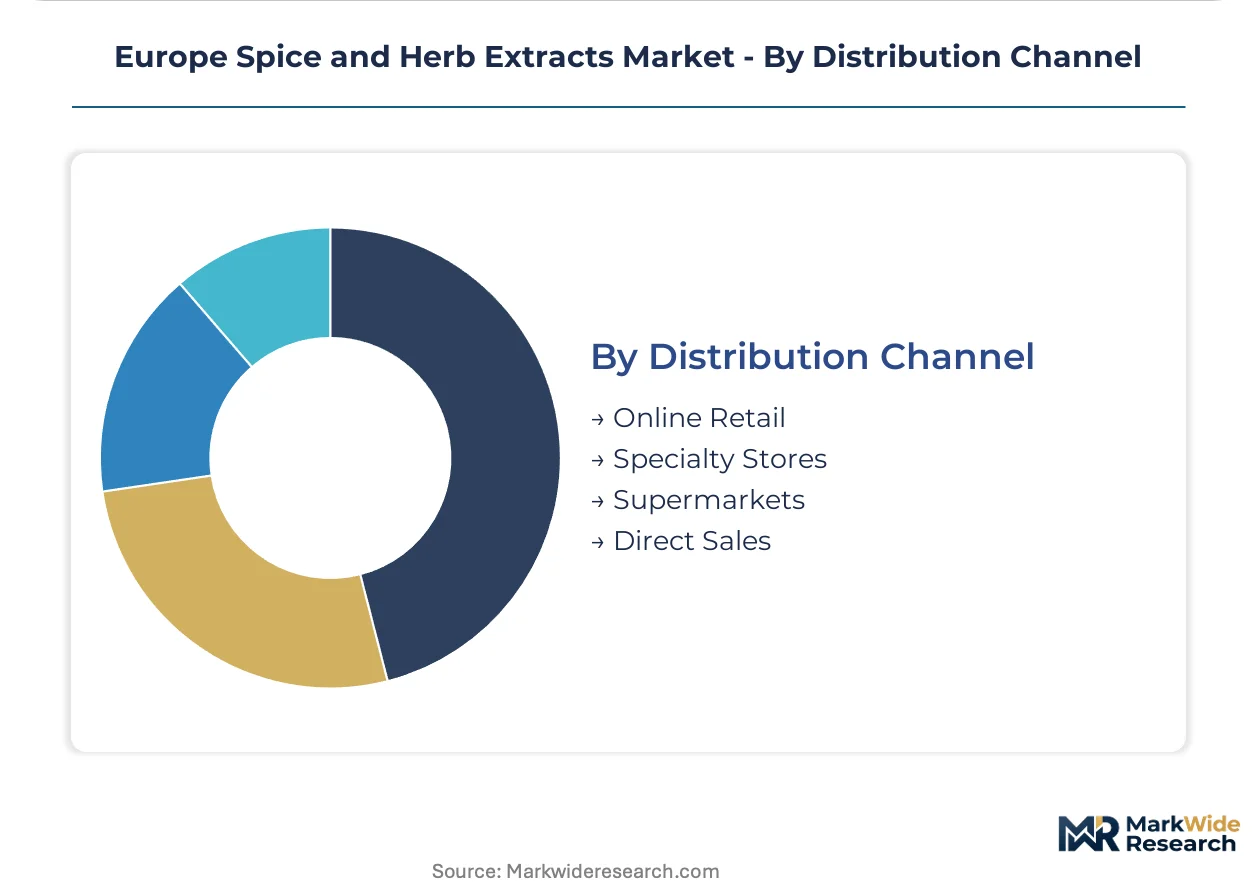
- Online Retail:E-commerce platforms serve small-batch cosmetic compounders and artisan food producers seeking minimum-order flexibility. Austrian and Swiss specialty ingredient distributors have built digital portals with integrated EFSA Novel Food documentation access.
- Specialty Stores:Regional ingredient brokers provide technical consultation for formulation troubleshooting. Spanish herb extract specialists maintain physical presence near Mediterranean cultivation zones to verify raw material provenance.
- Supermarkets:Mass-market retail channels move standardized consumer-facing extract products with basic organic certification.
- Direct Sales:Large food manufacturers and pharmaceutical firms negotiate bilateral supply agreements bypassing intermediaries.
Direct sales captures the highest volume share, with online retail gaining share fastest among emerging cosmetic and nutraceutical formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting extraction capacity toward Central European jurisdictions where EU Green Deal compliance costs remain lower than in established Western processing hubs. Poland and Romania attract greenfield investment as extractors seek to minimize F-Gas Regulation retrofitting burdens while maintaining single-market access.
Germany
Food manufacturers in Lower Saxony and Bavaria anchor continental demand for certified-organic extracts through three-year supply contracts. The country's Federal Office for Consumer Protection and Food Safety enforces strict EFSA Novel Food documentation requirements that disqualify non-compliant imports. Frankfurt-Rhine-Main processing clusters concentrate supercritical CO2 extraction capacity serving sauerkraut and condiment producers.
France
Beverage compounders in Île-de-France drive premium demand for heat-stable color fractions from paprika and turmeric sources. ANSM pharmaceutical oversight extends to botanical extracts entering medicinal product supply chains. Provence-Alpes-Côte d'Azur cultivation zones supply raw material to Grasse-area flavor houses with integrated extraction capabilities.
Spain
Mediterranean herb cultivation in Andalusia and Murcia broadens raw material availability for regional extractors despite weather-dependent yield variability. The Spanish Agency for Food Safety and Nutrition implements EFSA-aligned Novel Food protocols that extend supplier qualification timelines. Valencia processing facilities specialize in rosemary and oregano oleoresin production for export markets.
Netherlands
Ready-meal manufacturers in Randstad generate fastest-expanding powder extract demand for dry-blend convenience products. The Netherlands Food and Consumer Product Safety Authority enforces REACH chemical safety documentation for imported extract fractions. Eindhoven-region logistics hubs facilitate distribution to German and Belgian food processing clusters.
Poland
Underdeveloped extraction capacity in Silesia and Greater Poland offers first-mover positioning for EU-funded greenfield facilities. The country's national chemical regulator applies F-Gas Regulation standards with transitional compliance windows that reduce capital redeployment pressure. Warsaw-area food processors are expanding procurement of clean-label extracts for export-oriented production lines.
Europe Spice and Herb Extracts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized oleoresin and certified-organic niches to bypass incumbent scale advantages. The market structures around three tiers: integrated botanical processors with year-round sourcing networks, mid-sized flavor houses with regional agricultural partnerships, and specialist extractors with proprietary purification technologies. Dominant competitive moves include backward integration into Mediterranean cultivation zones and technology licensing agreements for supercritical CO2 system deployment.
Within the integrated processor tier, Kerry Group plc and Symrise AG exemplify archetypes combining agricultural sourcing networks with extraction capabilities. Among specialist technology providers, Kalsec Inc. occupies a position representing advanced oleoresin extraction methodologies. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their visible structural characteristics.
| Leading Market Players |
|---|
| Kerry Group plc |
| Kalsec Inc. |
| Döhler GmbH |
| Olam International |
| Sensient Technologies Corporation |
| Givaudan |
| Symrise AG |
| McCormick & Company |
| Frutarom Industries Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into Mediterranean herb cultivation zones anchors supply security and pricing power for European extractors facing EU Green Deal compliance costs. This upstream control over rosemary, oregano, and paprika feedstocks insulates integrated processors from spot-market volatility while commanding traceability premiums under EFSA Novel Food frameworks.
Pricing Analysis
Distributor margins in the three-tier pricing structure across premium, standard, and economy levels absorb certification documentation costs before reaching food manufacturers. Price differentiation hinges on organic certification tier and batch-level traceability depth, with EMA-compliant pharmaceutical-grade fractions commanding substantial premiums over beverage-grade oleoresins. Cost compression in standard-tier liquid extracts is intensifying because REACH compliance documentation raises formulation barriers against smaller suppliers. Mass-market condiment producers exhibit highest price sensitivity, while Swiss nutraceutical contract manufacturers show least elasticity for certified-organic provenance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German sauerkraut and condiment clusters, bypassing intermediaries for three-year offtake contracts. Geographic supply concentration centers on Spain, southern France, and emerging Polish processing zones, with raw material dependencies on Mediterranean climate-sensitive herb harvests, supercritical CO2 equipment, and analytical validation services. Single-source vulnerability from weather-dependent Andalusian rosemary cultivation threatens oleoresin supply continuity. Distribution runs through Frankfurt-Rhine-Main logistics hubs serving continental food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe spice and herb extracts market compounds steadily as clean-label procurement mandates from German retailers drive structural demand for certified-organic inputs. Regulatory compression under F-Gas Regulation and REACH protocols reinforces incumbent advantages while raising barriers against unstandardized imports.
For Market Incumbents: Lock in Mediterranean cultivation zones through long-term agricultural cooperative partnerships to secure year-round raw material consistency. Invest in supercritical CO2 retrofitting before EU Green Deal enforcement windows tighten, converting legacy solvent lines during planned maintenance cycles. This defensive positioning counters emerging Polish greenfield entrants and synthetic biotechnology flavor substitution threats.
For New Entrants and Emerging Players: Enter via underdeveloped Central European extraction capacity, specifically EU-funded greenfield facilities in Silesia and Greater Poland where F-Gas transitional compliance reduces capital pressure. Target powder extract production for Dutch ready-meal manufacturers facing dry-blend capacity shortages. Pursue compliance-software service revenue streams under mandatory EU AI Act traceability documentation requirements.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized flavor houses with regional agricultural partnerships because EFSA Novel Food documentation barriers prevent rapid organic growth. The 5-to-10-year viability window favors platforms consolidating pre-audited European extractors with integrated botanical sourcing. Watch for inflection when German food manufacturers accelerate long-term contract displacement of spot-market purchasing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Kerry Group plc secures year-round rosemary supply from Spanish agricultural cooperatives. |
| Supercritical CO2 Technology Deployment | Symrise AG preserves heat-sensitive volatile compounds for premium oleoresin fractions. |
| EU AI Act Traceability Compliance | Software providers capture service revenue from mandatory digital supply chain documentation. |
| Polish Greenfield Facility Development | First-movers exploit EU funding and transitional F-Gas compliance windows in Silesia. |
| Long-term Offtake Contracting | German condiment manufacturers secure supply security through three-year procurement agreements. |
Research Methodology
Direct dialogue with extraction plant managers, procurement leads at German food manufacturers, EFSA regulatory affairs specialists, and Mediterranean agricultural cooperative directors grounded the qualitative foundation. Secondary validation drew from REACH chemical safety filings, EMA herbal medicinal product registrations, EU Green Deal implementation directives, and customs trade data for botanical extract flows. Bottom-up and top-down triangulation cross-referenced facility capacity assessments against macro-level consumption trends.
Segment-level value outputs emerged from modeling across extraction format, application end-use, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs were derived through regression analysis of historical procurement patterns and projected clean-label adoption curves. Industry-specific inputs included supercritical CO2 equipment deployment timelines, EFSA Novel Food qualification durations, and organic certification conversion rates for Mediterranean cultivation zones.
The model holds under stable EU regulatory enforcement; deviation in F-Gas Regulation implementation pace or synthetic biotechnology flavor adoption rates would shift volume trajectories. Forecasts reflect documented assumptions regarding German retailer sustainability scorecard expansion and REACH disclosure threshold evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Thyme Extract Market
Spices and Seasonings
Organic Saffron Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Mint Oils Market
Spices and Seasonings
Garlic Salt Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Garlic Oleoresin Market