
 Africa Seasoning and Spices Market | 2026-2036
Africa Seasoning and Spices Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Seasoning and Spices Market Outlook
Nigeria's expanding ginger and chili processing corridors are reshaping raw material flows across West Africa. Olam Group leverages its integrated sourcing infrastructure to control quality from farm to mill. Freddy Hirsch Group anchors Southern African distribution through its seasoning manufacturing footprint in South Africa. Cape Spice Company specializes in ethnic blend formulations tailored to regional taste profiles.
Seasoning and spices encompass dried aromatic plant materials, essential oil-bearing seeds, and compounded flavor formulations used to enhance palatability and preserve food products. These materials typically undergo cleaning, drying, grinding, and blending processes to achieve specified particle sizes and volatile oil retention thresholds for industrial and culinary applications. Herbs and spices occupy the core volume position within product type segmentation, while seasoning blends capture expanding shelf space in formal retail channels. The food service end user segment drives bulk procurement patterns, whereas food manufacturers demand certified clean-label ingredients with documented supply chain traceability.
South Africa's Department of Health enforces food fortification standards that mandate iodine levels in salt and micronutrient thresholds in seasoning blends sold through formal channels. Nigeria's National Agency for Food and Drug Administration and Control monitors aflatoxin limits in ground spices and dried herbs entering interstate commerce. Kenya's Bureau of Standards applies packaging and labeling rules that shape pouch and jar specifications for domestic and export-bound products. Stakeholders must track evolving national standards harmonization initiatives to anticipate compliance cost shifts and market access barriers.
Market Dynamics
Food manufacturers across Africa are accelerating backward integration into domestic spice sourcing to circumvent tightening aflatoxin thresholds and currency-driven import cost volatility. This structural pivot is compressing traditional trading margins while elevating quality-certified local processors.
Growth Catalysts
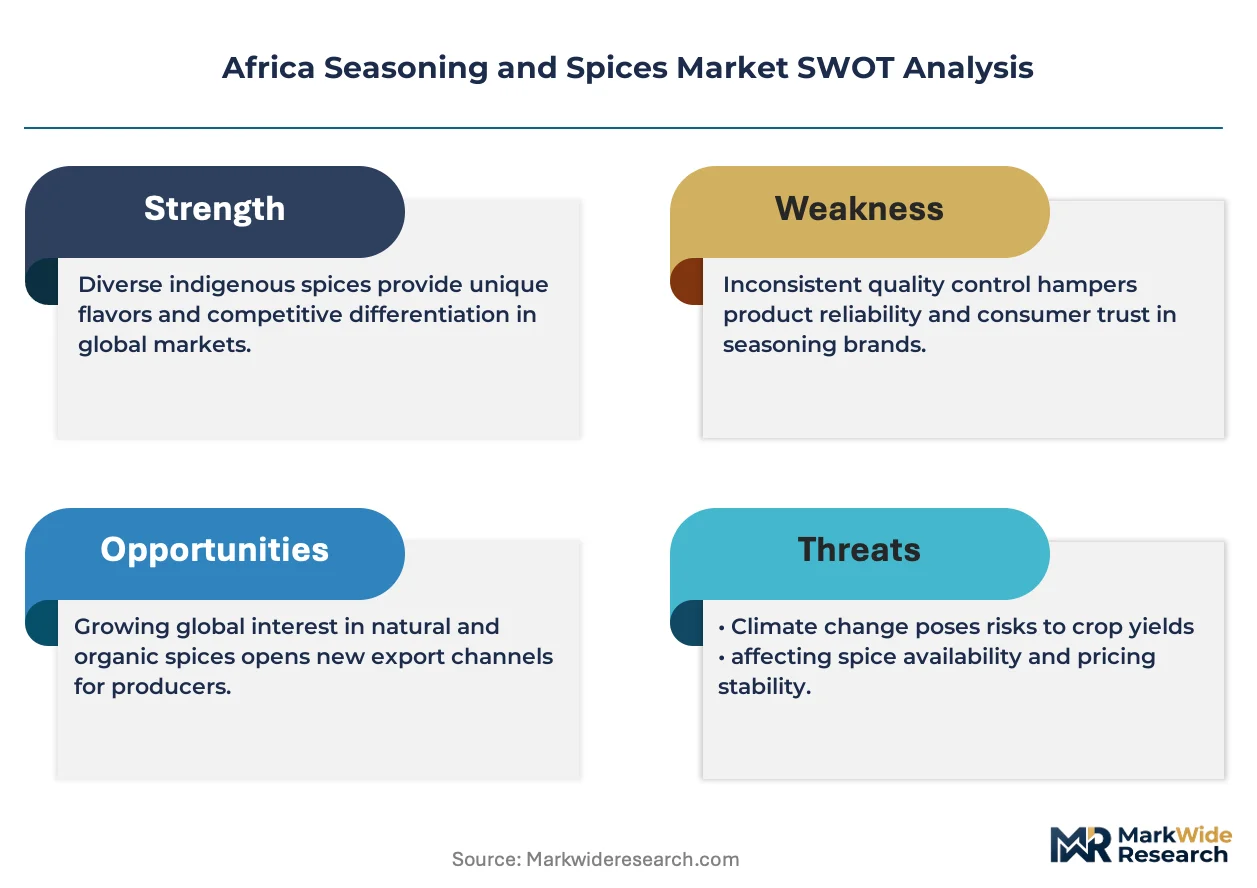
- NAFDAC aflatoxin enforcement:Nigeria's stricter monitoring of ground spices is forcing formal channel suppliers to invest in laboratory testing infrastructure, creating tiered market access for certified versus uncertified producers.
- Urban food service expansion:Quick-service restaurant chains in Lagos and Johannesburg are standardizing proprietary seasoning blends across franchise networks, driving bulk procurement contracts with documented traceability.
- Solar drying cooperatives:Post-harvest processing technology in ginger and chili corridors is reducing moisture-related spoilage and volatile oil degradation, improving raw material consistency for industrial buyers.
Market Restraints
- Input cost volatility:Erratic rainfall patterns in Ethiopia's korarima growing regions are disrupting cardamom supply cycles and amplifying price swings for blend manufacturers dependent on consistent recipes.
- Supply concentration risk:Over half of Southern Africa's industrial paprika processing capacity sits within a 200-kilometer radius of Pretoria, exposing buyers to localized logistics disruptions and single-source dependency.
- Technical limitation:Smallholder drying practices in Madagascar's vanilla belt struggle to meet European ethylene oxide residue standards, excluding artisanal producers from formal export channels.
Strategic Opportunities
- Underpenetrated East African retail:Formal supermarket penetration in Tanzania and Uganda remains below fifteen percent, creating first-mover shelf space for packaged ethnic blends targeting emerging middle-class households.
- Regulatory tailwind:South Africa's mandatory salt iodization and micronutrient fortification rules are compelling reformulation of existing seasoning lines, opening technical partnership opportunities between blenders and premix suppliers.
- Technology convergence:Blockchain-enabled farm-to-retail traceability platforms combined with mobile payment systems are enabling direct farmer-aggregator-processor linkages that bypass traditional commodity brokers.
Industry Challenges
- Certification timeline compression:Kenya's Bureau of Standards has shortened approval windows for revised packaging claims, forcing exporters to accelerate label redesign and laboratory validation cycles.
- Capex intensity:Steam sterilization equipment required for EU-bound spice shipments demands capital outlays that exceed the balance sheet capacity of most mid-scale Nigerian processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Seasoning and Spices Market |
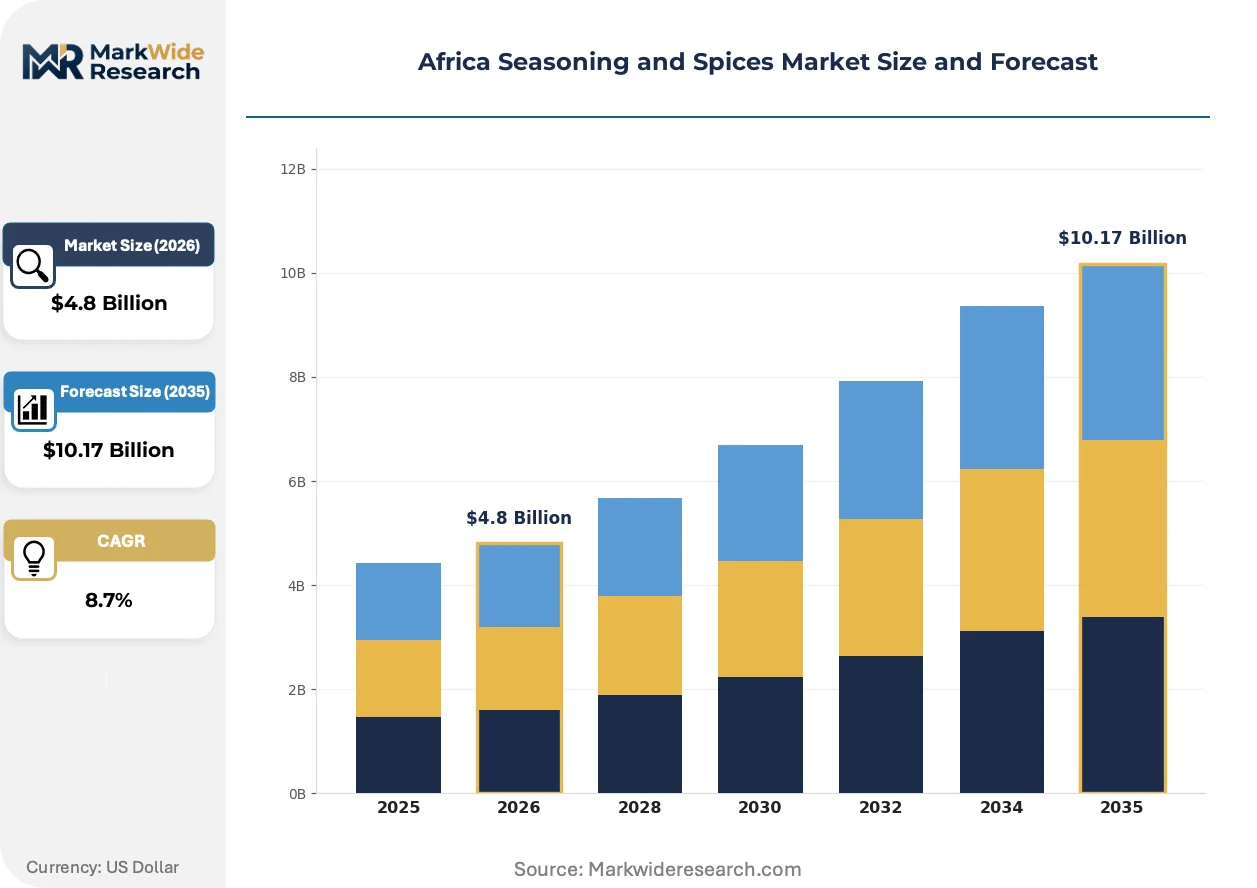
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbs, Spices, Seasoning Blends, Salt End User: Households, Food Service, Retail, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores Packaging Type: Bottles, Pouches, Cans, Jars |
| Companies Covered | Givaudan, Spice Importers and Millers CC, McCormick & Company Inc, Cape Spice Company, Exim International (Pty) Ltd, Freddy Hirsch Group, Olam Group, Natpro Spicenet (Pty) Ltd, Kerry Group, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Seasoning and Spices Market Strategic Shifts
Processing technology and procurement protocols across Africa's seasoning sector are converging around contamination control and supply chain transparency. These shifts are reconfiguring competitive advantage toward integrated quality systems rather than commodity trading relationships.
Near-infrared spectroscopy for rapid mycotoxin detection is migrating from laboratory environments to receiving bays at major processing facilities. Industrial buyers in Nigeria's ginger belt are deploying handheld devices to screen incoming shipments within minutes rather than days. This capability is compressing rejection windows and forcing upstream suppliers to invest in pre-drying quality controls.
South Africa's Department of Health has tightened enforcement timelines for salt iodization compliance in blended seasonings. Manufacturers now face accelerated audit cycles and public disclosure requirements for fortification levels. Medium-scale blenders are responding by consolidating premix sourcing to certified suppliers with documented batch testing.
Food manufacturers are consolidating supplier rosters to single-source relationships with integrated processors capable of farm-origin documentation. This concentration is displacing spot-market purchasing through commodity brokers in Lagos and Nairobi. Large retail chains in Johannesburg are now requiring blockchain-verified provenance claims for premium private-label spice lines.
Africa Seasoning and Spices Market Segmentation
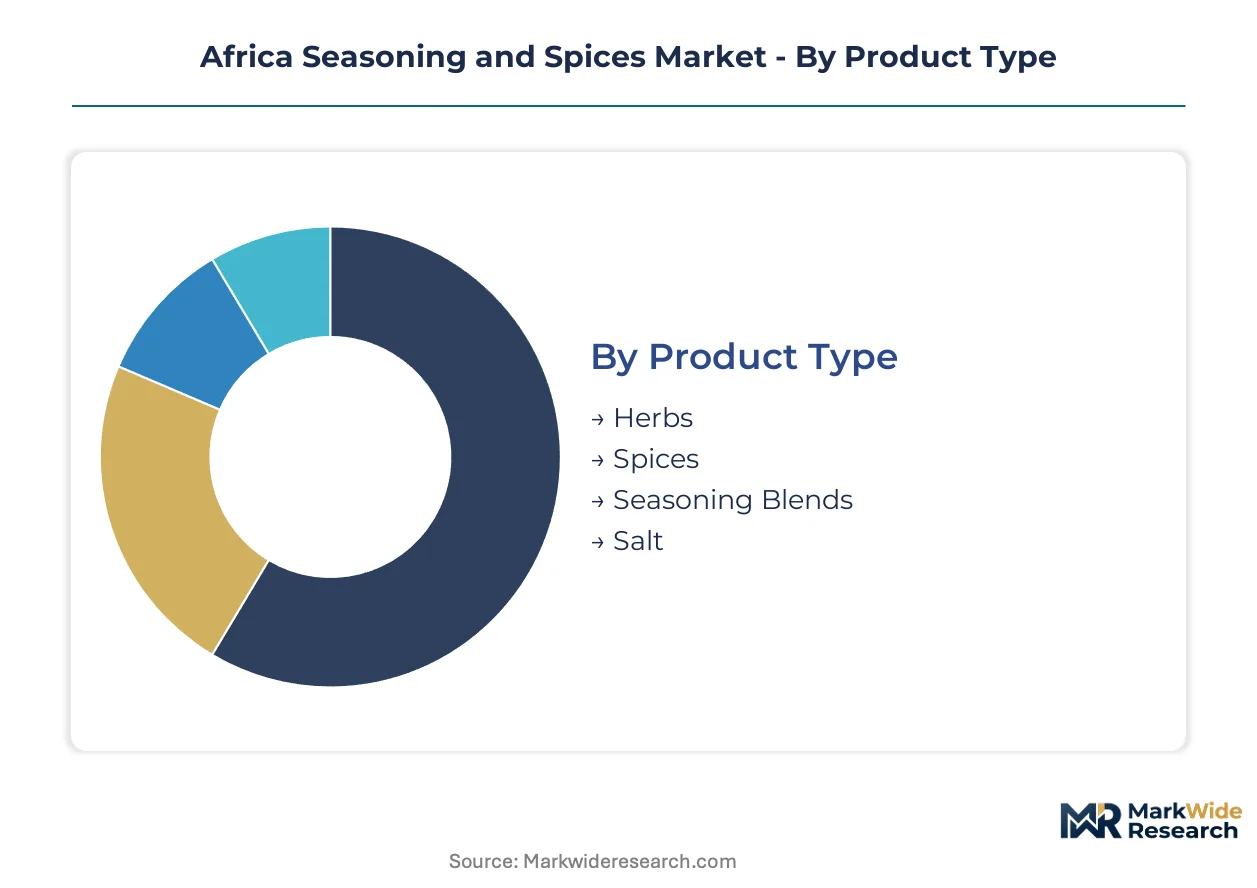
Segmentation in Africa's seasoning and spices market reveals how procurement priorities diverge across formal and informal channels. Raw material quality thresholds, packaging regulations, and end-user traceability requirements create distinct competitive arenas that reward specialized capabilities over commodity trading.
Product Type:
Volume concentration and margin structure vary sharply across these four product categories, with processing intensity determining supplier viability.
- Herbs:Dried leafy plant materials including basil, oregano, and thyme retain volatile oil specifications critical for industrial buyers. Nigeria's NAFDAC enforces aflatoxin limits that disqualify sun-dried smallholder supply from formal retail, channeling certified volumes toward Johannesburg and Lagos food manufacturers.
- Spices:Seed, bark, and root derivatives such as ginger, cardamom, and paprika drive the bulk of raw material trade flows. Ethiopian korarima harvest volatility and Madagascar vanilla residue compliance struggles concentrate procurement risk for blenders dependent on consistent recipe inputs.
- Seasoning Blends:Compounded formulations combining multiple spices, salt, and flavor enhancers capture expanding shelf space in formal retail. South Africa's fortification mandates for iodine and micronutrients force reformulation partnerships between blenders and premix suppliers.
- Salt:Mineral-derived sodium chloride serves as both standalone commodity and blend base material. Kenya's Bureau of Standards packaging specifications and South Africa's iodization requirements split the market between bulk industrial supply and consumer-packaged segments.
Herbs and spices command the established base. The steepest expansion runs through seasoning blends.
End User:
Customer type determines specification rigor, with formal channel buyers imposing documentation and certification burdens that informal traders bypass.
- Households:Individual consumers purchasing through retail channels drive pouch and jar volume. Tanzania and Uganda's sub-fifteen-percent supermarket penetration leaves traditional markets dominant, though emerging middle-class households in Dar es Salaam and Kampala are shifting toward packaged ethnic blends.
- Food Service:Quick-service restaurant chains and institutional kitchens procure bulk quantities with standardized specifications. Lagos and Johannesburg franchise networks are consolidating supplier rosters to single-source relationships with integrated processors capable of blockchain-verified provenance.
- Retail:Supermarket and specialty store channels intermediate between manufacturers and household buyers. South Africa's formal retail concentration around Johannesburg and Cape Town creates tiered access for certified versus uncertified producers.
- Food Manufacturers:Industrial buyers of ingredient inputs demand documented supply chain traceability and contaminant testing. NAFDAC's compressed approval windows for revised packaging claims force exporters to accelerate laboratory validation cycles.
Food manufacturers anchor procurement volume. Food service is climbing the fastest.
Distribution Channel:
Channel structure shapes pricing realization and working capital requirements, with formal retail extracting compliance investments that wholesale bypasses.
- Supermarkets:Formal retail chains in South Africa's urban corridors require blockchain-verified provenance claims for premium private-label lines. Shelf slotting fees and listing standards exclude uncertified processors.
- Online Retail:Digital platforms are enabling direct farmer-aggregator-processor linkages that bypass traditional commodity brokers in Lagos and Nairobi. Mobile payment convergence reduces transaction friction for cross-border spice trade.
- Wholesale:Traditional commodity brokers dominate raw material flows across West and East Africa. Spot-market purchasing persists where traceability documentation remains absent.
- Specialty Stores:Ethnic and gourmet retailers cater to diaspora demand and premium household segments in Johannesburg and Lagos. Regional taste profile specialization creates niche positioning for blend formulators.
Wholesale channels retain volume dominance. Online retail is gaining share fastest.
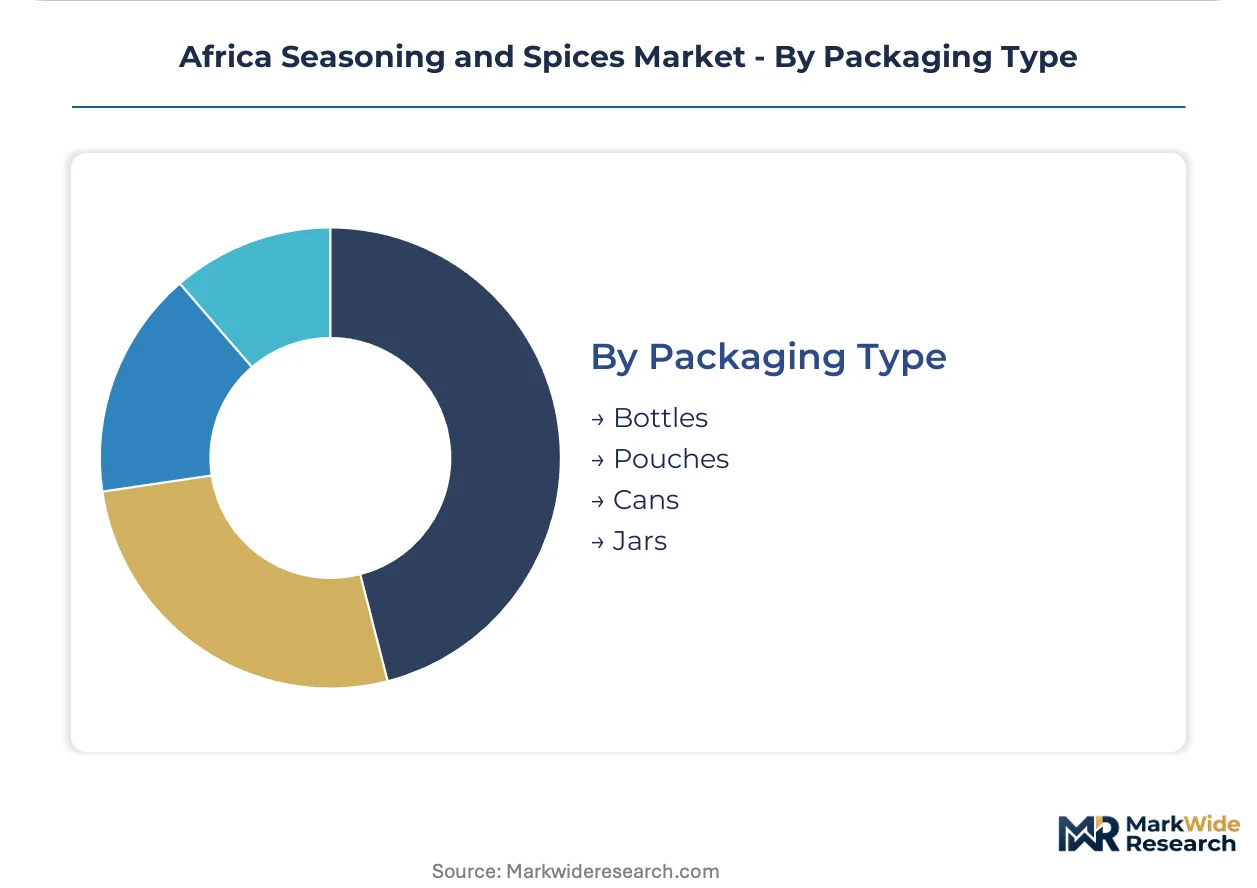
Packaging Type:
Packaging specifications respond to regulatory labeling rules, moisture protection requirements, and retail shelf presentation standards.
- Bottles:Rigid glass and plastic containers suit premium positioning and repeated-use household segments. Kenya's Bureau of Standards labeling rules shape bottle specification for export-bound products.
- Pouches:Flexible laminated films dominate mass-market seasoning blends and single-use spice portions. Compressed material costs and logistics efficiency favor pouch adoption in price-sensitive markets.
- Cans:Metal containers serve industrial bulk supply and long-shelf-life export requirements. Steam sterilization compatibility for EU-bound shipments demands capital equipment beyond mid-scale processor capacity.
- Jars:Wide-mouth rigid packaging facilitates spoon-access for thick paste seasonings and wet spice blends. South African retail channels specify jar formats for premium private-label lines.
Pouches hold the volume base. Bottles are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NAFDAC's aflatoxin enforcement protocols in Nigeria are reshaping procurement patterns across West African spice corridors. South Africa's Department of Health fortification mandates drive reformulation activity in Southern African blending facilities. National regulators from Nairobi to Lagos are tightening contaminant thresholds and packaging specifications simultaneously.
Nigeria
Urban food service chains in Lagos and Abuja are standardizing proprietary seasoning blends across quick-service restaurant networks. NAFDAC monitors aflatoxin limits in ground spices and dried herbs entering interstate commerce. Ginger and chili processing corridors in Kaduna and Kano states are expanding solar drying infrastructure to reduce moisture-related spoilage.
South Africa
Formal retail channels in Johannesburg and Cape Town require blockchain-verified provenance claims for premium private-label spice lines. The Department of Health enforces iodine levels in salt and micronutrient thresholds in seasoning blends sold through formal channels. Industrial paprika processing capacity concentrates within a 200-kilometer radius of Pretoria.
Kenya
Emerging middle-class households in Nairobi and Mombasa are shifting toward packaged ethnic blends through expanding supermarket penetration. The Bureau of Standards applies packaging and labeling rules that shape pouch and jar specifications for domestic and export-bound products. Smallholder drying practices in the Mount Kenya region struggle to meet residual contaminant standards for formal export channels.
Ethiopia
Cardamom demand from blend manufacturers depends on consistent korarima harvest cycles from the SNNPR and Oromia highlands. The country's national food safety authority monitors moisture content and volatile oil retention in dried spice shipments. Addis Ababa serves as the primary collection and export staging point for highland-grown aromatic seeds.
Tanzania
Formal supermarket penetration remains below fifteen percent, creating first-mover shelf space for packaged ethnic blends in Dar es Salaam and Arusha. The Tanzania Bureau of Standards enforces labeling and fortification compliance for seasoning products entering domestic retail. Ginger and turmeric processing clusters in the Morogoro corridor are attracting backward integration investments from regional food manufacturers.
Africa Seasoning and Spices Market Competitive Environment
Capability concentration sits with integrated processors controlling farm-to-mill quality systems; scale advantage sits with diversified agribusiness conglomerates with pan-African distribution networks. The market structures around three tiers: multinational flavor houses with technical premix capabilities, regional integrated processors with traceable sourcing infrastructure, and commodity traders dependent on spot-market purchasing. Competitive moves center on backward integration into domestic spice sourcing and consolidation of supplier rosters to single-source relationships with documented provenance.
Among integrated African processors, Olam Group and Freddy Hirsch Group exemplify the control-over-quality archetype through captive sourcing infrastructure. Cape Spice Company occupies a specialist position in ethnic blend formulations tailored to regional taste profiles. These three represent distinct competitive vectors: pan-continental scale, Southern African distribution anchoring, and niche formulation expertise respectively.
| Leading Market Players |
|---|
| Givaudan |
| Spice Importers and Millers CC |
| McCormick & Company Inc |
| Cape Spice Company |
| Exim International (Pty) Ltd |
| Freddy Hirsch Group |
| Olam Group |
| Natpro Spicenet (Pty) Ltd |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Pretoria's paprika processing cluster concentrates over half of Southern Africa's industrial capacity within a 200-kilometer radius, anchoring margin pools with blend manufacturers dependent on consistent recipe inputs while exposing buyers to localized logistics disruptions.
Pricing Analysis
Price spreads between certified and uncertified spice shipments widen across the Lagos-Johannesburg corridor as NAFDAC's aflatoxin enforcement compresses market access for non-compliant producers. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified provenance claims from traditional commodity spot purchases. Cost compression in mid-scale processing tiers intensifies because steam sterilization equipment for EU-bound shipments demands capital outlays beyond most Nigerian processor balance sheets. Food manufacturers demonstrate lowest price sensitivity due to mandatory traceability documentation, while traditional wholesale traders in informal channels face acute margin pressure from solar-drying cooperative competition.
Supply Chain Analysis
Contract manufacturing concentration sits with Olam Group's integrated farm-to-mill infrastructure and Freddy Hirsch Group's Southern African seasoning manufacturing footprint, with Cape Spice Company occupying specialist ethnic blend formulation capacity. Geographic supply concentrates in Nigeria's ginger and chili corridors, Ethiopia's korarima highlands, and Madagascar's vanilla belt. Raw material dependencies center on cardamom harvest cycles, paprika color consistency, and vanilla ethylene oxide compliance. Single-source vulnerability runs through Pretoria's paprika processing radius. Distribution runs through formal retail chains requiring blockchain verification, wholesale commodity brokers in Lagos and Nairobi, and emerging online platforms enabling direct farmer-aggregator-processor linkages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC's compressed certification timelines and South Africa's iodization mandates are disrupting established trading relationships, creating acquisition opportunities for quality-integrated processors.
For Market Incumbents: Insulate market position by consolidating premix sourcing to certified suppliers with documented batch testing ahead of South Africa's accelerated audit cycles. Deepen backward integration into Nigeria's solar-drying ginger corridors to circumvent spot-market volatility and secure aflatoxin-compliant raw material flows. For New Entrants and Emerging Players: Pursue shelf space in Tanzania and Uganda's sub-fifteen-percent supermarket penetration zones with packaged ethnic blends targeting Dar es Salaam and Kampala's emerging middle-class households. Leverage mobile payment convergence to establish direct farmer-aggregator-processor linkages bypassing traditional Lagos and Nairobi commodity brokers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with captive sourcing infrastructure and blockchain-enabled traceability platforms capable of serving Johannesburg's formal retail provenance requirements. Long-term viability centers on quality-certification moats rather than commodity trading scale. Watch for NAFDAC laboratory testing infrastructure investments as inflection signal for tiered market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Sourcing | Olam Group's farm-to-mill infrastructure reduces import dependency and aflatoxin exposure for Nigerian food manufacturers. |
| Blockchain Traceability Platform Deployment | Johannesburg retail chains now require verified provenance claims for premium private-label spice lines. |
| Solar Drying Cooperative Expansion | Kaduna and Kano state infrastructure reduces moisture-related spoilage and volatile oil degradation for industrial buyers. |
| Premix Supplier Consolidation | South Africa's iodization mandates force medium-scale blenders toward certified suppliers with documented batch testing. |
| Near-Infrared Spectroscopy Adoption | Handheld mycotoxin detection devices compress rejection windows at Nigerian ginger belt receiving bays. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs records, NAFDAC enforcement bulletins, South African Department of Health fortification disclosures, and trade flow databases. Interviews with spice processing plant managers, procurement leads at Lagos and Johannesburg food manufacturers, distribution channel partners in Nairobi and Dar es Salaam, and technical R&D directors at integrated agribusiness conglomerates inform qualitative assessments. Bottom-up volume modeling from identified processing facilities triangulates against top-down consumption estimates derived from retail channel audits.
Forecast inputs span product type segmentation across herbs, spices, seasoning blends, and salt; end-user categories from household retail through food service and industrial manufacturing; distribution channel evolution from wholesale through online retail; and packaging format specifications governed by Kenya's Bureau of Standards and South Africa's labeling mandates. CAGRs derive from regression analysis against historical trade volumes and projected urban food service expansion across Lagos and Johannesburg metropolitan corridors.
Sensitivities concentrate around NAFDAC enforcement intensity, rainfall volatility in Ethiopia's korarima regions, and European ethylene oxide residue standard revisions affecting Madagascar vanilla access. Quarterly review of aflatoxin laboratory certification rates, solar drying cooperative formation pace, and blockchain traceability platform adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Onion Powder Market
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
Jalapeno Salt Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Organic Spice Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Celery Seed Extract Powder Market