
 Ginger Oil Market | 2026-2036
Ginger Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Ginger Oil Market Analysis
EU REACH compliance is hardening purity requirements for essential oil imports, forcing suppliers to upgrade chromatographic testing and batch traceability systems. Synthite Industries Pvt. Ltd. leverages its integrated Kerala extraction facilities to control raw ginger supply from farm to distillate. The Lebermuth Co. Inc. sustains North American distribution dominance through decades-long relationships with flavor houses and cosmetic formulators. doTERRA International LLC differentiates via direct-to-consumer channels and proprietary sourcing standards that command premium positioning.
Ginger oil is a volatile essential oil extracted from the rhizome of Zingiber officinale, typically containing 20-30% zingiberene and 15-25% sesquiphellandrene by GC-MS analysis, with steam distillation yielding a pale yellow to amber liquid used primarily for flavoring, fragrance, and therapeutic applications. Steam distilled ginger oil occupies the largest volume share due to cost efficiency and standardized terpene profiles favored by industrial buyers. Organic ginger oil is gaining fastest in cosmetics and aromatherapy channels where clean-label certification supports price premiums. Cold pressed variants retain higher gingerol content, attracting pharmaceutical and nutraceutical formulators seeking bioactive standardization.
India's BIS essential oil standards, the EU REACH framework, and the US FDA food additive regulations collectively govern market access, with each jurisdiction imposing distinct limits on pesticide residues and heavy metals that filter supplier eligibility. ISO 9001 and GMP certifications have become baseline requirements for contract manufacturing relationships with multinational flavor and fragrance houses. Stakeholders must monitor how evolving organic certification reciprocity between India and the EU reshapes competitive sourcing dynamics.
Market Dynamics
EU REACH compliance is hardening purity requirements for essential oil imports, forcing suppliers to upgrade chromatographic testing and batch traceability systems while reshaping competitive eligibility across extraction and distribution tiers.
Growth Catalysts
- Clean-label certification pull:Food and beverage manufacturers are expanding ginger oil procurement for natural flavoring applications as synthetic alternatives face consumer rejection. Formulators prioritize organic grades to secure shelf placement in premium retail channels.
- REACH framework expansion:The EU's Registration, Evaluation, Authorisation and Restriction of Chemicals regulation is mandating enhanced documentation for essential oil imports. Compliance investments by Indian and Indonesian suppliers are unlocking premium market access previously blocked by documentation gaps.
- Steam distillation standardization:Industrial buyers favor standardized terpene profiles from steam distilled ginger oil for batch consistency. Flavor houses consolidate procurement around suppliers with in-house GC-MS verification capabilities.
Market Restraints
- Raw ginger price volatility:Rhizome harvest fluctuations in Kerala and Karnataka directly compress extraction margins. Distillers lack forward-contracting depth to hedge against monsoon-driven supply interruptions.
- Organic certification reciprocity gaps:Non-recognition between India's National Programme for Organic Production and EU organic standards forces dual certification costs. Smallholder-dependent supply chains struggle to absorb audit expenses for both jurisdictions.
- Supercritical CO2 substitution pressure:Selective extraction technologies for ginger oleoresin capture higher gingerol concentrations for pharmaceutical applications. Oleoresin formulators are diverting R&D budgets away from traditional essential oil matrices.
Strategic Opportunities
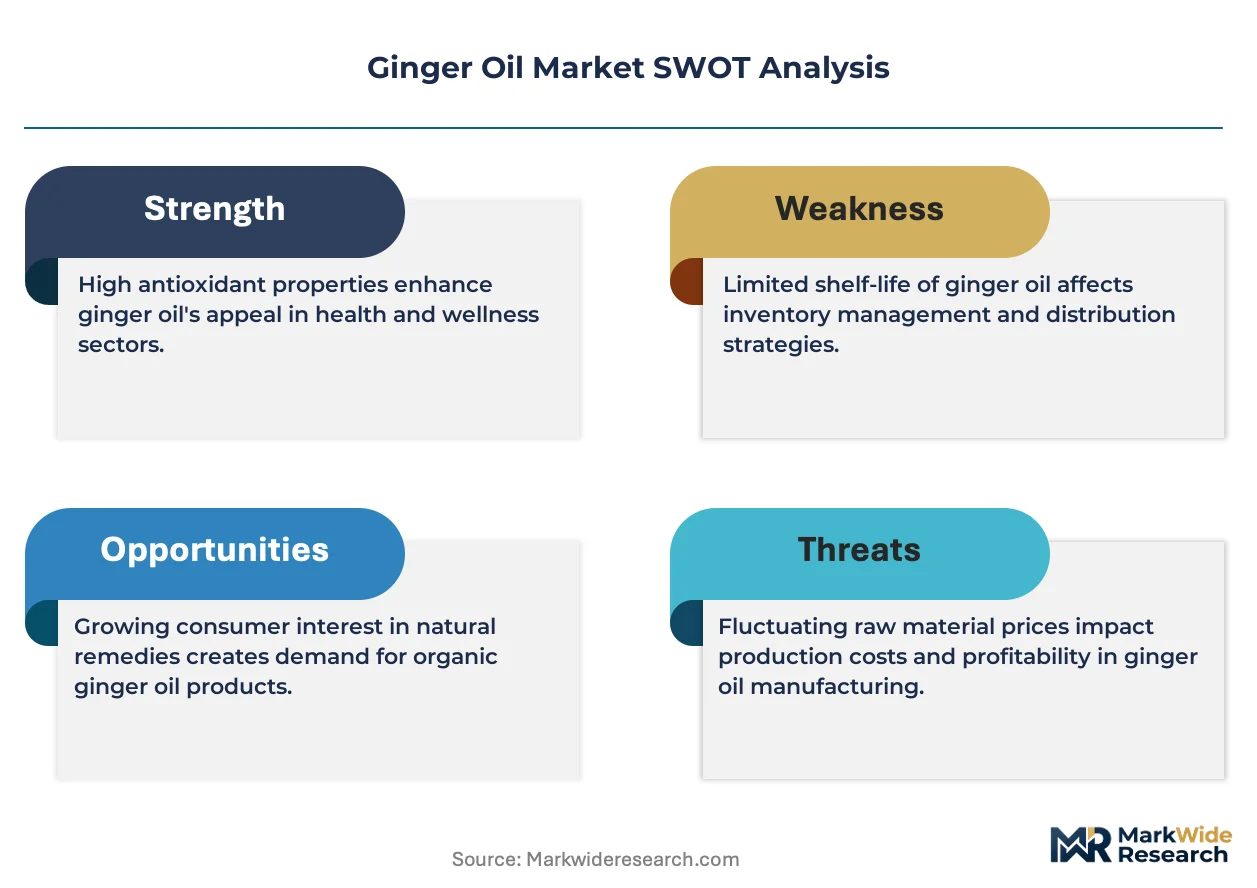
- Cosmeceutical channel expansion:Cold pressed ginger oil variants with elevated gingerol content are attracting pharmaceutical and nutraceutical formulators seeking bioactive standardization. Clean-label positioning supports price premiums in dermal and topical delivery systems.
- BIS-REACH alignment lobbying:Stakeholders can accelerate organic certification reciprocity negotiations between India's Bureau of Indian Standards and EU competent authorities. Mutual recognition would eliminate redundant audit costs for cross-border suppliers.
- Direct-to-consumer aromatherapy:Digital-native wellness brands are building proprietary sourcing narratives around single-origin ginger oil. Subscription models bypass traditional flavor house intermediaries and capture retail margin pools.
Industry Challenges
- Chromatographic analyst scarcity:GC-MS interpretation expertise for terpene profiling is concentrated in legacy flavor and fragrance houses. Emerging extraction facilities in Uttar Pradesh and Tamil Nadu face recruitment bottlenecks for qualified quality control personnel.
- Batch traceability system integration:Blockchain and ERP upgrades for farm-to-distillate tracking require capital deployment that conflicts with seasonal working capital cycles. Small and mid-scale distillers delay compliance investments until contract volumes justify fixed cost absorption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ginger Oil Market |
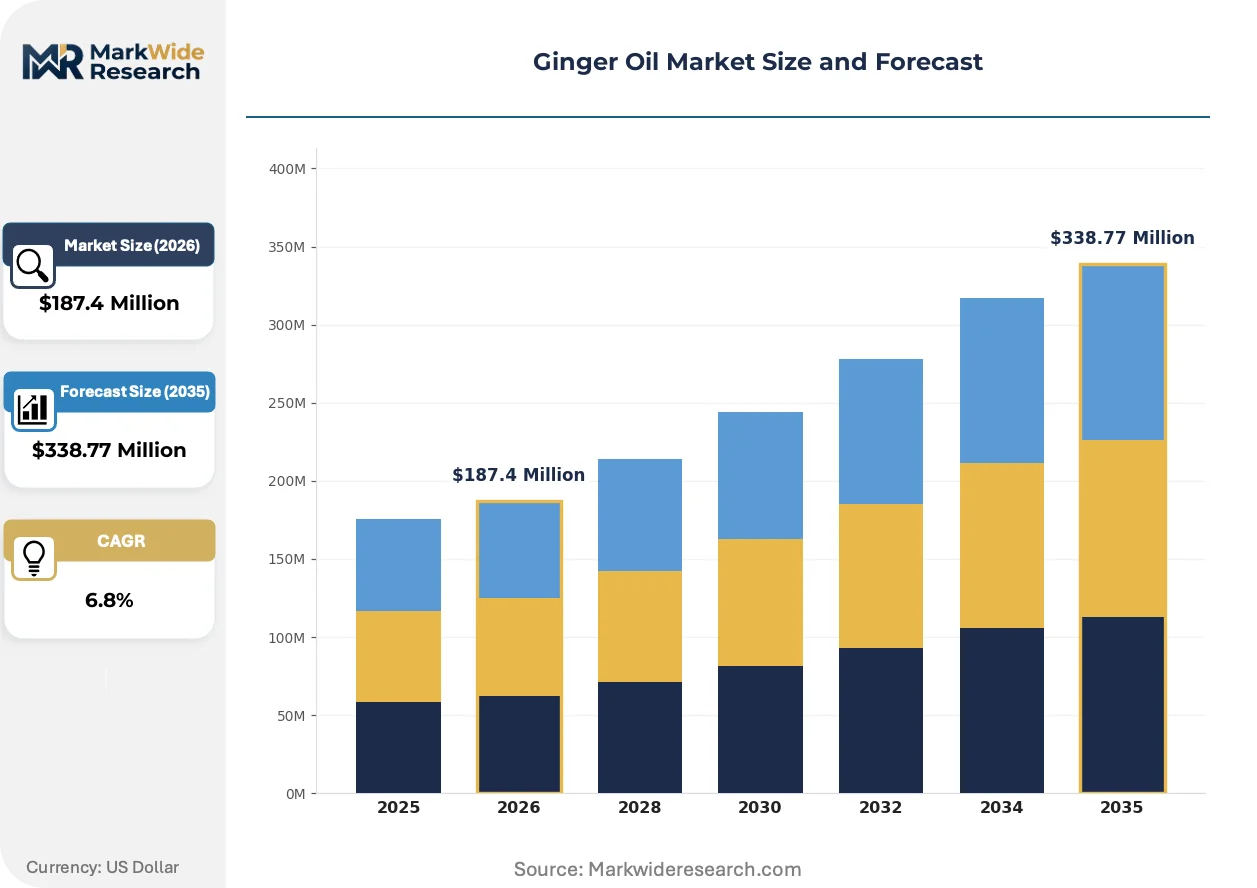
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Ginger Oil, Steam Distilled Ginger Oil, Cold Pressed Ginger Oil, Others Application: Cosmetics, Food & Beverage, Aromatherapy, Pharmaceutical End User: Households, Health & Wellness Centers, Food Industries, Cosmetic Manufacturers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Synthite Industries Pvt. Ltd., The Lebermuth Co. Inc., Young Living Essential Oils, New Directions Aromatics Inc., Edens Garden, doTERRA International LLC, International Flavors and Fragrances Inc., Ozone Naturals, AOS Products Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ginger Oil Market Emerging Trajectories
Supercritical fluid extraction and blockchain traceability are redrawing competitive boundaries between commodity distillers and premium positioning specialists across the ginger oil value chain.
Supercritical CO2 extraction technology is decentralizing quality control from centralized flavor house laboratories to origin-based processing facilities. Mid-scale Indian distillers in Kerala and Karnataka are adopting semi-continuous CO2 systems to capture oleoresin fractions with precise gingerol standardization. This capability shift is compressing the traditional advantage of European and North American extraction houses that previously controlled high-value pharmaceutical-grade output.
The EU REACH framework is tightening heavy metal and pesticide residue thresholds for essential oil imports entering the European Economic Area. ECHA documentation requirements now mandate full supply chain disclosure from rhizome cultivation through final distillation. Organic-certified ginger oil imports from India face the steepest compliance burden, with BIS-certified suppliers accelerating investment in ICP-MS testing infrastructure to maintain market access.
Flavor house procurement patterns are fragmenting as mid-sized food manufacturers build direct relationships with origin distillers. Digital platforms for sample validation and contract negotiation are displacing traditional broker networks in North American and European buying offices. This disintermediation is most visible in the natural and organic retail segment, where private-label formulators prioritize transparent sourcing narratives over incumbent supplier relationships.
Ginger Oil Market Segmentation
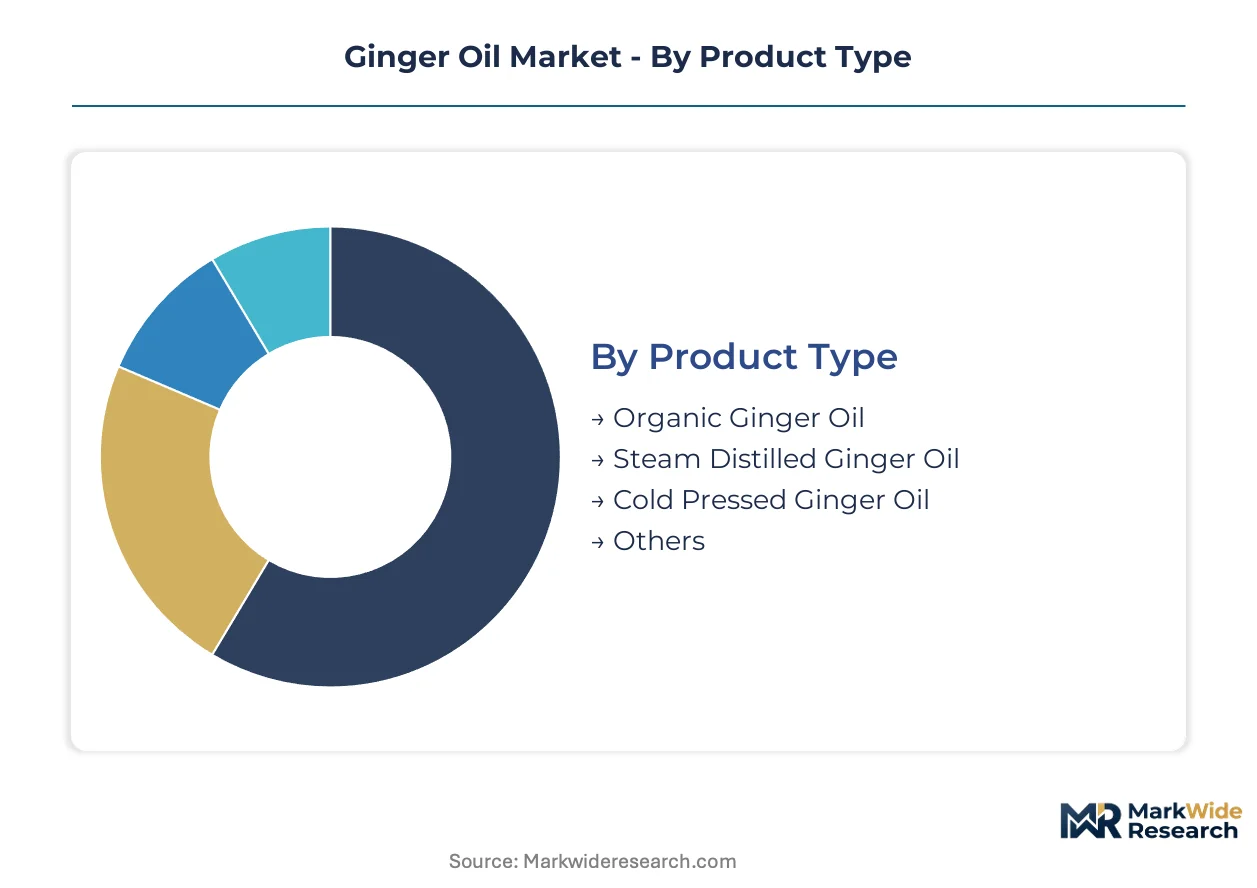
Segmentation in ginger oil reveals how extraction methods, certification grades, and channel strategies partition margin pools across industrial buyers and direct consumers. Understanding these splits exposes where standardization premiums apply versus where origin narratives command price multiples.
Product Type:
Volume concentration favors cost-optimized extraction, while premium positioning clusters around certification and bioactive retention.
- Steam Distilled Ginger Oil:Pale yellow to amber liquid containing 20-30% zingiberene and 15-25% sesquiphellandrene by GC-MS analysis. Industrial flavor houses in the United States and Germany consolidate procurement around this grade for batch consistency in beverage and confectionery applications. Standardized terpene profiles reduce formulation rework costs.
- Organic Ginger Oil:Certified under India's National Programme for Organic Production or EU-equivalent standards, commanding shelf placement premiums in natural retail channels. Clean-label certification supports price multiples in cosmetics and aromatherapy segments where ingredient transparency drives consumer selection.
- Cold Pressed Ginger Oil:Retains higher gingerol content than thermally processed alternatives, attracting pharmaceutical formulators seeking bioactive standardization for topical and nutraceutical delivery systems.
- Others:Solvent-extracted and CO2-derived variants serving niche pharmaceutical and research applications with specific purity requirements.
Mature deployment sits with Steam Distilled Ginger Oil. Newer deployment is concentrated in Organic Ginger Oil.
Application:
Demand fragmentation tracks regulatory exposure, with food-grade volumes separating from cosmetic and therapeutic premiums based on compliance burden.
- Food & Beverage:Natural flavoring applications dominate procurement volumes as synthetic alternatives face consumer rejection. Manufacturers prioritize organic grades to secure placement in premium retail channels with clean-label positioning.
- Cosmetics:Cold pressed variants with elevated gingerol content attract dermal and topical formulators. Bioactive standardization supports price premiums in clean-label cosmeceutical channels.
- Aromatherapy:Direct-to-consumer wellness brands build proprietary sourcing narratives around single-origin ginger oil, bypassing traditional flavor house intermediaries through subscription models.
- Pharmaceutical:Precise gingerol concentration requirements drive selective extraction technology adoption, with supercritical CO2 systems displacing traditional distillation for high-potency applications.
Volume leadership remains with Food & Beverage. Steepest expansion trajectory belongs to Cosmetics.
End User:
Customer type determines contract structure, with industrial buyers demanding batch traceability systems that household channels ignore.
- Food Industries:Consolidated procurement around suppliers with in-house GC-MS verification capabilities. REACH documentation requirements filter supplier eligibility for European Economic Area access.
- Cosmetic Manufacturers:Clean-label certification requirements concentrate sourcing decisions on organic-certified origins with blockchain-tracked supply chains.
- Health & Wellness Centers:Therapeutic-grade specifications favor cold pressed and organic variants with verified bioactive content for topical and inhalation protocols.
- Households:Digital-native purchasing through direct-to-consumer channels prioritizes origin storytelling and subscription convenience over technical specifications.
Contract scale peaks with Food Industries. Channel experimentation concentrates in Households.
Distribution Channel:
Channel selection separates industrial procurement efficiency from consumer margin capture, with platform economics reshaping traditional broker networks.
- Direct Sales:Flavor houses and cosmetic formulators build decades-long relationships with origin distillers, consolidating volume commitments around verified terpene profiles and batch consistency.
- Online Retail:Digital platforms for sample validation and contract negotiation displace traditional broker networks in North American and European buying offices, most visible in natural and organic retail segments.
- Specialty Stores:Aromatherapy and wellness retailers curate single-origin narratives for consumers prioritizing transparent sourcing over incumbent supplier relationships.
- Supermarkets:Mass-market placement for standardized grades serving household cooking and basic topical applications with price-competitive positioning.
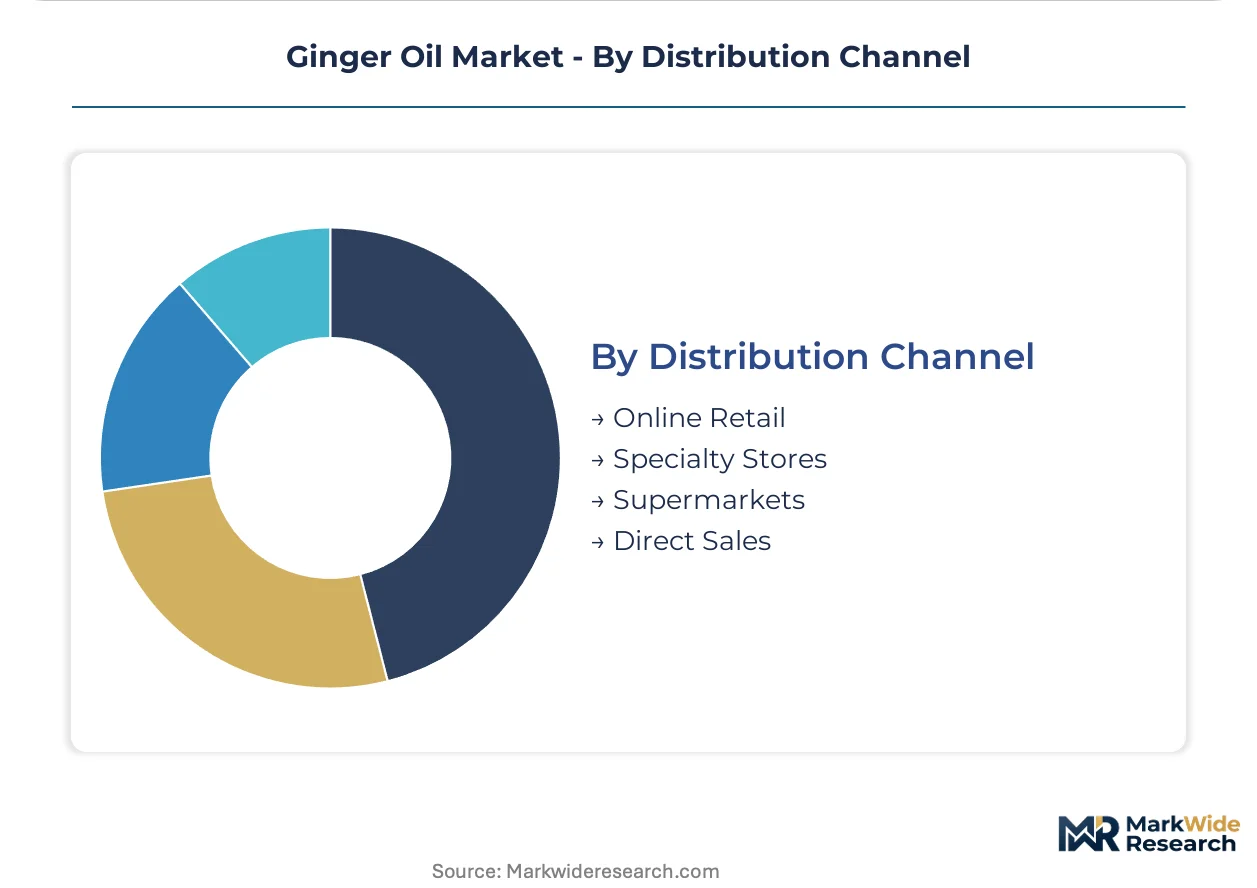
Volume consolidation favors Direct Sales. Margin expansion concentrates in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India dominates ginger oil production through Kerala and Karnataka extraction clusters, while the United States, Germany, China, and Japan absorb premium volumes for flavor, fragrance, and therapeutic applications. Consumption concentrates in import-dependent markets with stringent purity standards.
United States
Flavor houses in New Jersey and California drive bulk procurement of steam-distilled grades for beverage and confectionery formulations. FDA food additive regulations govern import documentation, with terpene profile verification mandatory for batch release. Indianapolis-based distributors maintain decades-long relationships with origin distillers for supply security.
Germany
REACH compliance investments by importers in Hamburg and Frankfurt unlock premium market access for certified organic grades. ECHA documentation requirements now mandate full supply chain disclosure from rhizome cultivation through final distillation. Bavarian cosmetic formulators prioritize cold-pressed variants with verified gingerol content for dermal applications.
India
Domestic extraction capacity expansion in Kerala and Karnataka reduces export dependency on European processing houses. BIS essential oil standards filter supplier eligibility, with ICP-MS testing infrastructure investments accelerating for EU market access. Uttar Pradesh and Tamil Nadu emerging distillers face recruitment bottlenecks for GC-MS interpretation expertise.
China
Supercritical CO2 technology adoption in Sichuan and Yunnan provinces targets pharmaceutical-grade oleoresin output with precise bioactive standardization. GB standards for essential oils impose distinct heavy metal limits that reshape supplier qualification protocols. Pearl River Delta flavor manufacturers consolidate procurement around verified terpene profiles.
Japan
Aromatherapy channel expansion in Tokyo and Osaka metropolitan areas supports direct-to-consumer wellness brand proliferation. METI guidelines for natural product labeling influence import specification requirements for cosmetic and therapeutic applications. Kansai-region cosmetic manufacturers prioritize single-origin sourcing narratives for clean-label positioning.
Ginger Oil Market Vendor Landscape
The competitive structure tilts toward integrated origin processors with captive raw material control. Distillers with farm-to-distillate traceability systems capture premium positioning, while commodity traders face margin compression from regulatory compliance costs. Three archetypes dominate: Kerala-based integrated extractors, North American distribution specialists, and direct-to-consumer wellness brands. Capacity expansion and certification reciprocity lobbying represent the dominant competitive moves across tiers.
Within the integrated extraction tier, Synthite Industries Pvt. Ltd. and AOS Products Pvt. Ltd. represent Kerala-based specialists with backward control over raw ginger supply chains. The Lebermuth Co. Inc. exemplifies North American distribution dominance through flavor house relationships. doTERRA International LLC anchors the direct-to-consumer archetype with proprietary sourcing standards that command premium positioning in wellness channels.
| Leading Market Players |
|---|
| Synthite Industries Pvt. Ltd. |
| The Lebermuth Co. Inc. |
| Young Living Essential Oils |
| New Directions Aromatics Inc. |
| Edens Garden |
| doTERRA International LLC |
| International Flavors and Fragrances Inc. |
| Ozone Naturals |
| AOS Products Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
Raw ginger rhizome costs from Kerala and Karnataka farms cascade through extraction margins into three distinct buyer tiers, with organic certification premiums widening spreads between commodity distillers and pharmaceutical-grade suppliers serving EU and North American flavor houses.
Pricing Analysis
Certification-grade standardization anchors pricing tiers across the ginger oil market. Pricing stratifies across organic-certified premium, steam-distilled standard, and cold-pressed specialty tiers based on terpene profile verification and REACH documentation completeness. Price compression runs through standard grades as Indian capacity expansion intensifies competition for industrial flavor house contracts. Food and beverage manufacturers exhibit highest price sensitivity, while pharmaceutical formulators accept premiums for bioactive-standardized cold-pressed variants with verified gingerol content.
Supply Chain Analysis
EU REACH registration requirements and BIS certification standards gate supplier eligibility for premium market access. Extraction capacity concentrates in India, China, and Indonesia, with Kerala and Karnataka clusters feeding pharmaceutical and flavor house demand. Supply chains draw from monsoon-dependent ginger harvests, exposing margins to climate-driven yield volatility. Single-source vulnerability sits with smallholder-dependent raw material bases lacking forward-contracting depth. Distribution runs through direct sales relationships with flavor houses, supplemented by digital platforms disintermediating traditional broker networks in North American and European buying offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH compliance investments and chromatographic testing infrastructure requirements force sub-scale distillers into acquisition targets or contract manufacturing relationships.
For Market Incumbents: Anchor market position through backward integration into captive ginger cultivation in Kerala and Karnataka to secure raw material supply against monsoon volatility. Invest in in-house GC-MS verification capabilities to meet ECHA documentation requirements and lock in flavor house procurement relationships. Defend against supercritical CO2 oleoresin substitution by co-locating distillation and cold-pressing facilities for dual-product output. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a technology-first wedge into pharmaceutical-grade gingerol standardization previously controlled by European processing houses. Target white-space opportunity in direct-to-consumer aromatherapy channels where subscription models bypass incumbent flavor house intermediaries. Prioritize organic certification reciprocity lobbying between India's NPOP and EU competent authorities to eliminate redundant audit costs for cross-border suppliers. For Investors and Strategic Acquirers: BIS-REACH alignment announcement is the leading indicator that certification cost structures will shift favoring integrated Indian extractors over commodity traders. Long-term viability favors vertically integrated origin processors with farm-to-distillate traceability systems and ICP-MS testing infrastructure already deployed. Monitor organic certification reciprocity negotiations as the signal for competitive sourcing dynamics reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Kerala and Karnataka land leases secure raw ginger supply against monsoon-driven harvest volatility. |
| ICP-MS Testing Infrastructure Deployment | Heavy metal verification capabilities unlock EU REACH-compliant premium market access for Indian distillers. |
| Direct-to-Consumer Channel Launch | Subscription aromatherapy models capture retail margin pools previously extracted by flavor house intermediaries. |
| Supercritical CO2 Capacity Addition | Pharmaceutical-grade gingerol standardization displaces traditional distillation for high-potency therapeutic applications. |
| Organic Certification Reciprocity Lobbying | Mutual recognition between India's NPOP and EU standards eliminates redundant audit costs for cross-border suppliers. |
Methodological Framework
Multi-period observation of extraction capacity expansion, certification investment patterns, and import documentation requirements anchored the trend analysis, supplemented by interviews with distillery operations managers, flavor house procurement directors, cosmetic formulator R&D leads, and organic certification auditors. Secondary validation drew from BIS essential oil standards filings, ECHA REACH registration databases, Indian customs export records, and EU organic import statistics. Bottom-up capacity modeling triangulated against top-down consumption estimates across food, cosmetic, pharmaceutical, and aromatherapy end-uses.
Input-output matrices mapped ginger rhizome harvest volumes through extraction yields to refined oil output across steam-distilled, cold-pressed, and organic-certified grade tiers over the projection horizon. Segmentation dimensions included extraction method, certification status, application category, and end-user contract structure. CAGRs were derived from slope-intercept modeling of historical price-volume relationships and forward capacity announcements. Forecast inputs incorporated monsoon pattern variability, EU regulatory threshold evolution, and substitution elasticity between ginger oil and oleoresin formulations.
Several conditions sit outside the modeled scope, including geopolitical trade restriction implementation, breakthrough synthetic ginger flavor commercialization, and pandemic-scale supply chain disruption. Forecasts reflect documented assumptions regarding certification reciprocity timelines and extraction technology adoption curves. A model refresh is warranted upon material change in EU REACH heavy metal threshold revision or India-EU organic mutual recognition agreement finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Global Spices and Stimulants Market
Spices and Seasonings
Spices Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
North American Seasonings and Spices Market