
 Glass Spice Jars Market | 2026-2036
Glass Spice Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Spice Jars Market Foresight
Multi-source glass procurement is realigning how mid-sized spice brands manage container supply chains. O-I Glass leverages its North American furnace network to sustain bulk pricing leverage for high-volume seasoning clients. Vetropack anchors Central European supply through its integrated melting and forming operations.
Glass spice jars are hermetically sealable cylindrical or square containers, typically formed from soda-lime or borosilicate glass with wall thicknesses of 2–4 mm, designed to preserve aromatic volatile compounds against moisture and oxidation. Shaker jars and grinder jars dominate unit volume due to their direct-to-consumer utility in home kitchens and commercial cooking environments. Amber glass commands premium positioning in specialty retail channels where UV protection justifies higher price points.
FDA food-contact regulations and EU REACH migration standards shape material certification requirements for glass-to-spice interfaces. BIS certification in India and GB standards in China add compliance layers for exporters targeting those markets. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and state-level packaging mandates in California and New York.
Market Dynamics
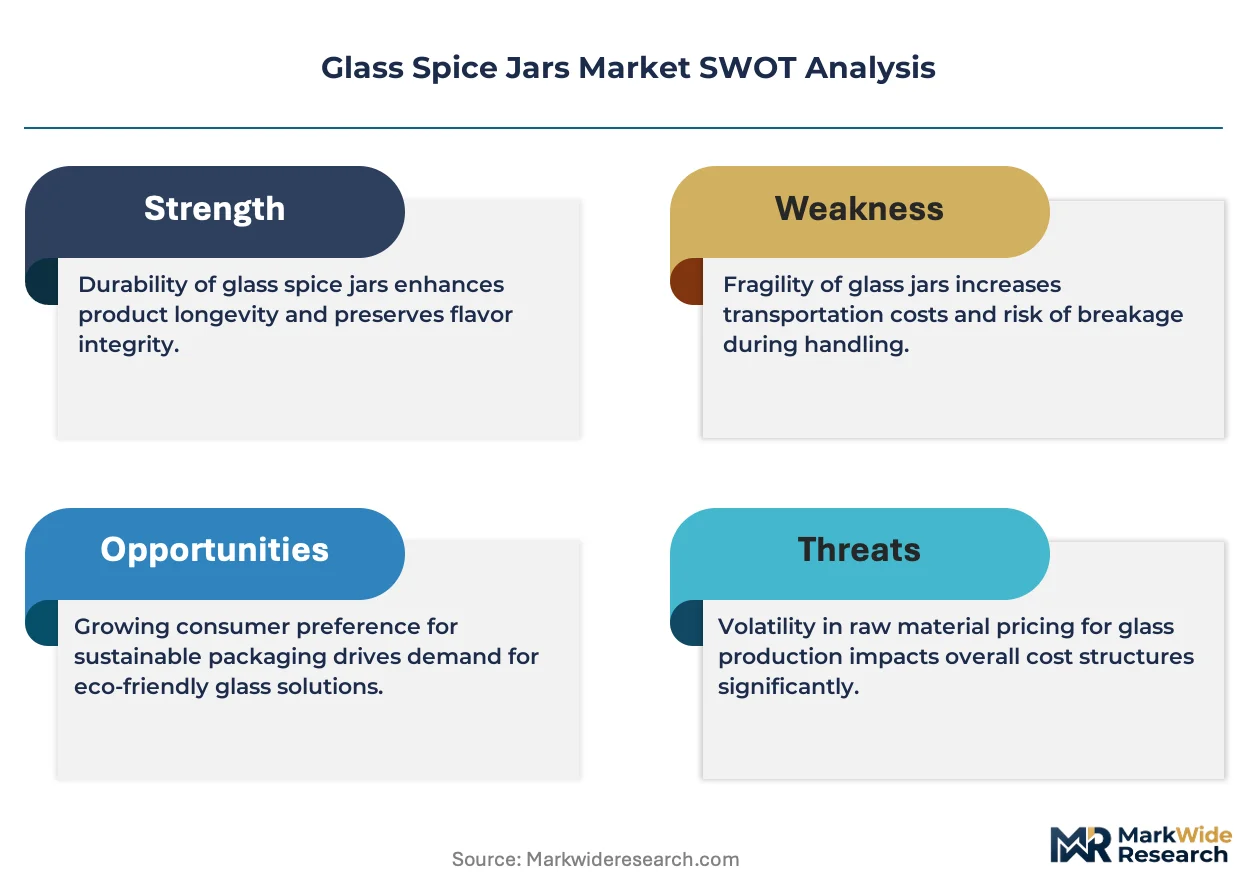
REACH migration limits are tightening across the European Union, forcing glass-to-food contact suppliers to recertify material compositions and accelerating consolidation among mid-sized container manufacturers.
Growth Catalysts
- E-commerce channel expansion:Specialty retail platforms in North America and Western Europe are capturing premium spice jar volumes through direct-to-consumer fulfillment models.
- Borosilicate glass adoption:Thermal shock resistance specifications from commercial kitchen equipment manufacturers are displacing soda-lime formats in high-heat applications.
- Extended Producer Responsibility frameworks:EU packaging mandates are creating compliance-driven replacement cycles for non-recyclable container stock.
Market Restraints
- Energy cost volatility:Natural gas price spikes at Central European melting furnaces are compressing margin structures for borosilicate and amber glass production.
- Supply concentration risk:Container glass capacity clusters along the Rhine corridor create single-point vulnerability for seasoning brands dependent on just-in-time delivery.
- Plastic substitution threat:Polypropylene shaker formats with oxygen scavenger liners are capturing economy-tier volume in private-label spice segments.
Strategic Opportunities
- India export corridor:BIS certification requirements for food-contact glass are creating first-mover advantage for pre-certified European suppliers entering organized retail channels.
- Smart packaging convergence:Near-field communication tags embedded in jar lids are unifying inventory tracking with consumer engagement for premium spice brands.
- California packaging mandates:State-level recycled content minimums are generating demand for post-consumer cullet integration in amber glass production.
Industry Challenges
- Migration testing backlog:ECHA notification queues for novel glass surface treatments are extending product launch timelines by 8-14 months.
- Legacy equipment retrofit costs:IS machine upgrades for lightweighting programs require capital deployment that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Spice Jars Market |
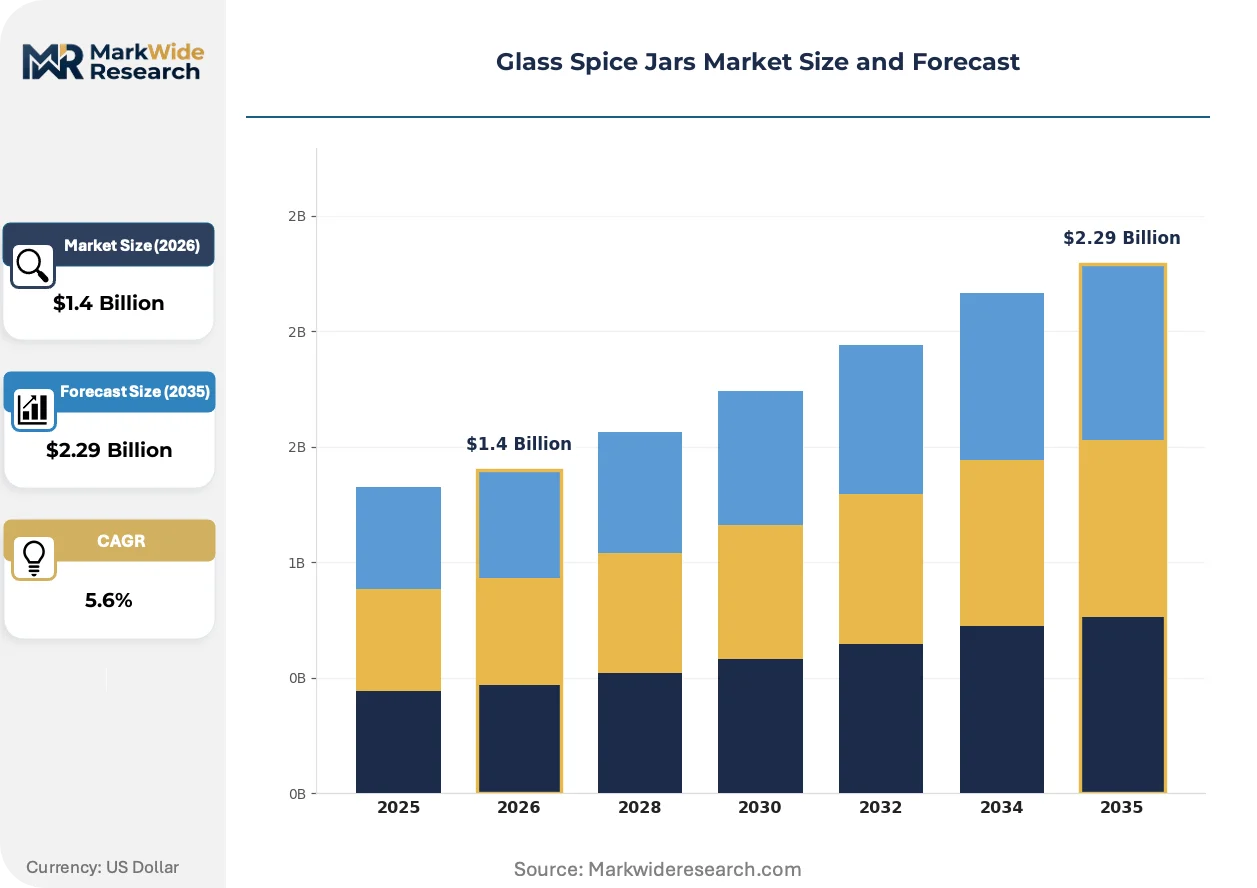
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaker Jars, Grinder Jars, Wide Mouth Jars, Flip-Top Jars, Refillable Bottles Material: Borosilicate Glass, Soda-Lime Glass, Tempered Glass, Frosted Glass, Amber Glass Application: Home Kitchens, Commercial Cooking, Culinary Studios, Food Packaging, Specialty Stores Distribution Channel: Supermarkets, E-Commerce Platforms, Specialty Retailers, Wholesale Distributors, Direct Sales |
| Companies Covered | O-I Glass, Roetell Glass, Vetropack, Bormioli Rocco, Anchor Glass Container Corporation, Greif, Gerresheimer, PGP Glass, Alcan Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Spice Jars Market Shifts & Advancements
Container functionality is converging with digital traceability and circular material flows, reshaping how glass spice jars are specified, procured, and recovered across food manufacturing and retail channels.
Borosilicate-to-amber hybrid formulations are unifying thermal performance with UV protection in single-wall constructions. Premium spice brands in Germany and France are adopting these formats for shelf-stable seasoning lines. This unification is compressing the traditional separation between commercial kitchen and retail display specifications.
REACH Annex XVII amendments on heavy metal content are forcing reformulation of decorative ceramic inks used in jar labeling. Glass decorators serving the European market are switching to organic pigment systems. Specialty retail channels are absorbing higher unit costs to maintain EU market access.
Buyers are consolidating container specifications across multiple seasoning SKUs to reduce supplier management overhead. Mid-sized spice brands are shifting from fragmented jar-format portfolios to standardized cylindrical platforms. This consolidation is most visible in North American private-label manufacturing, where co-packing agreements favor interchangeable lid systems.
Glass Spice Jars Market Segmentation
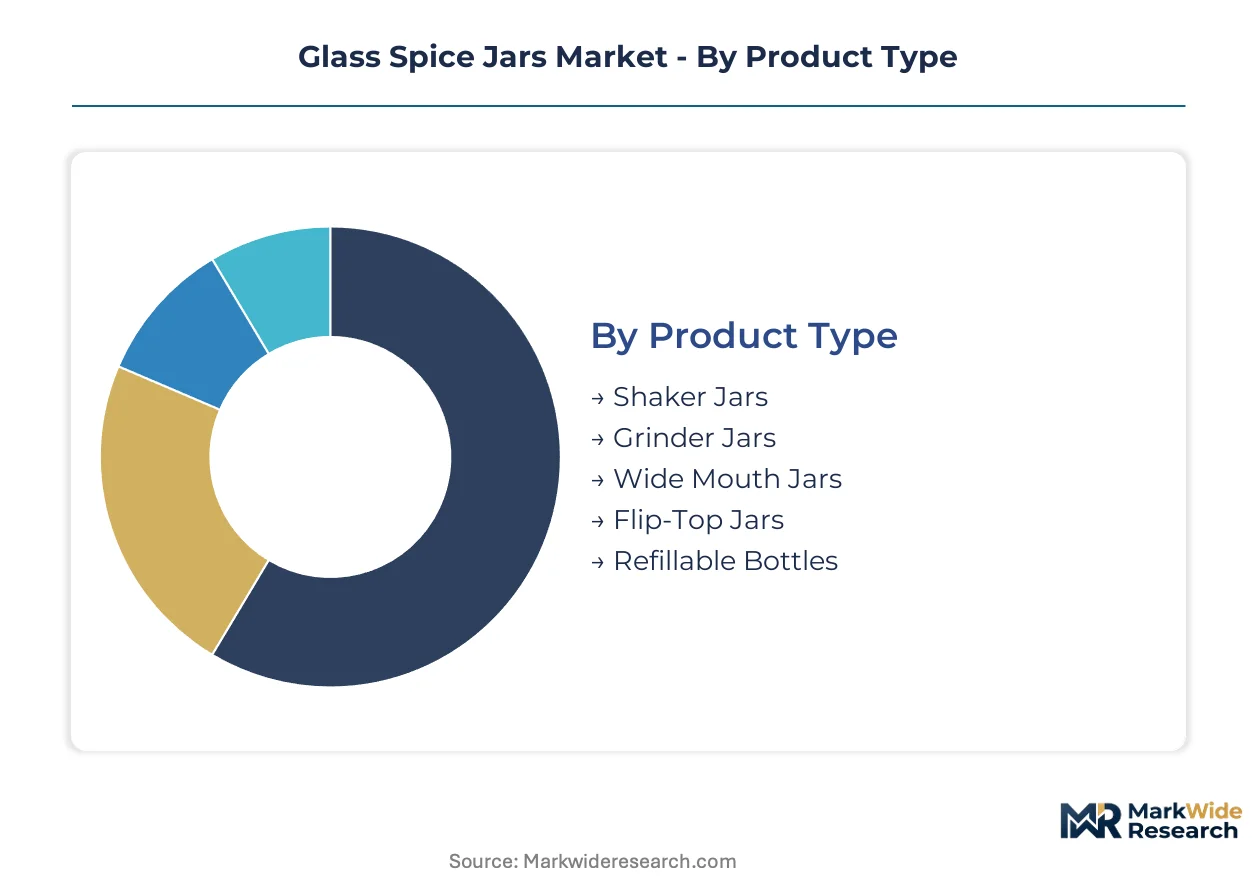
Glass spice jar specifications diverge sharply across end-use environments, with thermal performance, seal integrity, and UV protection driving distinct procurement criteria. Manufacturers align furnace output and forming tooling to these segment-specific requirements, creating specialization barriers that shape competitive positioning.
Product Type:
Upgrade cycles in home kitchen equipment are accelerating replacement demand for jars with integrated dispensing mechanisms.
- Shaker Jars:Cylindrical containers with perforated metal or polymer lids enabling controlled particle dispersion. Demand concentrates in North American private-label spice manufacturing where co-packing agreements standardize 4-ounce and 8-ounce formats. E-commerce fulfillment models favor these units for their shipping durability and consumer familiarity.
- Grinder Jars:Thick-walled borosilicate constructions with ceramic or steel grinding mechanisms integrated into the cap assembly. Premium positioning in German and French specialty retail channels justifies higher unit economics through whole-spice freshness preservation. REACH-compliant surface treatments on grinding components extend certification timelines.
- Wide Mouth Jars:Large-diameter openings facilitating bulk spice access and cleaning; favored by culinary studios and commercial kitchens.
- Flip-Top Jars:Hinged lid designs enabling single-handed operation; penetrating quick-service restaurant prep lines.
- Refillable Bottles:Narrow-neck formats supporting bulk-to-consumer transfer; aligning with California and New York state packaging mandates on reusable container adoption.
Volume placements concentrate in Shaker Jars; the faster expansion belongs to Grinder Jars.
Material:
Cost stratification across glass chemistries separates premium thermal performance from economy-tier transparency.
- Borosilicate Glass:Low thermal expansion coefficient (3.3 × 10⁻⁶/K) enabling direct stovetop and oven exposure. Commercial cooking equipment manufacturers in Germany specify this material for spice warming stations. Energy-intensive melting requirements at Central European furnaces compress margin structures during natural gas price volatility.
- Amber Glass:Iron-sulfur colorant systems absorbing UV wavelengths below 450 nm. Specialty retail channels in France absorb higher unit costs to maintain shelf-stable seasoning line positioning. REACH Annex XVII heavy metal limits are forcing reformulation of traditional colorant packages.
- Soda-Lime Glass:Standard container chemistry dominating economy-tier volume through lower melting energy requirements.
- Tempered Glass:Thermal strengthening through controlled surface compression; penetrating food packaging segments requiring drop resistance.
- Frosted Glass:Acid-etched or sandblasted surface treatments for premium aesthetic differentiation in direct-to-consumer channels.
Unit economics favor Soda-Lime Glass at scale; Amber Glass commands the steepest price premium trajectory.
Application:
Customer type determines whether procurement prioritizes batch consistency, thermal resilience, or retail shelf presence.
- Home Kitchens:Direct-to-consumer specifications emphasizing ergonomic handling and dishwasher compatibility. E-commerce platforms in North America capture premium volumes through subscription spice services. California packaging mandates on recycled content minimums are reshaping material specifications.
- Commercial Cooking:High-throughput environments requiring thermal shock resistance and standardized lid interfaces for prep line efficiency. Equipment manufacturers in Germany specify borosilicate formats for integration with warming stations.
- Culinary Studios:Educational and content-production settings favoring wide-mouth accessibility and visual clarity for instruction.
- Food Packaging:Co-packing operations demanding interchangeable lid systems across multiple seasoning SKUs to reduce supplier management overhead.
- Specialty Stores:Curated retail environments where amber glass UV protection and decorative ceramic labeling justify premium positioning.
Procurement scale concentrates in Food Packaging; Specialty Stores are expanding most quickly.
Distribution Channel:
Channel selection dictates packaging specifications, order fragmentation, and compliance documentation requirements.
- E-Commerce Platforms:Direct-to-consumer fulfillment models requiring damage-resistant packaging and standardized case counts. Specialty retail platforms in North America and Western Europe are capturing premium spice jar volumes through subscription and replenishment algorithms.
- Specialty Retailers:Curated assortment strategies favoring amber glass and grinder formats with distinctive labeling. EU REACH migration documentation requirements extend supplier onboarding timelines.
- Supermarkets:High-volume, low-fragmentation procurement of shaker and wide-mouth formats for private-label spice lines.
- Wholesale Distributors:Intermediate stocking points serving foodservice and small-format retail; concentrating inventory risk.
- Direct Sales:Manufacturer-to-end-user relationships enabling custom specification and extended payment terms for large culinary studios.
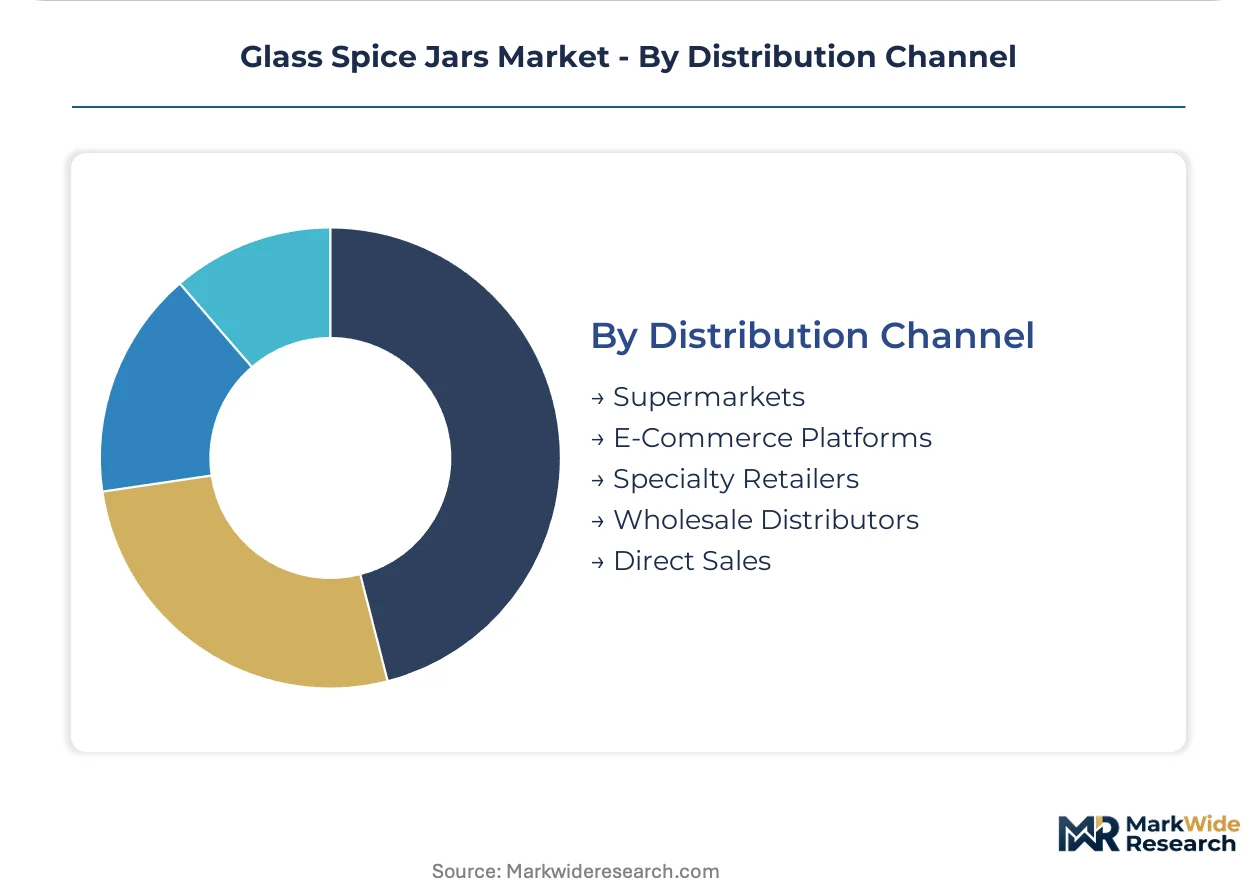
Order volume concentrates in Supermarkets; E-Commerce Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silica sand deposits in the upper Midwest anchor North American container glass production. Central European natural gas pricing volatility reshapes furnace economics across the Rhine corridor. Indian soda ash availability from Gujarat drives cost competitiveness for export-oriented forming operations.
United States
E-commerce subscription spice services drive demand for standardized shaker formats. California's recycled content mandates under SB 54 reshape amber glass procurement specifications. Toledo, Ohio hosts concentrated container glass furnace capacity serving seasoning brand co-packers.
Germany
Commercial kitchen equipment manufacturers specify borosilicate formats for spice warming stations. REACH Annex XVII amendments force reformulation of decorative ceramic inks. The Rhineland-Palatinate furnace cluster supplies premium grinder jar volumes to French specialty retailers.
France
Specialty retail channels absorb higher unit costs for UV-protected amber glass seasoning lines. ANSM oversight of food-contact materials adds compliance documentation requirements. The Paris Basin distribution hub concentrates inventory for European culinary studio procurement.
India
BIS certification requirements for food-contact glass create first-mover advantage for pre-certified European suppliers. FSSAI labeling mandates extend product registration timelines. Gujarat's soda ash production corridor feeds cost-competitive forming operations in Maharashtra.
China
GB standards for glass-to-food contact surfaces shape export certification requirements. Dual carbon goals accelerate furnace efficiency upgrades in Shandong Province. The Yangtze River Delta hosts concentrated decorating and labeling capacity for premium spice brand packaging.
Glass Spice Jars Market Competitive Landscape
Capacity expansion dominates the current landscape as furnace operators respond to tightening EU migration standards. The vendor base separates into three tiers: integrated multinational furnaces, regional forming specialists, and niche decorators serving premium channels. Strategic archetypes include borosilicate thermal-performance specialists, amber-UV-protection premium-positioned players, and lightweighting-focused standard-container converters. Geographic expansion and portfolio diversification represent the dominant competitive moves as players seek to offset Rhine corridor concentration risk.
Among North American integrated producers, O-I Glass and Anchor Glass Container Corporation occupy positions defined by furnace network scale and bulk pricing leverage for high-volume seasoning clients. Vetropack exemplifies the Central European archetype with integrated melting and forming operations anchoring supply security for mid-sized spice brands. These three entities represent distinct strategic postures: continental-scale furnace optimization, regional supply-chain anchoring, and compliance-driven premium-format specialization.
| Leading Market Players |
|---|
| O-I Glass |
| Roetell Glass |
| Vetropack |
| Bormioli Rocco |
| Anchor Glass Container Corporation |
| Greif |
| Gerresheimer |
| PGP Glass |
| Alcan Packaging |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap glass converters in Central Europe exercise tighter pricing discipline than private-equity-rolled-up North American peers, passing through natural gas cost volatility while reinvesting furnace efficiency gains into REACH-compliant surface treatment capabilities. This ownership pattern concentrates supply bargaining power with Rhineland-Palatinate melting operations and compresses margin recovery timelines for seasoning brands locked into annual contract renegotiations.
Pricing Analysis
Warranty and certification bundling separates grinder jar quotations from unbundled shaker formats, with REACH Annex XVII documentation and migration testing reports commanding 15-25% price premiums in specialty retail channels. Three-tier pricing structure across premium borosilicate, standard amber, and economy soda-lime levels reflects thermal performance certification and UV protection grades. Pricing pressure stems from polypropylene substitution in private-label segments, with North American co-packers absorbing cost compression through volume consolidation. Food packaging buyers exhibit highest price sensitivity; German commercial kitchen equipment manufacturers show lowest.
Supply Chain Analysis
Regional distribution centers along the Rhine corridor and Toledo, Ohio hub-and-spoke patterns govern downstream fulfillment, with specialty retail channels demanding fragmented case counts that strain inventory turns. Supply concentrates in Germany, France, and the United States, with Gujarat soda ash and upper Midwest silica sand anchoring raw material flows. The chain rests on natural gas pricing at Central European furnaces, ceramic grinding mechanism sourcing from China, and oxygen scavenger liner polymers. Single-point vulnerability clusters around Rhineland-Palatinate melting capacity. Distribution runs through wholesale distributors serving foodservice intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container glass specialists are racing to deepen backward integration into cullet recovery and captive silica sand processing, with furnace operators acquiring regional recycling infrastructure to secure post-consumer feedstock for California-mandated amber glass production.
For Market Incumbents: Hedge against polypropylene substitution by accelerating borosilicate-to-amber hybrid formulation patents and securing exclusive co-packing agreements with North American subscription spice services. Anchor furnace capacity additions in Toledo or Gujarat rather than Rhine corridor expansions exposed to energy cost volatility. Prioritize ECHA pre-certification of novel surface treatments to compress grinder jar launch timelines. For New Entrants and Emerging Players: Enter via BIS-certified export corridors into Indian organized retail, where pre-certified European suppliers capture first-mover premiums ahead of domestic forming capacity expansion. Target culinary studio direct sales channels in the Paris Basin, where fragmented procurement favors custom specification capabilities over scale economics. Lead with smart packaging convergence offerings embedding near-field communication inventory tracking. For Investors and Strategic Acquirers: Distressed-cycle entries favor amber-UV-specialist decorators in France and Germany facing REACH Annex XVII ceramic ink reformulation costs, with consolidation multiples compressing ahead of organic pigment system transition completion. Long-term viability hinges on post-consumer cullet integration capabilities and extended producer responsibility framework compliance infrastructure. Watch California SB 54 recycled content enforcement as inflection signal for premium format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Recovery | Secures post-consumer feedstock for California recycled content mandates. |
| REACH Pre-Certification Investment | Compresses ECHA notification queues and accelerates grinder jar launches. |
| Smart Packaging Convergence | Unifies inventory tracking with consumer engagement for premium spice brands. |
| Hybrid Formulation Patenting | Protects borosilicate-amber thermal-UV unification from polypropylene displacement. |
| Geographic Capacity Diversification | Offsets Rhine corridor concentration risk through Toledo or Gujarat furnace expansion. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among furnace operations managers, seasoning brand procurement directors, specialty retail category buyers, and ECHA regulatory affairs consultants. ECHA substance notification databases, FDA food-contact substance inventories, BIS certification registries, and European container glass association production statistics provided validation benchmarks. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Granularity-level modeling distinguished borosilicate, amber, and soda-lime material chemistries; shaker, grinder, wide-mouth, flip-top, and refillable product formats; and home kitchen, commercial cooking, culinary studio, food packaging, and specialty store applications across the projection horizon. CAGRs derived from elasticity-adjusted volume projections and price trajectory assumptions. Forecast inputs incorporated natural gas pricing scenarios at Central European furnaces and California recycled content mandate implementation pacing.
Revisions become necessary when ECHA migration limit amendments, California packaging mandate enforcement delays, or Rhine corridor energy supply disruptions materialize beyond modeled scenarios. Forecasts reflect documented assumptions regarding furnace capacity utilization, ceramic grinding mechanism import flows, and polypropylene substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Europe Seasoning Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Africa Seasoning and Spices Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Turmeric Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Spices and Seasonings Market
Spices and Seasonings
Seasonings Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Cajun Spice Market