
 Mint Oils Market | 2026-2036
Mint Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Mint Oils Market Intelligence
Natural personal care formulators is reorganizing procurement priorities around traceable, single-origin mint oils with verifiable chemotype profiles. Givaudan leverages its integrated botanical supply network to secure consistent mentha arvensis volumes from contracted Indian farms. Symrise AG sustains competitive positioning through advanced fractional distillation capabilities that yield high-purity menthol crystals and terpene isolates. Robertet S.A. anchors its premium segment presence with heritage extraction methods tied to specific Provençal and Mediterranean terroirs.
Mint oils are hydrodistilled or steam-distilled volatile concentrates derived from Mentha species, typically containing 30-50% menthol in peppermint variants and 50-70% carvone in spearmint types, with terpene profiles dictating their cooling, antimicrobial, and flavor-masking functionalities across oral care, confectionery, and topical therapeutics. Peppermint oil leads absolute volume due to its dominance in pharmaceutical and oral hygiene applications, while spearmint oil captures faster growth in clean-label confectionery and beverage formulations where milder flavor profiles align with reduced-sugar product architectures. The aromatherapy end-use channel remains fragmented with margin pools concentrated in certified organic and therapeutic-grade certifications that command wholesale premiums over commodity grades.
The European Pharmacopoeia and ISO 4720 standards govern essential oil identity and purity testing, with REACH compliance adding supply chain documentation burdens for EU-bound imports. India's BIS certification and FSSAI labeling requirements shape domestic market access and export-readiness for Indian distillation operations. FDA oversight of flavor ingredient GRAS status and EPA pesticide residue limits on raw botanicals create dual compliance thresholds for US-facing suppliers. Stakeholders must monitor evolving pharmacopeial monographs and pesticide maximum residue limits as these specifications increasingly determine contract eligibility with multinational flavor houses and pharmaceutical buyers.
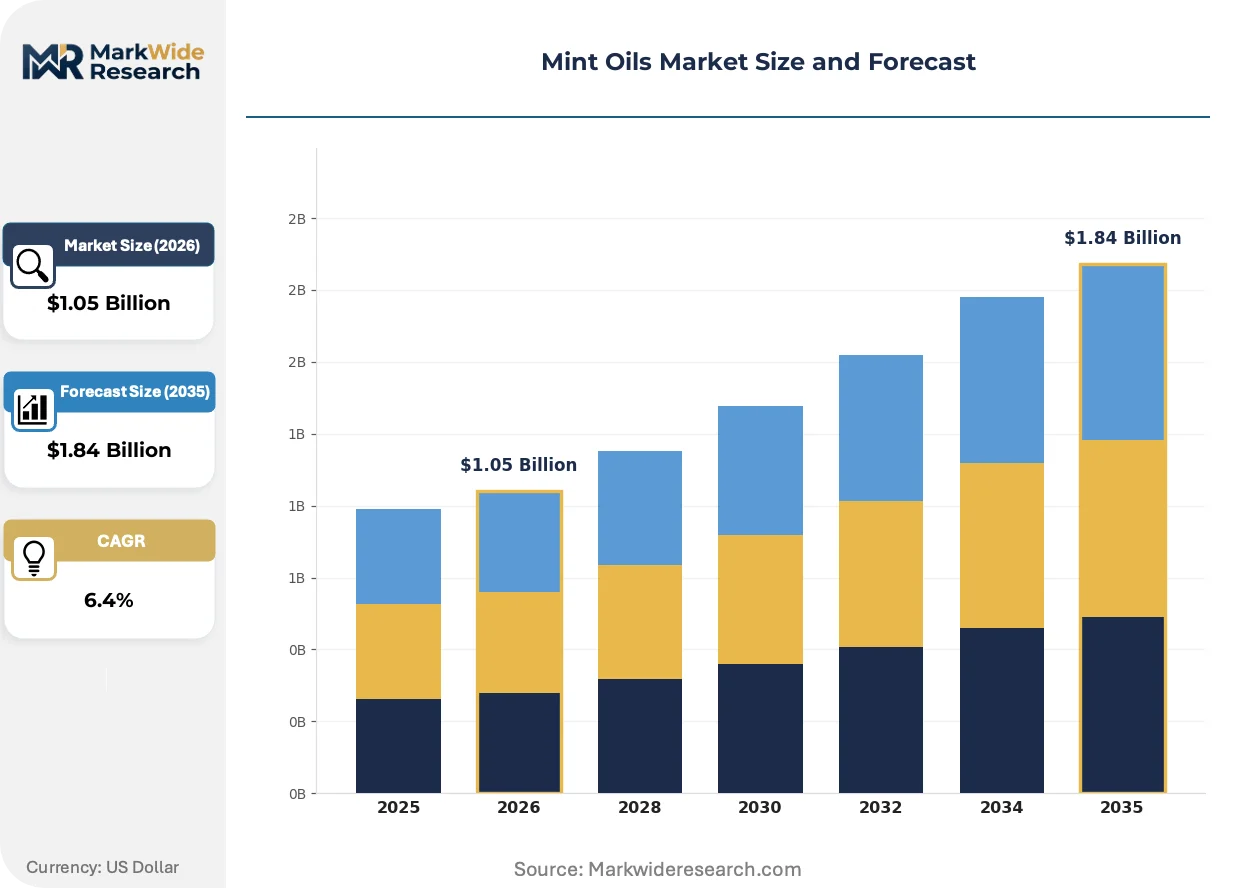
Market Dynamics
Pharmaceutical formulators are driving structural demand for enteric-compatible peppermint oil grades, while the European Pharmacopoeia's tightened monographs on essential oil purity are forcing upstream distillation investments across Indian and Mediterranean supply bases.
Growth Catalysts
- REACH documentation mandates:EU-bound suppliers are upgrading chromatographic testing infrastructure to meet ECHA traceability requirements, creating competitive moats for compliant Indian distillers.
- Enteric drug delivery expansion:Pharmaceutical manufacturers are specifying high-menthofuran peppermint chemotypes for gastric-resistant coatings, pulling premium-grade volumes from traditional flavor applications.
- Uttar Pradesh contract farming density:Vertically organized mentha arvensis cultivation clusters are securing year-round biomass flows for continuous distillation operations serving export markets.
Market Restraints
- Monsoon-dependent biomass pricing:Indian mentha leaf yields fluctuate with irregular rainfall patterns, transmitting volatility through spot menthol crystal quotations.
- FSSAI-BIS dual certification burden:Domestic Indian distillers face overlapping inspection timelines that delay export-readiness for EU and US pharmaceutical buyers.
- Synthetic menthol substitution:BASF and Takasago's fermentation-derived menthol is capturing share in commodity oral care applications where natural provenance carries no price premium.
Strategic Opportunities
- Therapeutic-grade aromatherapy channel:Certified organic peppermint oil with verifiable chemotype documentation commands wholesale premiums in German and French pharmacy retail.
- Clean-label confectionery pivot:Spearmint oil with documented low-pulegone profiles is displacing artificial flavor systems in reduced-sugar gum and mint formulations.
- Carbon-negative distillation:Biogas-powered steam generation at Indian cooperative facilities aligns with EU Green Deal import preferences and CSRD Scope 3 reporting requirements.
Industry Challenges
- Gas chromatography-mass spectrometry technician scarcity:Indian distillation clusters lack sufficient analytical chemists to execute pharmacopeial-compliant batch testing for pharmaceutical contracts.
- ISO 4720 identity verification timelines:Third-party laboratory backlogs extend certification cycles, delaying shipments to flavor houses with just-in-time formulation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mint Oils Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spearmint Oil, Peppermint Oil, Wild Mint Oil, Other Mint Oils End Use: Food & Beverage, Cosmetics, Pharmaceuticals, Aromatherapy Distribution Channel: Online, Retail Stores, Wholesale, Direct Sale Form: Liquid, Solid, Extract, Concentrate |
| Companies Covered | H. Reynaud & Fils, Givaudan, Symrise AG, International Flavors & Fragrances Inc., Young Living Essential Oils, doTERRA International, BASF SE, India Essential Oils, Robertet S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mint Oils Market Strategic Shifts & Innovations
Fractional distillation and analytical specification technologies are compressing batch-to-batch variation, enabling pharmaceutical-grade supply agreements that were previously impossible for botanical extractors.
Molecular distillation systems with computer-controlled temperature profiling are miniaturizing at Indian cooperative facilities, allowing small-batch processors to achieve menthol crystal purities previously requiring industrial-scale equipment. Regional pharmaceutical buyers in Maharashtra and Gujarat are adopting these systems for captive spearmint terpene isolation. The technology is miniaturizing capital barriers, fragmenting what was once concentrated in integrated flavor houses.
EMA's updated guidelines on herbal medicinal product quality require quantitative nuclear magnetic resonance fingerprinting for essential oil identity confirmation. European contract manufacturers are rejecting shipments lacking this documentation, forcing Indian exporters to invest in qNMR capability. Pharmaceutical excipient applications face the steepest compliance cost escalation.
Formulation houses are consolidating supplier rosters around single-origin traceability, replacing multi-source blending with direct farm-to-flask relationships. Oral care multinationals are auditing Uttar Pradesh contract networks for pesticide residue compliance. This concentration is most visible in German and Swiss buying offices, where procurement teams now specify individual farm GPS coordinates in purchase orders.
Mint Oils Market Segmentation
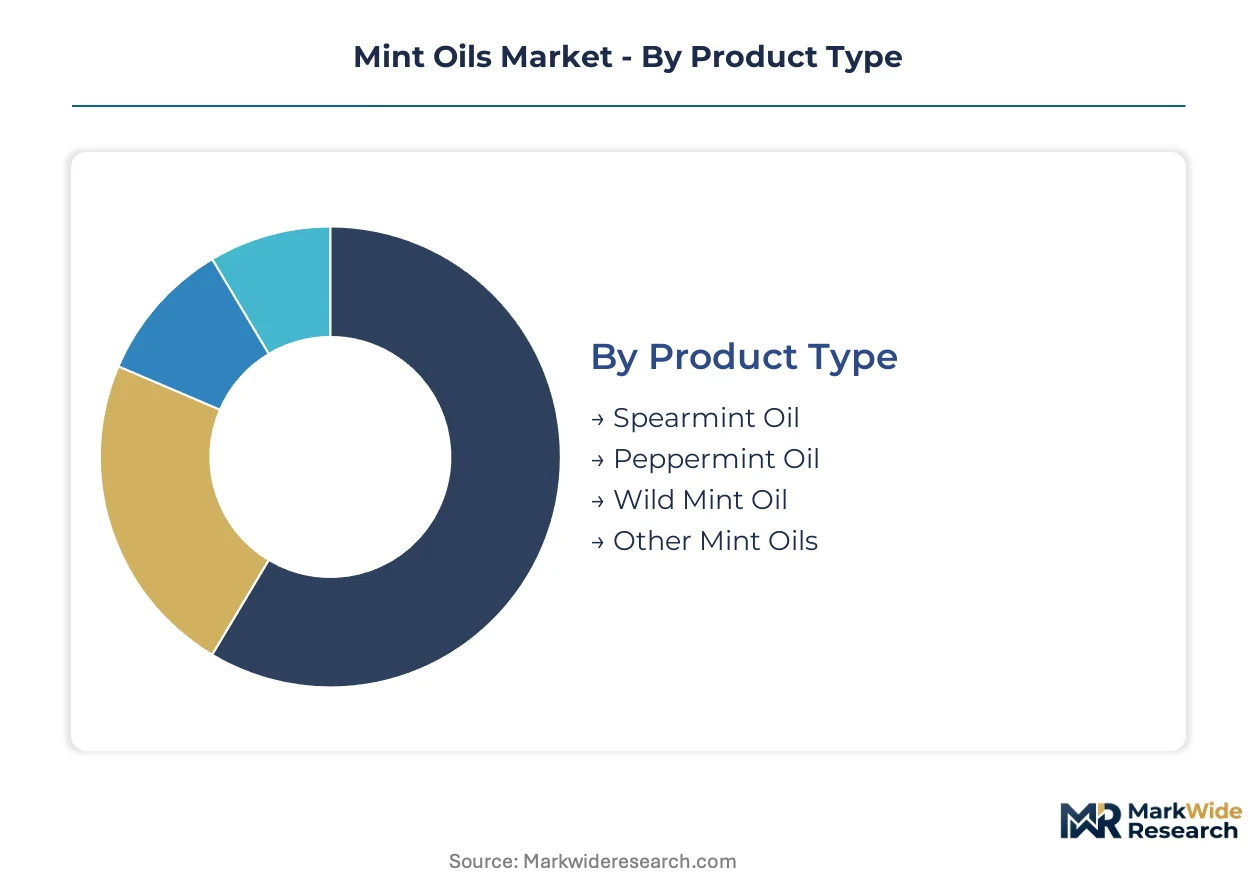
Mint oil segmentation reflects divergent compliance burdens across pharmaceutical, food, and cosmetic regulatory frameworks. Product chemotypes and purity grades determine contract eligibility with multinational buyers, while distribution channel selection shapes margin capture and traceability documentation.
Product Type:
EMA monographs and ISO 4720 identity standards create tiered purity requirements that separate pharmaceutical-grade from flavor-grade specifications.
- Peppermint Oil:Distilled from Mentha piperita with 30-50% menthol content and variable menthofuran levels that determine enteric coating compatibility. Demand concentrates in Maharashtra and Gujarat pharmaceutical corridors where CDSCO-registered manufacturers specify high-purity batches for gastric-resistant drug delivery systems.
- Spearmint Oil:Derived from Mentha spicata with 50-70% carvone dominance and characteristically low pulegone profiles preferred in clean-label confectionery. German and French food formulators are specifying documented terroir origins for reduced-sugar gum applications.
- Wild Mint Oil:Harvested from non-cultivated Mentha arvensis stands with inconsistent chemotype stability limiting pharmaceutical uptake.
- Other Mint Oils:Includes corn mint and bergamot mint variants serving regional flavor traditions and artisanal aromatherapy channels.
Established volume favors Peppermint Oil; emerging adoption favors Spearmint Oil.
End Use:
Application-specific purity thresholds segment the market into pharmaceutical excipient, food-grade, and cosmetic-grade tiers with non-overlapping certification requirements.
- Pharmaceuticals:Enteric-coated drug delivery systems demand menthofuran-controlled peppermint chemotypes with qNMR fingerprinting documentation. Indian contract manufacturers serving EU export markets face EMA herbal medicinal product quality compliance costs that commodity flavor suppliers cannot absorb.
- Food & Beverage:Clean-label confectionery and reduced-sugar beverages drive spearmint oil specification for milder flavor masking. FSSAI labeling requirements and BIS certification shape domestic Indian market access.
- Cosmetics:Natural personal care formulators prioritize single-origin traceability with verifiable pesticide residue compliance for EU Green Deal-aligned procurement.
- Aromatherapy:Certified organic and therapeutic-grade designations command wholesale premiums in German pharmacy retail, though channel fragmentation limits volume concentration.
Pharmaceutical-grade specifications capture the steepest margin premiums; food-grade applications provide volume scale.
Distribution Channel:
Channel selection determines documentation depth and buyer relationship structure across spot market and contract supply models.
- Direct Sale:Farm-to-flask relationships with specified GPS coordinates dominate oral care multinational procurement. Uttar Pradesh contract farming networks supply continuous distillation volumes under audited pesticide compliance protocols.
- Wholesale:Traditional flavor house aggregation blends multi-origin batches, sacrificing traceability for cost efficiency in commodity oral care applications.
- Online:Certified organic and therapeutic-grade aromatherapy oils reach German and French pharmacy retail through specialized e-commerce platforms with batch-specific chromatographic reports.
- Retail Stores:Branded consumer packaged goods distribution for finished mint oil products in domestic Indian markets.
Direct sale channels concentrate pharmaceutical and premium cosmetic volumes; wholesale retains commodity flavor applications.
Form:
Physical state selection aligns with formulation integration requirements and stability considerations across end-use applications.
- Liquid:Standard hydrodistilled and steam-distilled oils for direct incorporation into food, cosmetic, and pharmaceutical formulations. REACH documentation mandates for EU-bound shipments drive chromatographic testing infrastructure investment.
- Solid:Menthol crystals and terpene isolates from advanced fractional distillation serving high-purity pharmaceutical and flavor applications.
- Extract:Solvent-derived concentrates for specific cosmetic and aromatherapy applications with distinct volatile profiles.
- Concentrate:Standardized potency preparations for industrial-scale flavor and fragrance compounding.
Liquid forms dominate absolute volume; solid isolates capture premium pricing in pharmaceutical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian mentha arvensis distillers supply peppermint oil to European pharmaceutical formulators under EMA herbal medicinal product quality protocols, while contract farming networks in Uttar Pradesh and Madhya Pradesh secure biomass flows for continuous distillation operations.
India
Uttar Pradesh contract farming clusters supply mentha arvensis biomass to domestic distillers serving pharmaceutical export markets. CDSCO registration requirements and FSSAI labeling mandates shape compliance costs for manufacturers in Maharashtra and Gujarat pharmaceutical corridors. Vertically organized cultivation networks in Madhya Pradesh are securing year-round raw material flows for EU-bound shipments.
Germany
Pharmaceutical excipient buyers in German manufacturing hubs specify qNMR fingerprinting documentation for enteric-compatible peppermint oil grades. EMA updated guidelines on herbal medicinal product quality mandate quantitative nuclear magnetic resonance identity confirmation for essential oil shipments. Flavor house procurement teams in Hamburg and Frankfurt specify individual farm GPS coordinates in purchase orders for traceable supply.
United States
FDA oversight of GRAS status for flavor ingredients and EPA pesticide residue limits on raw botanicals create dual compliance thresholds for domestic formulators. Oral care multinationals audit supply chains for REACH documentation readiness despite domestic manufacturing. Carbon-negative distillation claims from Indian suppliers align with corporate Scope 3 reporting requirements for sustainability-focused buyers.
France
Robertet S.A. anchors premium segment positioning with heritage extraction methods tied to specific Provençal terroirs for aromatherapy and cosmetic applications. ANSM quality benchmarks for pharmacy-distributed essential oils exceed general food-grade specifications. Certified organic peppermint oil commands wholesale premiums in French pharmacy retail channels with batch-specific chromatographic documentation.
Switzerland
Swissmedic pharmaceutical excipient standards and CSRD Scope 3 reporting requirements drive procurement decisions for flavor and fragrance houses with integrated botanical networks. Givaudan leverages its supply infrastructure to secure consistent mentha arvensis volumes from contracted Indian farms for global formulation operations. Swiss buying offices specify single-origin traceability with verifiable pesticide residue compliance in contract terms.
Mint Oils Market Key Industry Players
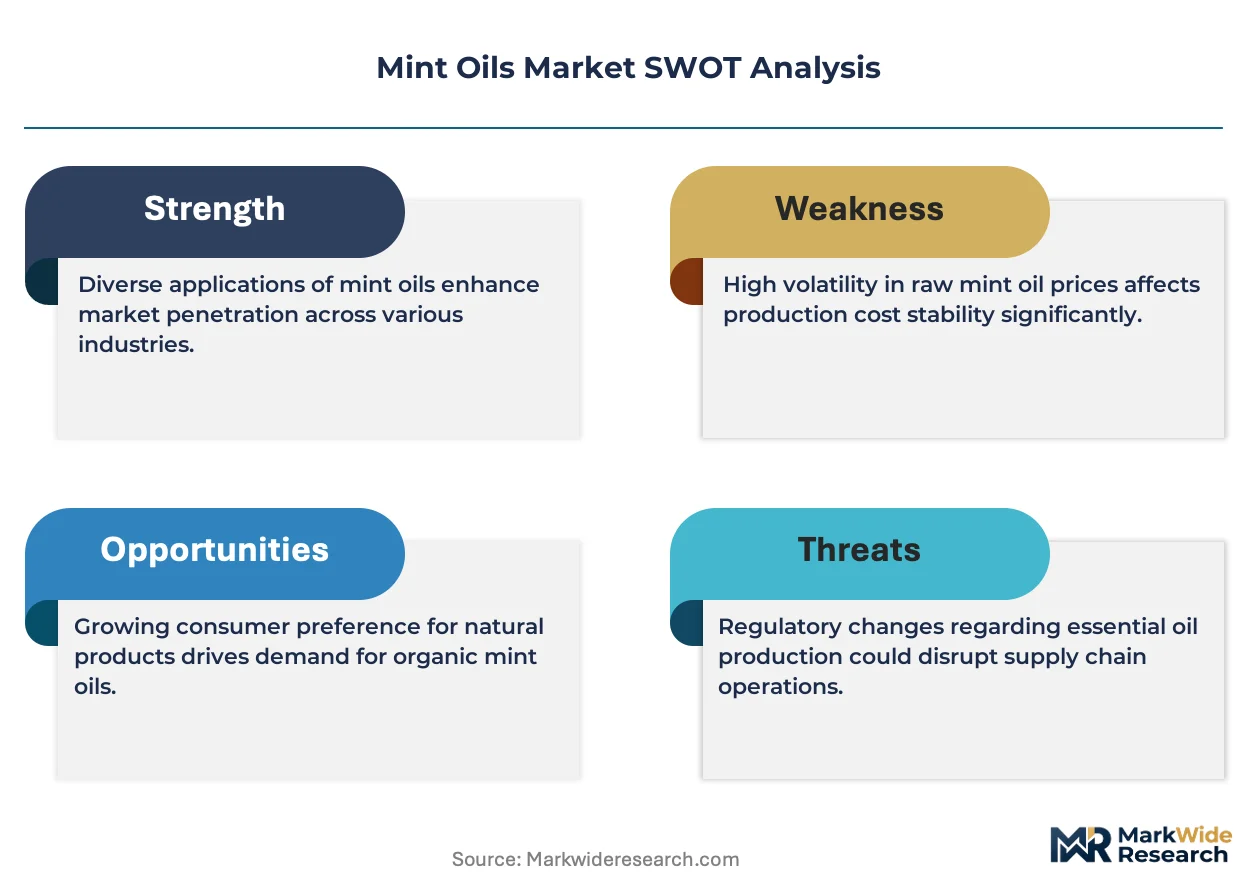
Listed leaders compete with private specialists across integrated supply chain control versus flexible sourcing agility. The vendor base spans Swiss and German fragrance houses with captive botanical networks, Indian cooperative distillers with regional biomass access, and multinational chemical conglomerates with synthetic menthol capabilities. Three archetypes dominate: integrated flavor houses with farm-level contracts, regional distillers with pharmacopeial certification infrastructure, and fermentation technology platforms displacing natural extraction in commodity segments. Competitive moves center on backward integration into contract farming and analytical testing capability acquisition.
Within the integrated flavor house tier, Givaudan and Symrise AG exemplify archetypes combining captive supply networks with fractional distillation expertise. Robertet S.A. occupies a position representing heritage extraction methods tied to specific Mediterranean terroirs. Among India-based operators, India Essential Oils sits within the regional distiller archetype with domestic biomass access and export certification infrastructure.
| Leading Market Players |
|---|
| H. Reynaud & Fils |
| Givaudan |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| Young Living Essential Oils |
| doTERRA International |
| BASF SE |
| India Essential Oils |
| Robertet S.A. |
| Others |
Cost & Logistics Intelligence
Continuous distillation capacity utilization at Uttar Pradesh cooperative facilities creates scale economies that compress unit costs for pharmaceutical-grade peppermint oil while establishing price floors resistant to spot-market volatility. Indian mentha arvensis processors with integrated biomass contracts capture margin stability unavailable to spot-dependent traders serving commodity flavor applications.
Pricing Analysis
Next-generation molecular distillation systems command 40-60% premiums over conventional steam-distillation outputs, while legacy hydrodistilled volumes face compression from synthetic menthol substitution in oral care. Three-tier pricing structure across pharmaceutical-grade, food-grade, and cosmetic-grade certifications separates qNMR-documented batches from commodity blends. Cost compression in standard-grade segments intensifies because BASF and Takasago fermentation platforms capture share where natural provenance carries no premium. Commodity oral care manufacturers exhibit highest price sensitivity; pharmaceutical excipient buyers demonstrate lowest sensitivity due to regulatory switching costs.
Supply Chain Analysis
Container availability constraints on India-Europe trade lanes extend lead times for EU-bound pharmaceutical shipments, forcing buyers to buffer inventory. Geographic supply concentration centers on India, China, and select Mediterranean terroirs for premium heritage extraction. Raw material dependencies draw from mentha leaf biomass, specialized distillation equipment, and chromatographic testing reagents. Single-source vulnerability concentrates in Uttar Pradesh contract farming networks where monsoon irregularity transmits yield volatility. Distribution runs through direct farm-to-flask relationships for pharmaceutical buyers and wholesale flavor house aggregation for commodity applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic and therapeutic-grade aromatherapy channels represent a service-attach opportunity where batch-specific documentation and recurring quality audits expand faster than base oil volumes. Analytical certification services and carbon-negative distillation verification create recurring-revenue layers with superior retention economics.
For Market Incumbents: Shield pharmaceutical-grade positioning by acquiring qNMR capability before EMA documentation mandates harden contract eligibility. Backward integration into Madhya Pradesh biomass networks secures year-round distillation capacity against monsoon-dependent competitors. Synthetic menthol substitution in commodity oral care threatens volume erosion; defend margin position by concentrating on enteric-coating chemotypes with不可替代 pharmacopeial specifications. For New Entrants and Emerging Players: BIS-FSSAI dual certification fast-tracks access to domestic Indian pharmaceutical corridors where CDSCO-registered manufacturers face supplier consolidation. Therapeutic-grade aromatherapy channels in German pharmacy retail offer penetrable white space with documented organic provenance as the primary go-to-market angle. Carbon-negative distillation claims align with EU Green Deal procurement preferences for sustainability-focused buyers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional distillers with captive analytical testing infrastructure and multi-year pharmaceutical supply agreements. Long-term viability across the analysis window favors operators with integrated biomass contracts and pharmacopeial certification capability rather than spot-market traders. Acquisition target archetype: Indian cooperative facilities with underutilized molecular distillation capacity and pending EMA documentation readiness. Signal to watch: qNMR equipment installation rates as leading indicator of contract eligibility with European pharmaceutical buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Uttar Pradesh biomass networks secure year-round raw material flows against monsoon volatility. |
| qNMR Capability Acquisition | EMA herbal medicinal product quality guidelines mandate quantitative nuclear magnetic resonance fingerprinting documentation. |
| Carbon-Negative Distillation Certification | Biogas-powered steam generation aligns with EU Green Deal import preferences and CSRD Scope 3 reporting. |
| Pharmaceutical-Grade Menthol Crystal Expansion | Enteric-coated drug delivery systems specify high-purity isolates with controlled menthofuran profiles. |
| Therapeutic-Grade Aromatherapy Channel Development | Certified organic peppermint oil commands wholesale premiums in German and French pharmacy retail. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and pharmacopeial monograph updates. Primary interviews engaged distillation plant managers, pharmaceutical procurement leads at Maharashtra and Gujarat manufacturing corridors, flavor house technical directors, and agricultural cooperative administrators. Secondary sources incorporated EMA herbal medicinal product quality guidelines, FSSAI labeling requirements, BIS certification standards, and EU REACH documentation protocols. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use application, and distribution channel dimensions.
Segmentation dimensions modeled include chemotype specification, purity grade tier, regulatory compliance cluster, and geographic production hub across the projection horizon. CAGRs derive from trend extrapolation of pharmaceutical excipient demand, clean-label confectionery substitution rates, and aromatherapy channel premiumization. Industry-specific forecast inputs encompass mentha leaf yield variability indices and synthetic-natural menthol price convergence dynamics.
Underlying assumptions cover sustained EMA documentation stringency, stable India-Europe trade lane capacity, and continued pharmaceutical preference for natural-derived excipients, with deviation risk concentrated in monsoon pattern disruption and accelerated synthetic menthol cost reduction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
Carthamus Yellow Market
Spices and Seasonings
Turkey Flavors Market
Spices and Seasonings
Celery Seed Extract Powder Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Middle East and Africa Botanical Extract Market
Spices and Seasonings
Chipotle Salt Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Coleus and Turmeric Market
Spices and Seasonings
Spice Coated Casing Market