
 Boswellia Extract Market | 2026-2036
Boswellia Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Boswellia Extract Market Outlook
Direct-to-practitioner distribution is narrowing as e-commerce platforms and specialty health retailers capture patient-converted consumers. Sabinsa Corporation leverages its vertical integration from raw gum resin to standardized extracts, sustaining supply security for European pharmaceutical clients. PLT Health Solutions differentiates through clinically substantiated branded ingredients, while Arjuna Natural Pvt. Ltd. dominates India-origin Boswellia serrata supply with solvent-free extraction capabilities.
Boswellia extract comprises triterpenic acids—principally boswellic acids AK and KBA—obtained through supercritical CO₂ or ethanol extraction of Boswellia serrata or B. carterii gum resin, standardized typically to 30-65% total boswellic acids for anti-inflammatory and joint health applications. Capsule formulations occupy the largest finished-product margin pool due to consumer convenience and dose precision, while resin extracts command premium positioning in pharmaceutical compounding. Nutraceuticals represents the fastest-growing end-user channel as sports nutrition and healthy-aging brands integrate Boswellia into multi-ingredient joint support stacks.
FDA New Dietary Ingredient notifications and EMA monograph compliance for herbal medicinal products shape extract standardization requirements and batch-release protocols for US and EU market access. India's CDSCO and AYUSH ministry regulations govern domestic Ayurvedic drug manufacturing, while ISO 17025 laboratory accreditation increasingly filters supplier qualification for international buyers. Stakeholders must monitor evolving pharmacopeial monograph revisions and adapt extraction profiles to meet shifting regulatory thresholds for marker compound content.
Market Dynamics
Pharmaceutical-grade standardization requirements under EMA monographs are compressing supplier margins while concentrating procurement among vertically integrated extractors capable of batch-level boswellic acid certification.
Growth Catalysts
- EMA Herbal Medicinal Product Framework:European pharmaceutical formulators now require certified extracts under monograph HMC/0027, creating captive demand for GMP-compliant processors.
- Sports Nutrition Stack Integration:Joint health formulations in nutraceuticals are incorporating standardized Boswellia alongside glucosamine and curcumin, expanding finished-product applications.
- Gujarat-Karnataka Processing Clusters:India's concentrated resin collection and solvent-free extraction infrastructure anchor supply security for export-oriented Ayurvedic drug manufacturers.
Market Restraints
- Wild Harvest Dependency:Boswellia serrata gum resin supply concentrates in arid zones of Gujarat, Rajasthan, and Madhya Pradesh, exposing processors to climate-induced yield volatility.
- Supercritical CO₂ Equipment Costs:Pharmaceutical-grade extraction requires capital-intensive systems exceeding standard ethanol infrastructure, elevating entry barriers for mid-scale entrants.
- Synthetic Anti-Inflammatory Substitution:NSAID cost compression in emerging-market healthcare systems limits Boswellia penetration in price-sensitive therapeutic categories.
Strategic Opportunities
- German Pharmaceutical Compounding:EMA-compliant extract demand from Munich and Heidelberg formulation houses outpaces domestic European supply, creating import substitution potential.
- Direct-to-Consumer E-Commerce:Specialty health platforms are disintermediating practitioner channels, enabling branded ingredient suppliers to capture margin previously lost to distribution tiers.
- ISO 17025 Laboratory Accreditation:Third-party testing protocols are becoming a procurement filter for US and EU buyers, rewarding early certifiers with preferred supplier status.
Industry Challenges
- Phytochemical Standardization Expertise:Batch-to-batch consistency in AK and KBA ratios requires analytical chemists trained in HPLC method validation, a skill set concentrated among legacy Ayurvedic processors.
- FDA New Dietary Ingredient Timelines:NDIN preparation and 75-day pre-market notification cycles delay US market entry for novel extraction profiles or dosage forms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boswellia Extract Market |
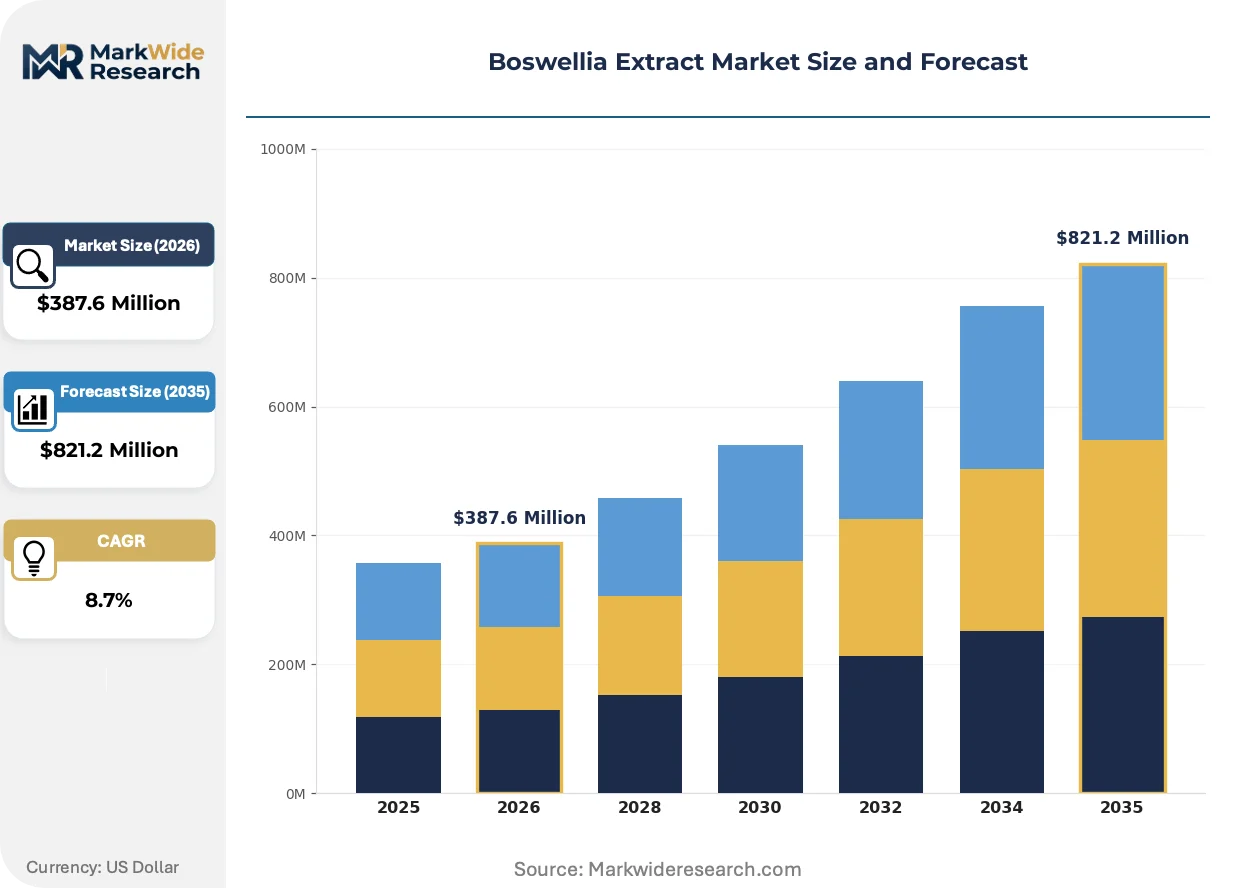
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Resin, Capsules, Powder End User: Pharmaceuticals, Food & Beverages, Cosmetics, Nutraceuticals Application: Anti-Inflammatory, Pain Relief, Joint Health, Digestive Support Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Sabinsa Corporation, PLT Health Solutions, Arjuna Natural Pvt. Ltd., Alchem International Pvt. Ltd., NutraScience Labs, Indena S.p.A., Gurjar Phytochem Pvt. Ltd., Alpspure Lifesciences Private Limited, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boswellia Extract Market Strategic Shifts
Extraction technology and regulatory compliance protocols are converging to reshape competitive positioning, with digitized quality assurance and channel disintermediation emerging as the dominant vectors of change.
Supercritical CO₂ extraction systems with integrated in-line near-infrared spectroscopy are digitizing real-time boswellic acid monitoring during processing. German pharmaceutical clients now mandate this capability for batch release, compressing quality control cycles from days to hours. The technology is digitizing supplier qualification protocols, as automated documentation replaces manual certificate-of-analysis exchanges.
EMA's revised monograph for herbal medicinal products is tightening marker compound thresholds for Boswellia serrata extracts. Formulators in Stuttgart and Hamburg are reformulating to meet the updated AK/KBA ratio specifications, forcing raw material suppliers to retune extraction parameters. Capsule and tablet manufacturers serving the EU market are absorbing compliance costs through premium pricing stratification.
Practitioner-dependent distribution is fragmenting as patient-converted consumers migrate to subscription-based e-commerce platforms. Sports nutrition brands in North America are bypassing traditional nutraceutical distributors to source directly from Indian extractors with US warehouse presence. This channel compression is most visible in California and Texas, where direct-to-consumer joint health stacks now capture shelf space previously reserved for professional-grade formulations.
Boswellia Extract Market Segmentation
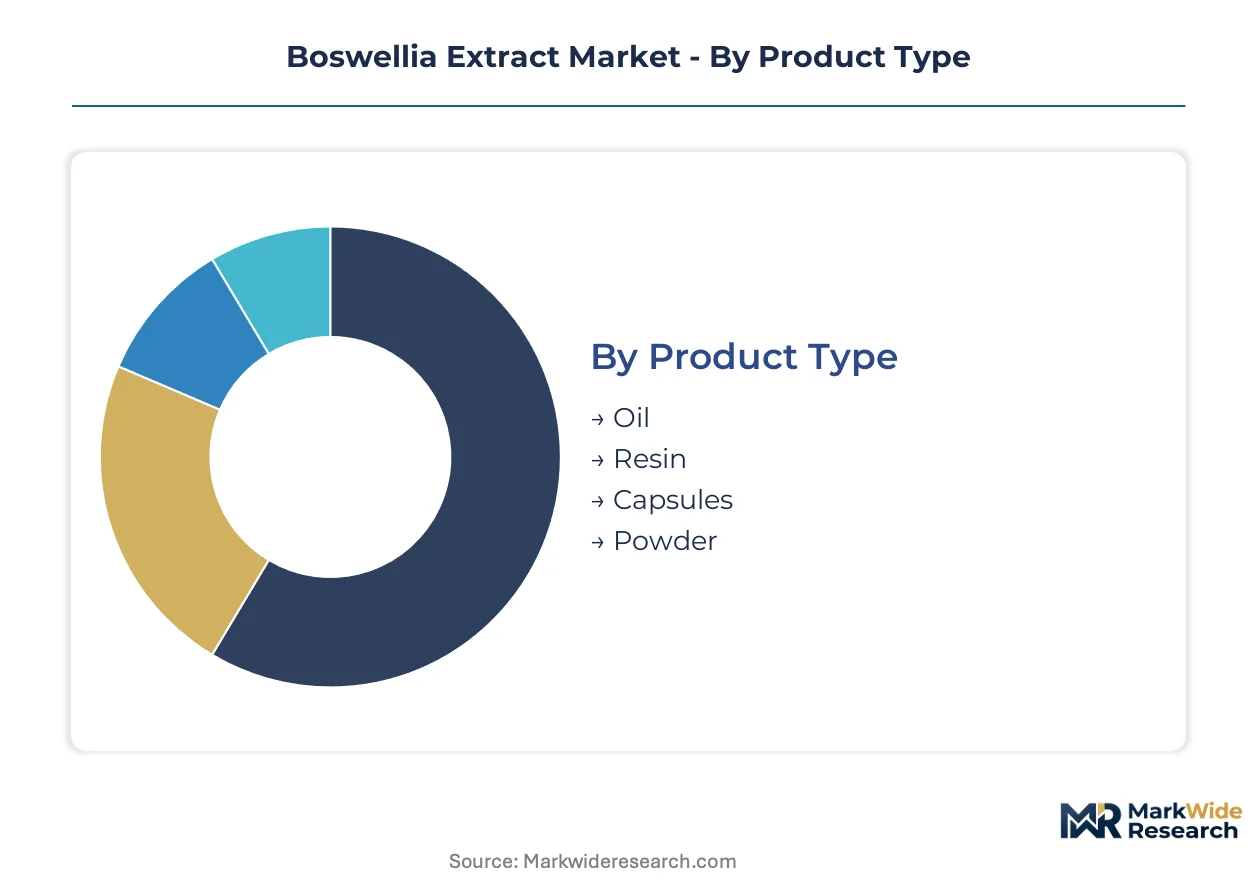
Boswellia extract applications span therapeutic, preventive, and cosmetic domains, with each use case demanding distinct standardization profiles and extraction specifications. Segmentation reveals how supply-side capabilities align with divergent customer requirements across pharmaceutical compounding, finished consumer goods, and direct wellness applications.
Product Type:
Use-case spectrum ranges from industrial raw material inputs to precision-dosed finished formats, with extraction method and standardization level determining addressable market tier.
- Capsules:Encapsulated standardized extracts typically deliver 300-500mg doses with 30-65% total boswellic acid content, enabling precise AK/KBA ratio control for joint health stacks. North American sports nutrition brands and German pharmaceutical compounders concentrate procurement here, driven by patient compliance advantages and EMA batch-release documentation requirements.
- Resin:Raw gum resin or partially refined extracts serve Ayurvedic drug manufacturers and traditional medicine practitioners requiring customizable processing flexibility. India's Gujarat and Karnataka processing clusters dominate supply, with solvent-free extraction infrastructure supporting export certification for European herbal medicinal product frameworks.
- Oil:Lipid-soluble fractions extracted via supercritical CO₂ or cold-press methods target topical anti-inflammatory and cosmetic applications.
- Powder:Spray-dried or milled extracts integrate into functional food matrices and bulk supplement manufacturing.
Established volume favors capsules; emerging adoption favors resin extracts in pharmaceutical compounding.
End User:
Customer type determines regulatory pathway, with pharmaceutical and nutraceutical channels imposing divergent compliance burdens on extractors.
- Nutraceuticals:Sports nutrition and healthy-aging brands drive fastest-expanding demand, integrating standardized Boswellia into multi-ingredient joint support formulations alongside glucosamine and curcumin. Direct-to-consumer e-commerce platforms in California and Texas accelerate procurement from Indian extractors with US warehouse presence.
- Pharmaceuticals:EMA monograph HMC/0027 compliance and FDA New Dietary Ingredient notifications govern market access, with Munich and Heidelberg formulation houses sourcing certified extracts under GMP protocols. Batch-level boswellic acid certification and ISO 17025 laboratory documentation filter supplier qualification.
- Food & Beverages:Functional beverage and fortified food applications require flavor-masked extracts with GRAS status or novel food approvals.
- Cosmetics:Topical anti-aging and soothing formulations utilize oil-soluble fractions for dermal delivery.
Pharmaceutical channels command premium positioning; nutraceuticals are climbing the fastest.
Application:
Therapeutic indication shapes marker compound targeting, with AK and KBA ratios optimized for specific physiological pathways.
- Joint Health:Osteoarthritis and rheumatoid arthritis applications require high-KBA extracts modulating 5-lipoxygenase inflammatory cascades. German and US orthopedic supplement brands specify 10%+ KBA content, with clinical substantiation driving branded ingredient premiums.
- Anti-Inflammatory:Systemic inflammation management targets broader boswellic acid spectra, with Ayurvedic practitioners and integrative medicine clinics in India and Germany utilizing traditional B. serrata preparations.
- Pain Relief:Adjunctive analgesic applications compete with NSAID cost structures in emerging-market healthcare systems.
- Digestive Support:Inflammatory bowel condition applications leverage gut-targeted delivery formats and enteric coating technologies.
Joint health captures dominant revenue share; anti-inflammatory applications gain share fastest in clinical settings.
Distribution Channel:
Channel structure determines margin capture and customer relationship depth, with disintermediation reshaping traditional practitioner-dependent models.
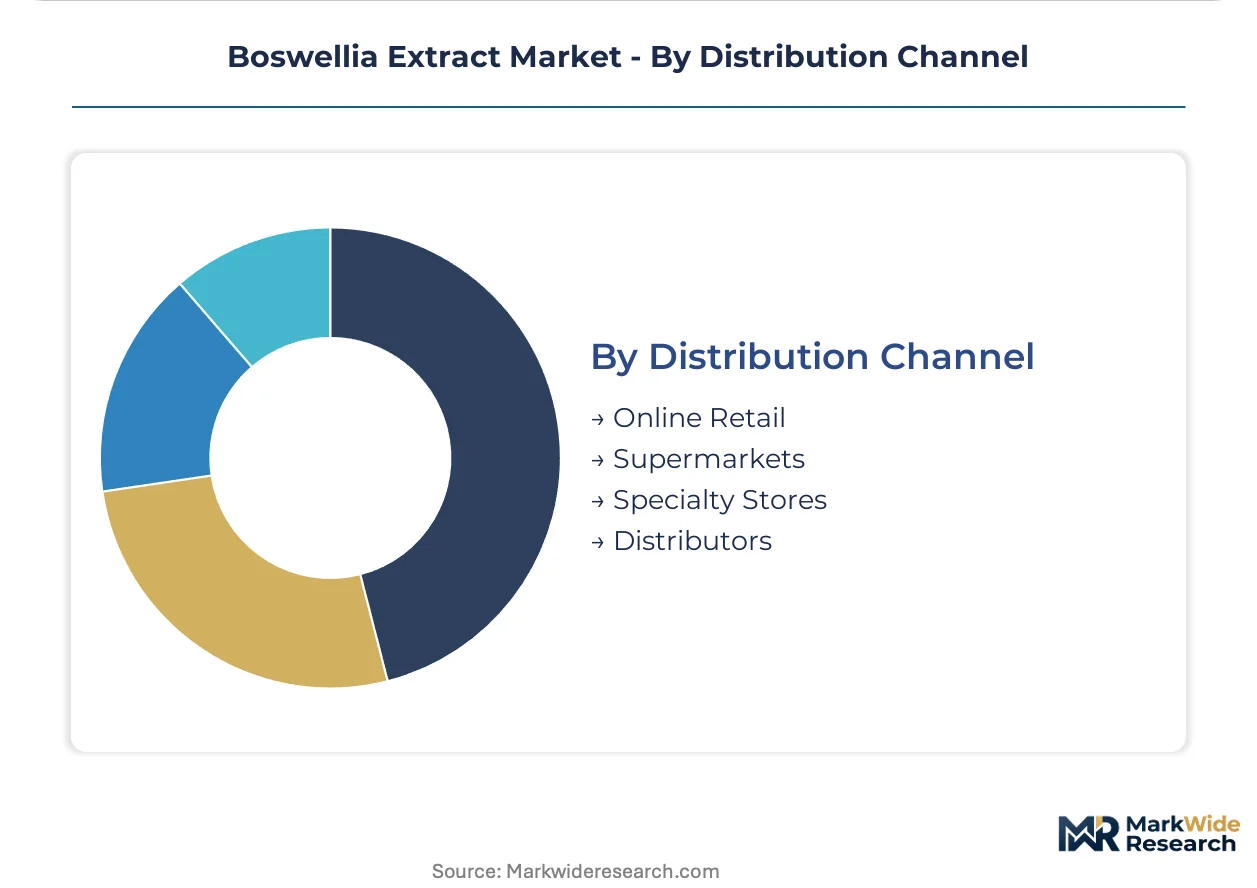
- Online Retail:Subscription-based specialty health platforms and direct-to-consumer brands disintermediate traditional distribution tiers, enabling extractors to capture margin previously lost to wholesale layers. Sports nutrition stack integration accelerates through California and Texas e-commerce fulfillment centers.
- Distributors:Professional-grade and practitioner-exclusive formulations maintain reliance on nutraceutical distributors with clinical education capabilities.
- Specialty Stores:Natural products retailers and Ayurvedic pharmacies serve educated consumer segments seeking traditional preparation guidance.
- Supermarkets:Mass-market penetration remains limited by price positioning against synthetic alternatives and consumer awareness gaps.
Distributor relationships defend professional-grade volume; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical channels while Indian extractors absorb margin compression from raw material volatility. EMA-compliant certification commands premiums unavailable to standard nutraceutical suppliers. Regional supply chains fragment between regulated European compounders and cost-optimized Asian processors.
Germany
Munich and Heidelberg formulation houses drive certified extract procurement under EMA monograph HMC/0027. The country's national pharmaceutical regulator mandates batch-level boswellic acid documentation for herbal medicinal products. Bavaria's GMP-compliant processing infrastructure anchors European pharmaceutical compounding demand.
India
Gujarat and Karnataka processing clusters concentrate solvent-free extraction capacity for export-oriented Ayurvedic manufacturers. CDSCO and AYUSH ministry regulations govern domestic drug manufacturing while ISO 17025 accreditation filters international buyer qualification. Resin collection networks in Rajasthan and Madhya Pradesh feed standardized extract production for European and North American clients.
United States
California and Texas e-commerce fulfillment centers accelerate direct procurement from Indian extractors with domestic warehouse presence. FDA New Dietary Ingredient notifications shape market entry timelines for novel extraction profiles. Sports nutrition brands in the Mountain West and Pacific Northwest integrate standardized Boswellia into joint support formulations.
Italy
Indena S.p.A.'s Milan-area operations exemplify European phytochemical standardization capabilities for pharmaceutical clients. The country's national pharmaceutical regulator aligns with EMA frameworks for herbal medicinal product compliance. Northern Italian extraction facilities serve branded ingredient demand from Swiss and German compounders.
Switzerland
Swissmedic regulations enforce stringent marker compound thresholds for Boswellia serrata extracts entering therapeutic channels. Basel-area pharmaceutical formulators source certified materials for inflammatory condition applications. The country's precision-chemical infrastructure supports high-KBA extraction for orthopedic supplement brands.
Boswellia Extract Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in raw resin collection and standardized extract production. The vendor base stratifies between vertically integrated Ayurvedic processors with captive gum resin supply and technology-licensed Western formulators dependent on outsourced standardization. Three archetypes dominate: legacy Indian extractors with analytical chemistry depth, North American branded ingredient marketers with clinical substantiation portfolios, and European pharmaceutical compounders with EMA compliance infrastructure. Competitive moves concentrate on ISO 17025 laboratory accreditation acquisition and direct-to-consumer channel disintermediation.
Among India-origin processors, Sabinsa Corporation, Arjuna Natural Pvt. Ltd., and Alchem International Pvt. Ltd. occupy positions spanning resin collection through pharmaceutical-grade extraction. These entities exemplify the vertically integrated archetype with in-house control over raw material supply and batch certification capabilities. North American representation includes PLT Health Solutions and NutraScience Labs, which sit within the branded ingredient marketing tier emphasizing clinical substantiation and direct e-commerce relationships. European processing concentration appears in Indena S.p.A., representing the pharmaceutical-standard extraction archetype serving EMA-compliant formulation houses.
| Leading Market Players |
|---|
| Sabinsa Corporation |
| PLT Health Solutions |
| Arjuna Natural Pvt. Ltd. |
| Alchem International Pvt. Ltd. |
| NutraScience Labs |
| Indena S.p.A. |
| Gurjar Phytochem Pvt. Ltd. |
| Alpspure Lifesciences Private Limited |
| Givaudan |
| Others |
Value Chain & Pricing Dynamics
Gujarat and Karnataka processing clusters anchor global resin-grade supply, with solvent-free extraction capacity concentration translating directly into premium capture for EMA-compliant batch certification. Standardized extract pricing stratifies sharply between pharmaceutical compounders absorbing GMP documentation costs and nutraceutical brands sourcing through direct e-commerce channels.
Pricing Analysis
The customization-premium spread separates configured-to-order pharmaceutical extracts from standard nutraceutical grades. Three-tier pricing structure across EMA-certified, ISO-accredited, and commodity resin tiers reflects divergent documentation burdens and analytical chemistry depth. Price differentiation hinges on AK/KBA ratio certification and batch-level HPLC validation. Cost compression in the standard nutraceutical tier intensifies as Indian extractors with US warehouse presence disintermediate traditional distribution layers. Sports nutrition brands in California and Texas exhibit highest price sensitivity, while Munich and Heidelberg formulation houses accept premium positioning for monograph compliance.
Supply Chain Analysis
Extended payment terms from German pharmaceutical clients and supply-chain finance facilities anchored by Gujarat processors lubricate working capital across the resin-to-extract pipeline. Raw material sourcing concentrates in India's Rajasthan and Madhya Pradesh collection networks, with downstream processing drawing from solvent-free extraction infrastructure in Karnataka. Supercritical CO₂ equipment dependencies and wild harvest yield volatility constitute structural supply risk. Distribution runs through direct-to-consumer e-commerce platforms, specialty health retailers, and practitioner-exclusive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against synthetic NSAID cost compression in emerging-market healthcare systems. Incumbents must navigate pricing pressure from low-cost chemical anti-inflammatories while preserving premium positioning through clinical substantiation.
For Market Incumbents: Build analytical chemistry moats through ISO 17025 laboratory accreditation and in-house HPLC method validation capabilities. Deepen backward integration into Rajasthan and Madhya Pradesh resin collection networks to secure captive supply against climate-induced yield volatility. Expand solvent-free extraction capacity in Karnataka processing clusters to serve EMA-compliant European pharmaceutical demand.
For New Entrants and Emerging Players: German pharmaceutical compounding houses in Stuttgart and Hamburg present underpenetrated demand for certified extracts under monograph HMC/0027. Target direct-to-consumer e-commerce fulfillment relationships with California and Texas sports nutrition brands seeking joint support stack ingredients. Pursue white-label manufacturing partnerships with Indian extractors lacking US warehouse presence.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because EMA and FDA compliance barriers protect incumbent returns while channel disintermediation expands addressable margin pools. Acquisition targets should display vertical integration from raw gum resin through batch certification, with established relationships to Munich or Heidelberg formulation houses. Monitor NDIN submission volumes and EMA monograph revision timelines as inflection indicators for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | Filters supplier qualification for EMA-compliant German pharmaceutical procurement. |
| Backward Integration into Resin Collection | Secures captive supply from Rajasthan and Madhya Pradesh wild harvest networks. |
| Direct-to-Consumer E-Commerce Launch | Disintermediates practitioner channels for California and Texas sports nutrition brands. |
| Solvent-Free Extraction Capacity Expansion | Supports export certification for European herbal medicinal product frameworks. |
| Clinical Substantiation Investment | Enables branded ingredient premiums for joint health applications with KBA ratio targeting. |
Study Parameters
A standing panel of Ayurvedic drug manufacturers, pharmaceutical formulators, nutraceutical procurement managers, and analytical chemistry laboratory directors provided ongoing calibration throughout the study. Primary interviews with resin collectors in Gujarat and extraction facility operators in Karnataka combined with secondary validation from CDSCO regulatory filings, EMA monograph documentation, AYUSH ministry guidelines, and customs trade data. Bottom-up volume modeling and top-down value triangulation anchored market size estimation.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of wild harvest yield assumptions and regulatory compliance cost trajectories. Segmentation modeling incorporated product type, end user channel, therapeutic application, and distribution pathway dimensions. CAGRs derived from fitted growth curves applied to resin collection volume estimates and extract price trajectories, with pharmaceutical-grade standardization premiums and nutraceutical channel expansion rates as key forecast inputs.
Practitioners should monitor EMA monograph revision timelines, FDA NDIN approval cycles, and climate-induced yield volatility in Rajasthan resin zones for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Myrrh Gum Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Habanero Salt Market
Spices and Seasonings
Dried Herbs Market
Spices and Seasonings
Egypt Herbs and Spices Market
Spices and Seasonings
Spice Coated Casing Market
Spices and Seasonings
Serrata Extract Market
Spices and Seasonings
Oregano Oil Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Wasabi Market
Spices and Seasonings
Pink Himalayan Salt Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Sichuan Peppercorn Market