
 Onion Salt Market | 2026-2036
Onion Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Onion Salt Market Analysis
Private-label seasoning revenue is fragmenting across retail and food-service channels as branded suppliers lose pricing power. McCormick & Company, Inc. anchors its position through R&D intensity in flavor extraction technologies. Badia Spices competes on manufacturing scale and channel control across Hispanic and mainstream grocery segments. Döhler extends its footprint in Europe through captive supply of natural onion extracts for industrial seasoning blends.
Onion salt is a blended seasoning comprising dehydrated onion particles and crystalline sodium chloride, typically containing 30–50% onion solids by weight and manufactured through low-temperature drying and precision milling to preserve volatile sulfur compounds responsible for pungency. Granulated and powdered variants dominate volume due to their dispersion uniformity in dry soup bases and snack coatings, while flake formats command premium positioning in gourmet retail. The culinary and snack foods use cases absorb the bulk of industrial demand, though sauces represent the fastest-growing application as ready-meal manufacturers seek clean-label umami enhancement.
FDA food additive regulations and USDA organic certification requirements govern ingredient disclosure and processing claims in the United States, while EFSA standards and EU labeling directives shape market access across European member states. Compliance with sodium-reduction frameworks in multiple jurisdictions is forcing reformulation toward potassium chloride blends and natural flavor potentiation. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to invest in proprietary drying technologies or outsource to specialized extract suppliers.
Market Dynamics
Clean-label sodium-reduction mandates across the United States and European Union are forcing reformulation of onion salt toward potassium chloride blends and natural flavor potentiation, compressing legacy formulations while opening premium positioning for compliant suppliers.
Growth Catalysts
- Snack food manufacturer demand:Processed food producers in the United States are expanding onion salt use as a core flavoring agent in coatings and seasonings, absorbing volume at industrial scale.
- EU clean-label regulations:EFSA standards and front-of-pack labeling directives are reshaping formulation requirements, advantaging suppliers with natural extract capabilities and transparent supply chains.
- Low-temperature drying technology:Precision milling and controlled dehydration preserve volatile sulfur compounds, enabling premium positioning for flavor-intense granulated variants in gourmet retail channels.
Market Restraints
- Onion input cost volatility:Weather-driven supply fluctuations in major onion-producing regions create margin pressure for dehydrated ingredient processors.
- Supply concentration in extract processing:Captive supply arrangements by European industrial blenders limit third-party access to standardized natural onion extracts.
- Potassium chloride substitution limits:Technical constraints on sodium replacement in specific applications cap reformulation flexibility under FDA and USDA frameworks.
Strategic Opportunities
- Sauce and ready-meal application expansion:Clean-label umami enhancement demand from sauce manufacturers represents underpenetrated volume potential.
- USDA organic certification tailwind:Organic processing claims unlock premium pricing in United States retail and food-service channels.
- Direct-to-food-service distribution:Bypassing traditional retail intermediaries allows customized blend development for regional restaurant chains.
Industry Challenges
- Volatile sulfur compound retention expertise:Specialized food engineering talent for optimizing pungency preservation commands scarcity premiums.
- Proprietary drying equipment capex:In-house low-temperature dehydration systems require substantial capital commitment versus outsourced extract sourcing.
- Multi-jurisdiction compliance synchronization:Aligning FDA disclosure requirements with EU labeling directives extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Onion Salt Market |
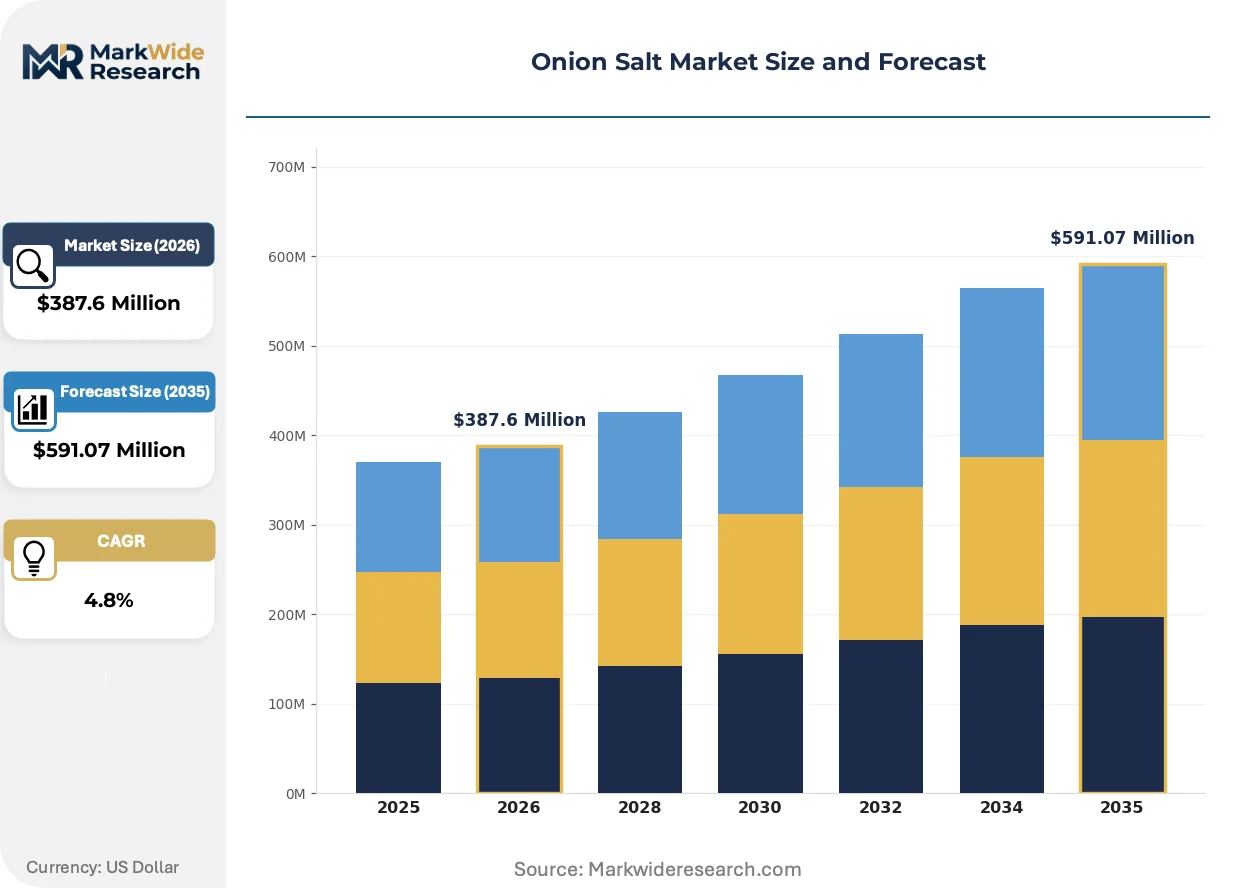
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated, Powdered, Flakes, Liquid Use Case: Culinary, Seasoning, Snack Foods, Sauces Packaging Type: Bottles, Pouches, Tubs, Bulk Distribution Channel: Supermarkets, Online Retail, Wholesale, Food Service |
| Companies Covered | Schwartz, Hoyts Food Manufacturing Industries Pty Ltd, McCormick & Company, Inc., Redmond Life, Woodland Foods, B&G Foods, Inc., The Kroger Co., Döhler, Badia Spices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Onion Salt Market Emerging Trajectories
Digital quality control systems and precision agriculture inputs are converging with regulatory pressure to reshape how onion salt specifications are verified and traced from field to finished seasoning.
Hyperspectral imaging for moisture and sulfur compound detection is virtualizing traditional laboratory testing protocols. Snack food manufacturers in the United States are adopting inline spectroscopic sorting at procurement stage. This technology is virtualizing quality assurance labor while compressing batch-to-batch variation penalties.
EFSA front-of-pack nutrient scoring mandates are tightening disclosure thresholds for sodium content in blended seasonings. Industrial blenders across European member states are reformulating toward reduced-sodium claims. Sauce and ready-meal segments face the steepest compliance curves, accelerating natural flavor potentiation R&D.
Consolidated procurement by national restaurant chains is displacing fragmented distributor purchasing. United States food-service operators are centralizing seasoning specification authority at corporate level. This concentration is most visible in quick-service and fast-casual verticals, compressing supplier negotiation leverage.
Onion Salt Market Segmentation
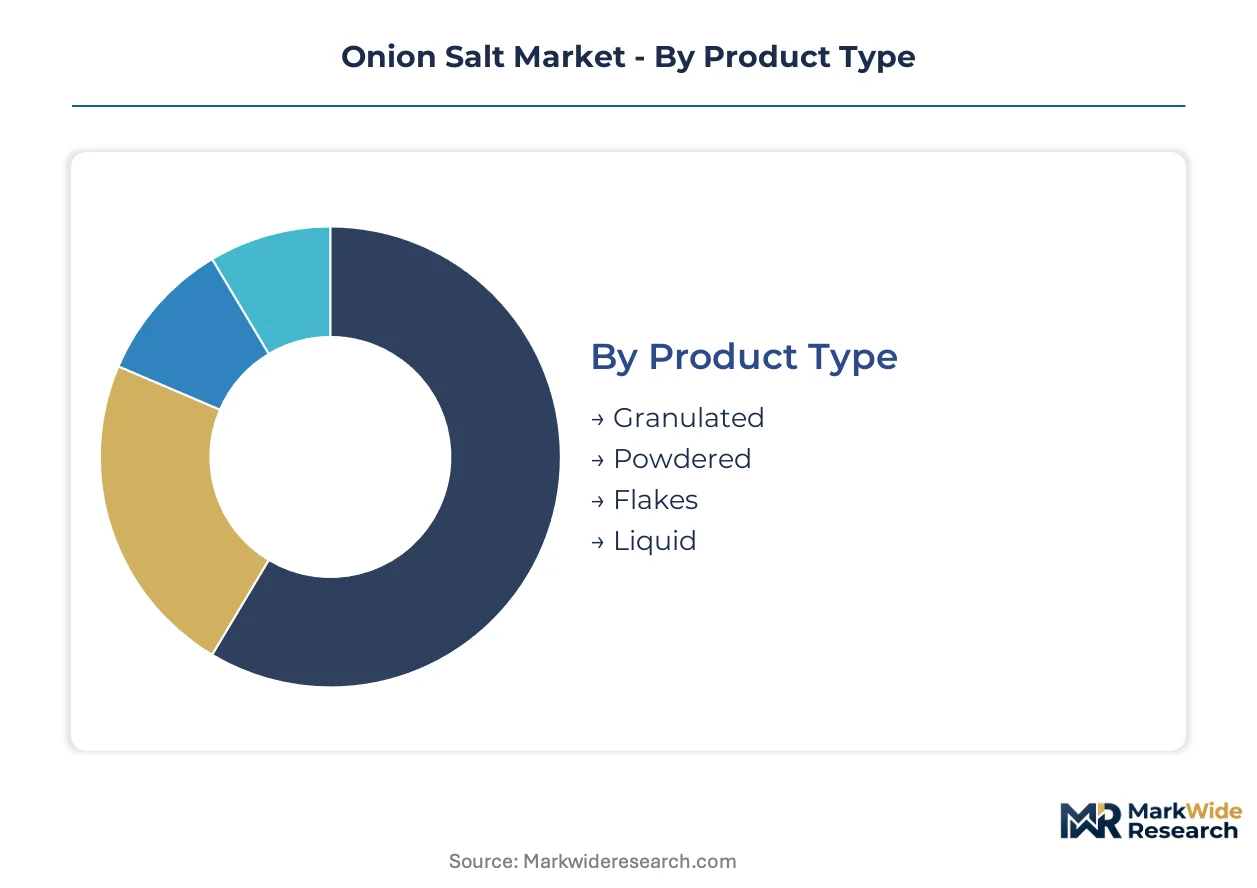
Onion salt segmentation reveals distinct performance profiles across physical form, end-use intensity, and channel economics. Each dimension carries implications for drying technology investment, shelf-life engineering, and margin capture.
Product Type:
After-sales service intensity concentrates in liquid and flake formats where flavor stability monitoring and reconstitution guidance generate recurring supplier engagement.
- Granulated:Uniform particle size between 0.5-2.0mm enables consistent dispersion in dry soup bases and industrial seasoning blends. Snack food manufacturers in the United States absorb volume at industrial scale for coating applications where precision dosing controls sodium delivery.
- Powdered:Sub-0.5mm milling maximizes surface area for rapid dissolution in wet applications. Sauce manufacturers seeking clean-label umami enhancement are driving formulation customization requests that extend technical service relationships.
- Flakes:Dehydrated onion pieces retain visual identity for gourmet retail positioning. Specialty food distributors command premium placement in European premium grocery channels.
- Liquid:Aqueous extracts and oil-based suspensions serve industrial food processors requiring pumpable delivery systems. Concentrated formats reduce shipping costs for transoceanic supply chains.
By volume, granulated leads. By growth pace, powdered is ahead.
Use Case:
Application-driven cost tiers separate commodity seasoning from value-added flavor systems where technical collaboration commands pricing premiums.
- Culinary:Home cooking and small-scale food preparation rely on retail-packaged formats with recipe-support content. Supermarket placement in the United States and Germany drives volume concentration.
- Seasoning:Industrial blenders integrate onion salt into multi-component spice mixes for meat processing and bakery applications. EFSA disclosure requirements are reformulating specifications across European member states.
- Snack Foods:Coating uniformity requirements for chips, crackers, and extruded products favor granulated variants with controlled particle distribution. United States quick-service chains centralize procurement authority at corporate level.
- Sauces:Ready-meal manufacturers and condiment producers seek sodium-reduced formulations with natural flavor potentiation. This segment is expanding most quickly as clean-label mandates tighten.
Culinary and snack foods absorb the bulk of volume. Sauces are climbing the fastest.
Packaging Type:
Customer type segmentation separates retail convenience buyers from industrial scale purchasers with divergent handling and storage requirements.
- Bottles:Glass and PET containers with shaker tops dominate United States mainstream grocery and Hispanic specialty retail. McCormick and Badia Spices compete for shelf space through differentiated cap designs.
- Pouches:Flexible film packaging reduces material cost and shipping weight for value-tier positioning. Online retail channels favor pouches for dimensional efficiency in fulfillment centers.
- Tubs:Rigid plastic containers serve food-service operators requiring scoop access and moisture protection. Regional restaurant chains specify tub formats for back-of-house efficiency.
- Bulk:Super sacks and fiber drums supply industrial seasoning blenders with tonnage-scale procurement. Captive supply arrangements by European extract processors limit third-party access.
Bottles command the highest unit margins. Bulk is gaining share fastest through food-service consolidation.
Distribution Channel:
Supply concentration across channel types creates divergent margin structures and technical service obligations.
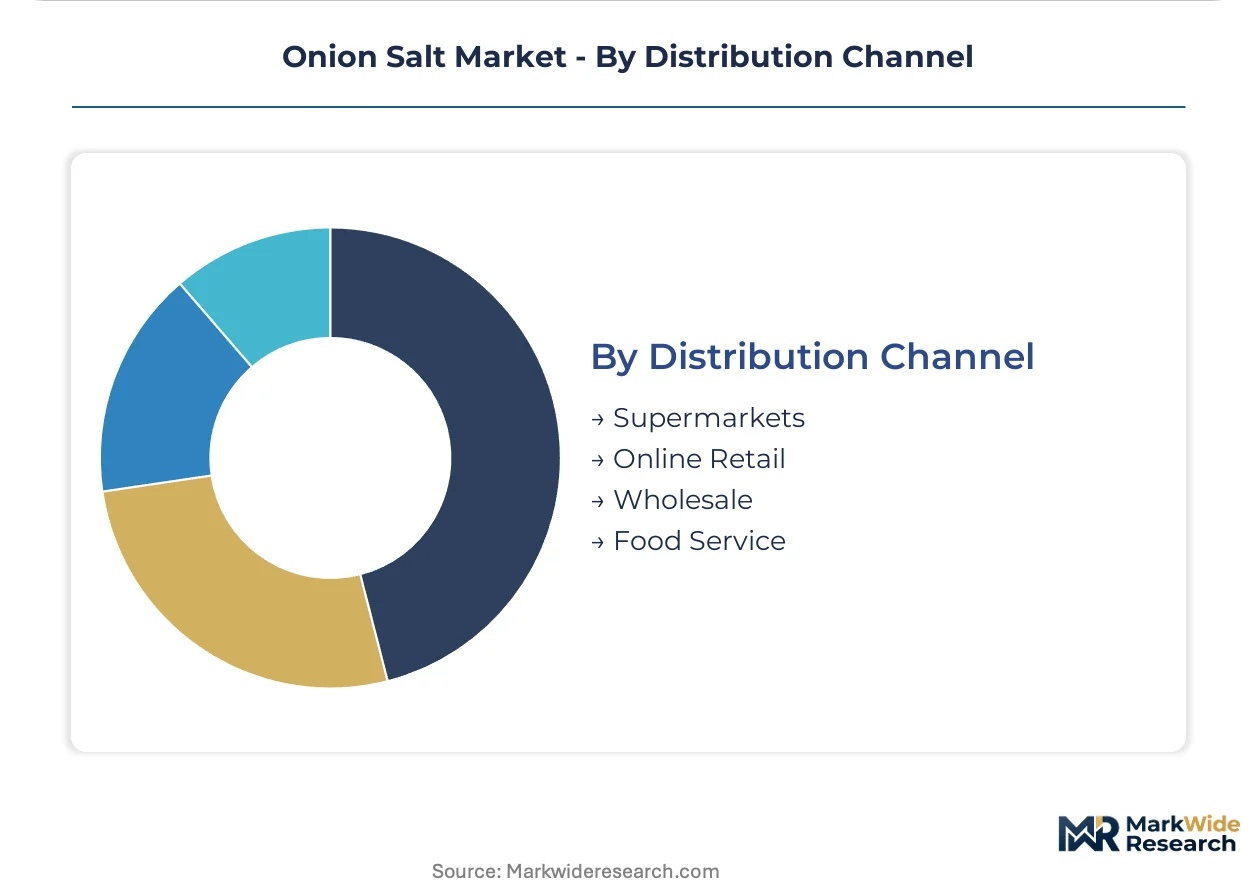
- Supermarkets:Brick-and-mortar grocery chains in the United States and Germany maintain category captain arrangements with branded suppliers. Planogram compliance and promotional funding determine placement depth.
- Online Retail:E-commerce platforms aggregate fragmented demand for specialty and organic variants. Direct-to-consumer subscription models are emerging for gourmet flake formats.
- Wholesale:Broadline distributors serve independent restaurants and regional food manufacturers with consolidated procurement. Döhler leverages European wholesale networks for natural extract distribution.
- Food Service:National chain direct accounts bypass distributor markups for customized blend development. Corporate-level specification authority compresses supplier negotiation leverage in United States quick-service verticals.
Supermarkets anchor volume. Food service is expanding most quickly through chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dehydrated onion processing clusters in the United States and Germany supply industrial blenders across North America and Europe. FDA sodium-reduction frameworks and EFSA front-of-pack labeling mandates are forcing parallel reformulation investments. Industrial seasoning demand concentrates in snack manufacturing corridors and ready-meal production zones.
United States
Snack food manufacturers in the Midwest and Southeast absorb granulated onion salt at industrial scale for coating applications. FDA food additive regulations and USDA organic certification requirements govern ingredient disclosure and processing claims. Chicago and Dallas-Fort Worth anchor blending operations where corporate procurement centralization compresses supplier negotiation leverage.
Germany
Industrial seasoning blenders across Bavaria and North Rhine-Westphalia source natural onion extracts for clean-label reformulation. EFSA standards and EU labeling directives shape specification requirements for sodium-reduced variants. Frankfurt-Rhine-Main cluster houses captive supply arrangements that limit third-party access to standardized extracts.
United Kingdom
Retail and food-service channels fragment private-label seasoning revenue as branded suppliers face pricing pressure. EFSA front-of-pack nutrient scoring mandates tighten disclosure thresholds for sodium content. London and the Midlands concentrate gourmet retail distribution where flake formats command premium positioning.
India
Dehydrated onion processing expands in Gujarat and Maharashtra to serve domestic seasoning manufacturers and export markets. FSSAI labeling requirements and state-level food safety audits govern processing facility compliance. Nashik and Ahmedabad clusters specialize in low-temperature drying for volatile sulfur compound retention.
China
Sauce and ready-meal manufacturers in the Yangtze River Delta seek sodium-reduced formulations with natural flavor potentiation. SAMR food additive standards and GB labeling requirements shape import and domestic production specifications. Shanghai and Suzhou industrial zones concentrate precision milling capacity for sub-0.5mm powdered variants.
Onion Salt Market Vendor Landscape
Multinational seasoning conglomerates and specialized extract suppliers split the market between scale-driven industrial supply and premium retail positioning. The vendor base concentrates around three strategic archetypes: R&D-intensive flavor technology developers, manufacturing-scale commodity processors, and natural extract specialists with captive supply integration. Dominant competitive moves include backward integration into dehydration capacity and strategic partnerships with snack food manufacturers for customized blend development.
Within the multinational conglomerate tier, McCormick & Company, Inc. and Döhler occupy positions defined by geographic reach and extract technology specialization respectively. Badia Spices exemplifies the manufacturing-scale archetype with channel control across Hispanic and mainstream grocery segments. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Schwartz |
| Hoyts Food Manufacturing Industries Pty Ltd |
| McCormick & Company, Inc. |
| Redmond Life |
| Woodland Foods |
| B&G Foods, Inc. |
| The Kroger Co. |
| Döhler |
| Badia Spices |
| Others |
Supply Flow & Price Mechanics
Nashik and Ahmedabad dehydration clusters in India anchor global supply of low-temperature dried onion solids, concentrating pricing power among processors with proprietary sulfur-retention technology while compressing margins for commodity-grade competitors serving bulk industrial blenders.
Pricing Analysis
After-sales technical service revenue for flavor stability monitoring and reconstitution guidance drives lifetime value differentiation across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified organic variants with USDA claims from conventional granulated formats and private-label commodity powder. Price differentiation hinges on volatile sulfur compound retention certification and volume-scale procurement terms. Pricing pressure stems from potassium chloride substitution R&D costs as sodium-reduction mandates tighten across FDA and EFSA jurisdictions. Snack food manufacturers in the United States exhibit highest price sensitivity due to corporate procurement centralization, while gourmet retail channels in Germany absorb premium flake positioning with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on precision milling equipment and hyperspectral imaging systems from Germany and Japan constrain capacity expansion for sub-0.5mm powdered variants in emerging processing hubs. Supply concentrates in the United States, India, and Germany, with raw material dependencies on yellow onion cultivars from California and Gujarat, crystalline sodium chloride from domestic salt deposits, and potassium chloride for reformulation blends. Single-source vulnerability runs through captive natural extract arrangements by European industrial blenders that limit third-party access. Distribution runs through food-service direct accounts for national chains and broadline wholesale networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh onion paste and refrigerated allium extracts represent immediate substitution threats that incumbent dehydrated processors must neutralize through convenience and shelf-stability positioning.
For Market Incumbents: Pre-empt potassium chloride blend commoditization by securing exclusive low-temperature drying technology licenses and expanding captive organic onion acreage in Gujarat. FDA sodium-reduction framework compliance investments anchor pricing power as regulatory barriers rise. Backward integration into precision milling equipment manufacturing defends margin position against import-restricted competitors. For New Entrants and Emerging Players: Mid-tier sauce manufacturers in China's Yangtze River Delta seeking clean-label umami enhancement represent the most penetrable entry point for natural extract specialists. USDA organic certification gaps among Hispanic grocery distributors in the United States Southwest create channel white-space. Direct technical service partnerships with regional ready-meal producers bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because sodium-reduction R&D intensity and multi-jurisdiction compliance synchronization favor scaled processors with regulatory affairs depth. Acquisition targets should display proprietary volatile sulfur compound retention expertise and existing EFSA front-of-pack labeling compliance. Monitor SAMR enforcement patterns in China as the inflection signal for Asian market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dehydration Capacity | In-house low-temperature drying secures sulfur compound retention margins against extract supply constraints. |
| USDA Organic Certification Investment | Premium positioning in United States retail channels unlocks pricing power as clean-label mandates tighten. |
| Direct-to-Food-Service Distribution Buildout | Bypassing broadline distributors enables customized blend development for national quick-service chains. |
| Potassium Chloride Reformulation R&D | Natural flavor potentiation expertise addresses FDA sodium-reduction framework compliance requirements. |
| Hyperspectral Imaging Quality Control Deployment | Inline spectroscopic sorting virtualizes laboratory testing labor for snack food manufacturer procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA food additive filings, EFSA scientific opinions, USDA organic certification databases, and customs trade records for dehydrated onion solids. Interviews with snack food procurement directors, industrial seasoning blenders, dehydration plant engineers, and gourmet retail category buyers inform demand-side validation. Bottom-up volume triangulation from processor capacity assessments and top-down value reconciliation from channel margin analysis anchor quantitative outputs.
Forecast inputs span product type granularity across granulated, powdered, flake, and liquid formats; use case segmentation for culinary, seasoning, snack foods, and sauces; and distribution channel dynamics from supermarket planogram economics to food-service direct account concentration. CAGRs derive from regression analysis against processed food production indices and seasoning innovation intensity metrics. Volatile sulfur compound retention technology adoption curves and sodium-reduction mandate implementation timelines shape projection trajectories across the modeling period.
Macroeconomic conditions sit as an overlay; deviation in onion input commodity prices, energy costs for low-temperature drying operations, or transoceanic freight rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and clean-label claim interpretation stability. Cross-checking against EEA trade statistics and United States Census Bureau processed food production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
Low Sodium Sea Salt Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Lemon Salt Market
Spices and Seasonings
Green Pepper Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Dried Spices Market
Spices and Seasonings
Herbs and Spices Market
Spices and Seasonings
Smoked Salt Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Pumpkin Pie Spices Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Blended Spices Market