
 Cajun Spice Market | 2026-2036
Cajun Spice Market Size, Share, and Industry Trends Forecast 2026-2036
Cajun Spice Market Outlook
Chili pepper cultivation expertise in Louisiana's Acadiana region is unwinding supply bottlenecks that previously constrained artisanal production scale. McCormick & Company, Inc. leverages its vertically integrated procurement network to secure consistent cayenne and paprika streams from contracted growers. Slap Ya Mama anchors its competitive stance through family-recipe authenticity and deep penetration of independent grocers across Gulf Coast states. Badia Spices competes on manufacturing scale, operating one of the largest spice grinding and blending facilities serving the Latin and Cajun crossover segments.
Cajun spice denotes a blended seasoning matrix typically comprising paprika, cayenne pepper, garlic powder, onion powder, black pepper, and dried herbs such as oregano and thyme, formulated to deliver a smoky-heat flavor profile characteristic of Louisiana Creole and Acadian cooking traditions. Industrial formulations achieve Scoville heat unit standardization through calibrated capsaicin extraction and controlled batch blending to ensure repeatable intensity across food manufacturing applications. Cajun Seasoning dominates volume flows through retail and foodservice channels, while Cajun Sauce captures expanding shelf-space in specialty stores as consumers seek ready-to-apply formats. Foodservice channels sustain the fastest growth trajectory, driven by quick-service restaurant chains incorporating Cajun profiles into limited-time offerings and permanent menu lines.
The FDA enforces stringent mycotoxin and pathogen thresholds under the Food Safety Modernization Act, compelling importers to implement hazard analysis and preventive controls across pepper supply chains originating from India and Mexico. USDA organic certification requirements shape premium tier positioning, as consumers associate clean-label claims with perceived authenticity in regional cuisine products. State-level cottage food laws in Louisiana and Texas create parallel regulatory pathways for small-batch producers entering farmers markets and direct-to-consumer channels. Stakeholders must monitor evolving FDA import alert protocols and climate-driven chili pepper harvest volatility to secure supply continuity and brand credibility.
Market Dynamics
The FDA's Food Safety Modernization Act is compressing supply chain configurations as importers rebuild pepper procurement networks around hazard-analysis mandates and traceability infrastructure.
Growth Catalysts
- Foodservice Channel Expansion:Quick-service restaurant chains in Texas and Louisiana are embedding Cajun profiles into permanent menu lines, creating sustained offtake agreements for calibrated heat-standardization services.
- Clean-Label Premium Tier:USDA organic certification requirements are pulling consumers toward perceived authenticity in regional cuisine products, rewarding small-batch producers with price premiums at specialty retail.
- Capsaicin Extraction Standardization:Industrial formulations now achieve repeatable Scoville heat units through controlled batch blending, enabling food manufacturers to specify exact intensity thresholds for co-manufacturing contracts.
Market Restraints
- Import Supply Concentration:Chili pepper sourcing from India and Mexico creates mycotoxin exposure risk that triggers FDA import alerts, forcing costly pre-shipment testing and detention contingency planning.
- Climate-Driven Harvest Volatility:Rainfall irregularity in Acadiana growing regions disrupts artisanal-scale cayenne availability, constraining family-recipe producers from fulfilling foodservice volume commitments.
- Substitution by Generic Heat Blends:Commodity paprika-cayenne mixtures without Louisiana heritage positioning capture price-sensitive retail shelf space, eroding brand-equity differentiation.
Strategic Opportunities
- Direct-to-Consumer Cottage Law Pathways:Louisiana and Texas state-level cottage food regulations enable small-batch producers to bypass conventional retail slotting fees through farmers market penetration and subscription box channels.
- Ready-to-Apply Sauce Formats:Cajun Sauce applications are capturing expanding specialty store shelf space as home cooks seek convenience without sacrificing perceived authenticity.
- Latin-Cajun Crossover Segmentation:Blending facilities serving both culinary traditions can leverage shared grinding infrastructure to achieve manufacturing scale economies across adjacent flavor categories.
Industry Challenges
- Preventive Controls Qualified Individual Shortage:FDA's FSMA mandate for documented hazard analysis creates talent scarcity as small importers compete for certified food safety professionals.
- Legacy Batch-to-Batch Variability:Family-recipe producers struggle to document consistent process controls for organic certification audits, delaying premium tier market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cajun Spice Market |
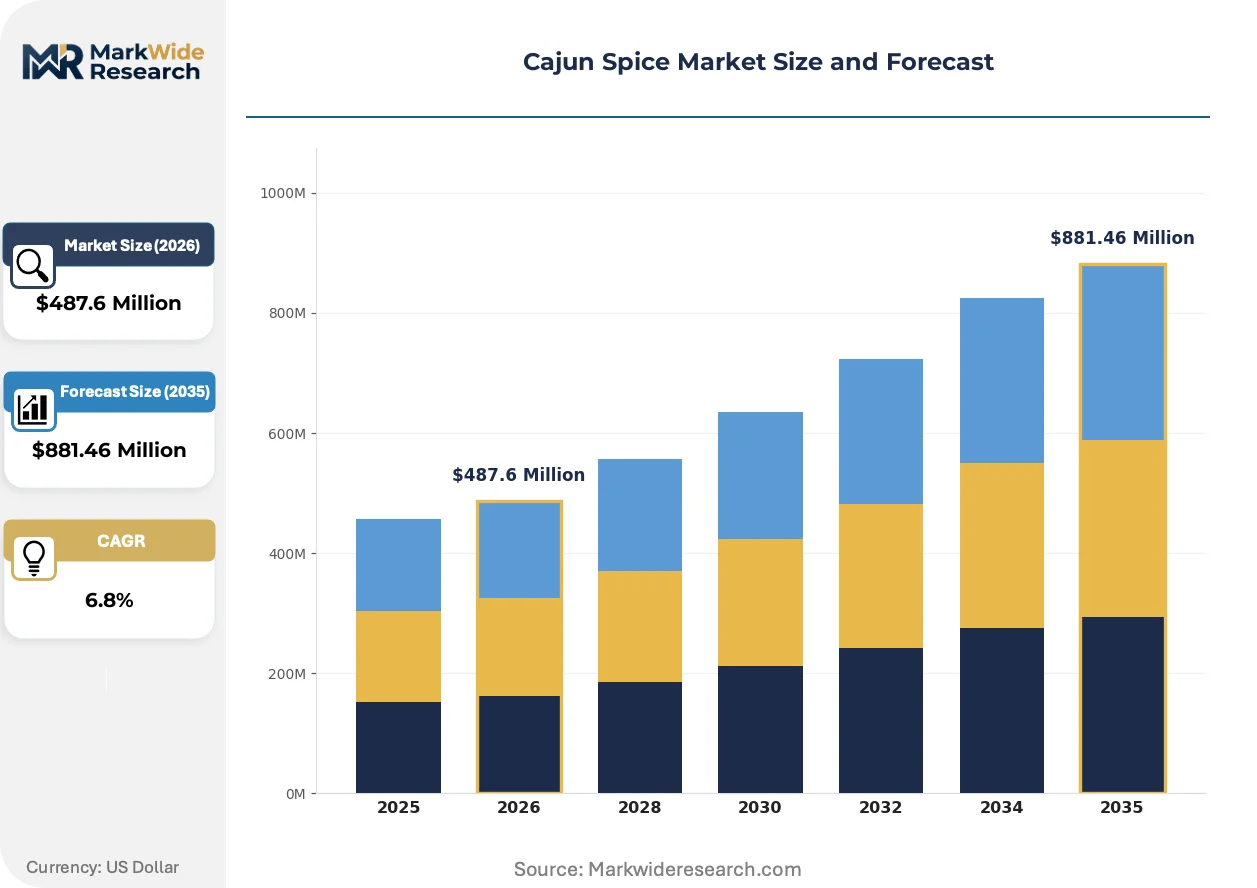
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cajun Seasoning, Cajun Sauce, Cajun Marinade, Cajun Infused Oil Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice End User: Home Chefs, Restaurants, Catering Services, Food Manufacturers Cuisine Type: Southern American, Barbecue, Creole, Spicy Foods |
| Companies Covered | McCormick & Company, Inc., The Kraft Heinz Company, Fiesta Spices, Louisiana Fish Fry, The Food Source International, Inc., Gel Spice Company, Inc., Keya Foods International Pvt Ltd., Slap Ya Mama, Badia Spices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cajun Spice Market Strategic Shifts
Processing technology and regulatory enforcement are actively fragmenting competitive positioning between industrial-scale standardization and artisanal authenticity claims.
Near-infrared spectroscopy for capsaicin content verification is bifurcating procurement relationships. Large food manufacturers are adopting this technology to enforce incoming raw material specifications. Small-batch producers lacking capital for spectroscopy investment are retreating toward direct-to-consumer channels where batch variability becomes a marketed authenticity signal.
REACH compliance requirements for imported spice extracts are tightening contaminant thresholds entering European Union markets. Exporters to Germany and France must now document pesticide residue testing across contracted Indian grower networks. This regulatory friction is diverting premium pepper volumes toward US Gulf Coast ports, intensifying competition for Louisiana and Texas distribution capacity.
Home cook experimentation patterns are compressing brand loyalty cycles. Social media recipe dissemination accelerates format switching between dry seasoning and wet sauce applications. This behavior is most visible in urban Texas markets where younger consumers treat Cajun profiles as modular components rather than traditional cuisine adherence.
Cajun Spice Market Segmentation
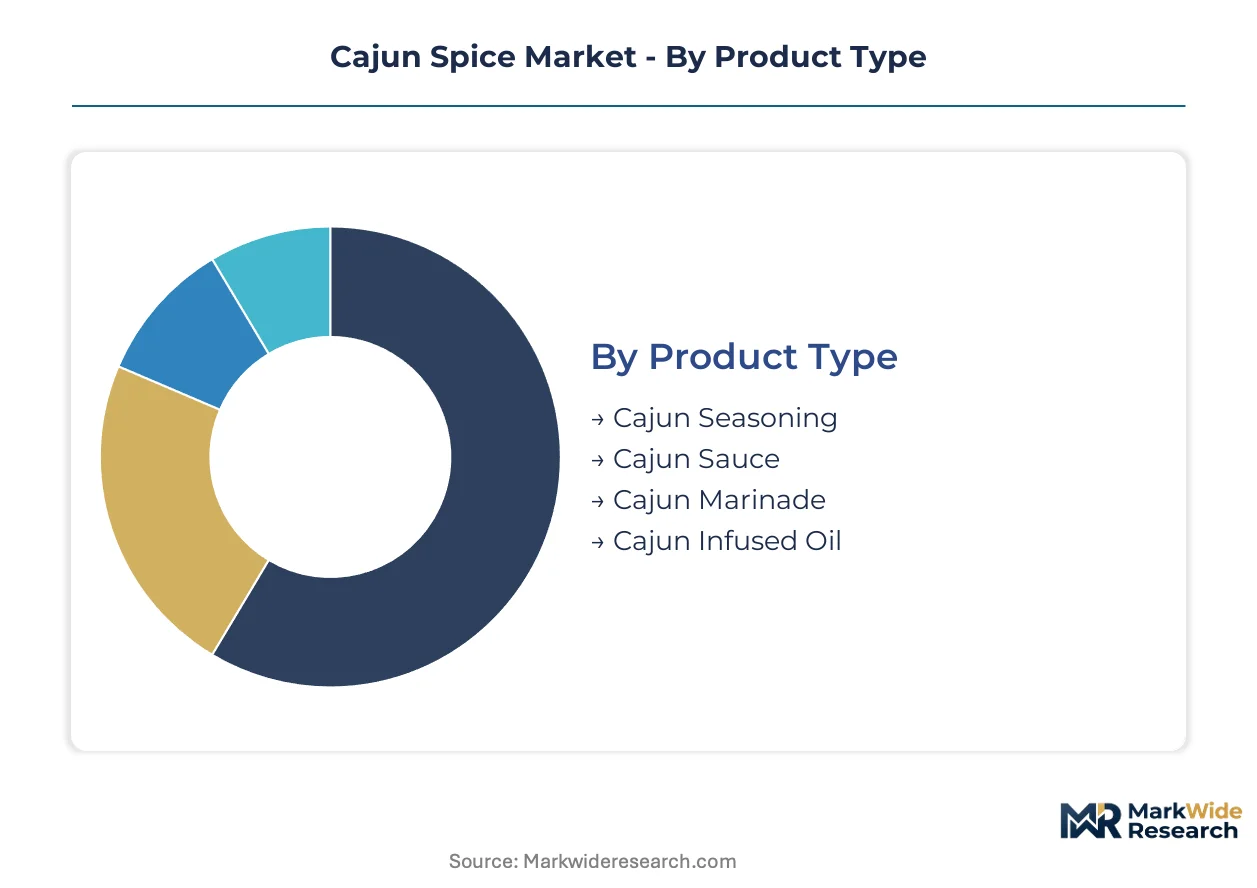
Cajun spice market segmentation reveals distinct regulatory and commercial pathways across product formats and channel structures. Understanding these divisions exposes where FDA compliance costs concentrate versus where cottage food exemptions create competitive entry points.
Product Type:
FDA hazard analysis requirements differentiate shelf-stable dry blends from acidified sauce formulations, creating divergent compliance cost structures for manufacturers.
- Cajun Seasoning:Dry blended matrices of paprika, cayenne, garlic powder, and dried herbs achieve extended shelf stability without acidification controls. Texas and Louisiana foodservice channels absorb the highest volumes as quick-service chains specify calibrated Scoville heat units for menu consistency. USDA organic certification commands price premiums at specialty retail, though batch-to-batch variability challenges small producers during audit documentation.
- Cajun Sauce:Acidified wet formulations containing vinegar or citrus bases require documented pH monitoring and scheduled process filings under FDA low-acid canned food regulations. Specialty store shelf space is expanding fastest as home cooks seek ready-to-apply convenience without sacrificing perceived Louisiana authenticity. REACH compliance for European export adds pesticide residue testing burdens that divert premium volumes toward domestic Gulf Coast distribution.
- Cajun Marinade:Liquid immersion preparations with oil and acid components straddle regulatory categories depending on water activity thresholds.
- Cajun Infused Oil:Oil-based extraction products face distinct FDA enforcement priorities around anaerobic packaging and botulism risk mitigation.
Established volume favors Cajun Seasoning; emerging adoption favors Cajun Sauce.
Distribution Channel:
Channel cost structures range from minimal slotting fees in direct-to-consumer pathways to substantial trade spend requirements in conventional retail.
- Foodservice:Quick-service restaurant chains in Texas and Louisiana generate sustained offtake through calibrated heat-standardization contracts. McCormick's vertically integrated procurement network secures consistent cayenne streams for large-scale manufacturing agreements. Climate-driven harvest volatility in Acadiana constrains artisanal producers from fulfilling volume commitments to regional chain accounts.
- Specialty Stores:Independent grocers across Gulf Coast states reward family-recipe authenticity with dedicated shelf space and localized marketing support. Slap Ya Mama leverages deep penetration here to defend against commodity substitution. Clean-label positioning aligns with USDA organic certification requirements that shape premium tier consumer perception.
- Supermarkets:National retail consolidation demands standardized case cube efficiencies and promotional calendar compliance.
- Online Retail:Direct-to-consumer pathways enable subscription box models that bypass conventional trade spend structures.
Margin concentration sits with Specialty Stores; volume scale concentrates in Foodservice.
End User:
User sophistication determines specification rigor, from home cook experimentation to industrial heat-unit tolerancing.
- Restaurants:Professional kitchens demand Scoville standardization through near-infrared spectroscopy verification of incoming raw materials. Badia Spices competes on manufacturing scale across Latin and Cajun crossover segments to serve this specification-driven demand. Social media recipe dissemination accelerates format switching between dry seasoning and wet sauce applications in urban Texas markets.
- Home Chefs:Younger consumers in metropolitan areas treat Cajun profiles as modular components rather than traditional cuisine adherence, compressing brand loyalty cycles. Louisiana and Texas cottage food laws enable farmers market penetration with minimal regulatory burden for small-batch producers.
- Catering Services:Event-scale volume requirements favor bulk procurement relationships with established distributors.
- Food Manufacturers:Co-manufacturing contracts specify exact intensity thresholds through controlled batch blending capabilities.
Specification intensity peaks with Restaurants; flexibility tolerance peaks with Home Chefs.
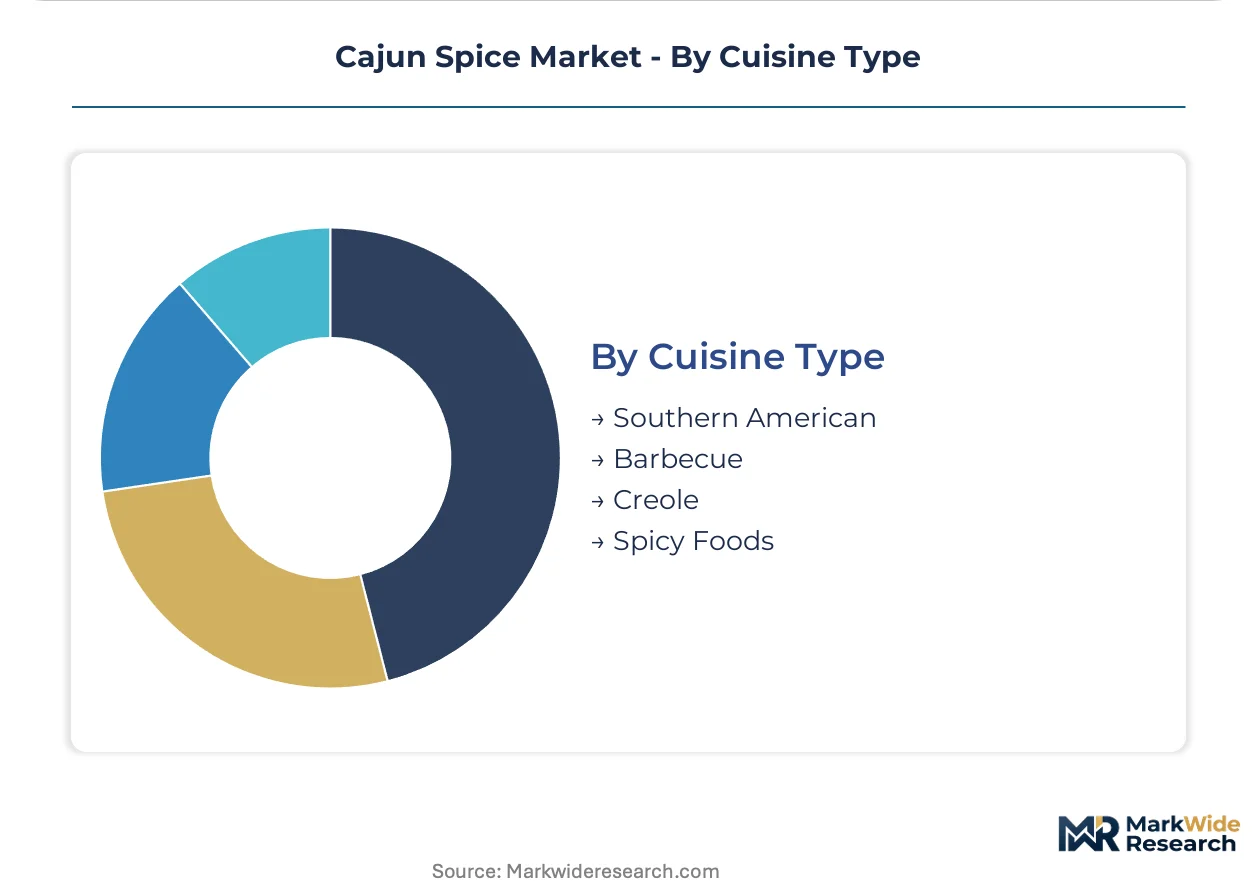
Cuisine Type:
Heritage positioning versus functional heat application creates divergent brand equity requirements across culinary contexts.
- Southern American:Louisiana and Texas regional cuisine heritage drives per-capita consumption rates above national averages through generational cooking tradition. FDA import alerts on Indian and Mexican pepper shipments create mycotoxin exposure risk that threatens supply continuity for heritage-positioned brands. Authenticity claims require documented provenance from Acadiana growing regions.
- Spicy Foods:Heat-seeking consumers prioritize capsaicin intensity over geographic origin, opening substitution vulnerability to generic paprika-cayenne mixtures. Industrial formulations achieve repeatable Scoville units through calibrated extraction that satisfies this specification-driven segment without heritage premium.
- Creole:New Orleans-specific culinary tradition demands distinct herb profiles including filé powder and distinct tomato-based preparations.
- Barbecue:Smoke-forward applications prioritize paprika sourcing over cayenne heat in rub formulations.
Brand equity defensibility concentrates in Southern American; price elasticity concentrates in Spicy Foods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of the Food Safety Modernization Act anchors supply chain configuration in the United States, where Louisiana and Texas concentrate per-capita consumption above national averages. Regional cuisine heritage drives demand clustering along the Gulf Coast.
United States
Texas and Louisiana generate the highest per-capita consumption rates through generational Southern American cooking traditions. FDA import alerts on Indian and Mexican pepper shipments trigger mycotoxin testing requirements that compress procurement timelines. The Acadiana region in Louisiana anchors artisanal cayenne cultivation expertise that unwinds previous supply bottlenecks.
Canada
Urban centers in Ontario and British Columbia show accelerating format switching between dry seasoning and wet sauce applications among younger consumers. Health Canada maintains parallel pathogen thresholds to FDA standards, creating streamlined compliance for US exporters. Montreal and Toronto specialty retail channels reward clean-label positioning with expanded shelf space.
Mexico
Chihuahua and Veracruz growing regions supply cayenne streams that face climate-driven harvest volatility disrupting contract fulfillment. Mexican agricultural regulators coordinate with FDA preventive controls mandates for cross-border pepper shipments. Guadalajara-based grinding facilities serve Latin-Cajun crossover manufacturing demand.
United Kingdom
London and Southeast England concentrate demand for premium-tier regional cuisine products through specialty import channels. EFSA mycotoxin standards align with FDA thresholds, reducing dual-compliance burdens for exporters. Birmingham foodservice distributors specify Scoville heat unit standardization for Southern American menu applications.
Germany
REACH compliance requirements tighten pesticide residue testing for imported spice extracts entering EU markets. Hamburg and Frankfurt distribution hubs compete for diverted premium pepper volumes from European export channels. German quick-service chains embed Cajun profiles into limited-time offerings calibrated to local heat tolerance thresholds.
Cajun Spice Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with family-recipe authenticity competing against manufacturing scale economies. Consolidation pressure intensifies as FDA compliance costs favor capitalized players with preventive controls infrastructure. Three archetypes dominate: vertically integrated procurement networks, family-recipe heritage brands, and Latin-Cajun crossover manufacturers. Competitive moves concentrate on calibrated heat-standardization services and direct-to-consumer channel expansion.
Within the integrated procurement tier, McCormick & Company, Inc. exemplifies scale-driven supply security through contracted grower relationships. Among heritage-positioned specialists, Slap Ya Mama occupies a position anchored in family-recipe authenticity and Gulf Coast independent grocer penetration. Badia Spices represents the crossover manufacturing archetype, leveraging shared grinding infrastructure across adjacent flavor categories.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| The Kraft Heinz Company |
| Fiesta Spices |
| Louisiana Fish Fry |
| The Food Source International, Inc. |
| Gel Spice Company, Inc. |
| Keya Foods International Pvt Ltd. |
| Slap Ya Mama |
| Badia Spices |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day pepper procurement lead times from Indian and Mexican growing regions concentrate pricing power among vertically integrated processors with captive cayenne contracts, while artisanal producers absorbing spot-market volatility struggle to defend premium positioning against commodity substitution.
Pricing Analysis
Texas-Louisiana wholesale spreads for calibrated heat-standardization services diverge sharply from Gulf Coast independent retail premiums. Three-tier pricing structure across USDA organic certified, conventional branded, and private-label economy levels reflects certification cost pass-through and brand-equity differentiation. Pricing pressure stems from generic paprika-cayenne mixtures capturing price-sensitive retail shelf space. Foodservice buyers exhibit lowest price sensitivity due to menu consistency requirements, while metropolitan home chefs show highest elasticity as format experimentation compresses loyalty cycles.
Supply Chain Analysis
Strategic stockpiling of Acadiana cayenne inventories dominates procurement strategy among heritage-positioned brands buffering climate-driven harvest volatility, while industrial processors favor just-in-time flows from contracted Indian and Mexican pepper streams. Raw material dependencies center on Chihuahua and Veracruz cayenne cultivation, Andhra Pradesh paprika drying, and Louisiana herb sourcing. Single-source vulnerability concentrates in cross-border pepper shipments facing FDA import alert triggers. Distribution runs through Gulf Coast specialty retail networks and Texas-Louisiana foodservice distributor hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cajun Sauce subscription and calibrated heat-standardization service contracts expand faster than dry seasoning hardware, creating attach-rate opportunities for recurring revenue layers in a market historically dominated by transactional spice sales.
For Market Incumbents: Compound defensive positioning through backward integration into Acadiana cayenne cultivation securing supply continuity against climate volatility, while investing in near-infrared spectroscopy capabilities to enforce raw material specifications that commodity substitutes cannot match. FDA preventive controls infrastructure serves as a moat against family-recipe competitors struggling to document consistent process controls for organic certification audits.
For New Entrants and Emerging Players: Direct-to-consumer cottage law pathways in Louisiana and Texas represent the most penetrable white-space, enabling farmers market penetration and subscription box channels with minimal regulatory burden. Target metropolitan home chefs treating Cajun profiles as modular components through social-native recipe content driving format switching between dry and wet applications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with under-monetized regional heritage brands lacking direct-to-consumer infrastructure. Long-term viability hinges on clean-label certification premiums sustaining through generational cooking tradition transfer. Monitor FDA import alert frequency on Indian and Mexican pepper shipments as inflection indicator for supply-cost compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acadiana Cultivation | Captive cayenne supply secures heritage authenticity claims against climate-driven harvest disruption. |
| Near-Infrared Spectroscopy Deployment | Capsaicin verification technology enforces incoming specifications that artisanal competitors cannot replicate. |
| Direct-to-Consumer Subscription Launch | Cottage law pathways bypass conventional retail slotting fees while capturing metropolitan format-switching behavior. |
| USDA Organic Certification Investment | Clean-label positioning commands specialty retail price premiums aligned with perceived authenticity demand. |
| Latin-Cajun Crossover Manufacturing Partnership | Shared grinding infrastructure achieves scale economies across adjacent flavor category demand pools. |
Study Parameters
A standing panel of foodservice procurement directors, specialty retail category buyers, Louisiana cottage food producers, and FDA compliance consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA import alert databases, USDA organic certification registries, customs trade flows, and foodservice distributor shipment records. Bottom-up volume modeling triangulated against top-down consumer expenditure benchmarks.
Consistency checks validated outputs against external trade data and regional consumption surveys across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-user sophistication, and cuisine heritage positioning. CAGRs derived from fitted growth curves incorporating climate volatility assumptions and regulatory compliance cost trajectories. Industry-specific inputs encompassed Scoville standardization service pricing and cottage law exemption utilization rates.
Underlying assumptions cover FDA enforcement continuity, Acadiana cultivation recovery patterns, and generational cuisine tradition transfer, with deviation risk concentrated in climate-driven harvest volatility and import alert frequency spikes. Revision becomes warranted when mycotoxin detection rates in Indian and Mexican pepper shipments cross thresholds triggering sustained detention patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Cinnamon Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Garlic Oil Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Herb Oil Market
Spices and Seasonings
Smoked Black Pepper Market
Spices and Seasonings
Ginger Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Glass Spice Jars Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Europe Seasoning and Spices Market
Spices and Seasonings
Fennel Powder Market
Spices and Seasonings
US Gourmet Salt Market
Spices and Seasonings
Middle East and Africa Food Micronized Salt Market
Spices and Seasonings
Sriracha Market
Spices and Seasonings
US Spice and Seasonings Market