
 White Pepper Market | 2026-2036
White Pepper Market Size, Share, and Industry Trends Forecast 2026-2036
White Pepper Market Outlook
Specialty spice distribution is rewriting procurement patterns across the White Pepper Market. Olam International leverages integrated sourcing networks from Vietnamese highlands to secure consistent supply for industrial buyers. Kerry Group anchors premium extraction contracts with pharmaceutical-grade specifications. McCormick & Company sustains retail dominance through controlled brand distribution in North American supermarkets.
White pepper consists of the dried seed of Piper nigrum L. after removal of the outer pericarp, containing piperine concentrations of 4-7% and volatile oil at 1-2.5%, primarily functioning as a pungency agent and flavor modifier in processed foods and medicinal formulations. Ground White Pepper occupies the largest volume share as institutional food manufacturers standardize on pre-milled formats for batch consistency. White Pepper Extract commands the fastest expansion as nutraceutical formulators substitute synthetic bioenhancers with natural piperine sources. Whole White Pepper retains niche positioning among artisanal processors and ethnic retail channels where visual quality verification drives selection.
FDA food additive regulations, EFSA pesticide maximum residue limits, and Vietnam's national good agricultural practice standards collectively constrain market access for uncertified producers. Compliance with these frameworks determines eligibility for pharmaceutical and cosmetic-grade extraction contracts. Stakeholders must monitor evolving organic certification reciprocity between Southeast Asian origin countries and European import authorities to anticipate supply reallocations.
Market Dynamics
Clean-label certification requirements from Vietnamese regulators and EFSA pesticide residue protocols are restructuring procurement flows toward certified organic estates, compressing margins for conventional suppliers while rewarding backward-integrated processors.
Growth Catalysts
- EFSA MRL harmonization:Aligned European pesticide limits reduce testing duplication for Vietnamese exporters, accelerating contract finalization with flavor houses in Germany and the Netherlands.
- Pharmaceutical-grade piperine demand:Nutraceutical formulators in North America substitute synthetic bioenhancers with natural white pepper extract, pulling volume through certified extraction channels.
- Lampung cluster concentration:Indonesia's premium-grade specialization attracts long-term supply agreements from European cosmetic manufacturers seeking consistent volatile oil profiles.
Market Restraints
- Input cost volatility:Fertilizer price fluctuations in Vietnamese highlands directly affect farmgate pepper pricing, compressing processor margins during contract renegotiations.
- Supply concentration risk:Vietnam's Binh Phuoc and Dak Lak provinces generate over sixty percent of exportable white pepper, creating weather-dependent volume vulnerability.
- Synthetic piperine substitution:Laboratory-derived bioenhancers from Chinese chemical manufacturers undercut natural extract pricing in cost-sensitive pharmaceutical applications.
Strategic Opportunities
- Organic certification arbitrage:Vietnamese estates pursuing EU organic equivalence can capture premium spreads currently commanded by Indonesian suppliers.
- Direct-to-manufacturer platforms:Blockchain-traceable procurement portals eliminate traditional spice broker layers, enabling price transparency for institutional food manufacturers.
- Cosmetic-grade extraction:Volatile oil specifications for fragrance applications remain underserved relative to food-grade demand, offering margin expansion for specialized processors.
Industry Challenges
- Skilled agronomist scarcity:Integrated pest management expertise required for EFSA-compliant cultivation outpaces training program output in Vietnamese provinces.
- Multi-standard certification timelines:Simultaneous USDA Organic, EU Organic, and Rainforest Alliance audits extend product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Pepper Market |
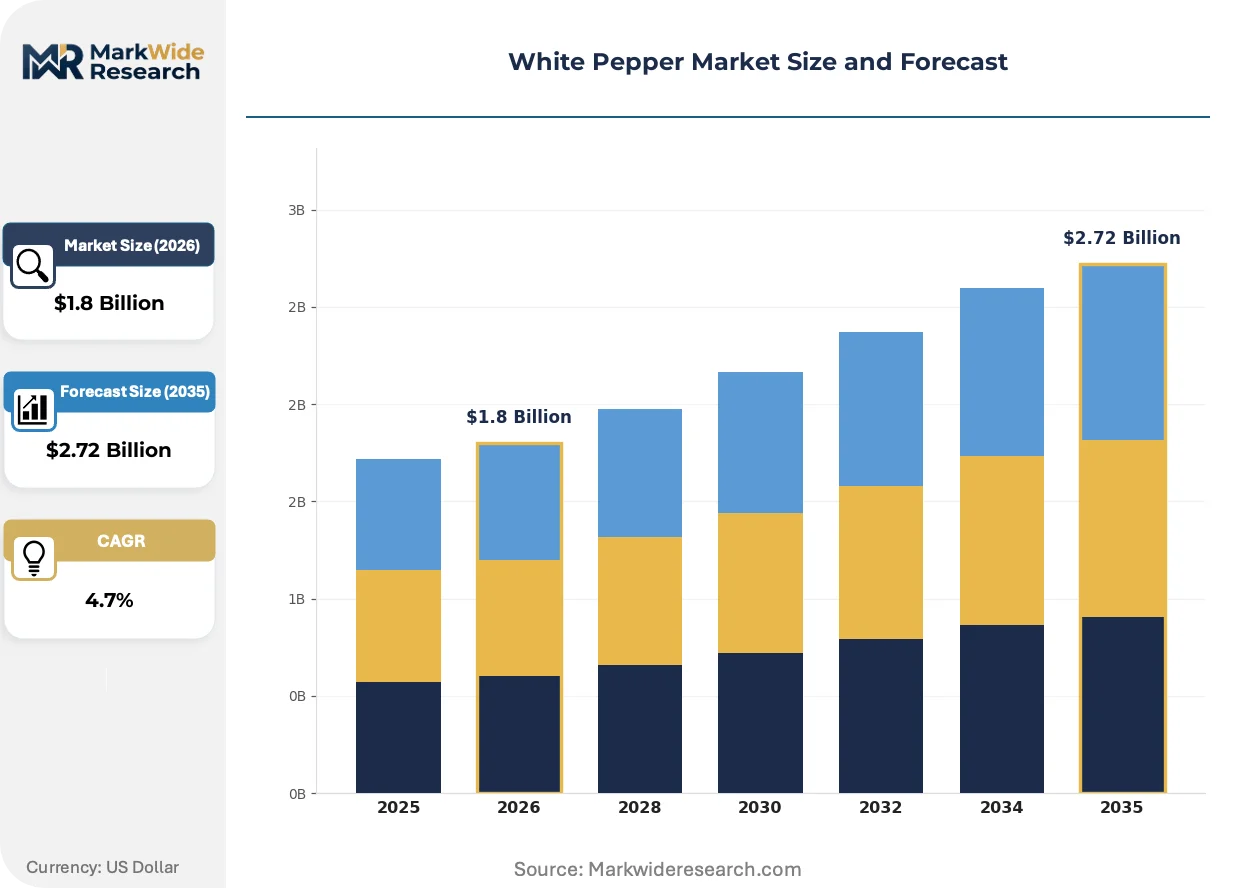
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground White Pepper, Whole White Pepper, White Pepper Extract, White Pepper Oil End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Packaging Type: Bags, Jars, Tins, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Food Service, Specialty Stores |
| Companies Covered | McCormick & Company, Olam International, Kerry Group, Ajinomoto, MDH Spices, The British Pepper & Spice Company Limited, Akay Spices, Maxrotth Global Foods, Fuchs Gruppe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Pepper Market Strategic Shifts
Processing technology and traceability systems are compressing traditional value chain layers while regulatory data requirements reshape supplier qualification protocols across Southeast Asian origin markets.
Steam-assisted pericarp removal systems are rendering obsolete sun-bleaching methods that required extended drying periods and exposed berries to contamination risks. Industrial processors in Vietnam's Central Highlands adopt these closed-loop units to meet pharmaceutical-grade hygiene specifications. The technology is rendering obsolete the seasonal production bottlenecks that previously constrained year-round extract supply.
REACH-compliant contaminant testing protocols now mandate expanded analyte panels for imported spice extracts entering European cosmetic formulations. German flavor houses and French fragrance manufacturers demand batch-level chromatography documentation. Specialty distributors respond by embedding certified laboratories within Vietnamese processing facilities, collapsing third-party verification timelines from weeks to days.
Long-term offtake contracts with fixed price bands displace spot-market purchasing among North American institutional food manufacturers. Kraft Heinz and McCormick procurement teams negotiate three-year supply agreements directly with Lampung and Binh Phuoc estates, bypassing traditional Amsterdam and Singapore trading houses. This pattern concentrates most visibly in condiment and ready-meal manufacturing verticals where input cost predictability outweighs price optimization.
White Pepper Market Segmentation
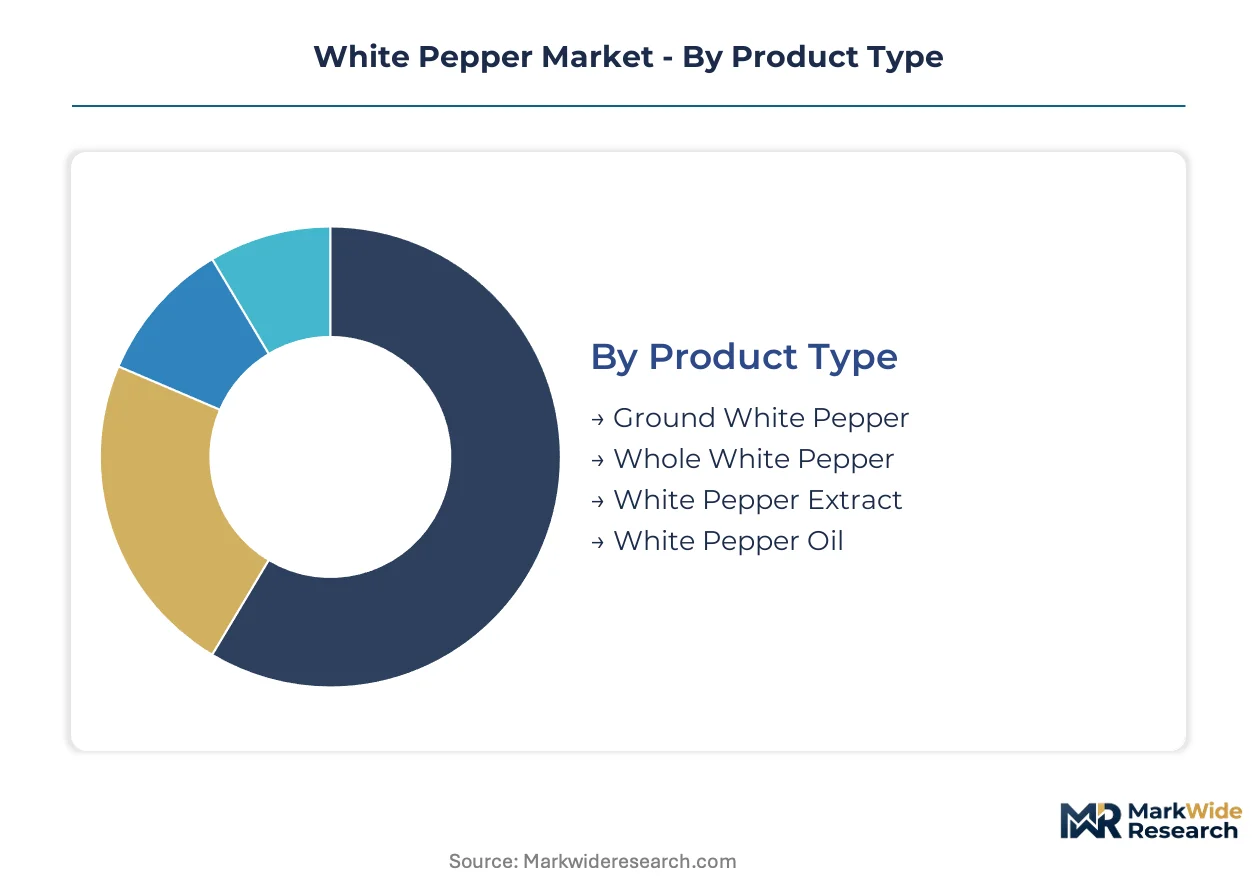
White pepper segmentation reflects divergent processing requirements across food-grade, pharmaceutical-grade, and cosmetic-grade supply chains. Each product format commands distinct certification standards, extraction protocols, and customer qualification timelines that reshape procurement economics.
Product Type:
Industrial buyers select formats based on batch consistency needs, extraction yield targets, and end-use regulatory thresholds.
- Ground White Pepper:Pre-milled powder with standardized particle size distribution ensures uniform pungency dispersion in processed foods. Institutional manufacturers in Vietnam and Indonesia standardize procurement on this format to eliminate in-house milling variability and reduce contamination exposure during handling.
- White Pepper Extract:Concentrated piperine isolates meeting pharmaceutical-grade specifications serve nutraceutical formulators replacing synthetic bioenhancers. North American supplement manufacturers drive contract volume through certified extraction channels with batch-level chromatography documentation.
- Whole White Pepper:Intact berries enable visual quality verification for artisanal processors and ethnic retail channels where pericarp removal completeness indicates grade authenticity.
- White Pepper Oil:Volatile oil fractions supply fragrance applications in European cosmetic manufacturing, with Lampung-sourced material commanding premium positioning for consistent terpene profiles.
Established volume favors Ground White Pepper; emerging adoption favors White Pepper Extract.
End Use Industry:
Regulatory stringency escalates across the value chain from food additive to active pharmaceutical ingredient classifications.
- Food & Beverage:Clean-label spice demand from Southeast Asian processors drives volume procurement of certified organic grades. EFSA pesticide residue protocols and Vietnam's tightened export standards redirect sourcing toward backward-integrated estates with integrated pest management documentation.
- Pharmaceuticals:Piperine bioenhancer applications in drug formulation require USP-grade material with validated extraction methods. FDA food additive regulations and EMA pharmaceutical guidelines constrain market access to processors with certified laboratory infrastructure.
- Cosmetics:Fragrance and topical applications leverage volatile oil specifications underserved relative to food-grade demand. REACH-compliant contaminant testing mandates expanded analyte panels for European market entry.
- Nutraceuticals:Natural bioenhancer substitution trends pull volume through certified channels as formulators reject synthetic alternatives. Fixed-price offtake contracts displace spot purchasing among North American manufacturers seeking input cost predictability.
Food & Beverage anchors procurement tonnage; Pharmaceuticals commands margin expansion.
Packaging Type:
Packaging selection tracks customer scale, shelf-life requirements, and handling automation compatibility across institutional and retail channels.
- Bulk Packaging:Industrial totes and fiber drums serve food manufacturers with automated batching systems, minimizing unit handling costs for high-volume condiment and ready-meal producers negotiating direct estate contracts.
- Bags:Flexible laminated pouches balance moisture protection with freight efficiency for mid-scale processors lacking bulk handling infrastructure.
- Jars:Glass containers with tamper-evident closures target retail spice aisles where visual premium positioning supports price differentiation.
- Tins:Metal canisters preserve volatile oil integrity for specialty distribution in European gourmet channels with extended distribution timelines.
Procurement scale determines format selection; shelf-life sensitivity elevates tin and jar premiums.
Distribution Channel:
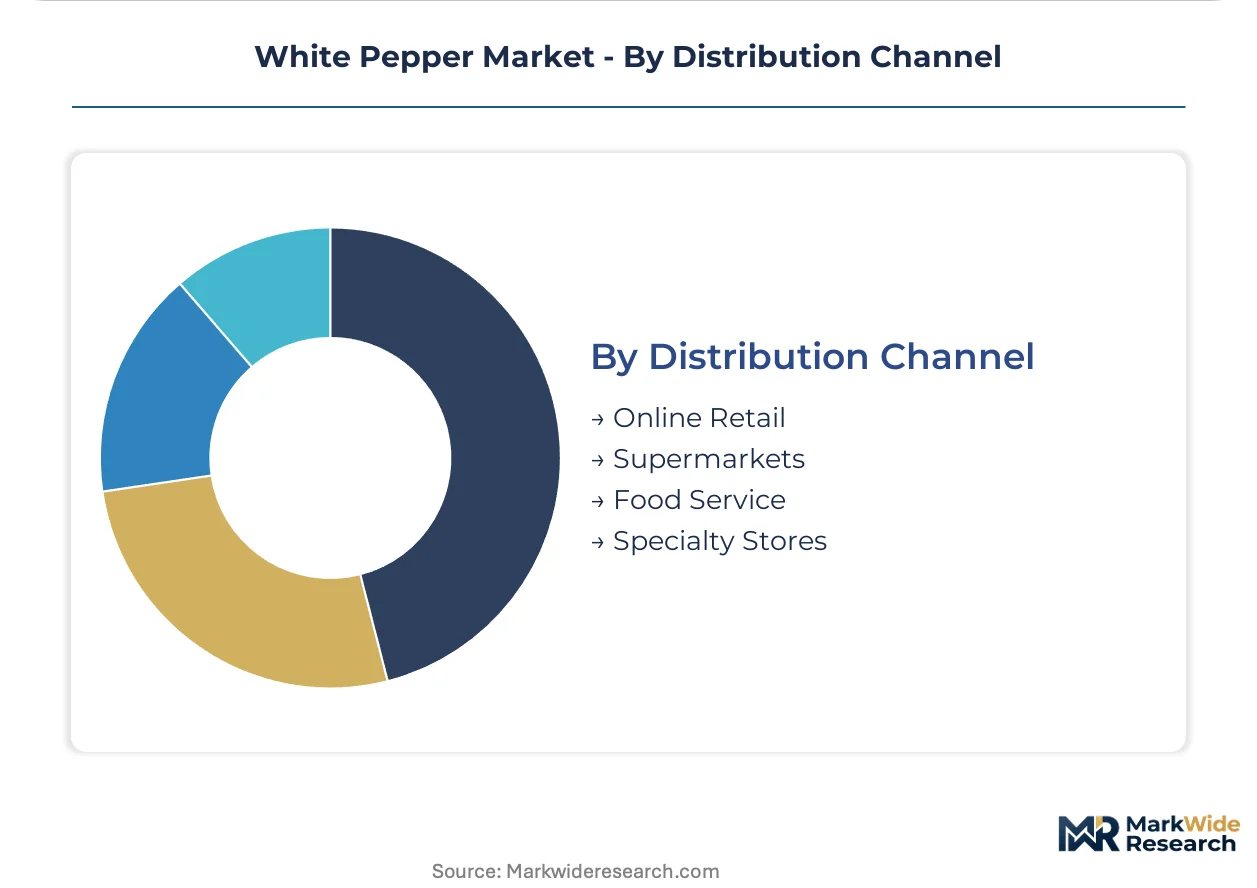
Channel structure reflects customer technical qualification requirements and traceability documentation needs.
- Food Service:Institutional procurement teams negotiate directly with Vietnamese and Indonesian estates, bypassing traditional Amsterdam and Singapore trading houses for three-year supply agreements with fixed price bands.
- Supermarkets:Controlled brand distribution dominates North American retail with standardized packaging formats and consolidated supplier audits reducing qualification overhead.
- Specialty Stores:Ethnic retail and gourmet channels source whole berry grades with origin verification, serving artisanal processors requiring visual quality assessment.
- Online Retail:Blockchain-traceable procurement portals emerge for small-batch buyers seeking price transparency and direct estate relationships outside traditional broker networks.
Direct contracting concentrates in Food Service; traceability innovation expands fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese exporters command premium spreads over Indonesian suppliers under EFSA-aligned protocols, while North American nutraceutical manufacturers source through certified extraction channels at fixed-price premiums.
Vietnam
Clean-label procurement from Southeast Asian food processors drives certified organic volume through Binh Phuoc and Dak Lak estates. The Ministry of Agriculture and Rural Development tightened pesticide residue protocols for pepper exports, redirecting sourcing toward backward-integrated processors with integrated pest management documentation. Central Highlands processors adopt steam-assisted pericarp removal systems to meet pharmaceutical-grade hygiene specifications.
Indonesia
European cosmetic manufacturers seek consistent volatile oil profiles from Lampung-sourced material for fragrance applications. The country's national agricultural standards authority maintains export quality protocols that align with REACH-compliant contaminant testing for European market entry. Lampung province concentrates premium-grade output, drawing long-term supply agreements from French fragrance manufacturers and German flavor houses.
United States
FDA food additive regulations constrain market access for uncertified producers while nutraceutical formulators substitute synthetic bioenhancers with natural piperine sources. McCormick procurement teams negotiate direct estate contracts with fixed price bands, bypassing traditional Amsterdam and Singapore trading houses. North American institutional food manufacturers prioritize input cost predictability in condiment and ready-meal manufacturing verticals.
Germany
REACH mandates expanded analyte panels for imported spice extracts entering European cosmetic formulations, requiring batch-level chromatography documentation. German flavor houses demand embedded certified laboratories within Vietnamese processing facilities to collapse third-party verification timelines. The Netherlands serves as a secondary distribution hub for German manufacturers seeking EFSA MRL harmonization benefits.
India
Domestic spice processors supply regional food service channels while export-oriented units target pharmaceutical-grade extraction contracts. FSSAI food safety standards and BIS quality protocols govern domestic distribution, with select estates pursuing EU organic equivalence certification. Kerala and Karnataka clusters specialize in whole berry grades for ethnic retail channels across the Middle East.
White Pepper Market Competitive Environment
Integrated sourcing networks and controlled brand distribution split the market between upstream estate controllers and downstream retail anchors. The vendor base concentrates around three strategic archetypes: backward-integrated processors with captive supply chains, specialty extraction houses serving pharmaceutical specifications, and retail brand owners with supermarket distribution dominance. Competitive moves center on direct-to-manufacturer contracting platforms and blockchain-traceable procurement portals that eliminate traditional spice broker layers.
Within the integrated sourcing tier, Olam International and Kerry Group exemplify contrasting geographic emphases—Singapore-based estate networks versus Irish-headquartered extraction specialization. McCormick & Company anchors North American retail dominance through controlled brand distribution. These three entities represent the dominant competitive vectors: upstream supply security, pharmaceutical-grade processing capability, and consumer-facing shelf presence.
| Leading Market Players |
|---|
| McCormick & Company |
| Olam International |
| Kerry Group |
| Ajinomoto |
| MDH Spices |
| The British Pepper & Spice Company Limited |
| Akay Spices |
| Maxrotth Global Foods |
| Fuchs Gruppe |
| Others |
Value Chain & Pricing Dynamics
Binh Phuoc province's certified organic estates command premium spreads over conventional Lampung suppliers as EFSA-aligned protocols compress margins for uncertified growers. The concentration of exportable white pepper in Vietnam's Central Highlands and Indonesia's Lampung cluster concentrates pricing power among backward-integrated processors with integrated pest management documentation.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade extract contracts from standard food-grade ground pepper procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with organic equivalence commanding the widest spreads. Price differentiation hinges on batch-level chromatography documentation for European cosmetic manufacturers. Cost compression in conventional grades is intensifying because Chinese synthetic piperine alternatives undercut natural extract pricing. Institutional food manufacturers exhibit the lowest price sensitivity due to fixed-price offtake contracts, while spot-market buyers in ethnic retail channels face the highest volatility exposure.
Supply Chain Analysis
Extended payment terms from European flavor houses and supply-chain finance facilities from Singapore trading platforms lubricate working capital for Vietnamese processors. Geographic supply concentrates in Vietnam, Indonesia, and India, with Binh Phuoc and Dak Lak provinces generating the dominant exportable volume. Raw material dependencies rest on fertilizer inputs for highland cultivation, sulfur for steam-assisted pericarp removal, and laboratory reagents for contaminant testing protocols. Single-source vulnerability from weather-dependent production in Vietnam's monsoon belt creates volume risk during contract renegotiations. Distribution runs through direct-to-manufacturer contracting platforms that displace traditional Amsterdam and Singapore spice broker layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label certification requirements and steam-assisted processing technology are disrupting procurement patterns across the white pepper value chain. EFSA MRL harmonization creates regulatory arbitrage opportunities for compliant Vietnamese estates.
For Market Incumbents: Entrench supply security through captive estate partnerships in Binh Phuoc and backward integration into steam-assisted processing infrastructure. Synthetic piperine substitution from Chinese chemical manufacturers threatens natural extract margins; defend through pharmaceutical-grade certification investment and long-term offtake contracts with fixed price bands that lock in institutional food manufacturer volume. For New Entrants and Emerging Players: Pursue cosmetic-grade extraction white space where volatile oil specifications for fragrance applications remain underserved relative to food-grade demand. The most penetrable segment sits with European fragrance manufacturers seeking REACH-compliant Lampung-sourced material with consistent terpene profiles. A blockchain-traceable procurement portal go-to-market angle eliminates traditional broker layers and captures price transparency premiums from small-batch buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty extraction houses with certified laboratory infrastructure and pharmaceutical-grade piperine capabilities. Long-term viability over a five-to-ten-year window rests on regulatory compliance moats rather than commodity volume scale. Acquisition targets should display embedded chromatography documentation capabilities and EU organic equivalence certification. The signal to watch is reciprocity agreements between Vietnamese origin authorities and European import regulators that would accelerate certified organic estate valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Estates | Captive supply from Binh Phuoc organic estates secures EFSA-compliant export eligibility. |
| Steam-Assisted Processing Scale-Up | Closed-loop pericarp removal meets pharmaceutical-grade hygiene specifications for extract contracts. |
| Blockchain Traceability Platform Launch | Direct-to-manufacturer portals collapse traditional Amsterdam and Singapore broker margins. |
| Cosmetic-Grade Extraction Specialization | Volatile oil fractions for fragrance applications command premium spreads over food-grade demand. |
| EU Organic Equivalence Certification | Vietnamese estates capture premium positioning currently commanded by Indonesian suppliers. |
Study Parameters
The analysis maps ground white pepper, extract, whole berry, and volatile oil fractions, each validated through estate managers, processing facility technical directors, and European flavor house procurement leads. Primary interviews with Vietnamese Ministry of Agriculture officials, Indonesian agricultural standards authority representatives, and North American nutraceutical formulators combined with secondary validation from FDA food additive regulations, EFSA pesticide residue databases, and Vietnam export customs records. Bottom-up estate capacity surveys triangulate against top-down import volume data from German and Dutch trade statistics.
Assumptions held fixed include EFSA MRL harmonization continuity, steam-assisted processing adoption curves, and organic certification reciprocity timelines between Southeast Asian origins and European import authorities. The analytical framework models product type, end-use industry, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by pharmaceutical-grade premium realization rates and cosmetic-grade volatile oil yield coefficients.
Macroeconomic conditions sit as an overlay; deviation in fertilizer input costs, freight rate volatility, or European regulatory stringency would shift the trajectory. Forecasts reflect documented assumptions about certification timeline compression and technology adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Savoury Seasoning Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
North American Seasonings and Spices Market
Spices and Seasonings
Tamarind Extract Market
Spices and Seasonings
Turmeric Oleoresin Market
Spices and Seasonings
Ginger Oil Market
Spices and Seasonings
Africa Spice and Herb Extracts Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Achiote Powder Market
Spices and Seasonings
Malaysia Spices and Seasonings Market
Spices and Seasonings
Dried Herbs Market