
 Seasonings Market | 2026-2036
Seasonings Market Size, Share, and Industry Trends Forecast 2026-2036
Seasonings Market Analysis
The gap between premium single-origin spice lines and mass-market commodity blends is broadening across retail and food service channels. McCormick & Company leverages its R&D intensity to sustain innovation in clean-label blends. Kerry Group anchors its position through vertical integration into savory taste systems for food manufacturers. Ajinomoto Co. competes in umami-based seasonings with specialized fermentation technology.
Seasonings encompass dried and processed plant-derived flavoring materials, including ground spices, dried herbs, compounded blends, and liquid condiments, typically standardized for volatile oil content, moisture levels below 12%, and particle size distribution to ensure shelf stability and flavor consistency in industrial applications. Their primary commercial purpose centers on enhancing sensory profiles, masking off-notes in reduced-sodium formulations, and enabling product differentiation across packaged food portfolios. Blends command the deepest margin pools due to formulation complexity and customer stickiness, while organic ingredient source segments outpace conventional growth as retailers enforce stricter procurement protocols. Food service application channels are expanding fastest, driven by chain restaurant demand for consistent, scalable flavor systems.
FDA food labeling rules, USDA National Organic Program standards, and EPA agricultural chemical residue limits collectively shape raw material eligibility, processing claims, and import access for seasonings sold in the United States. These frameworks elevate compliance costs for smaller suppliers while creating preferential pathways for certified organic and GRAS-affirmed ingredient portfolios. Stakeholders must monitor evolving state-level packaging waste regulations and carbon disclosure requirements that will soon filter into retailer sourcing scorecards.
Market Dynamics
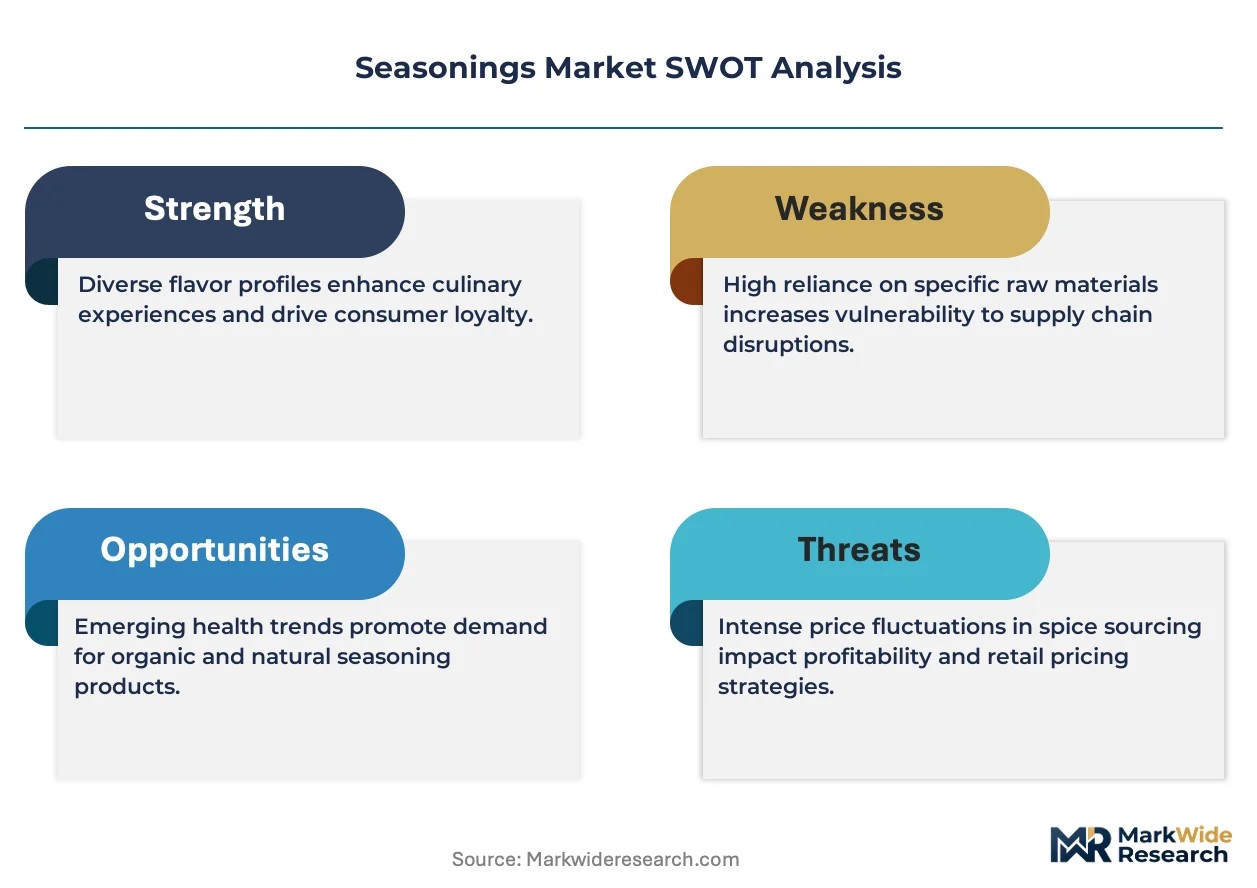
Clean-label mandates from food processing buyers are compressing formulation cycles and forcing suppliers to rebuild supply chains around certified organic inputs, with USDA National Organic Program compliance now a baseline qualification for shelf placement at major retailers.
Growth Catalysts
- USDA National Organic Program:Certification requirements are locking in long-term contracts between seasoning blenders and certified organic spice growers, creating captive supply relationships that stabilize input quality.
- Reduced-sodium formulation demand:Food manufacturers deploy umami-enhancing seasoning systems to mask salt reduction off-notes in packaged soups, snacks, and ready meals without reformulating base recipes.
- India:The country's dominance in turmeric, cumin, and chili processing is attracting multinational seasoning houses to establish direct sourcing operations and regional R&D facilities.
Market Restraints
- Climate volatility:Erratic monsoon patterns in Kerala and Karnataka are disrupting cardamom and black pepper harvests, forcing blenders to carry 40-60 day inventory buffers.
- Input cost concentration:Vanilla extract and saffron remain concentrated in Madagascar and Iran respectively, exposing premium blend margins to geopolitical supply interruptions.
- Technical limitation:Natural color stability in turmeric-based seasonings degrades under UV exposure, limiting clean-label applications in transparent packaging formats.
Strategic Opportunities
- Sub-Saharan Africa:Underdeveloped local blending capacity creates openings for exporters of standardized savory taste systems to emerging quick-service restaurant chains.
- EU Green Deal:Carbon border adjustment mechanisms will favor seasoning suppliers with verified Scope 3 emissions data from agricultural inputs.
- Fermentation-derived flavor precursors:Convergence of precision fermentation and enzymatic extraction is enabling novel umami compounds that bypass traditional soy sauce and yeast extract supply chains.
Industry Challenges
- Sensory science talent scarcity:Formulators with dual expertise in volatile oil chemistry and industrial scale-up are concentrated among a handful of legacy suppliers.
- Organic certification timelines:FSSAI in India and FDA in the United States operate non-harmonized audit schedules, forcing exporters to maintain parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seasonings Market |
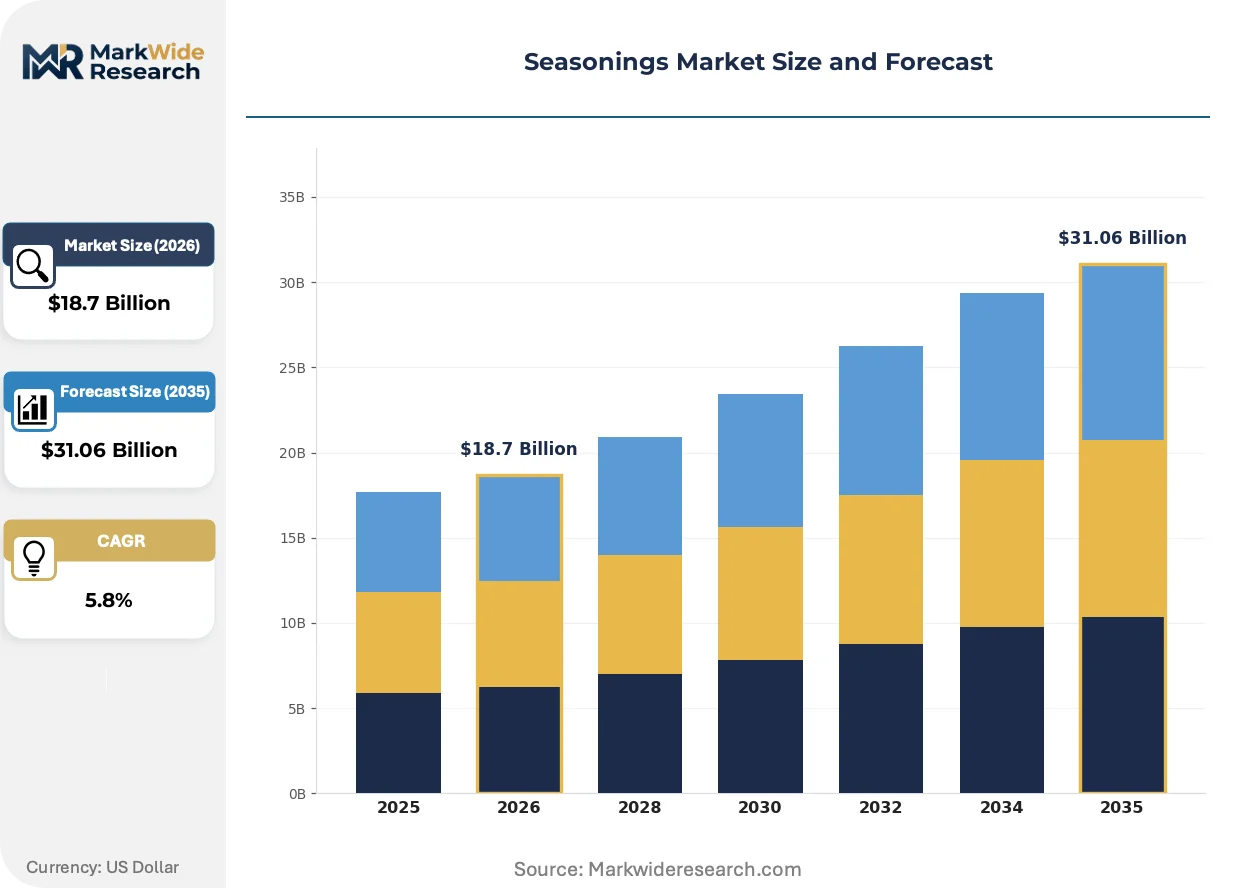
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spices, Herbs, Blends, Condiments Application: Food Processing, Retail, Food Service, Home Cooking Ingredient Source: Natural, Synthetic, Organic, Conventional Packaging Type: Bottles, Pouches, Tubs, Bulk |
| Companies Covered | McCormick & Company, Olam International, Ajinomoto Co., Kerry Group, Cargill Incorporated, Associated British Foods, Sensient Technologies, Kraft Heinz, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seasonings Market Emerging Trajectories
Digital traceability infrastructure and biotechnology-derived flavor building blocks are displacing conventional extraction and compounding methods across the seasoning value chain.
Precision fermentation platforms for producing natural flavor molecules is modularizing the upstream supply structure. Ingredient houses in the Netherlands and California are commissioning pilot facilities to generate capsaicin analogs and pyrazine compounds without agricultural cultivation. Food manufacturers are qualifying these inputs at 18-24 month cycles, compressing the traditional 5-7 year botanical sourcing relationships that previously locked in supplier positions.
REACH authorization requirements for residual solvent limits in oleoresin extracts are tightening purity specifications for EU-bound seasonings. EFSA evaluations of novel extraction methods are extending approval timelines for supercritical CO2 processes. Blenders serving European retail private-label accounts are consolidating supplier bases to pre-qualified facilities with existing REACH dossiers.
Chain restaurant procurement teams are consolidating flavor system vendors to reduce kitchen complexity and audit burden. Multi-unit operators in the United States are replacing 8-12 regional spice suppliers with 2-3 national seasoning houses capable of delivering identical sensory profiles across 500+ locations. This concentration is most visible in the fast-casual segment, where menu standardization takes priority over local ingredient provenance.
Seasonings Market Segmentation
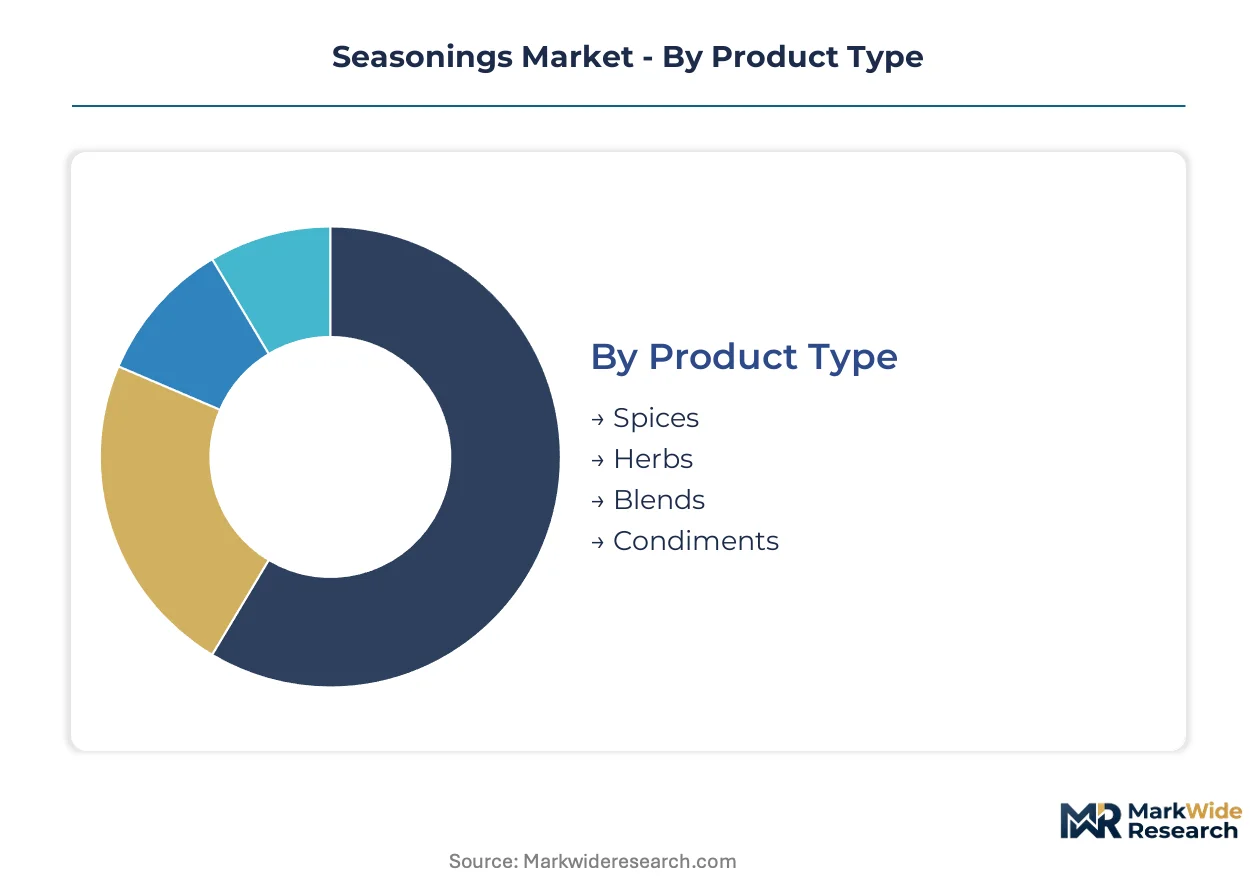
Segmentation in seasonings reveals how formulation complexity and procurement protocols create divergent margin pools. Suppliers configure production assets and certification pathways around distinct demand profiles rather than treating flavor inputs as interchangeable commodities.
Product Type:
Supply concentration varies sharply across product types, with volatile oil extraction and compounding capabilities determining which suppliers capture premium positions.
- Spices:Single-origin ground spices require standardized volatile oil content and particle size distribution for industrial consistency. Kerala and Karnataka in India concentrate cardamom and black pepper processing, though climate volatility now forces blenders to carry extended inventory buffers against harvest disruptions.
- Blends:Compounded seasoning systems combine multiple spice bases with salt carriers, anti-caking agents, and flavor enhancers in precise ratios. Food manufacturers in the United States and Europe lock in multi-year contracts with blenders capable of delivering identical sensory profiles across 500+ production locations, creating substantial customer stickiness.
- Herbs:Dried herb specifications center on moisture content below 10% and color retention metrics. Mediterranean basin suppliers dominate oregano and thyme sourcing.
- Condiments:Liquid and paste formats include soy sauce derivatives, hot sauces, and vinegar-based preparations. Fermentation capacity constraints limit qualified suppliers.
Today's leader: Blends. Tomorrow's challenger: Spices.
Application:
End-use channels impose fundamentally different technical requirements, from retail shelf stability to food service scalability.
- Food Processing:Industrial buyers demand batch-to-batch consistency for soups, snacks, and ready meals. Clean-label mandates from major packaged food manufacturers in the United States and Europe now require USDA National Organic Program or equivalent EU organic certification as baseline qualification, compressing supplier pools to certified blenders.
- Food Service:Chain restaurant procurement teams consolidate vendor bases to reduce kitchen complexity and audit burden. Quick-service operators in the United States specifically prioritize standardized savory taste systems that eliminate variation across hundreds of locations.
- Retail:Supermarket and specialty store channels emphasize packaging differentiation and origin storytelling for premium positioning.
- Home Cooking:Direct-to-consumer seasonings compete on convenience formats and recipe-specific positioning.
Food service channels are climbing the fastest as chain restaurant expansion outpaces retail footprint growth.
Ingredient Source:
Certification tier determines raw material eligibility and pricing architecture across all downstream applications.
- Organic:USDA National Organic Program compliance requires third-party verification of agricultural inputs, processing aids, and handling protocols. Major retailers in the United States now enforce organic certification as mandatory for shelf placement, locking blenders into long-term contracts with certified spice growers in India and Latin America.
- Natural:Plant-derived ingredients without synthetic additives satisfy clean-label positioning at mid-tier price points. EFSA evaluations of novel extraction methods extend approval timelines for supercritical CO2 processes in Europe.
- Conventional:Standard agricultural inputs without certification face margin compression as procurement protocols tighten.
- Synthetic:Laboratory-derived flavor compounds serve cost-sensitive applications where natural positioning is not required.
Organic commands the steepest expansion trajectory as retailer enforcement hardens.
Packaging Type:
Format selection interacts with product stability requirements and distribution economics.
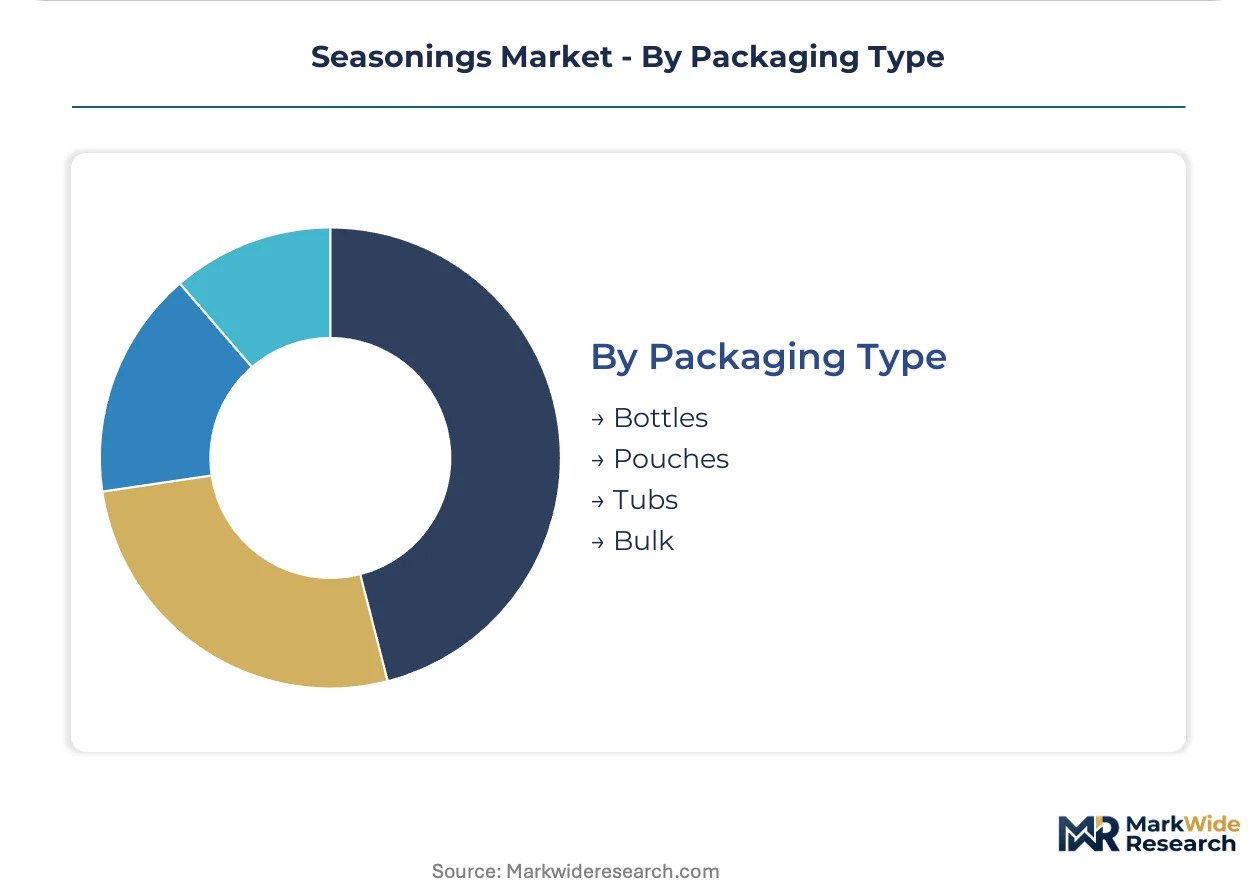
- Pouches:Flexible film structures dominate food service and industrial channels, offering cost efficiency and reduced shipping cube. Technical limitations around natural color stability in turmeric-based seasonings constrain transparent pouch applications due to UV degradation.
- Bottles:Rigid containers with moisture barriers protect volatile oil integrity in retail environments. Glass and high-barrier plastics command premium positioning.
- Bulk:Industrial totes and drums serve food processing volumes with minimal unit packaging cost.
- Tubs:Wide-mouth containers facilitate scoop access for food service and institutional kitchens.
Pouches hold current volume leadership. Bottles are gaining share fastest as premium retail positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes more turmeric and cumin than any other nation, while the United States drives premium blend consumption through chain restaurant procurement. Germany anchors European savory taste system demand, with Japan and Brazil completing the major consumption clusters.
United States
Chain restaurant procurement teams consolidate vendor bases to reduce kitchen complexity across 500-plus locations. FDA food labeling rules and USDA National Organic Program standards elevate compliance costs for smaller suppliers. Chicago and New Jersey host major seasoning blending facilities serving national food service distributors.
Germany
Industrial buyers demand batch-to-batch consistency for packaged soups and ready meals. REACH authorization requirements for residual solvent limits in oleoresin extracts tighten purity specifications. Hamburg concentrates import handling for spice-derived raw materials entering the EU market.
India
Kerala and Karnataka dominate cardamom and black pepper processing despite erratic monsoon disruptions. FSSAI organic certification timelines operate on non-harmonized schedules with FDA, forcing parallel documentation. Mumbai and Gujarat host regional R&D facilities established by multinational seasoning houses.
Japan
Food manufacturers deploy umami-enhancing seasoning systems to mask salt reduction off-notes in packaged applications. METI oversees fermentation technology standards for specialized savory compounds. Kanto region anchors precision fermentation pilot facilities for novel flavor molecules.
Brazil
Quick-service restaurant chains drive demand for standardized savory taste systems as they expand national footprints. ANVISA regulates agricultural chemical residue limits for imported spice inputs. São Paulo state concentrates domestic blending capacity serving Latin American food service channels.
Seasonings Market Vendor Landscape
Top-tier vendors anchor multinational food service contracts, while mid-tier blenders compete on regional organic certification and specialized fermentation capabilities. The structure stratifies across three tiers: integrated taste system houses, certified organic specialists, and commodity spice traders. Strategic archetypes include backward-integrated agricultural operators, precision fermentation technology licensors, and private-label retail suppliers. Competitive moves center on captive supply relationships with certified organic growers and consolidation of flavor system vendors to reduce audit burden.
Among the named players, McCormick & Company and Kerry Group exemplify the integrated taste system archetype, occupying positions that span R&D intensity through food manufacturer channel access. Ajinomoto Co. represents the fermentation-technology specialization tier, anchoring umami-based seasoning capabilities. These three entities sit within the premium competitive tier where formulation complexity and customer stickiness defend margin pools.
| Leading Market Players |
|---|
| McCormick & Company |
| Olam International |
| Ajinomoto Co. |
| Kerry Group |
| Cargill Incorporated |
| Associated British Foods |
| Sensient Technologies |
| Kraft Heinz |
| DSM-Firmenich |
| Others |
Supply Flow & Price Mechanics
Family-owned spice trading houses in Kerala and Gujarat anchor upstream supply, their generational grower relationships translating into preferential offtake terms that cushion margin compression when commodity volatility strikes downstream blenders. This ownership pattern concentrates pricing power among established processors while forcing newer entrants to absorb spot-market premiums or invest years building parallel certification pathways.
Pricing Analysis
The bundled-vs-unbundled service split separates commodity spice traders from integrated seasoning houses. Transactional spot pricing dominates conventional turmeric and cumin grades, while contract-based long-term offtake locks in organic-certified volumes at 15-25% premiums. Price differentiation hinges on USDA National Organic Program certification tier and volume scale commitments. Cost compression in mid-tier conventional blends is intensifying because Indian export processors are consolidating capacity. Quick-service restaurant chains exhibit highest price sensitivity due to menu cost controls, while premium retail private-label buyers prioritize consistency over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated food manufacturers mandate multi-supplier qualification for critical inputs. Geographic supply concentration centers on India for turmeric, cumin, and chili processing, Madagascar for vanilla extract, and Iran for saffron threads. Raw material dependencies include volatile oil-bearing spices, fermentation-derived yeast extracts, and salt carriers with anti-caking specifications. Single-source vulnerability in Madagascar vanilla exposes premium blend margins to cyclone disruption. Distribution runs through regional blending facilities in Chicago, New Jersey, and Hamburg serving food service and industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seasonings market functions as a stable compounder, with clean-label procurement mandates from major retailers generating predictable contract renewal cycles that underpin steady revenue visibility.
For Market Incumbents: Extend captive supply relationships with certified organic growers in Karnataka and Latin America to preempt input competition from emerging fermentation-based flavor houses. Deepen backward integration into volatile oil extraction capabilities to defend margin position against precision fermentation substitutes. Prioritize FSSAI-FDA harmonization investments to reduce parallel audit burdens that erode administrative efficiency. For New Entrants and Emerging Players: Quick-service restaurant chains in Sub-Saharan Africa represent the most penetrable channel, their vendor consolidation creating openings for exporters of standardized savory taste systems. Target underdeveloped local blending capacity in Nigeria and Kenya with turnkey formulation packages. Pursue co-manufacturing partnerships with established Indian processors to bypass multi-year organic certification timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier certified organic specialists with regional FSSAI approvals but limited multinational food service contracts. The five-to-ten year viability window favors blenders with demonstrated REACH dossier management and Scope 3 emissions tracking infrastructure. Watch for inflection when carbon border adjustment mechanisms in the EU Green Deal begin filtering into retailer sourcing scorecards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Spice Cultivation | Captive supply from certified growers in Kerala locks in USDA National Organic Program compliance for major retail accounts. |
| Precision Fermentation Platform Investment | Novel capsaicin analogs from Dutch and California pilot facilities bypass traditional agricultural cultivation cycles. |
| REACH Dossier Consolidation | Pre-qualified oleoresin extraction facilities reduce EFSA approval timelines for EU-bound private-label seasonings. |
| Food Service Vendor Consolidation | Multi-unit operators replace regional spice suppliers with national houses capable of 500-location sensory consistency. |
| Carbon Border Adjustment Preparation | Verified Scope 3 emissions data from Indian agricultural inputs secures preferential positioning under EU Green Deal mechanisms. |
Methodological Framework
Coverage spans the United States, Germany, India, Japan, and Brazil, with primary inputs from each market informing cross-regional pattern identification. The approach combines structured interviews with procurement directors at multinational food manufacturers, flavor chemists at integrated seasoning houses, and regulatory affairs leads navigating FSSAI-FDA parallel audit requirements. Secondary validation draws from USDA National Organic Program certification databases, EFSA novel food evaluations, customs records tracking spice-derived raw material flows, and SEC filings from publicly traded taste system suppliers. Bottom-up volume modeling triangulates against top-down market sizing from channel participant aggregation.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models segmentation dimensions spanning product type (spices, blends, herbs, condiments), application channel (food processing, food service, retail, home cooking), ingredient source tier (organic, natural, conventional, synthetic), and packaging format. CAGRs derive from regression against historical contract renewal patterns and procurement mandate diffusion curves. Industry-specific forecast inputs include monsoon variability indices for Kerala cardamom yields and chain restaurant expansion pipelines for standardized savory system demand.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to climate volatility in Indian spice-growing regions and regulatory harmonization progress between FSSAI and FDA. Forecasts reflect assumptions around clean-label mandate persistence and fermentation technology cost curves. Deviation in EU carbon border adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Cardamom Oil Market
Spices and Seasonings
US Spice and Seasonings Market
Spices and Seasonings
Asia-Pacific Seasoning and Spices Market
Spices and Seasonings
Mullein Leaf Market
Spices and Seasonings
BBQ Seasoning Market
Spices and Seasonings
Blended Spices Market
Spices and Seasonings
South America Seasoning and Spices Market
Spices and Seasonings
Wild Cherry Powder Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Global Black Pepper Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Cardamom Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Boutique Salt Market
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market