
 Middle East and Africa Food Micronized Salt Market | 2026-2036
Middle East and Africa Food Micronized Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Micronized Salt Market Foresight
Food manufacturers are collapsing the traditional buyer hierarchy that once favored commodity bulk salt purchasers. Restaurants and caterers now represent the fastest-expanding demand archetype for precision-dosed micronized grades. Cargill, Incorporated leverages its regional distribution infrastructure to supply packaged food processors across North Africa. El Nasr Salines Co. anchors Egyptian production with captive brine sourcing and controlled crystallization capacity. SASA SAUDI SALT dominates the Gulf premium segment through tight particle-size consistency and halal-certified processing lines.
Middle East and Africa food micronized salt denotes sodium chloride milled to sub-250-micron particle diameter, typically 99.0% NaCl purity, produced via vacuum evaporation or controlled mechanical grinding for rapid dissolution in processed foods. Its primary commercial purpose is to deliver uniform saline distribution in seasonings, cured meats, and dry bakery premixes where coarse crystals create sensory defects. Sea salt and rock salt variants command premium positioning in gourmet and health-oriented retail channels, while standard table salt occupies high-volume food processing contracts where cost efficiency governs procurement. The food processing application leads absolute tonnage across the region, though confectionery represents the fastest-growing application as chocolate and confection manufacturers adopt micronized salt for controlled flavor burst engineering.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce sodium content labeling and additive limits that reshape product formulation requirements for suppliers seeking Gulf market access. Egypt's Egyptian Organization for Standardization and Quality (EOS) maintains parallel specifications for local manufacturers, creating a dual-compliance burden for cross-border traders. Stakeholders must monitor evolving Gulf Cooperation Council technical harmonization talks, where unified micronized salt purity standards could consolidate testing protocols or fragment them further across national jurisdictions.
Market Dynamics
Gulf Cooperation Council food safety harmonization is tightening impurity thresholds and particle size specifications, forcing suppliers to retool crystallization and milling infrastructure to maintain market access across Saudi Arabia and the United Arab Emirates.
Growth Catalysts
- Processed Meat Expansion:Food manufacturers across the region are expanding procurement of micronized salt for processed meat applications, driven by rapid urbanization and retail format modernization.
- SFDA Sodium Labeling Mandates:Saudi Food and Drug Authority enforcement of sodium content labeling is reshaping product formulation requirements and creating demand for precision-dosed grades.
- Bakery Premix Industrialization:Large-scale food processing clusters in the Gulf are anchoring volume offtake for rapid-dissolution salt in dry bakery premixes where coarse crystals create sensory defects.
Market Restraints
- Captive Brine Concentration:Egyptian production relies heavily on El Nasr Salines Co.'s captive brine sourcing, creating supply concentration risk for cross-border traders dependent on Nile Delta feedstock.
- Vacuum Evaporation Energy Costs:Thermal processing for sub-250-micron particle production faces input cost volatility from natural gas and electricity tariffs across North African manufacturing zones.
- Dual-Compliance Burden:Egypt's EOS maintains parallel specifications to Gulf standards, fragmenting testing protocols and raising certification costs for suppliers serving both markets.
Strategic Opportunities
- Confectionery Flavor Engineering:Chocolate and confection manufacturers are adopting micronized salt for controlled flavor burst engineering, representing an emerging application with premium pricing potential.
- Halal-Certified Processing Lines:SASA SAUDI SALT's halal-certified infrastructure demonstrates how religious certification creates defensible positioning in Gulf premium segments.
- GCC Technical Harmonization:Unified micronized salt purity standards under active Gulf Cooperation Council talks could consolidate testing protocols and reduce compliance fragmentation for regional suppliers.
Industry Challenges
- Particle Size Consistency Talent:Controlled crystallization capacity requires specialized process engineers scarce across North African and Levantine manufacturing zones.
- Cross-Border Certification Timelines:ESMA and SFDA approval cycles for new salt grades extend commercialization timelines, compressing first-mover windows.
- Legacy Bulk Salt Infrastructure:Commodity salt handling systems at regional ports and warehouses require retrofitting to prevent contamination of precision-dosed micronized grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Micronized Salt Market |
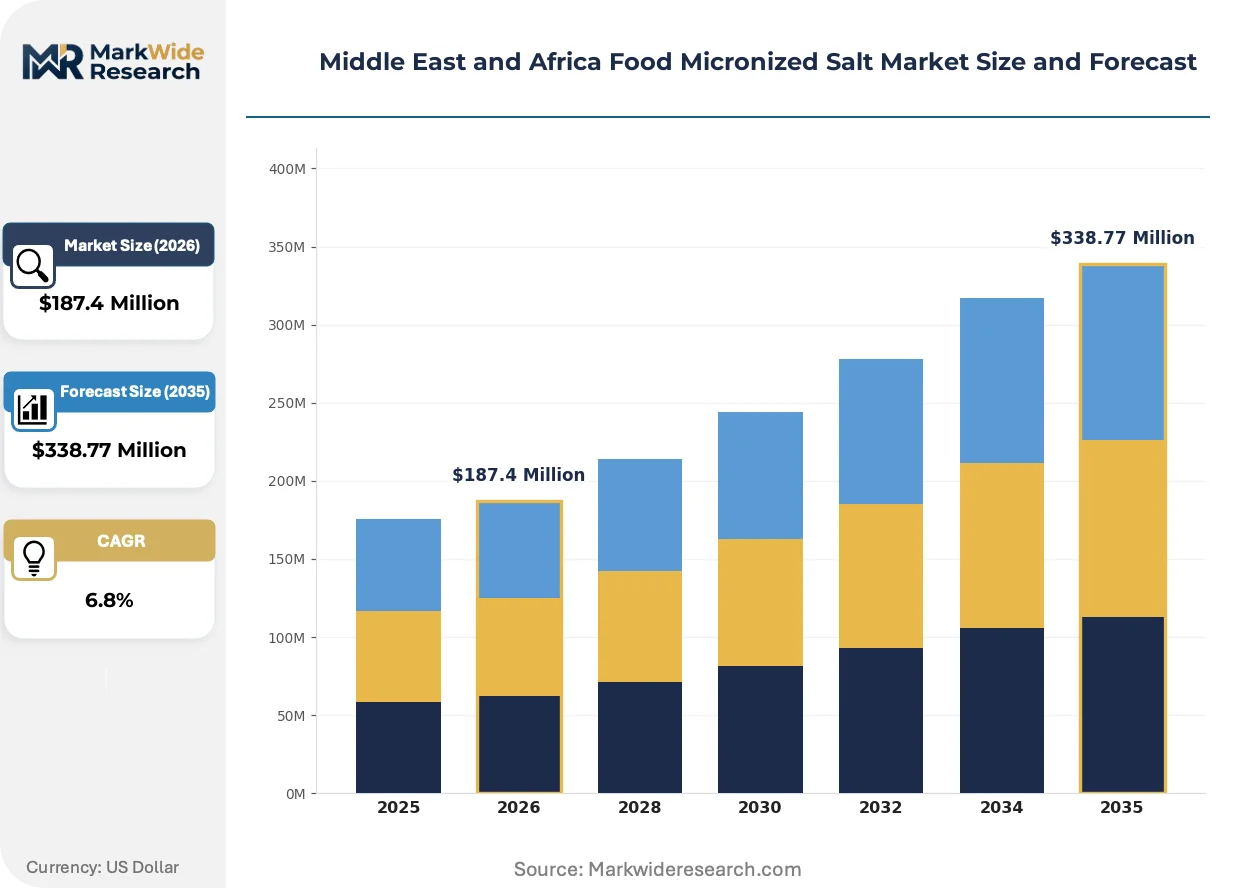
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Table Salt, Sea Salt, Rock Salt, Himalayan Salt Application: Food Processing, Seasoning, Preservation, Confectionery End User: Restaurants, Food Manufacturers, Retailers, Caterers Distribution Channel: Wholesale, Supermarkets, Online Retail, Specialty Stores |
| Companies Covered | Amra Salt Factory, El Nasr Salines Co., Cargill, Incorporated, Gulf Salt Co., Reefal for Salt, SASA SAUDI SALT, Samasalt, Blue Line Industries, Riyadh Salt Industry Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Micronized Salt Market Shifts & Advancements
Precision milling technology and regulatory labeling convergence are compressing the traditional commodity-premium divide, while confectionery and gourmet retail channels open new value-capture pathways beyond industrial food processing contracts.
Fluidized bed drying coupled with air classification is fragmenting the historical dominance of standard mechanical grinding in regional salt processing. Confectionery manufacturers in the UAE and Saudi Arabia are adopting these systems at accelerated pace to achieve sub-100-micron distributions for chocolate flavor burst engineering. This technology diffusion is compressing margins for legacy vacuum evaporation suppliers unable to retrofit crystallization trains.
ESMA's additive limit harmonization with Saudi SFDA standards is consolidating Gulf market access requirements into a single compliance pathway. Industrial consequence includes accelerated consolidation of testing laboratory accreditation across Dubai and Riyadh. Food processors in the Emirates are responding by pre-qualifying suppliers against unified purity benchmarks before contract tendering.
Restaurant and catering procurement of precision-dosed micronized grades is displacing traditional bulk salt purchasing hierarchies. Foodservice distributors in Jeddah and Manama are building dedicated handling infrastructure to serve this channel shift. This behavioral pivot is most visible in Saudi Arabia's central kitchen and cloud kitchen clusters where saline consistency governs brand replication across franchise networks.
Middle East and Africa Food Micronized Salt Market Segmentation
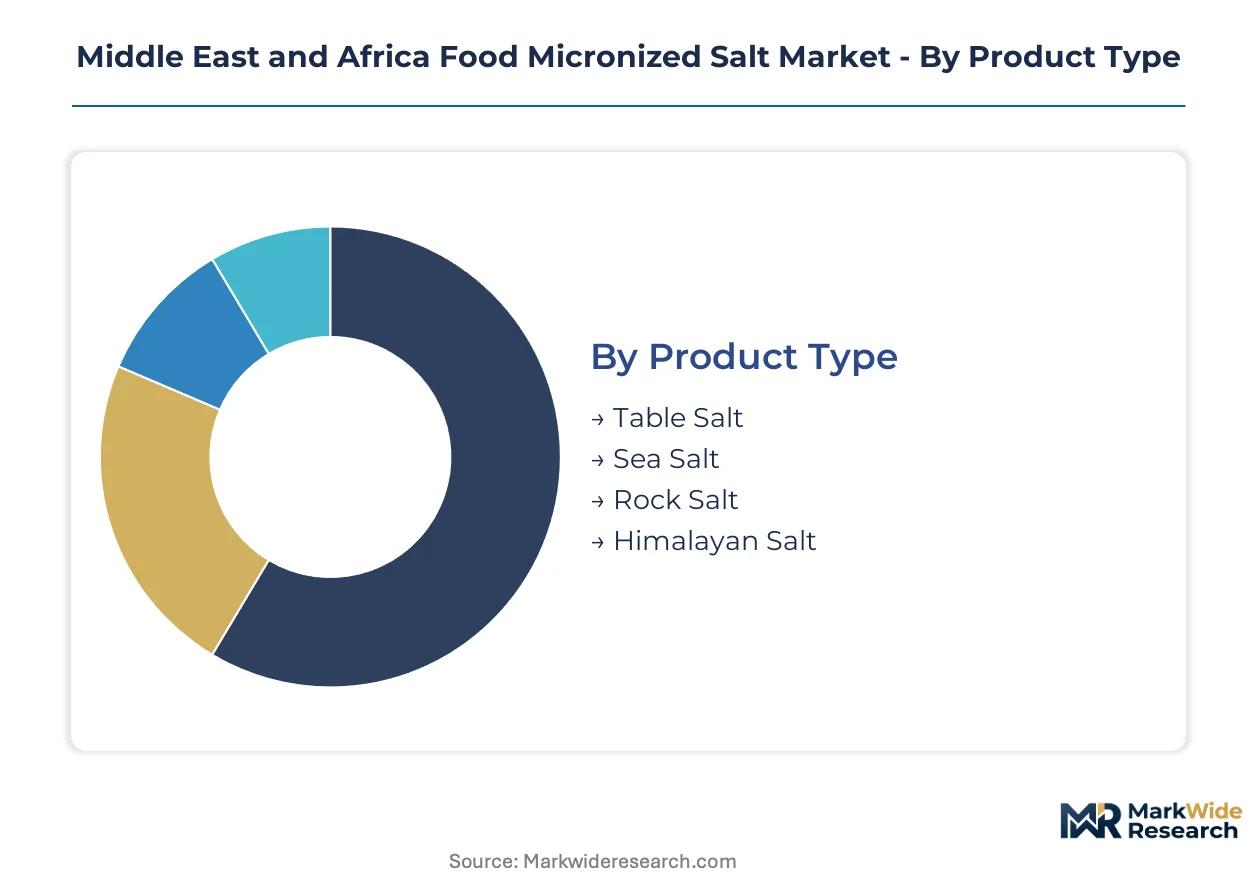
Micronized salt procurement patterns diverge sharply across product grades and channel structures in the Middle East and Africa. Margin capture depends on matching particle specification precision to end-use technical requirements rather than commodity volume plays.
Product Type:
Premium positioning concentrates in specialty mineral variants where Gulf food safety harmonization tightest impurity thresholds create pricing power for certified grades.
- Table Salt:Vacuum-evaporated sodium chloride milled to sub-250-micron diameter dominates industrial food processing contracts across Saudi Arabia and the UAE. Large-scale bakery and processed meat manufacturers in Jeddah and Dubai industrial zones anchor volume offtake for this standardized grade.
- Sea Salt:Solar-evaporated crystals mechanically ground to precision particle distributions command premium positioning in gourmet retail channels. UAE-based chocolate manufacturers and Saudi central kitchen operators are expanding procurement for controlled saline burst applications.
- Rock Salt:Mechanically milled mineral salt from subterranean deposits serves cost-sensitive industrial buyers in North African manufacturing zones.
- Himalayan Salt:Trace mineral content and distinctive coloration support health-oriented positioning in Levantine specialty retail and direct-to-consumer channels.
The dominant share belongs to Table Salt, while Sea Salt is closing the gap fastest.
Application:
Volume concentration tracks food processing cluster development, though technical specification intensity varies dramatically by end-use functional requirement.
- Food Processing:Dry bakery premixes and processed meat formulations require rapid-dissolution sodium chloride to eliminate sensory defects from coarse crystal distribution. Saudi Arabia's central kitchen networks and UAE cloud kitchen clusters are expanding precision-dosed procurement.
- Confectionery:Sub-100-micron salt distributions enable controlled flavor burst engineering in chocolate manufacturing. Fluidized bed drying adoption is accelerating among Emirates-based confectioners seeking particle consistency beyond standard mechanical grinding output.
- Seasoning:Blended spice and condiment manufacturers require uniform saline distribution for shelf-stable product formulations.
- Preservation:Cured meat processors in Egypt and Morocco utilize micronized grades for rapid brine penetration and consistent shelf-life extension.
Food Processing retains the largest volume position, though Confectionery is expanding most quickly as flavor engineering applications multiply.
End User:
Procurement authority is collapsing traditional hierarchies as restaurant and catering operators bypass bulk commodity purchasers for direct precision-grade sourcing.
- Restaurants:Central kitchen and franchise replication requirements in Saudi Arabia's QSR expansion are driving dedicated handling infrastructure investment. Jeddah and Riyadh foodservice distributors now stock segregated micronized salt lines to prevent contamination.
- Food Manufacturers:Packaged food processors across North Africa maintain the largest absolute tonnage contracts, though margin compression from energy cost volatility in vacuum evaporation operations is intensifying supplier negotiation leverage.
- Caterers:Event and institutional foodservice operators in the Gulf are adopting precision-dosed grades for menu consistency across high-volume preparation environments.
- Retailers:Supermarket private label programs in the UAE and Saudi Arabia are expanding gourmet salt offerings targeting health-conscious consumers.
Food Manufacturers still command the greatest contract value, yet Restaurants are gaining share fastest through channel restructuring.
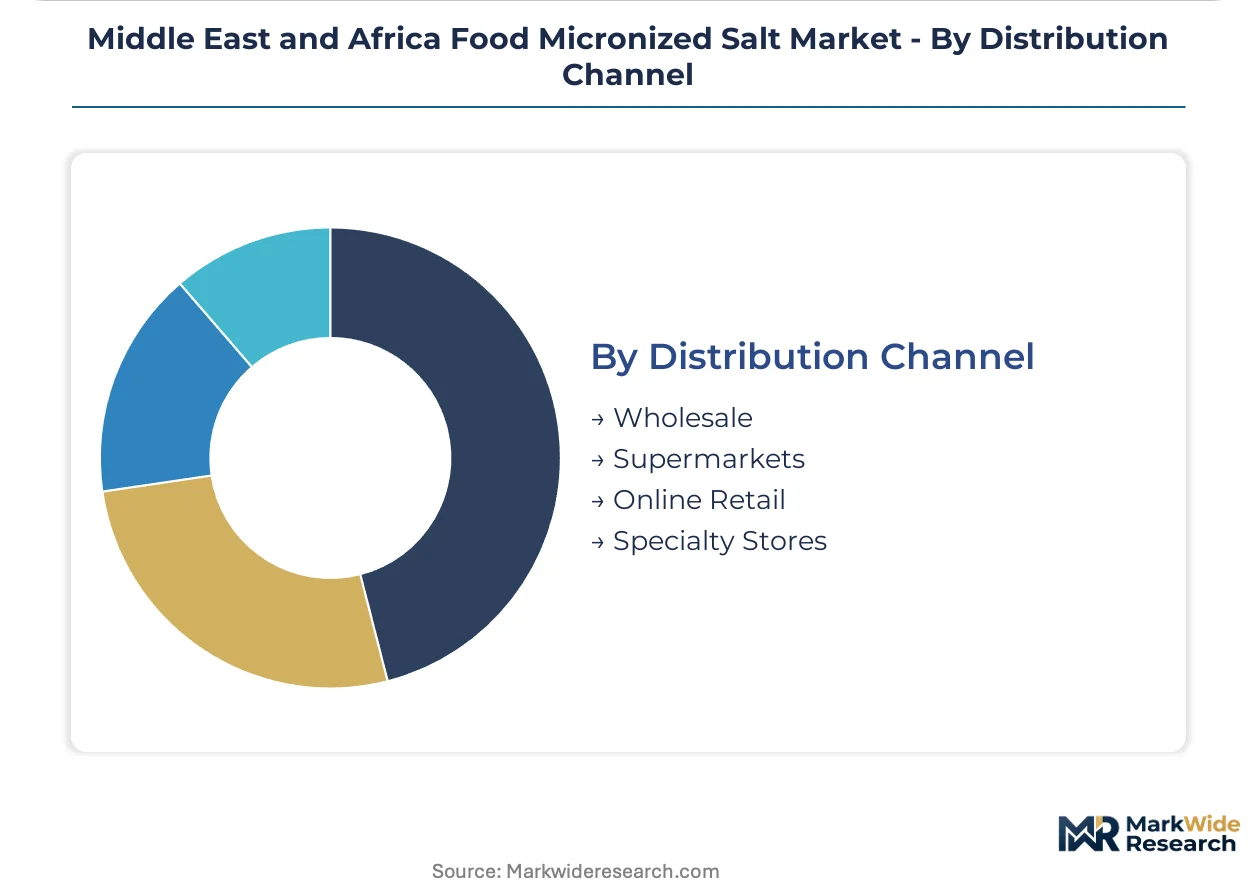
Distribution Channel:
Physical infrastructure requirements for contamination prevention are reshaping channel economics and supplier qualification protocols.
- Wholesale:Bulk handling systems at regional ports and warehouses require retrofitting to maintain precision-grade integrity. Cross-border traders serving Egypt and Gulf markets face dual-compliance certification burdens from parallel EOS and ESMA specifications.
- Supermarkets:Hypermarket chains in Dubai and Riyadh are expanding dedicated gourmet salt shelf space as health-positioned variants capture consumer attention.
- Specialty Stores:Organic and halal-certified retailers in Saudi Arabia leverage religious certification alignment to differentiate premium mineral salt offerings.
- Online Retail:Direct-to-consumer platforms are penetrating gourmet and health-oriented segments with subscription-based Himalayan and sea salt replenishment models.
Wholesale maintains structural dominance in volume terms, while Specialty Stores are climbing the fastest on certification-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput capacity underwrites Dubai's role as the Gulf's primary re-export hub for food-grade salt consignments bound for Saudi Arabia, Egypt, and East Africa.
Saudi Arabia
Central kitchen networks and QSR franchise expansion in Riyadh and Jeddah drive precision-dosed salt procurement. SFDA sodium labeling mandates reshape formulation requirements for suppliers seeking market access. Jeddah Industrial City hosts dedicated handling infrastructure to prevent contamination of micronized grades.
United Arab Emirates
Cloud kitchen clusters and chocolate manufacturers in Dubai anchor demand for sub-100-micron distributions. ESMA additive limit harmonization with Saudi standards consolidates Gulf compliance pathways. Dubai Industrial Park concentrates fluidized bed drying adoption among confectionery processors.
Egypt
Processed meat and cured food producers in the Nile Delta expand vacuum-evaporated salt offtake. EOS maintains parallel specifications to Gulf standards, fragmenting testing protocols. Alexandria's port infrastructure handles bulk salt imports requiring retrofitting for precision-grade integrity.
South Africa
Bakery premix industrialization in Gauteng drives rapid-dissolution salt demand for sensory defect elimination. The country's national food safety regulator enforces sodium content thresholds for packaged foods. Johannesburg-Pretoria corridor clusters food processing capacity requiring consistent saline distribution.
Morocco
Cured meat processors in Casablanca-Settat utilize micronized grades for rapid brine penetration. National standardization bodies maintain additive specifications for cross-border trade with European markets. Tangier Med Port's logistics infrastructure supports salt re-export to West African manufacturing zones.
Middle East and Africa Food Micronized Salt Market Competitive Landscape
Concentration sits with Gulf-based halal-certified specialists and Nile Delta captive brine operators. The vendor base spans multinational traders with regional distribution infrastructure and domestic crystallization specialists with controlled milling capacity. Two strategic archetypes dominate: vertically integrated brine-to-powder operators and logistics-anchored trading houses. Capacity expansion and certification alignment represent the dominant competitive moves as suppliers retool for tightened GCC purity standards.
Among Saudi-based specialists, SASA SAUDI SALT and Riyadh Salt Industry Company exemplify the halal-certified premium tier. El Nasr Salines Co. anchors Egyptian production with captive brine sourcing. Cargill, Incorporated occupies a position as the multinational trading archetype leveraging regional distribution infrastructure across North Africa.
| Leading Market Players |
|---|
| Amra Salt Factory |
| El Nasr Salines Co. |
| Cargill, Incorporated |
| Gulf Salt Co. |
| Reefal for Salt |
| SASA SAUDI SALT |
| Samasalt |
| Blue Line Industries |
| Riyadh Salt Industry Company |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Saudi food manufacturers and Gulf salt processors lock in both brine supply access and eighteen-month price visibility against natural gas tariff volatility. These arrangements insulate precision-grade buyers from spot market swings while binding suppliers to SFDA purity compliance investments.
Pricing Analysis
Volume-discount tiering structures stratify across halal-certified premium, standard vacuum-evaporated, and ungraded bulk economy levels. Price differentiation hinges on particle-size consistency certification and ESMA additive compliance, with premium tiers commanding substantial markups for sub-100-micron distributions. Cost compression in standard grades intensifies as Egyptian captive brine operators expand crystallization capacity. Food manufacturers in Jeddah Industrial City exhibit highest price sensitivity, while UAE confectionery processors prioritize specification precision over unit cost.
Supply Chain Analysis
Egypt and Saudi Arabia anchor regional micronized salt production through contrasting models. Egyptian output draws from El Nasr Salines Co.'s captive Nile Delta brine sourcing, while Saudi capacity clusters around Jeddah Industrial City's halal-certified processing corridors. Feedstock dependencies rest on natural gas for vacuum evaporation, mechanical grinding equipment, and specialized air classification systems. Single-source vulnerability concentrates in Egyptian brine field concentration, where cross-border traders lack alternative feedstock pathways. Distribution runs through Jebel Ali Port's re-export infrastructure serving Saudi Arabia and East African manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
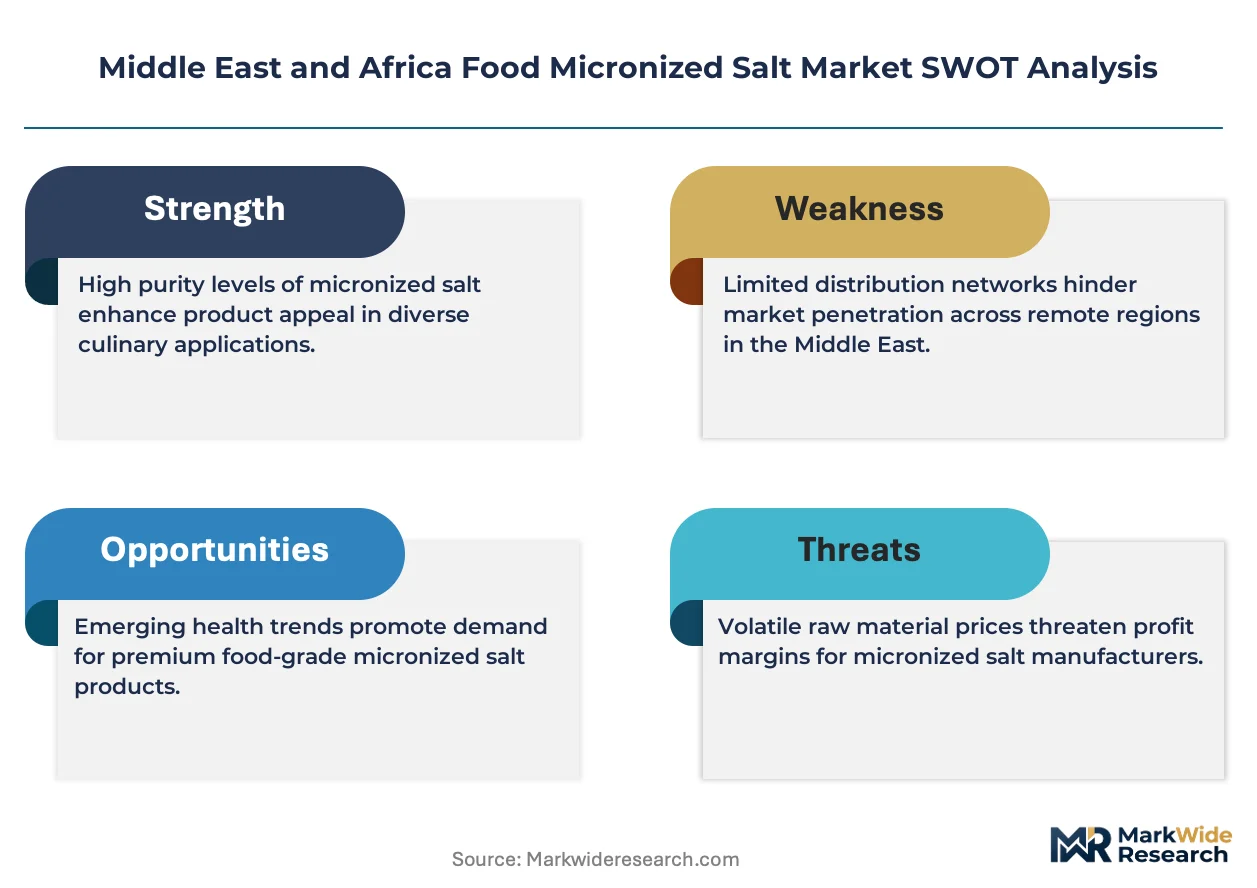
This market demands substitution defense against potassium-based salt replacers and novel umami enhancers threatening sodium chloride's formulation dominance in health-positioned processed foods.
For Market Incumbents: Secure backward integration into captive brine sourcing or controlled crystallization capacity to defend margin position against Egyptian supply concentration. Invest in fluidized bed drying retrofitting before GCC harmonization tightens particle-size specifications, locking out legacy mechanical grinding competitors. For New Entrants and Emerging Players: ESMA-SFDA dual certification fast-tracks unlock Gulf market access for North African traders currently fragmented by parallel testing protocols. Target UAE confectionery processors seeking sub-100-micron supply alternatives to incumbent vacuum evaporation suppliers. Position through direct foodservice distributor partnerships bypassing wholesale contamination risks. For Investors and Strategic Acquirers: Halal-certified mid-cap specialists with installed fluidized bed capacity represent prime acquisition targets as GCC harmonization consolidates compliance barriers. Monitor ESMA-SFDA technical alignment talks as inflection indicator for regulatory-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Brine | Eliminates Nile Delta feedstock dependency for cross-border traders serving Saudi Arabia. |
| Fluidized Bed Drying Retrofit | Enables sub-100-micron particle consistency for UAE chocolate manufacturers. |
| Halal Certification Investment | Creates defensible positioning in Saudi premium segments against Egyptian bulk imports. |
| Direct Foodservice Distribution | Bypasses wholesale contamination risks for Saudi central kitchen and cloud kitchen clusters. |
| ESMA-SFDA Dual Compliance | Consolidates testing protocols for suppliers serving both Emirates and Saudi markets. |
Research Methodology
A spread of perspectives from salt processing plant managers, food manufacturer procurement leads, ESMA regulatory affairs officers, and Jebel Ali Port logistics operators converged on the working assumptions. Primary fieldwork combined with secondary validation from SFDA additive limit filings, Egyptian Organization for Standardization and Quality specifications, Gulf Cooperation Council technical harmonization documents, and customs trade flow records. Bottom-up crystallization capacity modeling triangulated against top-down food processing demand estimates.
Segmentation dimensions modeled include product grade tier, application functional requirement, end-user procurement authority, and distribution channel contamination risk profile across the projection horizon. CAGRs were derived from installed capacity expansion pipelines and food processing cluster development trajectories. Industry-specific forecast inputs incorporated natural gas tariff scenarios and GCC technical harmonization implementation timelines.
Underlying assumptions cover SFDA-ESMA regulatory convergence, Egyptian brine field output stability, and vacuum evaporation energy cost trajectories, with deviation risk concentrated in dual-compliance fragmentation and fluidized bed technology diffusion rates. Recalibration cycles align with material shifts in Gulf harmonization talks and major food processing capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Bay Leaf Market
Spices and Seasonings
Organic Spices and Herbs Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Gourmet Seaweed Seasoning Market
Spices and Seasonings
Frankincense Extract Market
Spices and Seasonings
North America Spice and Herb Extracts Market
Spices and Seasonings
Dill Oil Market
Spices and Seasonings
Saffron Market
Spices and Seasonings
Cajun Spice Market
Spices and Seasonings
Pepper Market
Spices and Seasonings
All-Purpose Seasoning Market
Spices and Seasonings
Moringa Leaves Powder Market
Spices and Seasonings
Onion Oil Market
Spices and Seasonings
Meat Seasonings Market
Spices and Seasonings
Global Clove Market
Spices and Seasonings
Incense Sticks (Agarbatti) Market