
 EDA Tools Market | 2026-2036
EDA Tools Market Size, Share, and Industry Trends Forecast 2026-2036
EDA Tools Market Analysis
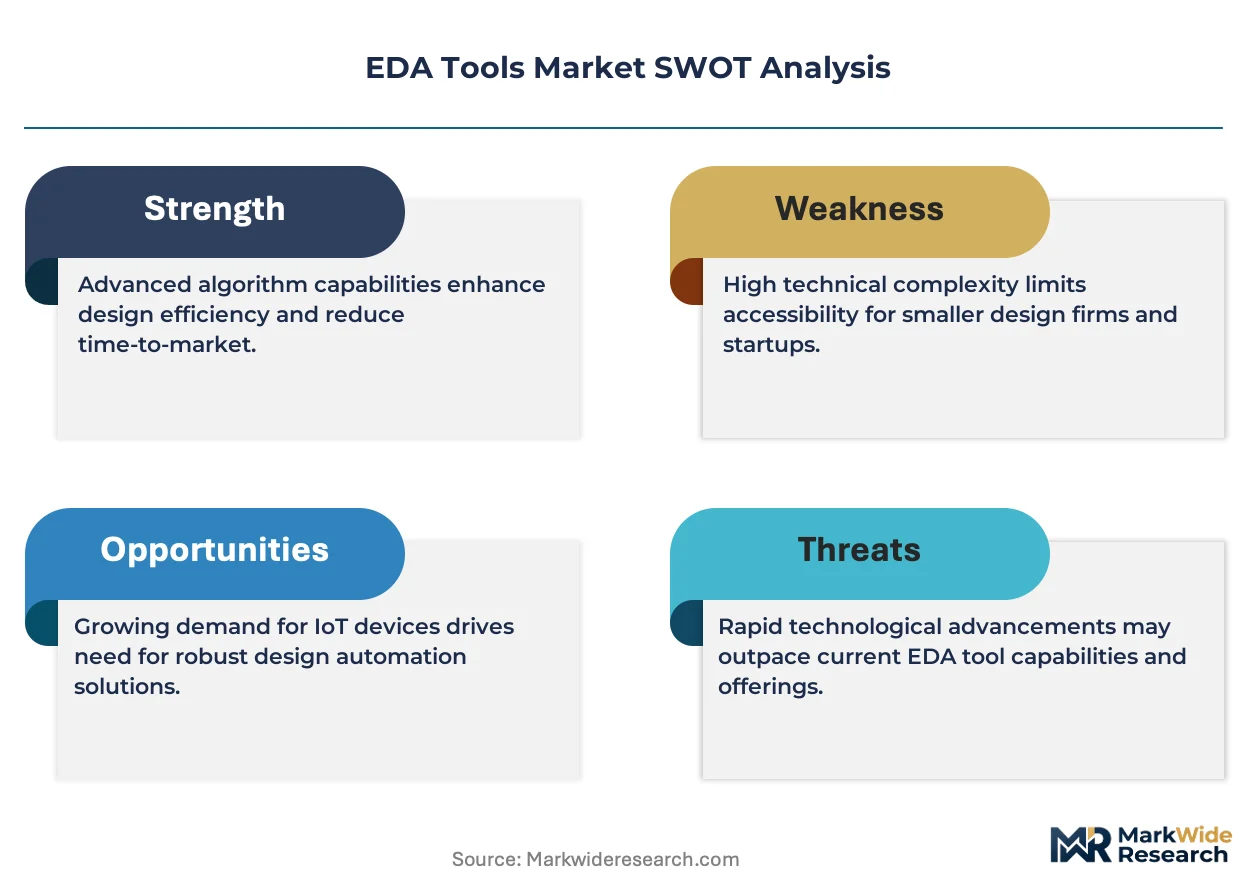
Project finance for advanced-node semiconductor fabrication is narrowing the competitive field for EDA tool vendors. Cadence Design Systems Inc. leverages deep integration between its custom design and verification suites to anchor relationships with leading foundries. Synopsys Inc. sustains R&D intensity across silicon-to-systems workflows that span artificial intelligence and automotive radar design. Siemens EDA competes through hardware-software co-verification platforms tied to industrial automation ecosystems.
Electronic design automation tools comprise software systems that enable integrated circuit and printed circuit board design through algorithmic synthesis, place-and-route optimization, and parasitic extraction at geometries measured in angstroms. These platforms serve the primary purpose of reducing tape-out risk and accelerating time-to-market for semiconductor devices. Mixed-signal design flows command premium licensing value as analog-digital boundary complexity rises in automotive sensor fusion chips. Cloud-based deployment models are expanding fastest among fabless startups seeking elastic compute access without datacenter capital expenditure, while on-premise installations retain dominance at defense-aerospace contractors with air-gapped security requirements.
The U.S. Department of Commerce export controls administered through BIS shape licensing restrictions for advanced-node EDA tools destined to specific foreign entities. The EU Chips Act and its national implementations in Germany and France are creating parallel compliance frameworks for subsidy-recipient fabs. REACH and RoHS directives from ECHA constrain materials databases within component libraries, forcing tool vendors to maintain updated restriction-of-hazardous-substances tracking. Stakeholders must monitor how bilateral technology transfer agreements between Washington and Brussels reshape the geographic portability of design-tool licenses.
Market Dynamics
Sub-3nm node migration is compressing design cycles and forcing foundries to license multi-physics simulation suites that bridge quantum effects with classical circuit analysis. This structural pressure rewards vendors who can unify process-design-kit calibration with in-design signoff acceleration.
Growth Catalysts
- CHIPS Act capital deployment:U.S. fabs receiving IRA-linked subsidies must procure domestic EDA licenses to satisfy domestic content thresholds, redirecting procurement toward North American tool vendors.
- Automotive sensor fusion:Radar-LiDAR integration in advanced driver-assistance systems requires mixed-signal verification flows that command premium licensing tiers from Tier-1 semiconductor suppliers.
- Angstrom-scale extraction:Parasitic extraction at 2nm and below demands machine-learning-accelerated field solvers that reduce signoff iterations by an order of magnitude.
Market Restraints
- Foundry concentration:Taiwan Semiconductor Manufacturing Company and Samsung Foundry control 90% of leading-edge capacity, creating single-source dependency for process-design-kit validation.
- PhD-level talent scarcity:Computational lithography and quantum transport modeling require specialized expertise concentrated in Zurich, Berkeley, and Tsukuba research clusters.
- Export control friction:BIS licensing restrictions on advanced-node EDA tools to specific Chinese entities fragment the addressable market and complicate revenue forecasting.
Strategic Opportunities
- India fabless ecosystem:Design-linked PLI scheme incentives are attracting 50+ semiconductor startups that lack datacenter capital and will adopt cloud-native EDA subscriptions.
- Photonics-electronics convergence:Silicon photonics foundries in the Netherlands and Germany need unified electromagnetic-circuit co-design platforms that incumbent digital-centric tools do not address.
- EU Chips Act compliance:Subsidy recipients in Dresden and Grenoble must document supply chain resilience, creating demand for EDA-embedded materials traceability modules.
Industry Challenges
- Legacy tool integration:Defense contractors with air-gapped 20-year-old design databases face multi-year migration timelines to modern verification environments.
- Multi-die packaging complexity:Chiplet-based architectures require thermal-mechanical-electrical co-simulation that strains existing tool interoperability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EDA Tools Market |
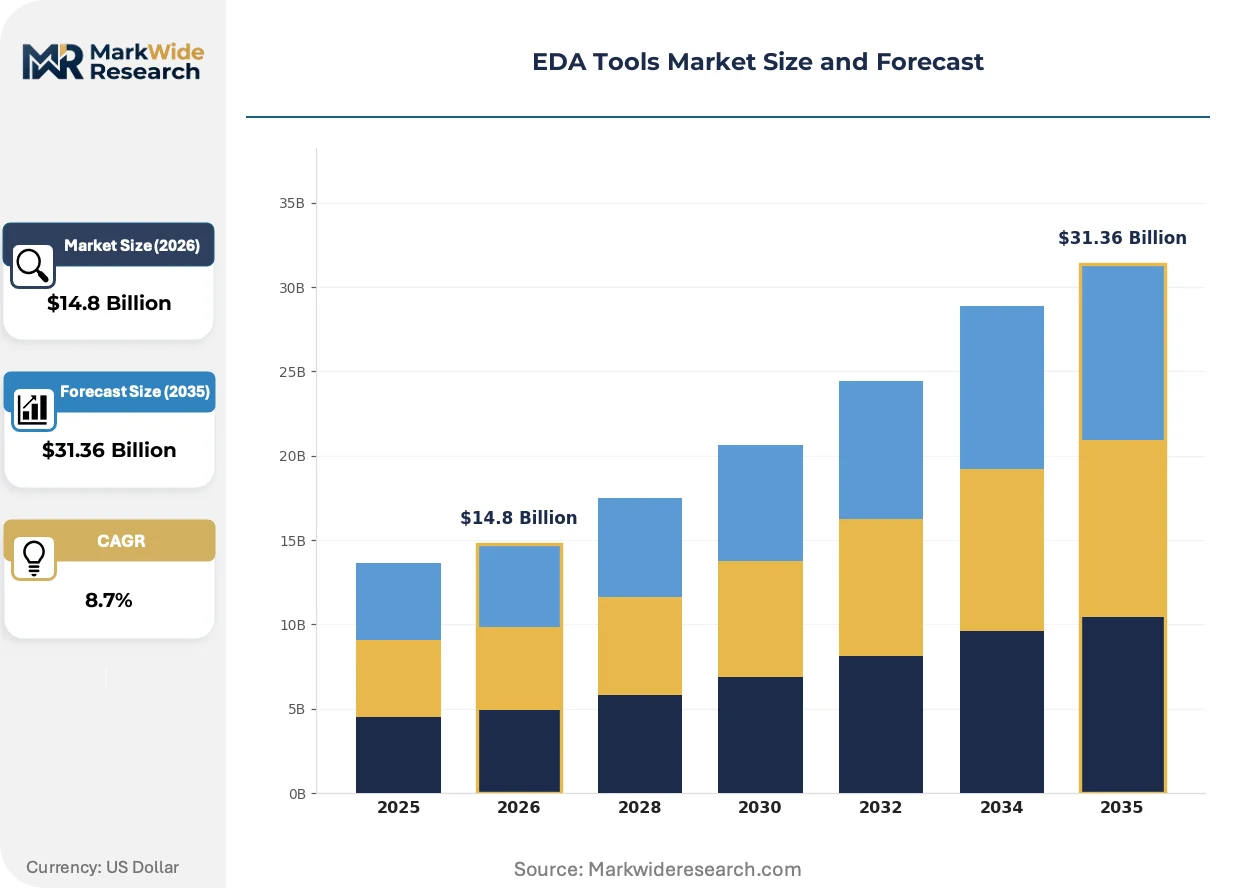
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Mixed-Signal, RF Technology: FPGA, ASIC, SoC, PCB End User: Telecommunications, Automotive, Consumer Electronics, Aerospace Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Keysight Technologies Inc., Altium Limited, Synopsys Inc., Silvaco Inc., Zuken Ltd., Cadence Design Systems Inc., Siemens EDA, Aldec Inc., Ansys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EDA Tools Market Emerging Trajectories
Cloud-native deployment architectures are displacing perpetual license models and enabling elastic compute access for design teams without datacenter infrastructure. This shift is compressing the traditional three-year procurement cycle and forcing vendors to restructure pricing around consumption metrics.
Machine learning is virtualizing physical verification workflows by training surrogate models that predict parasitic extraction results without full field-solver computation. Fabless startups in Israel and the United Kingdom are adopting these accelerated signoff methods to compress tape-out schedules by 40%. The technology is virtualizing the traditional hierarchy between pre-layout estimation and post-layout validation, collapsing what were separate tool categories into unified environments.
REACH and RoHS directives from ECHA are mandating hazardous substance tracking across component libraries used in European automotive and industrial designs. Tool vendors must now maintain updated restriction databases that flag non-compliant materials during schematic capture. German and French fabs receiving EU Chips Act subsidies face audit requirements that embed these compliance checks into their mandatory design flows.
Subscription consumption models are displacing perpetual licensing among mid-size fabless companies that prioritize operational expenditure flexibility over capital deployment. Cloud marketplaces operated by Amazon Web Services and Microsoft Azure are emerging as preferred procurement channels for these buyers. This pattern is most visible in the United States and United Kingdom, where venture-backed startups represent the fastest-growing customer segment for elastic EDA infrastructure.
EDA Tools Market Segmentation
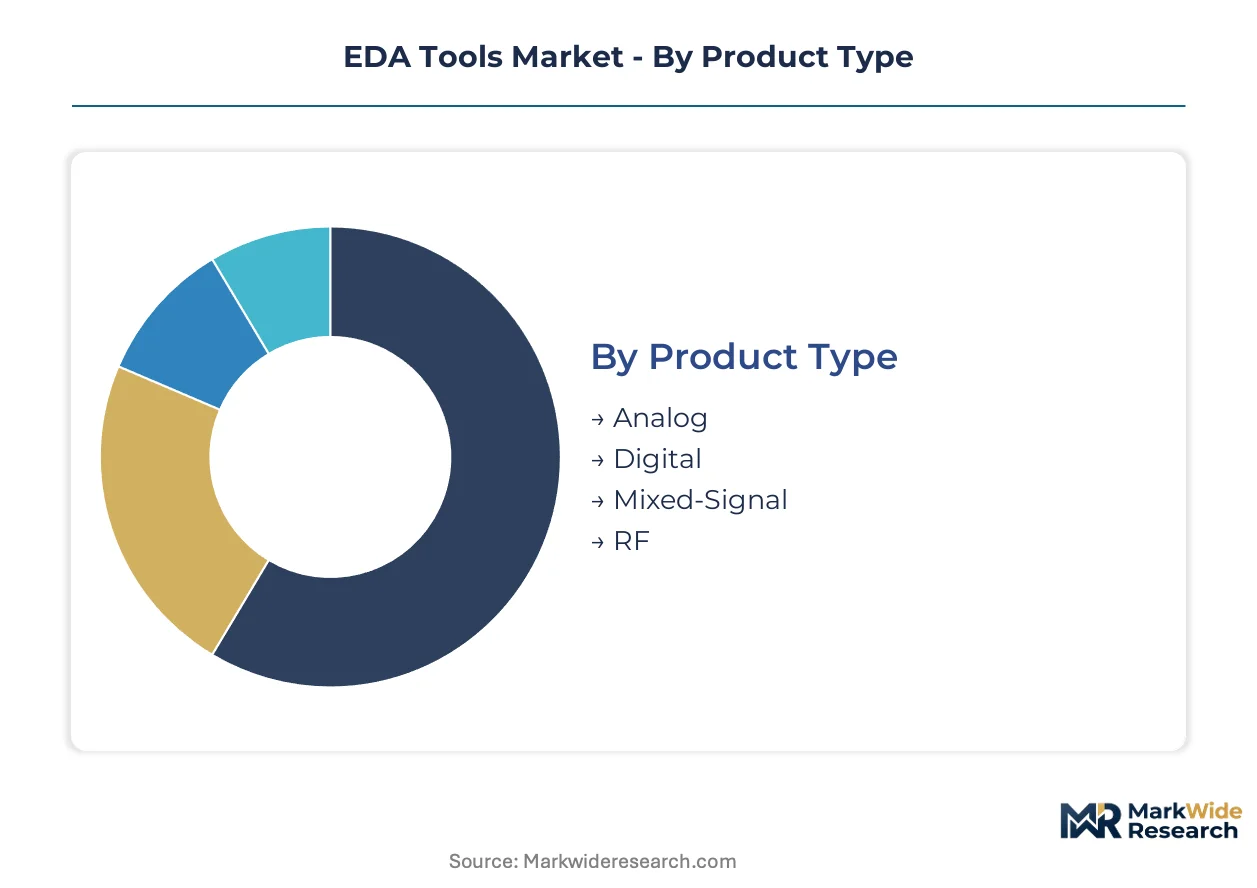
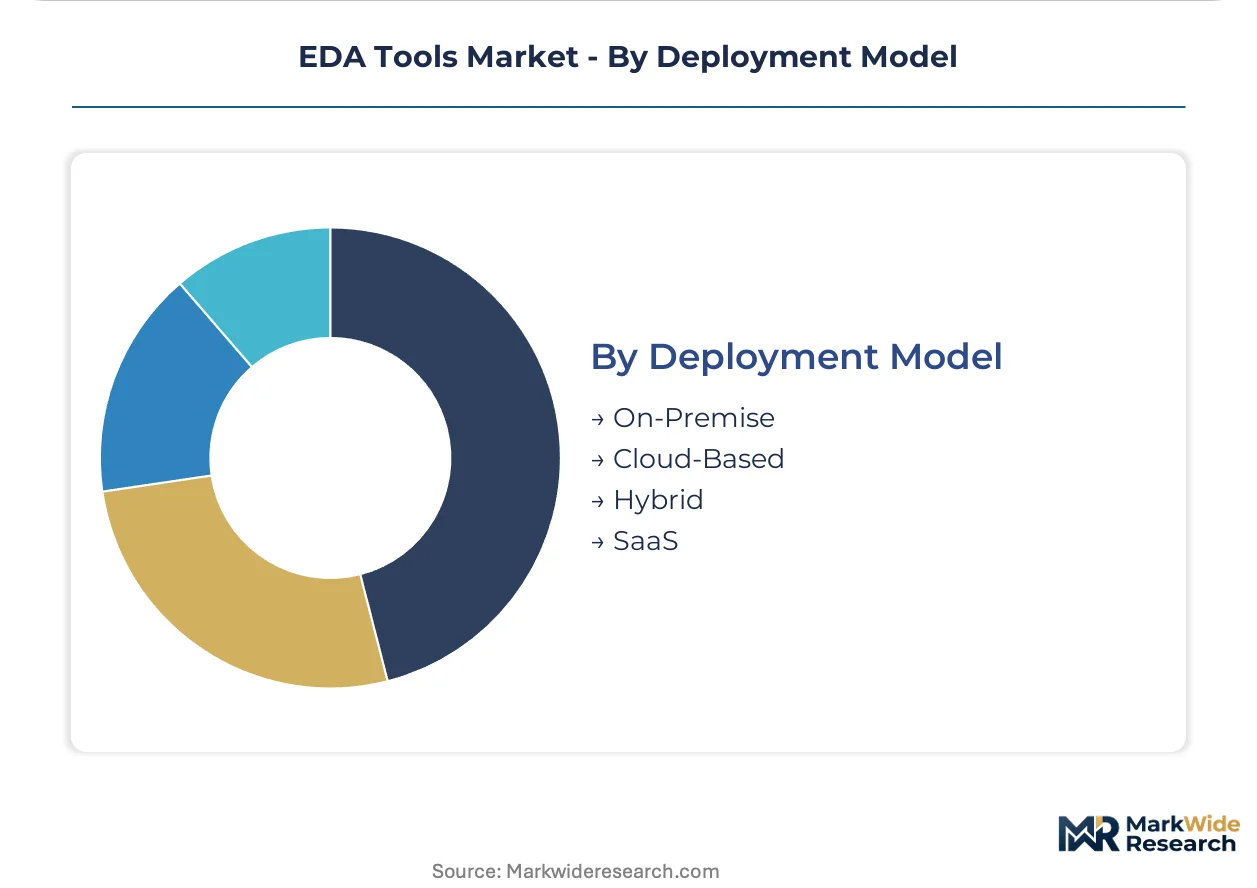
EDA tool procurement cycles vary dramatically by segment, with cloud deployment models refreshing every 12-18 months while on-premise installations persist for 7-10 years. Semiconductor foundries calibrate their tool mix against node migration timelines, creating divergent replacement rhythms across product categories.
Product Type:
Mixed-signal tools command the longest evaluation cycles due to analog-digital boundary complexity, while digital synthesis suites turn over fastest as algorithmic advances compress signoff iterations.
- Mixed-Signal:Unified environments that bridge transistor-level analog simulation with digital place-and-route optimization. Automotive sensor fusion chips in Germany and Japan drive demand as radar-LiDAR integration raises boundary verification complexity. Cadence and Synopsys anchor foundry relationships through PDK-calibrated mixed-signal flows.
- Digital:Logic synthesis and physical design platforms optimized for billion-gate scale-out. Taiwan and South Korea foundries license these most aggressively as sub-3nm node migration accelerates tape-out frequency.
- Analog:Custom IC design environments for power management and signal conditioning circuits.
- RF:Electromagnetic simulation suites targeting 5G millimeter-wave and automotive radar frequencies.
Digital tools dominate installed base volume. Mixed-signal is where expansion concentrates.
Technology:
Cost tiers separate these segments, with SoC platforms commanding premium licensing while PCB tools anchor entry-level procurement budgets.
- SoC:System-on-chip integration platforms unifying CPU, GPU, and NPU subsystems through hierarchical verification. Hyperscaler AI accelerator programs in the United States and China pull demand as chiplet architectures multiply die-to-die interface complexity.
- ASIC:Full-custom silicon flows for high-volume, single-purpose designs with power-performance-area constraints. Automotive Tier-1 suppliers in Germany and Japan deploy these for autonomous driving compute.
- FPGA:Programmable logic design suites with rapid prototyping capabilities.
- PCB:Board-level layout and signal integrity tools for system integration.
SoC commands the highest per-seat licensing. FPGA is climbing fastest on prototyping demand.
End User:
Application urgency dictates procurement speed, with automotive qualification timelines stretching 24-36 months while consumer electronics compress tool selection to 6-9 months.
- Automotive:Functional safety-certified flows meeting ISO 26262 ASIL-D requirements for autonomous systems. German and Japanese OEMs mandate these for sensor fusion and domain controller programs.
- Telecommunications:Baseband and RF front-end design environments for 5G infrastructure. South Korean and Finnish equipment vendors drive procurement as Open RAN architectures proliferate.
- Consumer Electronics:Mobile and wearable chip design with aggressive power-area constraints.
- Aerospace:Radiation-hardened and high-reliability flows for satellite and defense applications.
Automotive claims the longest sales cycles. Telecommunications is expanding most quickly on 5G refresh.
Deployment Model:
Customer type separates these tiers, with venture-backed startups favoring elastic consumption while defense contractors require air-gapped permanence.
- Cloud-Based:Elastic compute access through AWS and Azure marketplaces without datacenter capital expenditure. Israeli and United Kingdom fabless startups adopt these as design-linked incentives attract 50+ new semiconductor ventures.
- On-Premise:Perpetual licenses with dedicated hardware for security-sensitive environments. United States defense contractors and French aerospace suppliers maintain these for ITAR and classified program compliance.
- Hybrid:Split workflows with sensitive IP on local infrastructure and peak compute burst to cloud.
- SaaS:Subscription-native platforms with browser-based access and automatic feature updates.
On-premise retains dominance at defense-aerospace accounts. Cloud-based is gaining share fastest among venture-backed entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in EDA tools skew heavily toward net-importing regions, with software licensing flows concentrating from the United States toward fabrication hubs in Taiwan and South Korea. Capital subsidies in Europe and North America are redirecting procurement toward domestic vendors, reshaping traditional trade patterns.
United States
The CHIPS Act drives foundry construction in Arizona and Texas, pulling EDA licensing toward domestic procurement. BIS export controls restrict advanced-node tool transfers to specific foreign entities, fragmenting addressable markets. Silicon Valley and Austin anchor R&D clusters where machine-learning-accelerated verification tools command premium pricing.
Germany
Automotive sensor fusion chips for ADAS systems require mixed-signal verification flows from Dresden and Munich design centers. EU Chips Act subsidy recipients must document supply chain resilience, embedding materials traceability into mandatory design flows. Bavaria's semiconductor ecosystem concentrates photonics-electronics convergence research.
Taiwan
TSMC's sub-3nm node migration compresses design cycles and forces procurement of multi-physics simulation suites. The island's foundry dominance creates single-source dependency for process-design-kit validation. Hsinchu Science Park anchors the densest concentration of leading-edge EDA tool deployment worldwide.
South Korea
Samsung Foundry's angstrom-scale extraction demands strain existing tool interoperability standards. Korean equipment vendors drive 5G baseband and RF front-end procurement as Open RAN architectures proliferate. Pangyo and Hwaseong clusters concentrate domestic fabless startup activity seeking cloud-native EDA subscriptions.
India
Design-linked PLI scheme incentives attract 50-plus semiconductor startups lacking datacenter capital for on-premise installations. TRAI spectrum allocations for 5G infrastructure pull telecommunications chip design demand. Bengaluru and Hyderabad clusters concentrate venture-backed fabless ventures adopting elastic compute access models.
EDA Tools Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete verification niches. The vendor base concentrates around three dominant full-suite providers, with mid-tier players occupying specialized electromagnetic or photonics segments. Consolidation pressure intensifies as sub-3nm node complexity rewards unified process-design-kit calibration. M&A activity targets machine-learning acceleration capabilities, while strategic partnerships bridge cloud-deployment infrastructure gaps.
Among United States-based platform vendors, Cadence Design Systems Inc., Synopsys Inc., and Ansys Inc. exemplify divergent strategic archetypes. Cadence anchors mixed-signal integration relationships with leading foundries through PDK-calibrated flows. Synopsys occupies the silicon-to-systems breadth position spanning AI accelerator and automotive radar design. Ansys sits within the multi-physics simulation tier where thermal-mechanical-electrical co-simulation demands strain traditional tool boundaries. Specialists including Keysight Technologies Inc. and Silvaco Inc. represent component-tier positioning in RF and analog niches respectively, while Siemens EDA and Zuken Ltd. exemplify industrial automation-tied and PCB-centric alternatives.
| Leading Market Players |
|---|
| Keysight Technologies Inc. |
| Altium Limited |
| Synopsys Inc. |
| Silvaco Inc. |
| Zuken Ltd. |
| Cadence Design Systems Inc. |
| Siemens EDA |
| Aldec Inc. |
| Ansys Inc. |
| Others |
Supply Flow & Price Mechanics
TSMC and Samsung Foundry control ninety percent of sub-3nm leading-edge capacity, anchoring pricing power with full-suite EDA vendors who calibrate process-design-kit licensing to node migration timelines. Margin pools concentrate with vendors bundling multi-physics simulation, machine-learning acceleration, and foundry-certified signoff flows.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to mixed-signal verification flows with ISO 26262 ASIL-D certification for automotive sensor fusion, while economy tiers serve PCB-centric procurement at Tier-3 electronics suppliers. Cost compression in cloud-native subscriptions is intensifying because hyperscaler marketplace procurement bypasses traditional enterprise sales cycles. Fabless startups with venture backing exhibit highest price sensitivity; defense-aerospace contractors with air-gapped requirements show lowest.
Supply Chain Analysis
Supply-chain finance facilities from major cloud providers extend payment terms for fabless startups lacking datacenter capital. Software licensing flows concentrate from the United States toward Taiwan and South Korea, with raw material dependencies spanning advanced-node silicon wafers, GPU compute clusters, and specialized electromagnetic simulation IP. Single-source vulnerability runs through TSMC's process-design-kit validation monopoly. Distribution runs through direct enterprise sales for on-premise perpetual licenses and AWS/Azure marketplaces for elastic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EDA tools market functions as a defensive-moat business where foundry-certified process-design-kit relationships create switching costs that lock in multi-year procurement cycles. Regulatory entrenchment through CHIPS Act domestic content thresholds deepens incumbent positioning.
For Market Incumbents: Entrench through exclusive calibration partnerships with TSMC and Samsung Foundry for angstrom-scale extraction flows, while adding captive machine-learning acceleration capabilities via targeted specialist acquisition. Cloud-native deployment architectures from venture-backed entrants threaten traditional perpetual-license revenue; vertical integration into hardware-software co-verification platforms defends against Siemens EDA's industrial automation tie-ins.
For New Entrants and Emerging Players: Establish a beachhead in silicon photonics-electronics convergence for Dutch and German foundries, where incumbent digital-centric tools lack unified electromagnetic-circuit co-design capability. The most penetrable segment sits with India's design-linked PLI scheme attracting datacenter-capital-constrained fabless startups. A cloud-native subscription model through hyperscaler marketplaces accelerates land-and-expand velocity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electromagnetic simulation specialists possessing RF and millimeter-wave IP but lacking foundry integration depth. Long-term viability hinges on sub-3nm node complexity sustaining unified tool demand rather than point-solution fragmentation. Watch BIS export control expansion to Chinese entities as inflection signal for geographic revenue reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry PDK Calibration Partnership | TSMC-certified signoff flows lock in multi-year enterprise procurement at leading-edge nodes. |
| Machine-Learning Acceleration Acquisition | Surrogate model capabilities compress tape-out schedules for Israeli and UK fabless ventures. |
| Cloud-Native Platform Launch | AWS and Azure marketplace presence captures India's PLI-scheme startup ecosystem. |
| Photonics-Electronics Convergence Development | Dutch and German silicon photonics foundries need unified co-design platforms. |
| EU Chips Act Compliance Module | Dresden and Grenoble subsidy recipients require embedded materials traceability for audit documentation. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Semiconductor design executives, foundry process integration leads, fabless startup CTOs, and defense-aerospace procurement officers provided operational perspective. SEC 10-K disclosures from publicly traded EDA vendors, BIS export control determinations, EU Chips Act national implementation texts, and foundry capital expenditure announcements furnished secondary validation. Bottom-up segment sizing triangulated against top-down market aggregation.
Calibration against historical node migration timelines and foundry capacity buildouts structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-use application, and deployment model. CAGRs derived from elasticity analysis of licensing revenue to semiconductor capital expenditure cycles, with specific inputs from angstrom-scale design complexity indices and cloud consumption metrics.
Stress conditions across BIS licensing restriction expansion, EU subsidy disbursement delays, and sub-3nm yield ramp timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about foundry concentration and regulatory portability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Image Analysis Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Tag Management Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Global Business Software Market
Software & Services
API Design Software Market
Software & Services
Global Gamification Software Market
Software & Services
Driver Updater Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Spain HR Payroll Software Market
Software & Services
Europe Printing Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Time Series Analysis Software Market