
 Asia-Pacific Digital Remittance Market | 2026-2036
Asia-Pacific Digital Remittance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Remittance Market Analytics
Subscription-based premium transfer tiers with guaranteed exchange rates and fee transparency is repositioning how digital remittance platforms monetize customer relationships in the Asia-Pacific corridor. Wise PLC leverages real-time mid-market pricing to sustain its competitive edge across Southeast Asian corridors. Remitly Inc. anchors its growth on mobile-first onboarding tailored to underbanked migrant worker populations in the Philippines and India. NIUM Pte. Ltd. differentiates through its modular banking-as-a-service infrastructure that extends white-label remittance capabilities to regional neobanks.
Asia-Pacific digital remittance encompasses electronic fund transfers executed through licensed non-bank platforms, utilizing API-integrated compliance engines, real-time gross settlement interoperability, and multi-currency digital wallets to enable cross-border value movement for individuals and enterprises. Peer-to-Peer transfers dominate transaction volumes due to persistent outbound labor migration from India and the Philippines, while Blockchain-based settlement channels represent the fastest-growing technology segment as operators seek to bypass correspondent banking delays and reduce forex hedging costs. Business-to-Business corridors exhibit concentrated margin pools in intra-ASEAN trade settlements, though regulatory fragmentation across central bank digital currency pilots complicates unified platform deployment.
India's RBI mandates two-factor authentication and KYC tiering for all outward remittance platforms under the Payment and Settlement Systems Act, while Singapore's Monetary Authority enforces licensing under the Payment Services Act with strict anti-money laundering protocols for cross-border fintech operators. Australia's AUSTRAC and the Philippines' Bangko Sentral ng Pilipinas impose additional transaction monitoring thresholds that shape product architecture and customer onboarding flows. Stakeholders must monitor divergence in central bank digital currency roadmaps across ASEAN member states to anticipate corridor-specific infrastructure investments and partnership requirements.
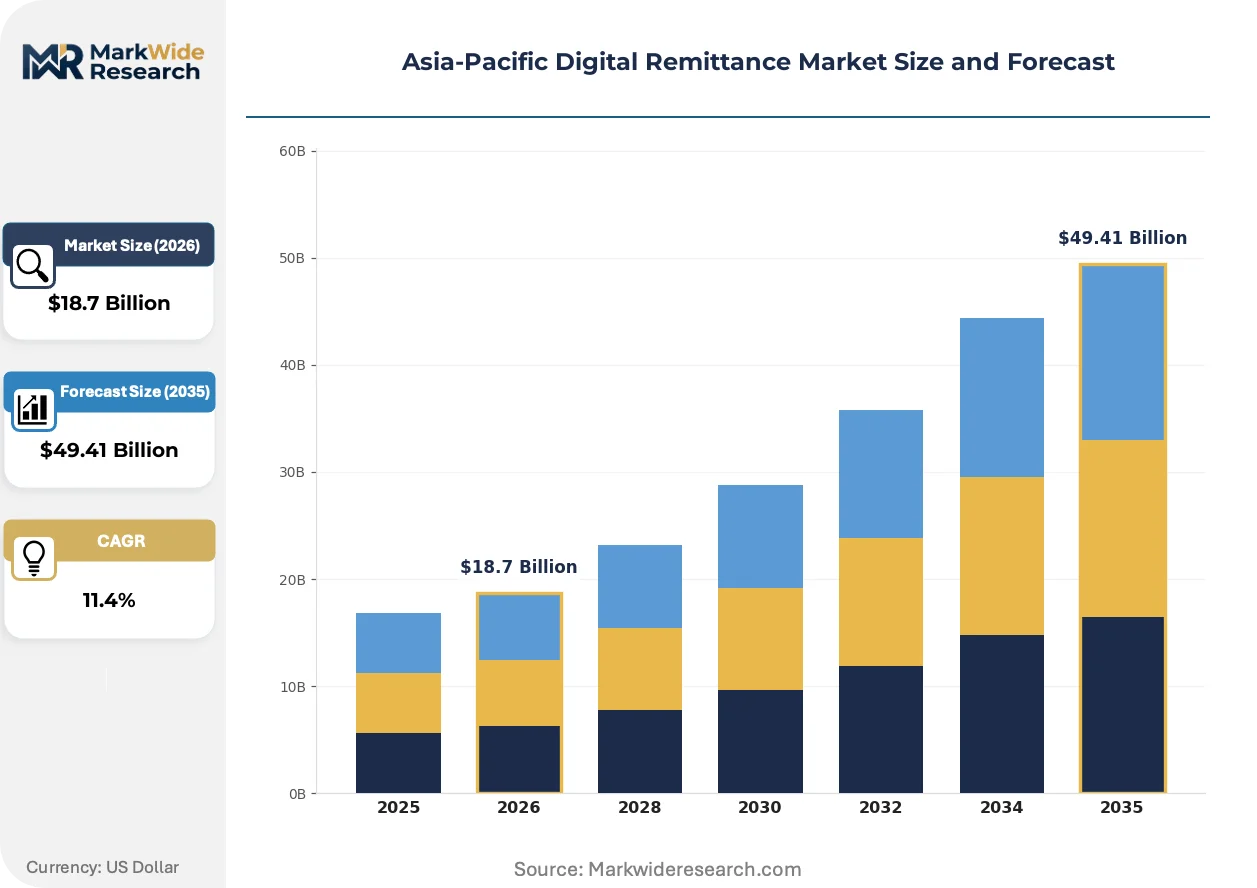
Market Dynamics
India's Unified Payments Interface and Singapore's Payment Services Act are compressing settlement timelines and forcing cross-border fintech operators to rebuild compliance architectures around real-time verification rails.
Growth Catalysts
- API-integrated compliance engines:Automated KYC tiering under India's Payment and Settlement Systems Act reduces onboarding friction for migrant workers in construction corridors.
- Gulf Cooperation Council labor migration:Persistent outbound flows from the Philippines and Vietnam generate recurring transaction volume on mobile-first platforms.
- Real-time gross settlement interoperability:Central bank digital currency pilots across ASEAN member states are creating infrastructure for instantaneous corridor settlements.
Market Restraints
- Correspondent banking concentration:Legacy SWIFT rails in Singapore and Hong Kong maintain fee structures that erode margin on low-value transfers.
- Forex hedging cost volatility:Unhedged rupee-dirham and peso-riyal exposures compress profitability during currency stress periods.
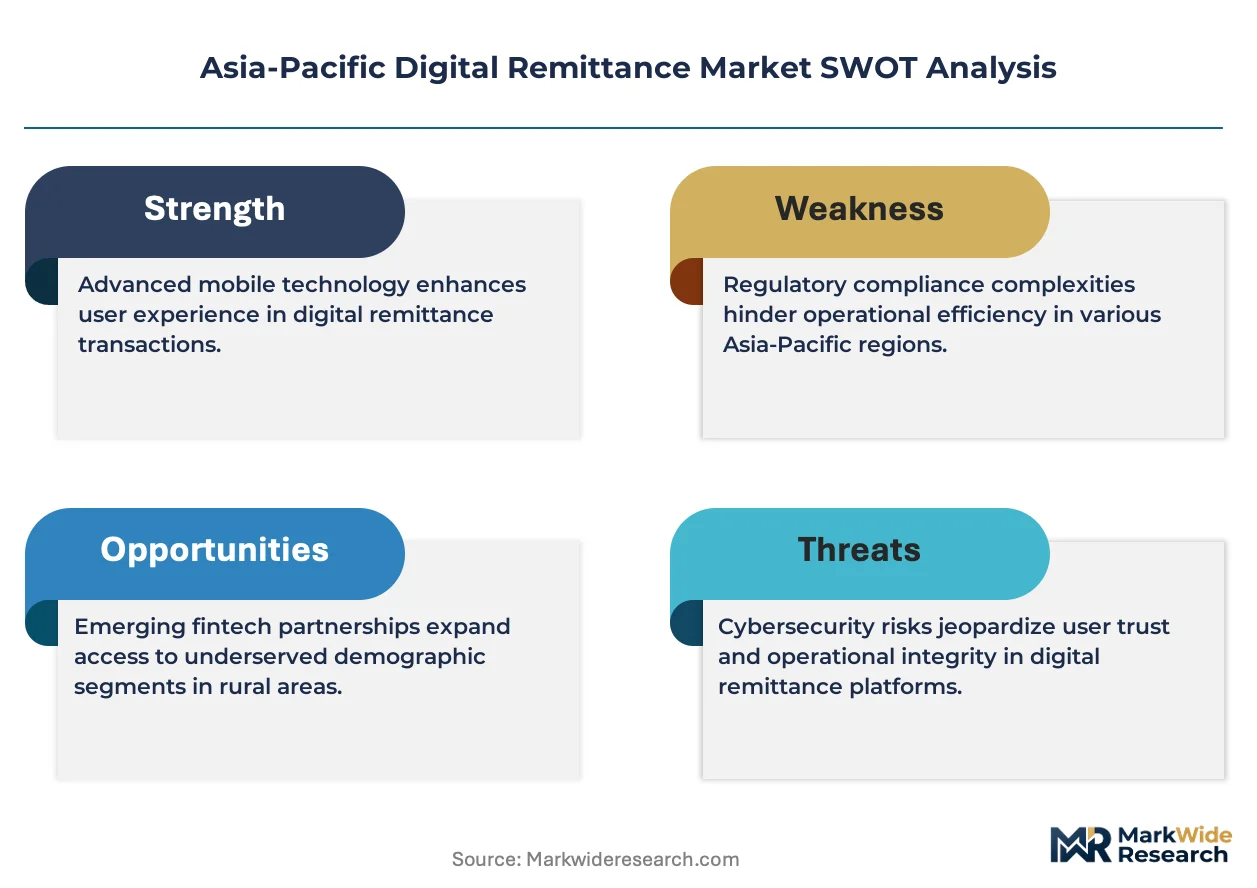
- Regulatory fragmentation:Divergent licensing requirements between Australia's AUSTRAC and the Philippines' Bangko Sentral ng Pilipinas force redundant compliance expenditure.
Strategic Opportunities
- Vietnam-GCC corridor underpenetration:Mobile wallet penetration lags India and the Philippines, creating first-mover space for neobank partnerships.
- Blockchain-DLT convergence:Distributed ledger settlement channels bypass correspondent delays and enable programmable compliance for intra-ASEAN B2B flows.
- Subscription-based premium tiers:Guaranteed exchange rate products monetize price-sensitive migrant workers through predictable fee structures.
Industry Challenges
- Two-factor authentication integration:RBI-mandated security layers complicate user experience design for underbanked populations with limited device sophistication.
- Cross-border data localization:Australia's privacy frameworks and Singapore's AML protocols create architectural conflicts for unified platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Remittance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Business-to-Business, Business-to-Consumer, Government Transfers Technology: Mobile Applications, Blockchain, Web Platforms, Payment Gateways Transaction Method: Bank Transfer, E-wallets, Cash Pickup, Credit/Debit Cards Customer Type: Expatriates, Migrant Workers, Corporates, Students |
| Companies Covered | Wise PLC, PayPal Holdings Inc., Remitly Inc., MoneyGram International Inc., WorldRemit Ltd., InstaReM, Ripple Labs Inc., NIUM Pte. Ltd., Azimo Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Remittance Market Evolving Landscape
Digital remittance infrastructure across Asia-Pacific is bifurcating between real-time retail rails and programmable wholesale settlement layers, with regulatory divergence acting as the primary forcing function on technology investment.
Blockchain-based settlement channels are absorbing correspondent banking volume in high-frequency corridors. Migrant worker platforms serving India-GCC and Philippines-GCC routes are piloting stablecoin bridges to compress settlement from T+2 to T+0. This compression is absorbing forex hedging expenditure previously allocated to nostro-vostro liquidity buffers.
Singapore's Payment Services Act enforcement is tightening licensing scrutiny for cross-border fintech operators. The Monetary Authority's anti-money laundering protocols now mandate transaction monitoring thresholds that reshape product architecture. Neobank white-label partners are responding by embedding modular compliance engines directly into customer onboarding flows.
Subscription pricing models are displacing per-transfer fees in customer acquisition strategies. Migrant workers in domestic services and construction verticals are migrating toward guaranteed exchange rate products that eliminate quote uncertainty. This behavioral shift is most visible in India-originated corridors where UPI familiarity has preconditioned users to expect price transparency.
Asia-Pacific Digital Remittance Market Segmentation
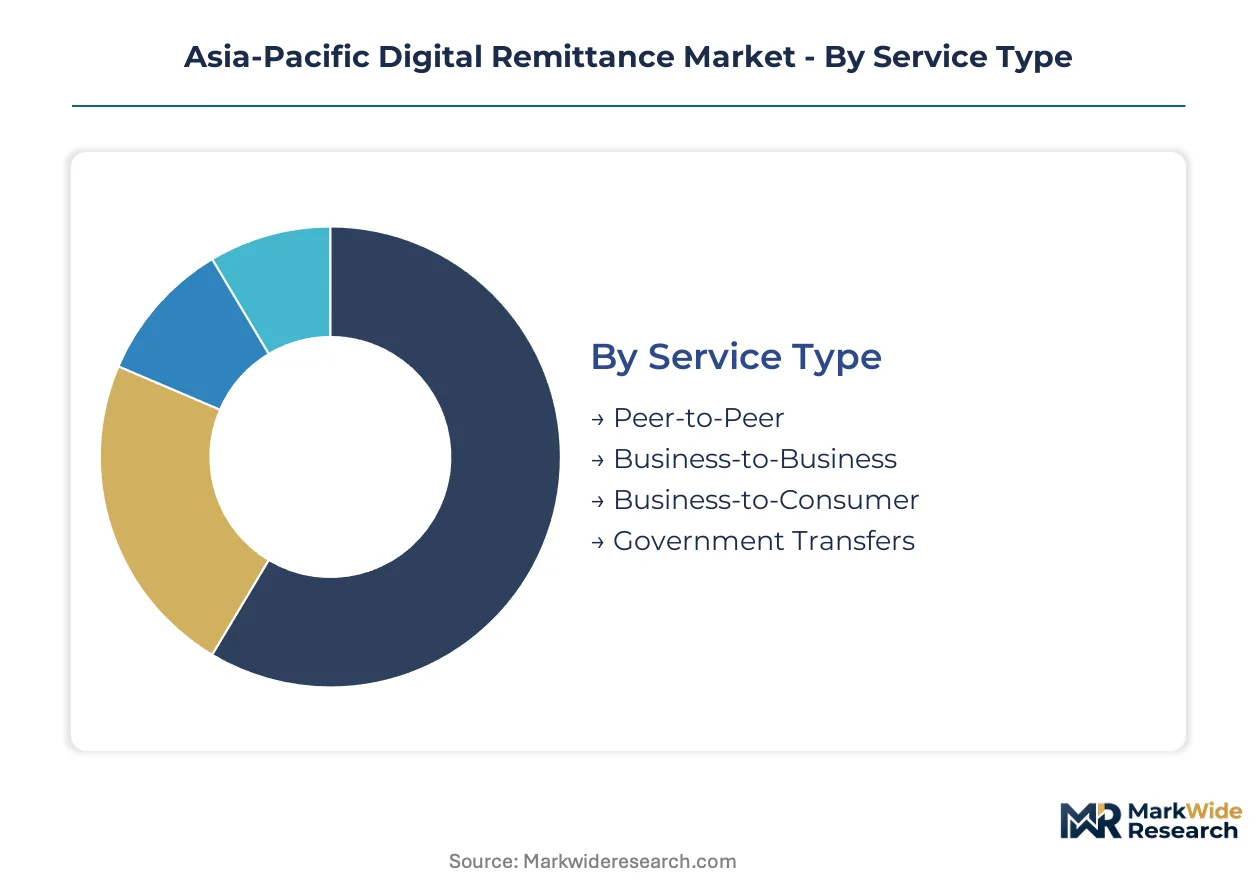
Segmentation in Asia-Pacific digital remittance reveals how corridor economics, regulatory exposure, and user sophistication split platform investment priorities. Each dimension exposes different margin pools and compliance burdens for operators competing across India-GCC and Southeast Asian corridors.
Service Type:
Buyer differentiation in this category tracks transfer scale, frequency, and regulatory scrutiny intensity.
- Peer-to-Peer:Individual transfers from migrant workers to family members in home countries. Demand concentrates in India-GCC and Philippines-GCC corridors where construction and domestic service workers remit monthly salaries. UPI familiarity in India has preconditioned users to expect real-time settlement and fee transparency.
- Business-to-Business:Cross-border settlements between enterprises, particularly intra-ASEAN trade corridors. Singapore's Payment Services Act licensing requirements and AUSTRAC thresholds in Australia force redundant compliance expenditure on unified platform architectures.
- Business-to-Consumer:Salary disbursements and vendor payments from employers to individual recipients. Mobile-first onboarding dominates in Vietnam where wallet penetration lags India and the Philippines.
- Government Transfers:Social benefit distributions and public sector payments. RBI-mandated two-factor authentication complicates user experience design for underbanked populations with limited device sophistication.
Peer-to-Peer leads volumes today; Business-to-Business is gaining share fastest.
Technology:
Technology choice reflects settlement speed requirements against infrastructure maturity and central bank tolerance for non-bank rails.
- Mobile Applications:Smartphone-native platforms with biometric KYC and real-time notifications. Remitly anchors growth on mobile-first onboarding tailored to underbanked migrant worker populations in the Philippines and India.
- Blockchain:Distributed ledger settlement channels bypassing correspondent banking delays. Stablecoin bridges are piloting T+0 compression in high-frequency corridors, absorbing forex hedging expenditure previously allocated to nostro-vostro liquidity buffers.
- Web Platforms:Browser-based interfaces for desktop users and corporate treasury functions. Concentrated margin pools exist in intra-ASEAN trade settlements where regulatory fragmentation complicates unified deployment.
- Payment Gateways:API-integrated infrastructure enabling white-label remittance capabilities. NIUM differentiates through modular banking-as-a-service extending to regional neobanks.
Mobile Applications dominate user acquisition today; Blockchain is climbing the fastest as operators seek to bypass SWIFT rails.
Transaction Method:
Method selection tracks banking access depth, cash preference persistence, and wallet infrastructure maturity across origin and destination markets.
- Bank Transfer:Direct account-to-account movement through licensed banking networks. Legacy SWIFT rails in Singapore and Hong Kong maintain fee structures that erode margin on low-value transfers.
- E-wallets:Stored-value account transfers through mobile money platforms. GCash in the Philippines and Paytm in India have built dense agent networks that compress last-mile delivery costs.
- Cash Pickup:Physical collection at agent locations for unbanked recipients. Demand persists in rural Vietnam and Philippine provinces where formal banking penetration remains shallow.
- Credit/Debit Cards:Card-funded transfers for urgent or unplanned remittances. Higher interchange fees limit scalability for recurring low-value flows.
Bank Transfer retains the largest volume base; E-wallets are expanding most quickly as UPI and similar rails proliferate.
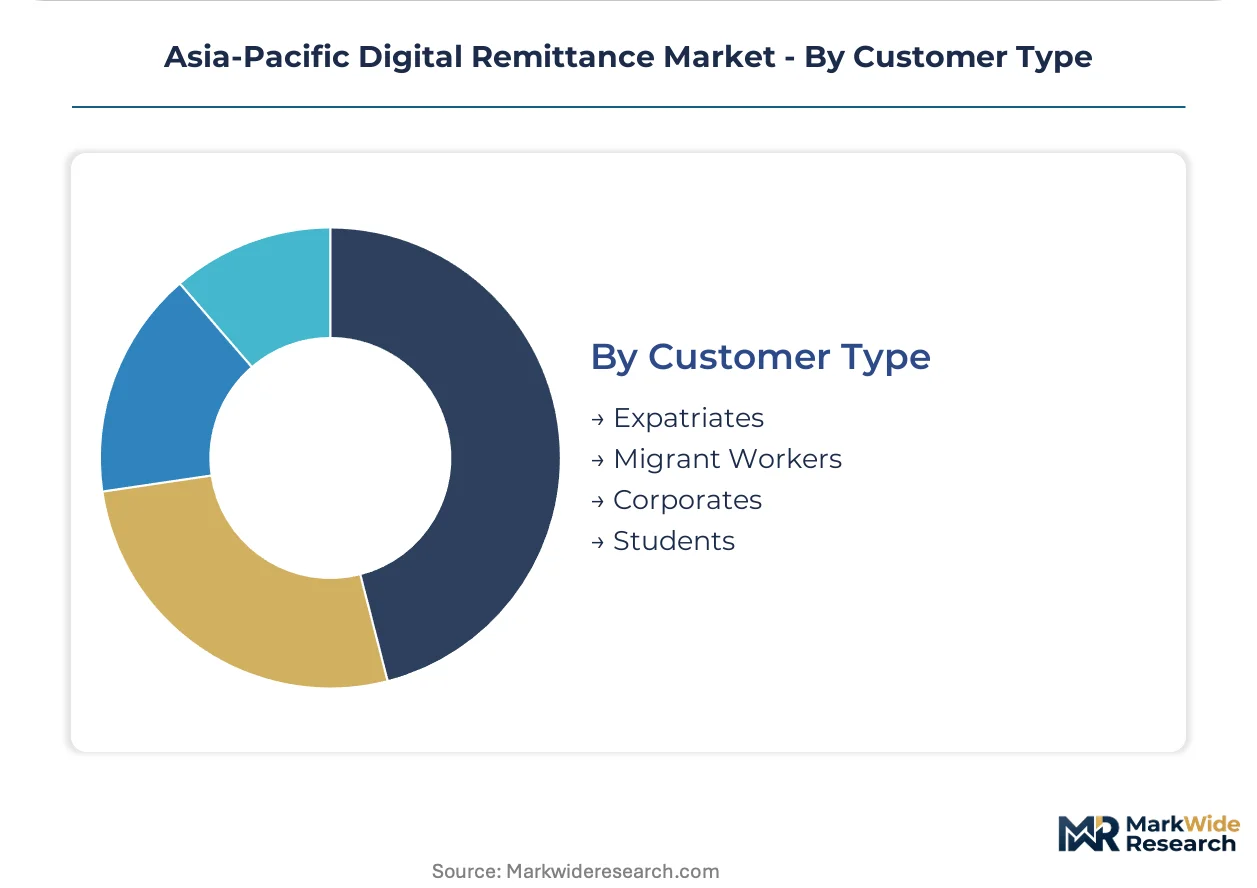
Customer Type:
Customer segmentation exposes divergent price sensitivity, documentation capacity, and platform loyalty patterns.
- Migrant Workers:Construction and domestic service employees remitting regular portions of salary. Subscription-based premium tiers with guaranteed exchange rates are repositioning how platforms monetize this price-sensitive base.
- Expatriates:Professional and managerial employees with higher transfer values and documentation sophistication. Wise leverages real-time mid-market pricing to sustain competitive edge across Southeast Asian corridors serving this segment.
- Corporates:Enterprises managing payroll, supplier payments, and treasury operations. Central bank digital currency pilots across ASEAN member states are creating infrastructure for instantaneous B2B settlements.
- Students:Cross-border education fee payers and living expense senders. Seasonal demand spikes align with academic calendar enrollment periods.
Migrant Workers generate the highest transaction frequency today; Corporates are gaining share fastest as intra-ASEAN trade volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping platform deployment across Asia-Pacific as operators migrate compliance infrastructure toward jurisdictions with harmonized licensing frameworks and real-time settlement rails.
India
RBI-mandated two-factor authentication and UPI interoperability are driving platform architecture decisions for migrant worker corridors. The Payment and Settlement Systems Act enforces KYC tiering that reduces onboarding friction for construction sector remitters. Mumbai and Bangalore host dense fintech clusters where neobanks are embedding modular compliance engines into customer acquisition flows.
Singapore
The Payment Services Act is compressing licensing timelines for cross-border operators while tightening AML scrutiny. MAS transaction monitoring thresholds are forcing product redesign around real-time verification rails. The city-state's financial district anchors regional headquarters for blockchain settlement pilots targeting T+0 compression in GCC corridors.
Philippines
Bangko Sentral ng Pilipinas thresholds on transaction monitoring shape mobile-first onboarding for domestic service workers remitting to rural provinces. GCash wallet penetration in Metro Manila is compressing last-mile delivery costs for cash pickup alternatives. Cebu and Davao are emerging as secondary hubs for agent network expansion.
Vietnam
Mobile wallet penetration lags regional peers, creating first-mover space for neobank partnerships in construction and manufacturing corridors. The State Bank of Vietnam is piloting central bank digital currency infrastructure that could enable instantaneous settlement with ASEAN neighbors. Ho Chi Minh City concentrates fintech development activity targeting underbanked migrant populations.
Australia
AUSTRAC transaction monitoring requirements are forcing redundant compliance expenditure for operators seeking unified platform deployment across Asia-Pacific. Sydney and Melbourne host corporate treasury functions that drive B2B corridor demand for programmable settlement layers. Privacy framework conflicts with Singapore's AML protocols complicate cross-border data architecture.
Asia-Pacific Digital Remittance Market Competitive Landscape
Branded specialists and white-label infrastructure providers split share differently across peer-to-peer and B2B segments. The market exhibits tiered concentration with global remittance platforms, regional neobank partners, and blockchain settlement specialists occupying distinct competitive positions. Strategic archetypes include mobile-first migrant worker specialists, real-time pricing transparent platforms, and modular banking-as-a-service infrastructure providers. Dominant competitive moves center on API-integrated compliance partnerships and subscription-based pricing model displacement of per-transfer fees.
Within the real-time pricing tier, Wise PLC and Remitly Inc. exemplify divergent customer acquisition strategies. Wise leverages mid-market rate transparency to anchor professional expatriate segments across Southeast Asian corridors. Remitly targets underbanked migrant worker populations through mobile-first onboarding optimized for Philippines and India origins. NIUM Pte. Ltd. occupies the infrastructure layer, extending white-label remittance capabilities to regional neobanks through modular banking-as-a-service architecture.
| Leading Market Players |
|---|
| Wise PLC |
| PayPal Holdings Inc. |
| Remitly Inc. |
| MoneyGram International Inc. |
| WorldRemit Ltd. |
| InstaReM |
| Ripple Labs Inc. |
| NIUM Pte. Ltd. |
| Azimo Limited |
| Others |
Value Network & Pricing Analysis
Migrant worker concentration in India-GCC and Philippines-GCC corridors anchors the dominant subscription-based pricing model, where guaranteed exchange rate products monetize price-sensitive construction and domestic service employees through predictable monthly fee structures rather than per-transfer charges.
Pricing Analysis
Capacity additions in Singapore and India are reshaping price floors for real-time settlement infrastructure as neobank partnerships proliferate. Three-tier pricing structure across premium guaranteed-rate, standard mid-market, and economy variable-rate levels segments buyers by documentation capacity and transfer urgency. Pricing pressure stems from unhedged rupee-dirham and peso-riyal exposures compressing margins during currency volatility periods. Migrant workers in construction verticals exhibit highest price sensitivity, while corporate treasury functions in intra-ASEAN B2B corridors accept premium pricing for programmable compliance features.
Supply Chain Analysis
Single-source vulnerability sits with Singapore's correspondent banking infrastructure for SWIFT rail access and India's UPI stack for retail settlement interoperability. Core technology inputs draw from licensed payment service providers in Singapore, API-integrated compliance engine developers in India, and blockchain settlement specialists piloting stablecoin bridges. Supply chain risk centers on regulatory fragmentation between Australia's AUSTRAC thresholds and Singapore's MAS protocols forcing redundant compliance architecture. Distribution runs through mobile application stores, white-label neobank partnerships, and agent networks in Philippine provinces and rural Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Singapore's Payment Services Act enforcement timeline and India's RBI KYC tiering mandates are accelerating platform consolidation and compliance infrastructure investment across the Asia-Pacific corridor.
For Market Incumbents: Hedge correspondent banking concentration risk by piloting blockchain-DLT settlement channels that bypass SWIFT rails in high-frequency GCC corridors. Anchor defensive positioning through backward integration into modular compliance engine development, reducing reliance on third-party KYC tiering providers as MAS and AUSTRAC thresholds tighten. Acquire specialist blockchain settlement capabilities before T+0 infrastructure becomes table stakes. For New Entrants and Emerging Players: Stablecoin bridge technology offers the most penetrable wedge for Vietnam-GCC corridor entry where mobile wallet penetration lags India and Philippines. Target underbanked construction workers in Ho Chi Minh City manufacturing hubs through agent network partnerships rather than direct digital onboarding. Lead with subscription pricing transparency to differentiate from incumbent per-transfer fee structures. For Investors and Strategic Acquirers: Regional neobanks are the most active acquirer in this space, seeking white-label remittance infrastructure to embed in mobile-first customer acquisition flows. Long-term viability rests on platform scale in at least two major GCC corridors and regulatory licensing in both Singapore and India. Watch central bank digital currency pilot convergence across ASEAN as the inflection signal for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| API-Integrated Compliance Partnership | MAS and RBI licensing requirements force real-time KYC tiering into customer onboarding flows. |
| Blockchain Settlement Pilot | Stablecoin bridges absorb forex hedging costs previously allocated to nostro-vostro liquidity buffers. |
| Neobank White-Label Expansion | Modular banking-as-a-service architecture extends remittance capabilities to underbanked migrant populations. |
| Subscription Pricing Rollout | Guaranteed exchange rate products monetize price-sensitive workers through predictable monthly fee structures. |
| Agent Network Densification | Physical collection points in rural Vietnam and Philippine provinces address cash preference persistence. |
Research Methodology
Coverage spans South Asia, Southeast Asia, and GCC destination markets, with primary inputs from each region combining structured interviews with platform compliance officers, neobank partnership leads, migrant worker focus groups, and central bank regulatory affairs specialists. Secondary validation draws from MAS licensing disclosures, RBI Payment and Settlement Systems Act circulars, AUSTRAC transaction monitoring guidelines, and ASEAN central bank digital currency pilot documentation. Bottom-up corridor volume estimates and top-down regional market sizing were triangulated to produce consistent value and growth projections.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by service type, technology platform, transaction method, and customer archetype. Modeled dimensions include peer-to-peer versus B2B corridor economics, mobile application versus blockchain settlement infrastructure, and migrant worker versus corporate treasury customer profiles. CAGRs were derived from historical corridor flow analysis projected against regulatory implementation timelines and technology adoption curves. Industry-specific forecast inputs encompass UPI transaction growth rates and GCC labor migration policy shifts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to central bank digital currency interoperability decisions and correspondent banking fee structure evolution. Forecasts reflect documented assumptions about regulatory harmonization pace and technology pilot conversion rates. Specific risk factors that could revise projections include RBI two-factor authentication mandate changes, MAS AML protocol tightening, and ASEAN CBDC pilot divergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
US Gift Card and Incentive Card Market
Payments
Africa Mobile Money Market
Payments
UAE Card Payments Market
Payments
Germany Real Time Payments Market
Payments
North America Payments Market
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Cross-Border Payment Platform Market
Payments
GCC Payment Gateway Market
Payments
Spain Real Time Payments Market
Payments
Russia Payments Market
Payments
Smart Home Payments Market
Payments
Norway Mobile Payments Market
Payments
Digital Remittance Service Market
Payments
Global Gift Card Market
Payments
Telecom Cloud Billing Market
Payments
Europe Credit Cards Market