
 Europe Fuel Cards Market | 2026-2036
Europe Fuel Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fuel Cards Market Intelligence
The integration of EV charging and telematics data is redrawing the strategic boundaries for fuel card providers in Europe. TotalEnergies leverages its extensive multi-energy station network to offer hybrid fuel and EV charging cards. BP p.l.c. competes by bundling advanced analytics with its fuel card services for large logistics fleets. DKV Euro Service specializes in providing multi-vendor toll and fuel solutions across multiple European countries.
A fuel card is a specialized payment instrument for managing fuel and related vehicle expenses within commercial fleets. These cards operate on proprietary networks, capturing Level 3 data such as odometer readings and driver IDs for enhanced transaction security and reporting. Multi-vendor cards dominate the market, offering fleets flexibility across different fuel brands and countries. Within service types, vehicle tracking and maintenance services represent the fastest-growing additions to core fuel purchase offerings, particularly for the logistics end-user segment.
The European Union's GDPR framework governs the handling of driver and vehicle data collected through telematics-integrated fuel card systems. Additionally, the Corporate Sustainability Reporting Directive (CSRD) compels large fleet operators to track and report on fuel consumption and emissions, directly influencing demand for advanced card features. Providers must now decide how to balance investment between legacy diesel networks and the expanding infrastructure for electric vehicle charging.
Market Dynamics
The fundamental market dynamic is the strategic tension between maintaining legacy diesel fuel networks and investing in a fragmented, rapidly expanding electric vehicle charging infrastructure. This dual-network challenge, intensified by European Union regulatory pressure on emissions, forces providers to evolve from fuel resellers into integrated energy and data management partners for commercial fleets.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) requires large companies to disclose detailed emissions data, directly stimulating demand for fuel cards with advanced tracking and analytics to automate this reporting.
- Logistics Sector Demands:Growth in European e-commerce and freight transport increases the need for sophisticated fleet management tools, with fuel cards providing essential control over expenses and driver spending across borders.
- Telematics Integration:The convergence of fuel payment data with vehicle telematics provides fleet managers with powerful insights into driver behavior, fuel efficiency, and route optimization, creating a strong value proposition beyond simple payment processing.
Market Restraints
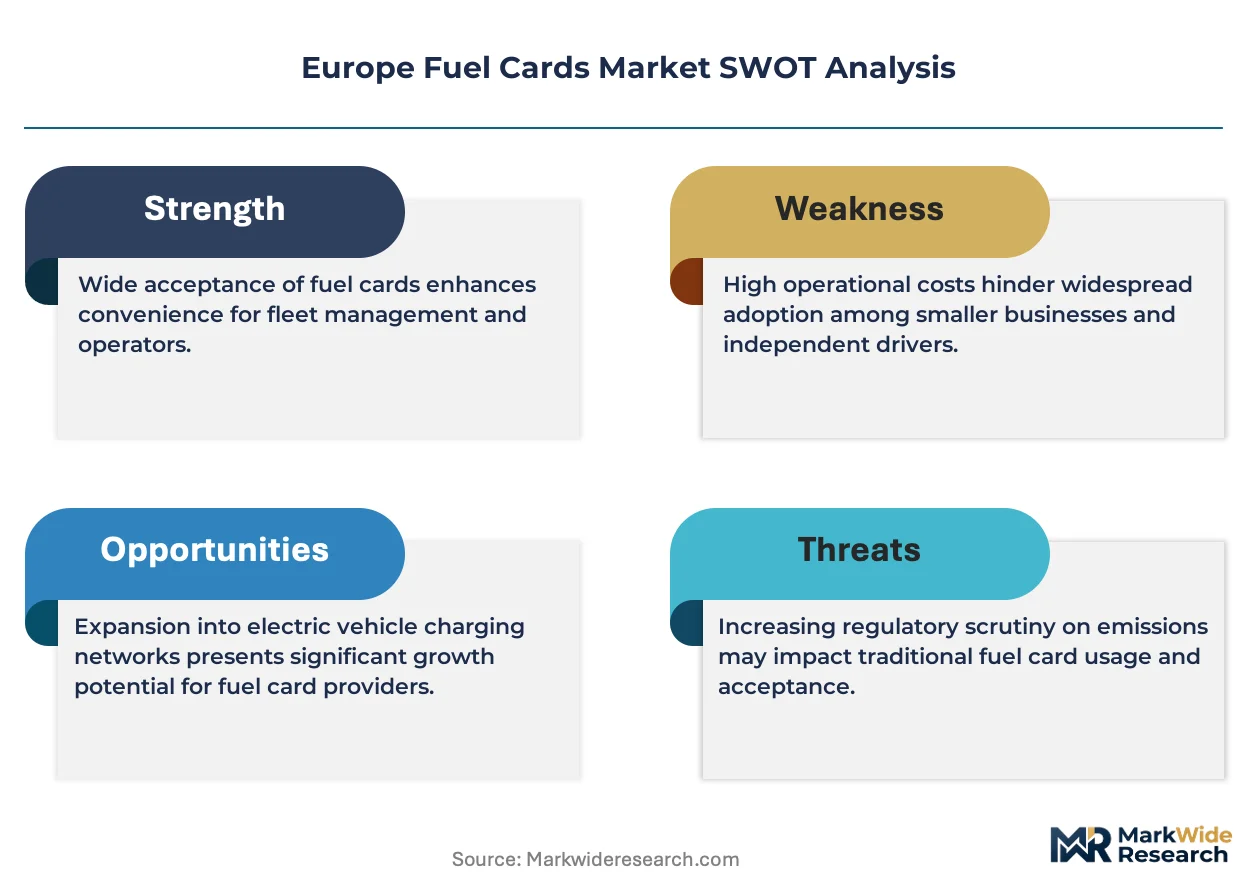
- High Capex for EV Infrastructure:The significant capital investment required to build out a proprietary or partnered EV charging network that rivals the coverage of existing fuel stations presents a major barrier for providers.
- GDPR Compliance Complexity:Strict data privacy rules under the GDPR framework create compliance burdens and legal risks for handling sensitive driver and vehicle data collected through telematics-linked fuel card systems.
- Interoperability Hurdles:The lack of a universal standard for EV charging plugs and payment protocols across Europe complicates the development of truly seamless, multi-vendor cards that work at every charging point.
Strategic Opportunities
- Value-Added Service Bundling:Providers can expand beyond fuel by integrating toll payments, parking fees, and vehicle maintenance services onto a single card and platform, creating a comprehensive mobility expense management solution.
- Eastern Europe Expansion:Targeting the growing logistics and freight markets in Eastern European countries offers a significant opportunity for providers offering strong cross-border network coverage and multi-currency support.
- Hybrid Fleet Solutions:Developing specialized cards and software platforms that cater to mixed fleets of diesel, petrol, and electric vehicles allows providers to capture clients managing the long-term transition to EVs.
Industry Challenges
- Legacy System Integration:A primary operational challenge is integrating modern API-based EV charging payment systems and data analytics platforms with older, batch-based processing systems used for traditional fuel transactions.
- Cybersecurity Threats:The increasing volume of valuable Level 3 transaction data and telematics information makes fuel card networks a high-value target for fraud and cyberattacks, requiring continuous investment in security.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fuel Cards Market |
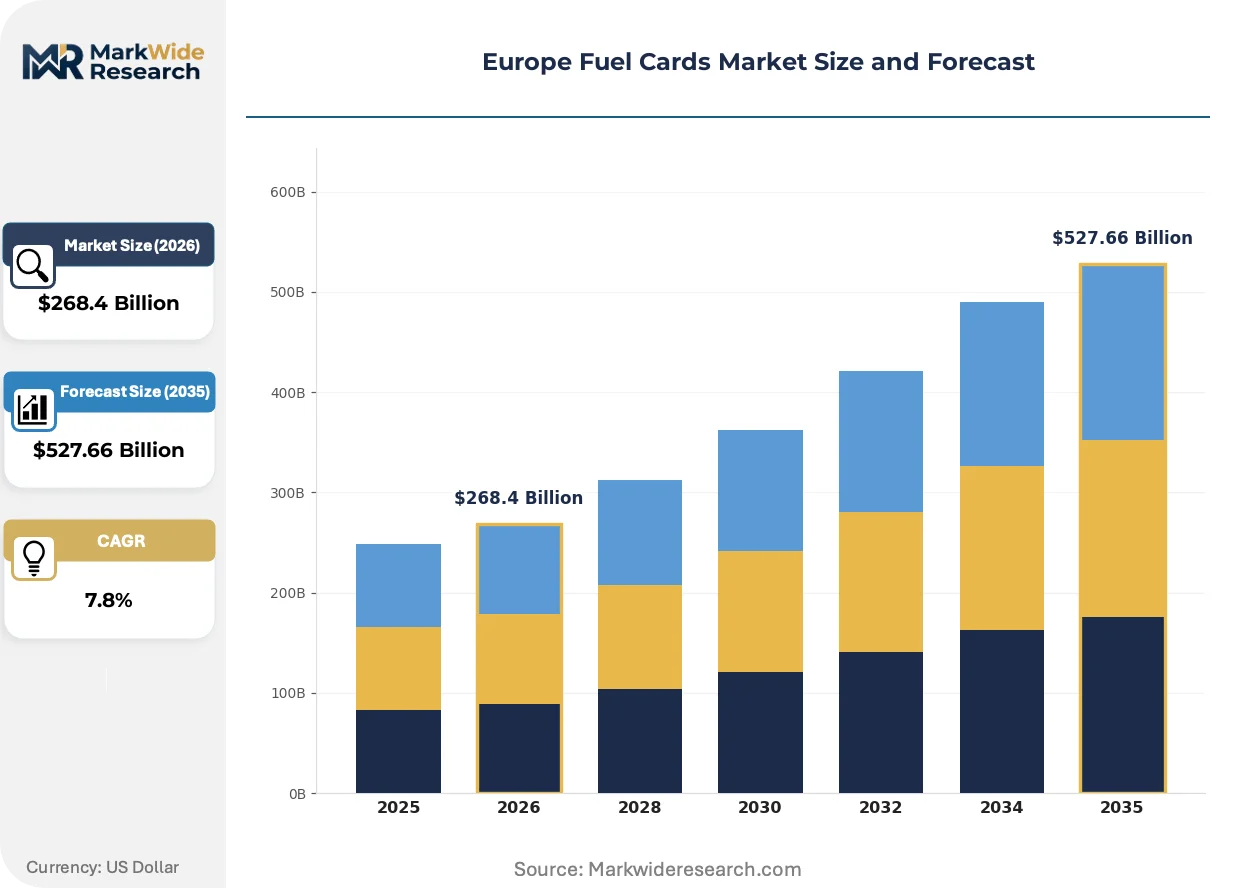
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $527.66 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Single Vendor, Multi-Vendor, Fleet Management, Fuel Only, Hybrid Cards End User Industry: Logistics, Public Transportation, Construction, Agriculture, Emergency Services Transaction Mode: Online Payment, POS Terminal, Mobile App, Automated Toll Payment, Contactless Payment Service Type: Fuel Purchase, Maintenance & Repair, Roadside Assistance, Toll Payments, Vehicle Tracking |
| Companies Covered | WEX Inc., Exxon Mobil Corporation, BP p.l.c., DKV Euro Service, Engen Petroleum Ltd., Royal Dutch Shell plc, TotalEnergies, Repsol, FleetCor Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fuel Cards Market Strategic Shifts & Innovations
The evolution from a payment tool to a data-centric platform is the central theme in the European fuel card market. This transformation is driven by the need to manage the complexities of mixed-energy fleets and comply with stringent environmental reporting standards set by the European Union.
API-driven data integration platforms provide a unified connection between fuel card transactions, telematics, and enterprise resource planning systems. Large logistics fleets are rapidly adopting this technology to achieve a single, real-time view of their total energy consumption and operating costs. This integrated data approach is displacing the use of siloed, single-function payment cards and the associated manual expense reconciliation processes.
The EU Green Deal and its associated "Fit for 55" package create a powerful regulatory tailwind. This policy forces fleet operators to meticulously track and report carbon emissions from transport activities to meet reduction targets. Consequently, heavy-duty vehicle fleets engaged in cross-border transport are prioritizing fuel card solutions that offer certified CO2 emissions reporting and analytics for compliance.
A distinct behavioral shift sees fleet managers prioritizing network flexibility over traditional brand loyalty. This disrupts the legacy model of major oil companies using proprietary cards to lock in commercial customers, favoring instead providers with broad, multi-brand acceptance. The trend is most visible in Central Europe, where extensive cross-border freight activity demands seamless access to fueling, tolling, and charging points across different countries and vendors.
Europe Fuel Cards Market Segmentation
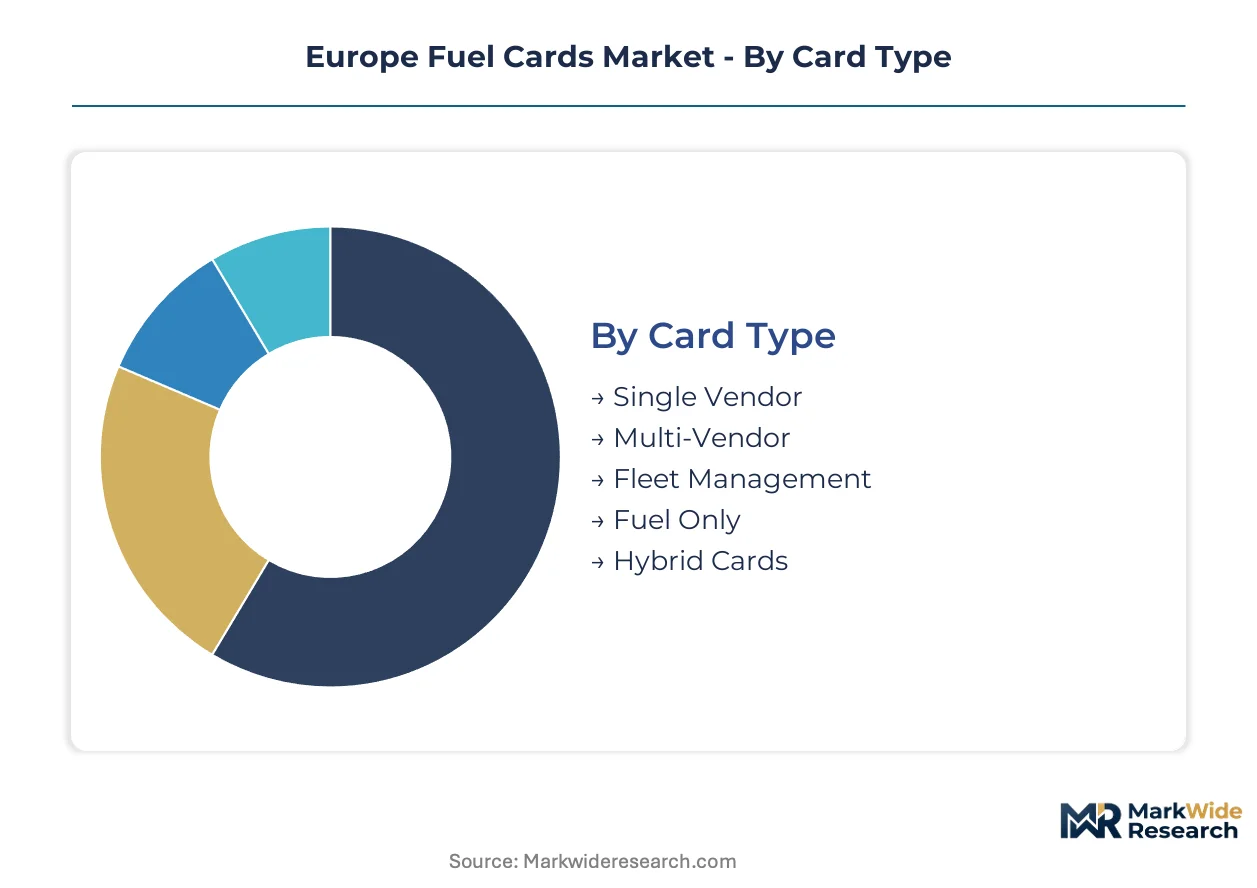
Understanding the segmentation of the Europe Fuel Cards market is essential for providers to tailor offerings that meet diverse fleet operational needs and navigate the complex regulatory landscape. This granular analysis reveals where demand is strongest and how service evolution is occurring across the region.
Card Type:
The diverse regulatory landscape across European nations influences the design and utility of various fuel card types, particularly regarding data collection and reporting requirements.
- Multi-Vendor:These cards offer broad acceptance across different fuel brands and countries, directly addressing the need for cross-border flexibility in European freight transport. Their robust data capabilities are crucial for CSRD compliance.
- Hybrid Cards:These cards support both traditional fuel and electric vehicle charging, providing a transitional solution for fleets adapting to the EU Green Deal's emissions reduction targets. They simplify expense management for mixed fleets.
- Single Vendor:These cards are tied to a specific fuel brand's network, often used by smaller, localized fleets with consistent routes within one country.
- Fleet Management:These cards integrate payment with comprehensive fleet management software, offering advanced data insights for operational efficiency and cost control.
- Fuel Only:Primarily used for fuel purchases, these basic cards provide straightforward expense tracking without additional integrated services.
Multi-Vendor cards handle the majority of throughput; Hybrid Cards are the fastest mover on share.
End User Industry:
Different end-user industries exhibit distinct operational demands and regulatory pressures that shape their specific fuel card requirements.
- Logistics:This sector drives significant demand for advanced fuel cards, requiring detailed expense tracking and emissions reporting for cross-border freight operations. E-commerce expansion across Europe intensifies this need.
- Construction:Construction companies utilize fuel cards for heavy machinery and on-site vehicles, prioritizing robust transaction security and flexible payment options across varied project locations. Efficiency in fuel expenditure directly impacts project profitability.
- Public Transportation:Public transport operators rely on fuel cards for consistent fleet fueling, often integrating with municipal procurement systems for streamlined financial management.
- Emergency Services:These critical services demand reliable, widely accepted fuel cards to ensure uninterrupted operations and rapid response capabilities across their service areas.
- Agriculture:Agricultural businesses use fuel cards for farm machinery and vehicles, valuing ease of use and expense control for seasonal operations.
The Logistics sector drives the largest volume of transactions, while the Construction segment shows expanding demand for specialized solutions.
Transaction Mode:
Technological advancements and evolving user preferences are continually refining the methods through which fuel card transactions are processed across Europe.
- POS Terminal:This traditional method remains foundational for fuel card transactions at physical stations, providing a widely accepted and secure payment interface. Its established infrastructure supports the bulk of current fuel purchases.
- Mobile App:Mobile applications offer enhanced convenience and integrate additional features like station locators and loyalty programs, appealing to younger fleet managers and drivers. This mode facilitates seamless EV charging payments.
- Online Payment:Online payment methods are primarily used for account management, invoicing, and some pre-paid or subscription-based services, offering administrative flexibility.
- Automated Toll Payment:This mode integrates toll charges directly into the fuel card system, streamlining cross-border operations for heavy-duty vehicles and reducing administrative burdens.
- Contactless Payment:Growing in popularity, contactless options provide speed and hygiene at the point of sale, enhancing user experience for quick transactions.
POS Terminal transactions constitute the majority of current usage, with Mobile App adoption showing significant momentum.
Service Type:
Fuel card providers are increasingly offering a tiered range of services beyond core fuel purchases to enhance value and capture a broader share of fleet expenditure.
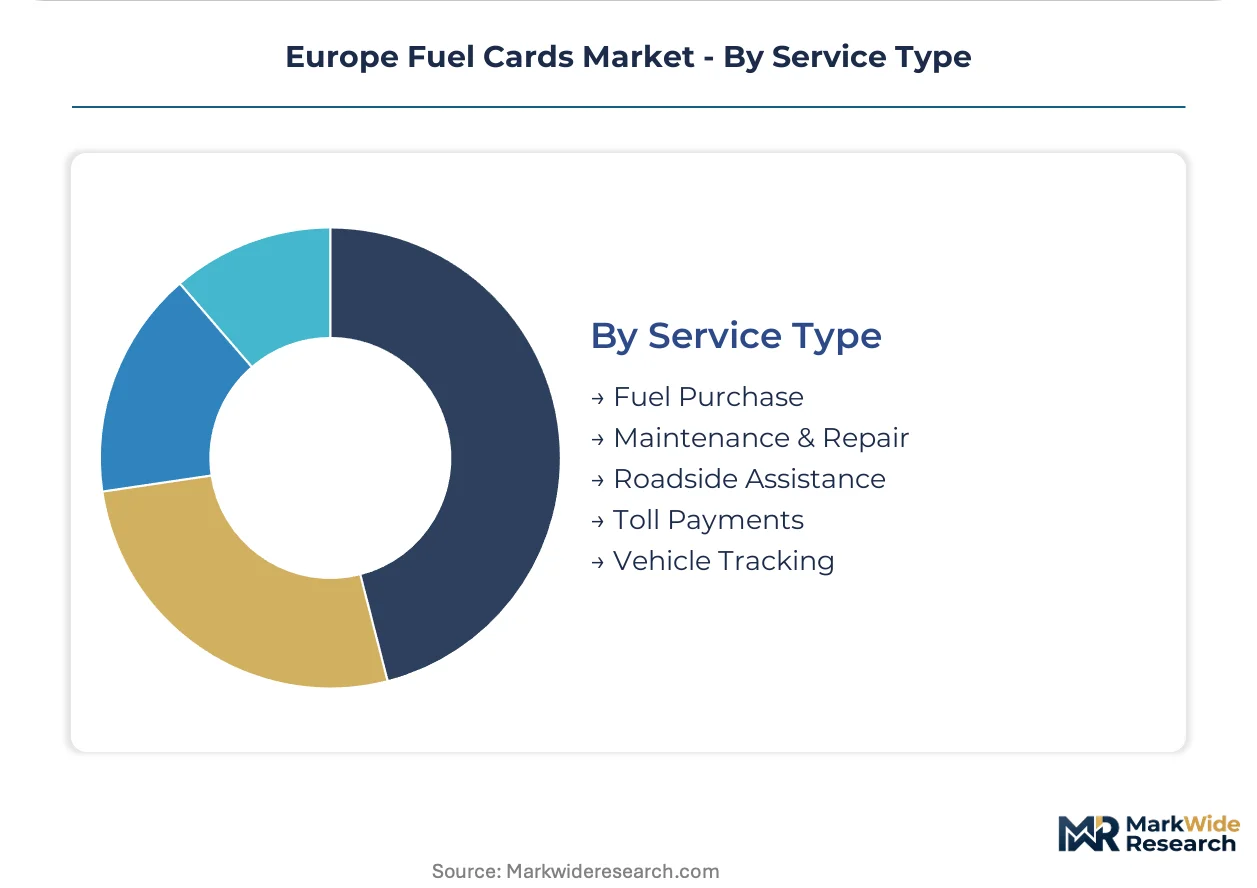
- Fuel Purchase:This core service remains the primary function of fuel cards, enabling secure and controlled acquisition of diesel, petrol, and alternative fuels across Europe. It underpins all other integrated offerings.
- Vehicle Tracking:Integrating telematics data with fuel card transactions provides fleet managers with powerful insights into driver behavior, fuel efficiency, and route optimization. This service supports compliance with environmental reporting.
- Maintenance & Repair:These services allow fleets to manage vehicle upkeep expenses through their fuel card system, simplifying budgeting and reducing administrative overhead.
- Toll Payments:Fuel cards facilitate automated payment of road tolls, particularly beneficial for international logistics fleets operating across multiple European countries.
- Roadside Assistance:Providing emergency support services through the card offers fleet drivers peace of mind and minimizes downtime for commercial vehicles.
Fuel Purchase services form the foundational offering, and Vehicle Tracking is experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for fuel cards remains tied to major energy companies with extensive physical networks across Europe. This market dynamic is now evolving as providers pivot to integrate electric vehicle charging infrastructure, driven by the EU's ambitious climate targets. Regulatory mandates influence demand patterns significantly, pushing fleets towards advanced data solutions for compliance.
Germany
Germany's central role in European freight transport necessitates advanced fuel card solutions for its logistics sector. The country's strong commitment to the EU Green Deal and stringent national emissions targets stimulate demand for cards with robust reporting capabilities. Major logistics hubs like the Rhine-Ruhr region are seeing increased adoption of integrated telematics and fuel card systems.
United Kingdom
The United Kingdom's large and diverse fleet operations drive demand for fuel cards that offer comprehensive vehicle tracking and maintenance services. UK government initiatives for decarbonization, alongside broader environmental reporting pressures, influence fleet managers' choices. London and the Southeast remain key commercial centers, where businesses prioritize efficient expense management and data insights.
France
France's significant domestic logistics market and its strategic position for cross-border transport create demand for multi-vendor fuel and EV charging cards. The country adheres to the EU's Corporate Sustainability Reporting Directive, compelling large operators to track fuel consumption and emissions. The Paris-Lyon corridor, a major freight route, exhibits strong demand for integrated payment and data solutions.
Netherlands
The Netherlands functions as a pivotal European distribution hub, prompting early adoption of hybrid fuel and EV charging cards. Dutch companies are particularly sensitive to the EU's "Fit for 55" package, seeking cards that simplify compliance with emissions reduction targets. The Port of Rotterdam, a major gateway, influences demand for seamless cross-border and multi-energy payment systems.
Poland
Poland's rapidly growing logistics and freight markets offer significant opportunities for fuel card providers with strong cross-border network coverage. Alignment with broader EU regulatory frameworks, including data privacy and environmental reporting, shapes local fleet requirements. Major trade corridors and urban centers like Warsaw are experiencing increased demand for multi-currency and multi-service card solutions.
Europe Fuel Cards Market Key Industry Players
Concentration sits with established energy majors and specialized fleet management solution providers. The market structure is tiered, with large oil companies leveraging existing infrastructure and dedicated fleet card issuers focusing on value-added services. Strategic partnerships between energy providers and technology companies are becoming a dominant competitive move, alongside portfolio diversification into EV charging solutions.
Multi-energy network providers like TotalEnergies exemplify the shift towards integrated fuel and EV charging offerings, leveraging their extensive station footprint. BP p.l.c. represents a focus on bundling advanced analytics with traditional fuel card services, catering to the complex needs of large logistics fleets. DKV Euro Service anchors the segment of specialists providing multi-vendor toll and fuel solutions across diverse European countries.
| Leading Market Players |
|---|
| WEX Inc. |
| Exxon Mobil Corporation |
| BP p.l.c. |
| DKV Euro Service |
| Engen Petroleum Ltd. |
| Royal Dutch Shell plc |
| TotalEnergies |
| Repsol |
| FleetCor Technologies |
| Others |
Cost & Logistics Intelligence
The transition from fossil fuels to electric vehicle charging represents a named substitution dynamic, simultaneously reshaping energy supply geography and pricing economics for European fleets. This shift necessitates investment in new infrastructure while managing existing networks, directly influencing service cost structures.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for advanced fuel card solutions, particularly those offering emissions reporting. The dominant pricing model is a hybrid subscription for value-added services combined with per-transaction charges for fuel and energy. Price differentiation stems from cross-border network coverage and integrated data analytics capabilities. Pricing softness exists for basic fuel-only cards due to commodity price volatility, while advanced solutions command higher value due to regulatory compliance. Small, localized fleets exhibit higher price sensitivity, whereas large logistics operators prioritize comprehensive data and service bundles.
Supply Chain Analysis
High capital expenditure for EV charging infrastructure presents a significant inbound logistics cost for energy providers and card issuers. Geographic supply concentration for traditional fuels remains with major oil companies, while EV charging infrastructure development concentrates in Germany and the Netherlands due to early adoption. The supply chain depends on diesel, petrol, and electricity for charging, alongside payment processing hardware. Interoperability hurdles across diverse EV charging networks pose a structural risk. Distribution runs through multi-vendor acceptance networks and proprietary station footprints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Fuel Cards Market requires a substitution defense against direct payment apps and integrated OEM telematics solutions that threaten traditional revenue streams.
For Market Incumbents: Secure strategic partnerships with EV charging network operators to expand multi-energy acceptance across Europe. Develop API-driven data platforms to integrate telematics and automate CSRD compliance reporting, mitigating the threat from fragmented EV infrastructure. Invest in robust cybersecurity measures to protect sensitive Level 3 transaction data. Consolidate market share through targeted acquisitions of smaller, tech-focused fleet management providers.
For New Entrants and Emerging Players: Differentiate on specialized end-user segments, such as last-mile delivery fleets or niche construction operations, offering tailored solutions. Target underserved Eastern European markets with comprehensive cross-border network coverage and multi-currency support. A strong go-to-market angle involves offering subscription-based, all-in-one mobility expense platforms featuring advanced analytics and seamless EV charging integration for small to medium-sized fleets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional fleet management software providers and independent EV charging aggregators seeking scale. The market demonstrates long-term viability, driven by sustained demand for fleet efficiency and the ongoing energy transition over the next decade. Identify acquisition targets with strong intellectual property in data analytics or established multi-vendor network agreements. The signal to watch is the consolidation of EV charging networks and the adoption of universal payment protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Charging Network Acquisition | Consolidates fragmented infrastructure and expands multi-energy offerings across Europe. |
| Telematics Data Platform Development | Enhances fleet efficiency and automates critical emissions reporting for compliance. |
| Cross-Border Service Expansion | Captures growth in Eastern European logistics markets and diversifies revenue streams. |
| Hybrid Card Product Launch | Addresses the transitional needs of mixed fleets adapting to EU decarbonization mandates. |
| Cybersecurity Investment | Protects sensitive Level 3 transaction data and maintains trust with commercial fleet operators. |
Research Approach
A spread of perspectives from fleet managers, fuel card providers, telematics solution vendors, and logistics operators converged on the working assumptions for this study. This approach combined primary interviews with industry stakeholders and secondary validation from EU regulatory documents, industry association reports, and financial filings of major energy companies. Bottom-up and top-down triangulation ensured robust data integrity.
The forecast framework modeled segmentation dimensions including card type, end-user industry, transaction mode, service type, and regional market dynamics. Compound annual growth rates were derived from historical trends, market growth drivers, and projected technological shifts across the analysis window. Key forecast inputs included projected EV adoption rates, commercial fleet expansion, and regulatory enforcement levels.
Material uncertainties — unforeseen geopolitical events or accelerated EV infrastructure development — sit outside the modeled envelope. Forecasts reflect current policy trajectories and technological adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Forex Prepaid Cards Market
Payments
Global Smart Payment Systems Market
Payments
Bill Splitting Apps Market
Payments
Japan Prepaid Cards Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Poland Payments Market
Payments
Vietnam Payments Market
Payments
Belgium Payments Market
Payments
United Kingdom Payment Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Global Financial Cards and Payments Market
Payments
United States Mobile Payment Market
Payments
Sweden Payments Market
Payments
Biometric Payment Market
Payments
Global Accounts Payable Automation Market
Payments
Global Telecom Billing Market