
 Luxembourg POS Terminals Market | 2026-2036
Luxembourg POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Luxembourg POS Terminals Market Foresight
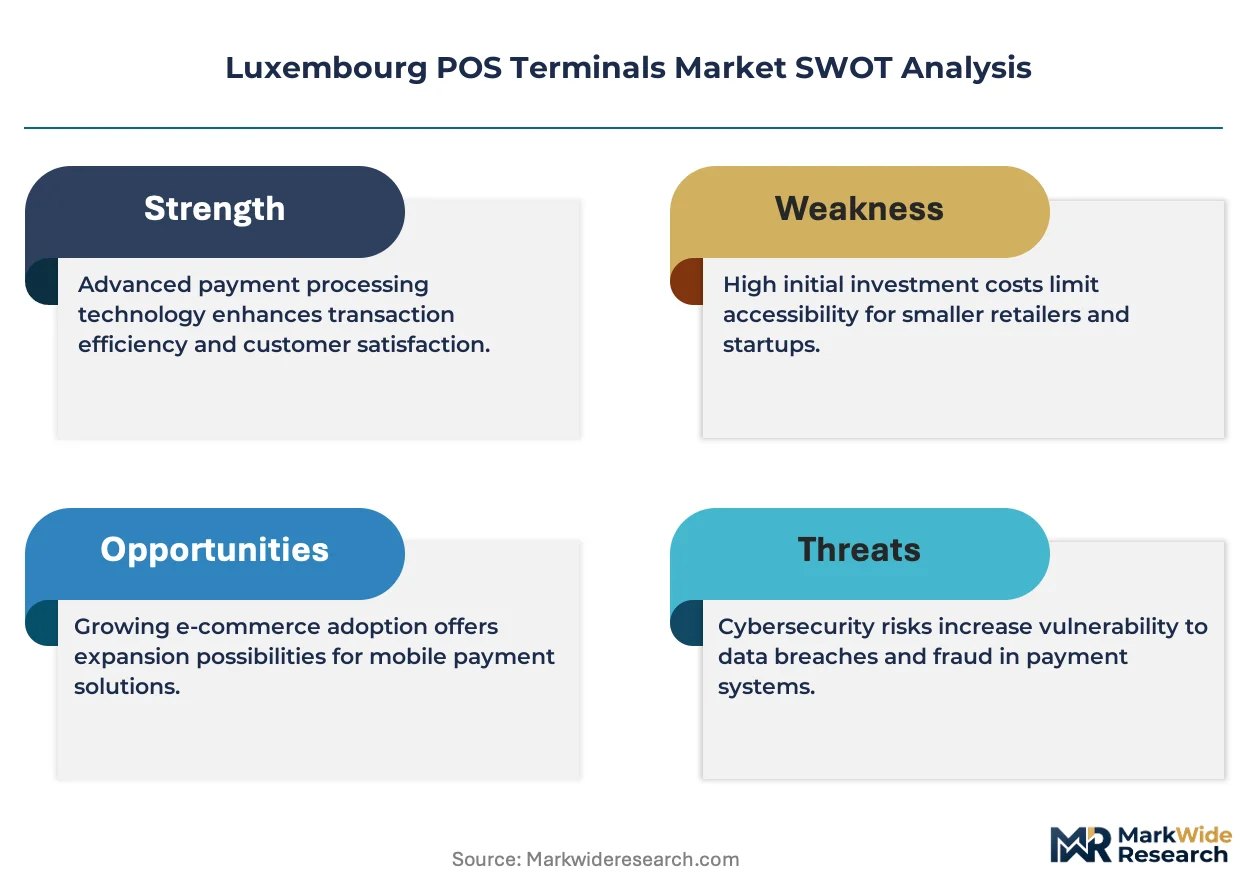
Asset-light leasing models for payment hardware is reconfiguring competitive dynamics among smaller merchants who previously faced high upfront capital barriers. Worldline leverages its European processing infrastructure to sustain merchant relationships across Luxembourg's cross-border commerce corridors. SumUp Inc competes through simplified onboarding for micro-enterprises in Luxembourg's dense hospitality clusters. Adyen differentiates via unified platform architecture that handles multi-currency settlement for the Grand Duchy's international banking clientele.
A POS terminal constitutes an electronic device combining secure microprocessor architecture, encrypted communication modules, and certified payment application software to authenticate and process card-present transactions at the point of sale. These systems integrate EMV chip readers, NFC antennas operating at 13.56 MHz, and PCI-DSS compliant cryptographic processors to enable real-time authorization through acquiring networks. Mobile terminals lead hardware deployment among Luxembourg's pop-up retail and food-truck operators, while cloud solutions capture the fastest expansion as merchants prioritize centralized transaction analytics and remote software management over on-premise server maintenance. NFC-enabled devices concentrate margin pools where contactless transaction volumes justify premium hardware pricing against legacy magnetic stripe configurations.
The European Banking Authority's technical standards under PSD2 mandate strong customer authentication for electronic payments, compelling terminal manufacturers to embed biometric-ready interfaces and dynamic cryptogram generation. Luxembourg's national data protection authority, the CNPD, enforces GDPR compliance across transaction data flows, shaping cloud deployment architectures and cross-border data residency requirements for payment service providers. Stakeholders must monitor how the EU's Digital Operational Resilience Act will impose incident reporting and stress-testing obligations on payment infrastructure operators serving Luxembourg's concentrated financial sector.
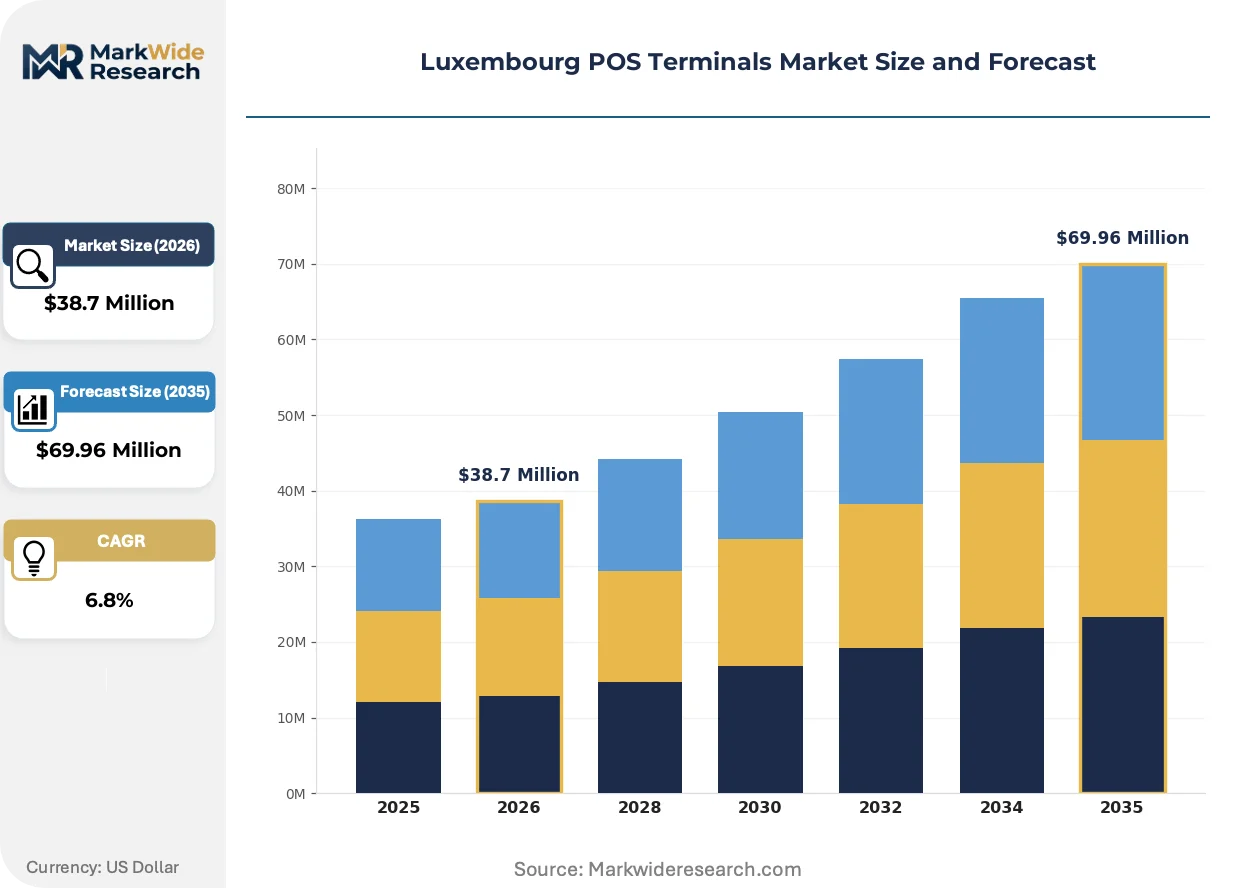
Market Dynamics
PSD2's strong customer authentication mandate is compressing hardware replacement cycles across Luxembourg's merchant base, forcing terminal upgrades that embed biometric interfaces and dynamic cryptogram capabilities ahead of functional end-of-life.
Growth Catalysts
- PSD2 Technical Standards:The European Banking Authority's authentication requirements accelerate terminal refresh cycles among Luxembourg's financial institutions and retail banking corridors.
- Contactless Transaction Volumes:NFC-enabled hardware captures premium positioning as Luxembourg's hospitality and transit sectors drive tap-to-pay adoption rates above European averages.
- Cloud Deployment Architectures:Centralized transaction analytics and remote software management reduce on-premise server maintenance burdens for Luxembourg City's dense merchant clusters.
Market Restraints
- GDPR Compliance Costs:Luxembourg's CNPD enforces stringent data residency requirements across cross-border transaction flows, elevating cloud infrastructure expenditure for payment service providers.
- Hardware Supply Concentration:Secure microprocessor and encrypted communication module sourcing concentrates among Asian semiconductor foundries, exposing Luxembourg deployers to geopolitical supply friction.
- Legacy Magnetic Stripe Infrastructure:Residual dependence on outdated card-reading technology in peripheral retail zones delays full NFC ecosystem maturation.
Strategic Opportunities
- Biometric-Ready Interface Integration:Fingerprint and facial recognition modules converge with EMV chip architecture to enable seamless authentication for Luxembourg's high-value transaction corridors.
- Pop-Up Retail and Food-Truck Mobility:Battery-powered mobile terminals with cellular connectivity address underserved micro-merchant segments in Luxembourg's seasonal hospitality markets.
- Cross-Border Commerce Corridors:Multi-currency settlement capabilities position Luxembourg terminals for Belgian, French, and German transient commerce volumes.
Industry Challenges
- PCI-DSS Certification Timelines:Cryptographic processor validation and payment application software approval cycles extend product launch windows for terminal manufacturers serving the Grand Duchy.
- Embedded Systems Talent Scarcity:Firmware engineering and secure element programming expertise concentrates among a limited pool of specialists across the Benelux region.
- Legacy System Integration Complexity:ERP and inventory management connectivity requirements fragment deployment specifications across Luxembourg's heterogeneous merchant technology stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxembourg POS Terminals Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Terminals, Fixed Terminals, Multilane Terminals, NFC-enabled Devices End User: Retail Stores, Restaurants, Hospitality, Transportation Technology: Contactless Payment, Chip & PIN, Magnetic Stripe, QR Code Deployment: On-premise Solutions, Cloud Solutions, Hybrid Solutions, Integrated Solutions |
| Companies Covered | Worldline, SumUp Inc, myPOS World Ltd, Payconiq International, VeriFone Inc, SIX Payment Services, Adyen, Ingenico Group, PAX Global Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxembourg POS Terminals Market Shifts & Advancements
Terminal architecture is pivoting from isolated payment devices toward integrated commerce platforms that bundle transaction processing with merchant analytics, inventory synchronization, and customer relationship management.
SoftPOS technology that transforms commercial smartphones and tablets into certified payment acceptance devices is rendering obsolete dedicated single-function hardware for micro-merchants and mobile operators. Luxembourg's pop-up retail vendors and independent food-truck operators adopt these SDK-based solutions to eliminate separate terminal procurement. The shift compresses addressable hardware revenue pools while expanding software and platform service monetization opportunities.
GDPR's data minimization principles shape cloud deployment architectures for transaction storage and analytics processing. Luxembourg's CNPD enforces cross-border data flow restrictions that compel payment service providers to localize server infrastructure within EU jurisdictions. Terminal manufacturers respond by embedding edge-computing capabilities that reduce centralized data transmission volumes.
Merchant procurement patterns favor hardware-as-a-service subscription models over capital purchase arrangements. Luxembourg's smaller hospitality operators and independent retailers lease terminals with bundled software updates and compliance management. The shift transfers obsolescence risk from merchant to provider while locking in recurring revenue relationships across the Grand Duchy's fragmented retail base.
Luxembourg POS Terminals Market Segmentation
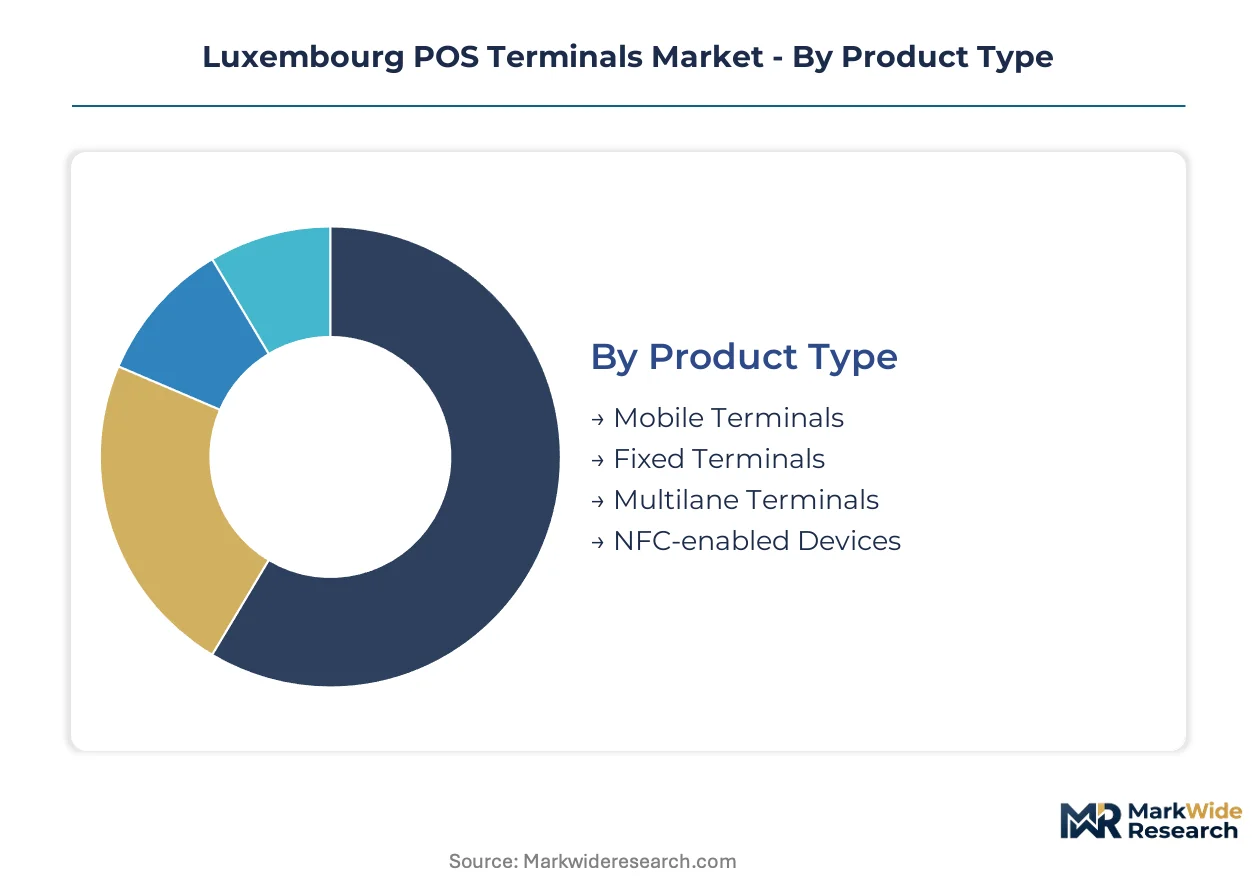
Luxembourg's concentrated financial district and cross-border commerce corridors create distinct demand profiles across terminal configurations. Merchants prioritize authentication capabilities and mobility features that align with PSD2 mandates and seasonal hospitality patterns.
Product Type:
Cost tier differentiation separates premium biometric-ready hardware from entry-level configurations serving Luxembourg's fragmented merchant base.
- Mobile Terminals:Battery-powered devices with cellular connectivity and integrated receipt printers serve Luxembourg's pop-up retail vendors and food-truck operators. Demand concentrates in seasonal hospitality clusters along Grund and Clausen districts where merchant mobility is essential.
- NFC-enabled Devices:These terminals embed 13.56 MHz antennas and EMV contactless kernels to process tap-to-pay transactions. Luxembourg City's financial district and retail corridors drive procurement as contactless transaction volumes justify premium hardware pricing against legacy configurations.
- Fixed Terminals:Countertop units with ethernet connectivity and high-speed thermal printers anchor permanent retail installations.
- Multilane Terminals:High-throughput devices with integrated barcode scanners and customer-facing displays serve supermarket checkout environments.
Fixed terminals command the established base. The steepest expansion runs through mobile terminals.
End User:
Application-specific requirements shape authentication protocols and integration complexity across Luxembourg's concentrated commercial zones.
- Restaurants:Tableside payment devices with tip-adjustment workflows and split-bill functionality dominate procurement. Luxembourg's dense hospitality clusters in Kirchberg and Hollerich prioritize handheld units that streamline service velocity during peak dining periods.
- Retail Stores:These merchants demand inventory synchronization and customer relationship management integration alongside core payment acceptance. Luxembourg City's pedestrian retail corridors concentrate deployment as merchants seek unified commerce platforms over isolated terminals.
- Hospitality:Hotels and accommodation providers require property management system connectivity and multi-currency settlement capabilities.
- Transportation:Transit operators need ruggedized outdoor units with rapid transaction processing for high-volume boarding scenarios.
Retail stores command the established base. The steepest expansion runs through restaurants.
Technology:
Volume trajectories diverge sharply between legacy magnetic infrastructure and contactless adoption curves across Luxembourg's merchant upgrade cycles.
- Contactless Payment:NFC transaction protocols operating at 13.56 MHz enable tap-to-pay authentication without physical card insertion. Luxembourg's hospitality and transit sectors drive adoption rates above European averages as consumers prioritize transaction speed.
- Chip & PIN:EMV chip-card authentication with cryptographic verification remains mandatory for high-value transactions. Luxembourg's banking sector sustains demand as PSD2 technical standards mandate dynamic cryptogram generation capabilities.
- Magnetic Stripe:Legacy card-reading technology persists in peripheral retail zones with delayed infrastructure refresh cycles.
- QR Code:Alternative payment rails using scanned matrix barcodes gain traction among micro-merchants seeking zero-hardware acceptance solutions.
Chip & PIN commands the established base. Contactless payment is climbing the fastest.
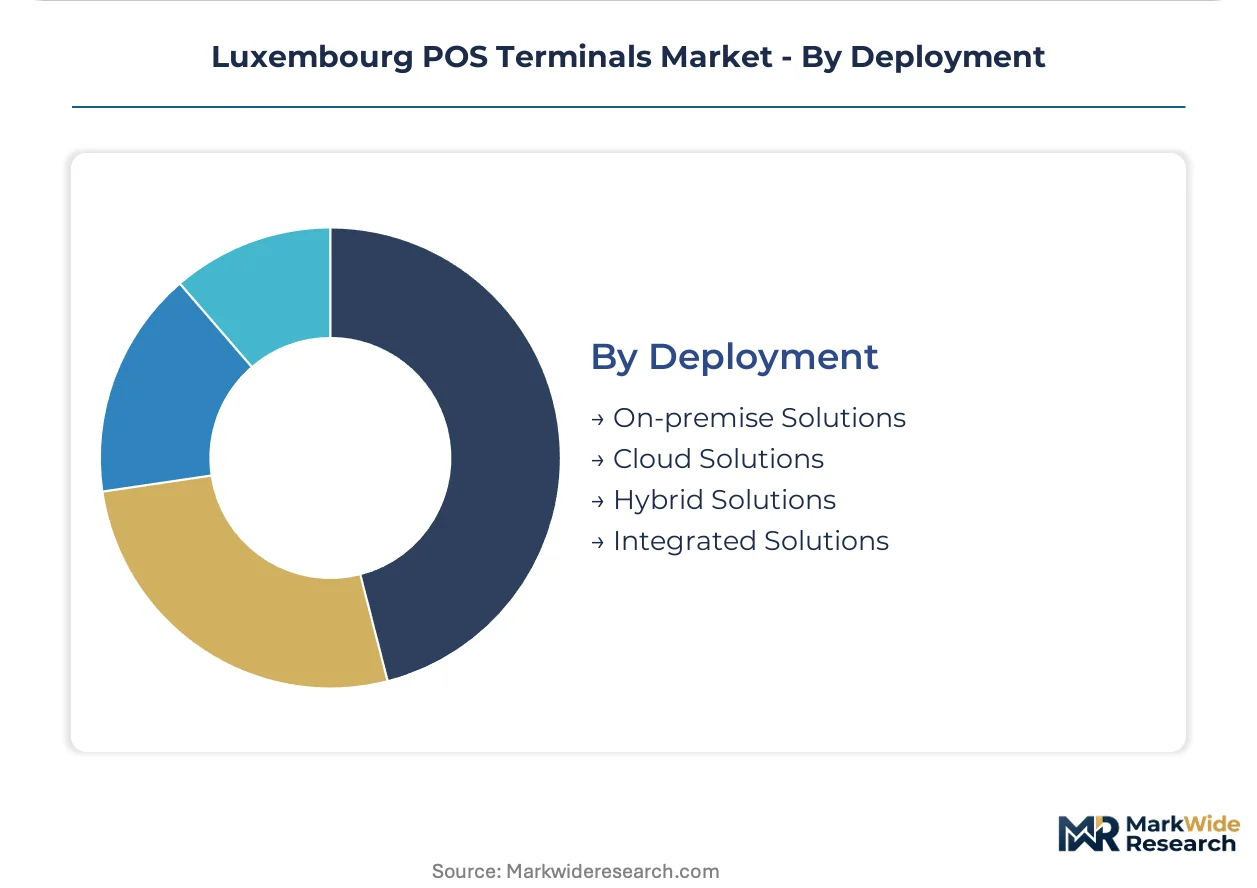
Deployment:
Customer type stratification separates enterprise merchants with dedicated IT infrastructure from smaller operators prioritizing operational simplicity.
- Cloud Solutions:Centralized transaction processing with remote software management and real-time analytics dashboards eliminates on-premise server maintenance. Luxembourg City's dense merchant clusters favor this architecture as GDPR compliance costs elevate data residency requirements.
- Integrated Solutions:These deployments bundle payment acceptance with enterprise resource planning, inventory management, and customer relationship management platforms. Luxembourg's larger retail chains and hospitality groups prioritize unified commerce architectures that consolidate vendor relationships.
- On-premise Solutions:Local server installations with dedicated network infrastructure serve merchants with strict data sovereignty requirements.
- Hybrid Solutions:Mixed architectures combine edge transaction processing with cloud-based reporting and backup functionality.
On-premise solutions command the established base. Cloud solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions and hospitality operators concentrate terminal procurement in Luxembourg's commercial corridors, with cross-border commerce patterns extending demand into adjacent Benelux and Rhine economies. Buyer archetypes span multinational banks, independent restaurateurs, and mobile micro-merchants with diverging authentication and mobility requirements.
Belgium
Brussels' dense financial services sector and Antwerp's port-commerce logistics drive contactless terminal deployment among institutional payment processors. The country's national banking regulator enforces PSD2 technical standards that accelerate hardware refresh cycles. Terminal procurement concentrates in Brussels-Capital's EU district and Antwerp's diamond-trading corridors where multi-currency settlement capabilities command premium positioning.
France
Parisian retail banking networks and Strasbourg's cross-border commerce with Germany sustain demand for NFC-enabled devices with biometric authentication. The French Prudential Supervision and Resolution Authority implements strong customer authentication mandates under EU Payment Services Directive 2. Deployment clusters in Paris' La Défense financial district and Strasbourg's European quarter where Luxembourg-originated transaction volumes require seamless interoperability.
Germany
Frankfurt's concentrated banking infrastructure and Trier's proximity to Luxembourg generate hardware demand for high-throughput multilane terminals. The Federal Financial Supervisory Authority enforces PSD2 compliance timelines that compress merchant upgrade cycles. Procurement concentrates in Frankfurt's Mainhattan financial district and Trier's retail zones serving cross-border Luxembourg commuters.
Netherlands
Amsterdam's fintech ecosystem and Maastricht's Limburg commerce corridor drive mobile terminal adoption among hospitality and pop-up retail operators. The Dutch Central Bank supervises payment institution licensing that shapes cloud deployment architectures for transaction data residency. Terminal demand clusters in Amsterdam's Zuidas business district and Maastricht's historic center where Belgian-German-Luxembourg transient commerce volumes justify multi-currency hardware specifications.
Luxembourg POS Terminals Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Luxembourg's concentrated merchant base, producing a tiered structure where scale-driven processors anchor relationships with financial institutions while agile entrants capture fragmented hospitality micro-merchants. European payment infrastructure operators and Asian hardware manufacturers constitute the dominant strategic archetypes, with software-platform specialists emerging as a third vector. Competitive dynamics center on merchant-acquiring network expansion and cloud-platform integration capabilities rather than hardware differentiation alone.
Among European payment processors, Worldline and Adyen exemplify the channel-control archetype through acquiring infrastructure that sustains cross-border merchant relationships, while Ingenico Group occupies a position bridging hardware fabrication and payment software integration. These entities represent how concentrated financial-sector demand in Luxembourg's Grand Duchy favors players with pre-established European regulatory compliance and multi-currency settlement architectures.
| Leading Market Players |
|---|
| Worldline |
| SumUp Inc |
| myPOS World Ltd |
| Payconiq International |
| VeriFone Inc |
| SIX Payment Services |
| Adyen |
| Ingenico Group |
| PAX Global Technology |
| Others |
Supply & Pricing Matrix
Single-source dependency on Taiwanese secure microprocessor foundries compresses both hardware procurement timelines and tiered pricing spreads across Luxembourg's terminal deployers. This concentration forces premium biometric-ready units toward cost-plus contracting indexed to semiconductor spot markets, while entry-level configurations face margin erosion from residual magnetic stripe inventory liquidation.
Pricing Analysis
Cost-plus contracts with Taiwanese foundry indexation dominate procurement for NFC-enabled and biometric-ready terminals serving Luxembourg's financial district. Three-tier pricing structure across premium authentication hardware, standard contactless units, and economy magnetic stripe configurations separates merchants by PSD2 compliance urgency and transaction volume scale. Price differentiation hinges on EMV certification tier and bundled cloud analytics subscriptions. Cost compression in entry-level hardware intensifies because SoftPOS SDK solutions displace dedicated terminal demand among micro-merchants. Independent food-truck operators and pop-up retail vendors exhibit highest price sensitivity; institutional banking clients demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
EU dual-use export controls on cryptographic processors constrain flows from Taiwan and South Korea into European terminal assembly facilities. Secure element manufacturing concentrates in Taiwan, South Korea, and mainland China, with firmware development anchored in Benelux engineering clusters. Raw material dependencies span silicon wafers, NFC antenna substrates, and PCI-DSS certified cryptographic modules. Single-source vulnerability in EMV kernel licensing from proprietary vendors threatens production continuity for non-integrated hardware manufacturers. Distribution runs through payment processor acquiring networks rather than direct merchant channels, with Worldline and Adyen controlling terminal provisioning relationships across Luxembourg's concentrated financial sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SoftPOS smartphone-based acceptance solutions threaten dedicated hardware incumbents with substitution-driven revenue compression. Terminal manufacturers must defend through embedded authentication moats and cloud-platform lock-in that SDK alternatives cannot replicate.
For Market Incumbents: Build switching-cost moats through deep ERP integration and property management system connectivity that SoftPOS solutions cannot easily replicate. Acquire firmware engineering talent pools across the Benelux region to address embedded systems scarcity. Prioritize biometric-ready interface R&D ahead of PSD3 regulatory anticipation. Channel control through acquiring network relationships remains the critical defensive lever against SumUp and myPOS aggregation plays. For New Entrants and Emerging Players: Pursue white-space capture in Luxembourg's seasonal hospitality clusters where battery-powered mobile terminals with cellular connectivity remain underserved. Target independent food-truck operators and Grund district pop-up vendors with hardware-as-a-service subscription models that eliminate upfront capital barriers. Leverage simplified onboarding workflows against incumbent procurement complexity. Geographic focus on Clausen and Hollerich seasonal corridors offers lowest competitive density. For Investors and Strategic Acquirers: DORA implementation reshapes the acquisition landscape by elevating incident reporting and stress-testing compliance costs for payment infrastructure targets. Frame long-term viability around cloud-platform revenue recurrence rather than hardware shipment volumes. Acquisition target archetype: software-platform specialists with embedded authentication IP and existing CNPD GDPR compliance infrastructure. Monitor EU Digital Operational Resilience Act enforcement timelines as inflection signal for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Interface Integration | PSD2 technical standards mandate fingerprint and facial recognition modules for high-value transaction corridors. |
| Cloud Platform Migration | Centralized analytics and remote software management reduce GDPR compliance costs for Luxembourg's dense merchant clusters. |
| Cross-Border Acquiring Expansion | Multi-currency settlement capabilities capture Belgian, French, and German transient commerce volumes. |
| SoftPOS SDK Development | Smartphone-based acceptance solutions address micro-merchant segments that dedicated hardware cannot serve profitably. |
| Hardware-as-a-Service Transition | Subscription models transfer obsolescence risk from merchant to provider while locking recurring revenue relationships. |
Research Methodology
Initial hypotheses were tested against primary input from payment processor executives, terminal manufacturer product managers, merchant acquiring relationship directors, and CNPD compliance officers, then refined through secondary validation. Primary fieldwork combined structured interviews with Luxembourg-based financial institutions and hospitality operators. Secondary sources encompassed ECB payment statistics, EBA PSD2 technical standard filings, CNPD GDPR enforcement decisions, and European Banking Authority regulatory guidance documents. Bottom-up terminal deployment estimates triangulated against top-down payment volume projections.
Demand-supply balance modeling anchored forecast construction across the projection horizon. Segmentation dimensions encompassed product type, end-user application, authentication technology, and deployment architecture. CAGRs derived from terminal refresh cycle compression rates and contactless transaction volume trajectories. Industry-specific inputs included PSD2 strong customer authentication compliance timelines and SoftPOS substitution elasticity estimates.
Sensitivities concentrate around semiconductor supply disruption, DORA implementation acceleration, and SoftPOS adoption curve steepness. Forecasts reflect documented assumptions regarding merchant upgrade cycle timing and regulatory enforcement intensity. Material shifts in EU export control regimes or cryptographic processor licensing structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Debit Market
Payments
United Kingdom Mobile Payments Market
Payments
Italy POS Terminals Market
Payments
Norway Mobile Payments Market
Payments
Europe Payments Market
Payments
France Virtual Cards Market
Payments
Argentina Mobile Wallet Market
Payments
Europe Accounts Payable Automation Market
Payments
P2P Payment Market
Payments
Greece POS Terminals Market
Payments
Digital Money Transfer Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Canada Real Time Payments Market
Payments
Europe Payment Gateways Market
Payments
Latin America Subscription and Billing Management Market
Payments
Europe Gift Card and Incentive Card Market